


Abstract
The aim of this paper is to show time-decay estimates of solutions to linearized two-phase Navier-Stokes equations with surface tension and gravity. The original two-phase Navier-Stokes equations describe the two-phase incompressible viscous flow with a sharp interface that is close to the hyperplane in the N-dimensional Euclidean space, . It is well-known that the Rayleigh–Taylor instability occurs when the upper fluid is heavier than the lower one, while this paper assumes that the lower fluid is heavier than the upper one and proves time-decay estimates of - type for the linearized equations. Our approach is based on solution formulas for a resolvent problem associated with the linearized equations.
Keywords:
two-phase flow; semigroup; Lp-Lq decay estimate; surface tension; gravity; resolvent problem MSC:
Primary 35Q30; Secondary 76D07
1. Introduction
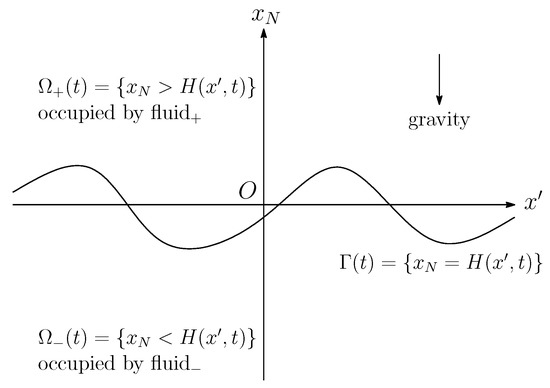
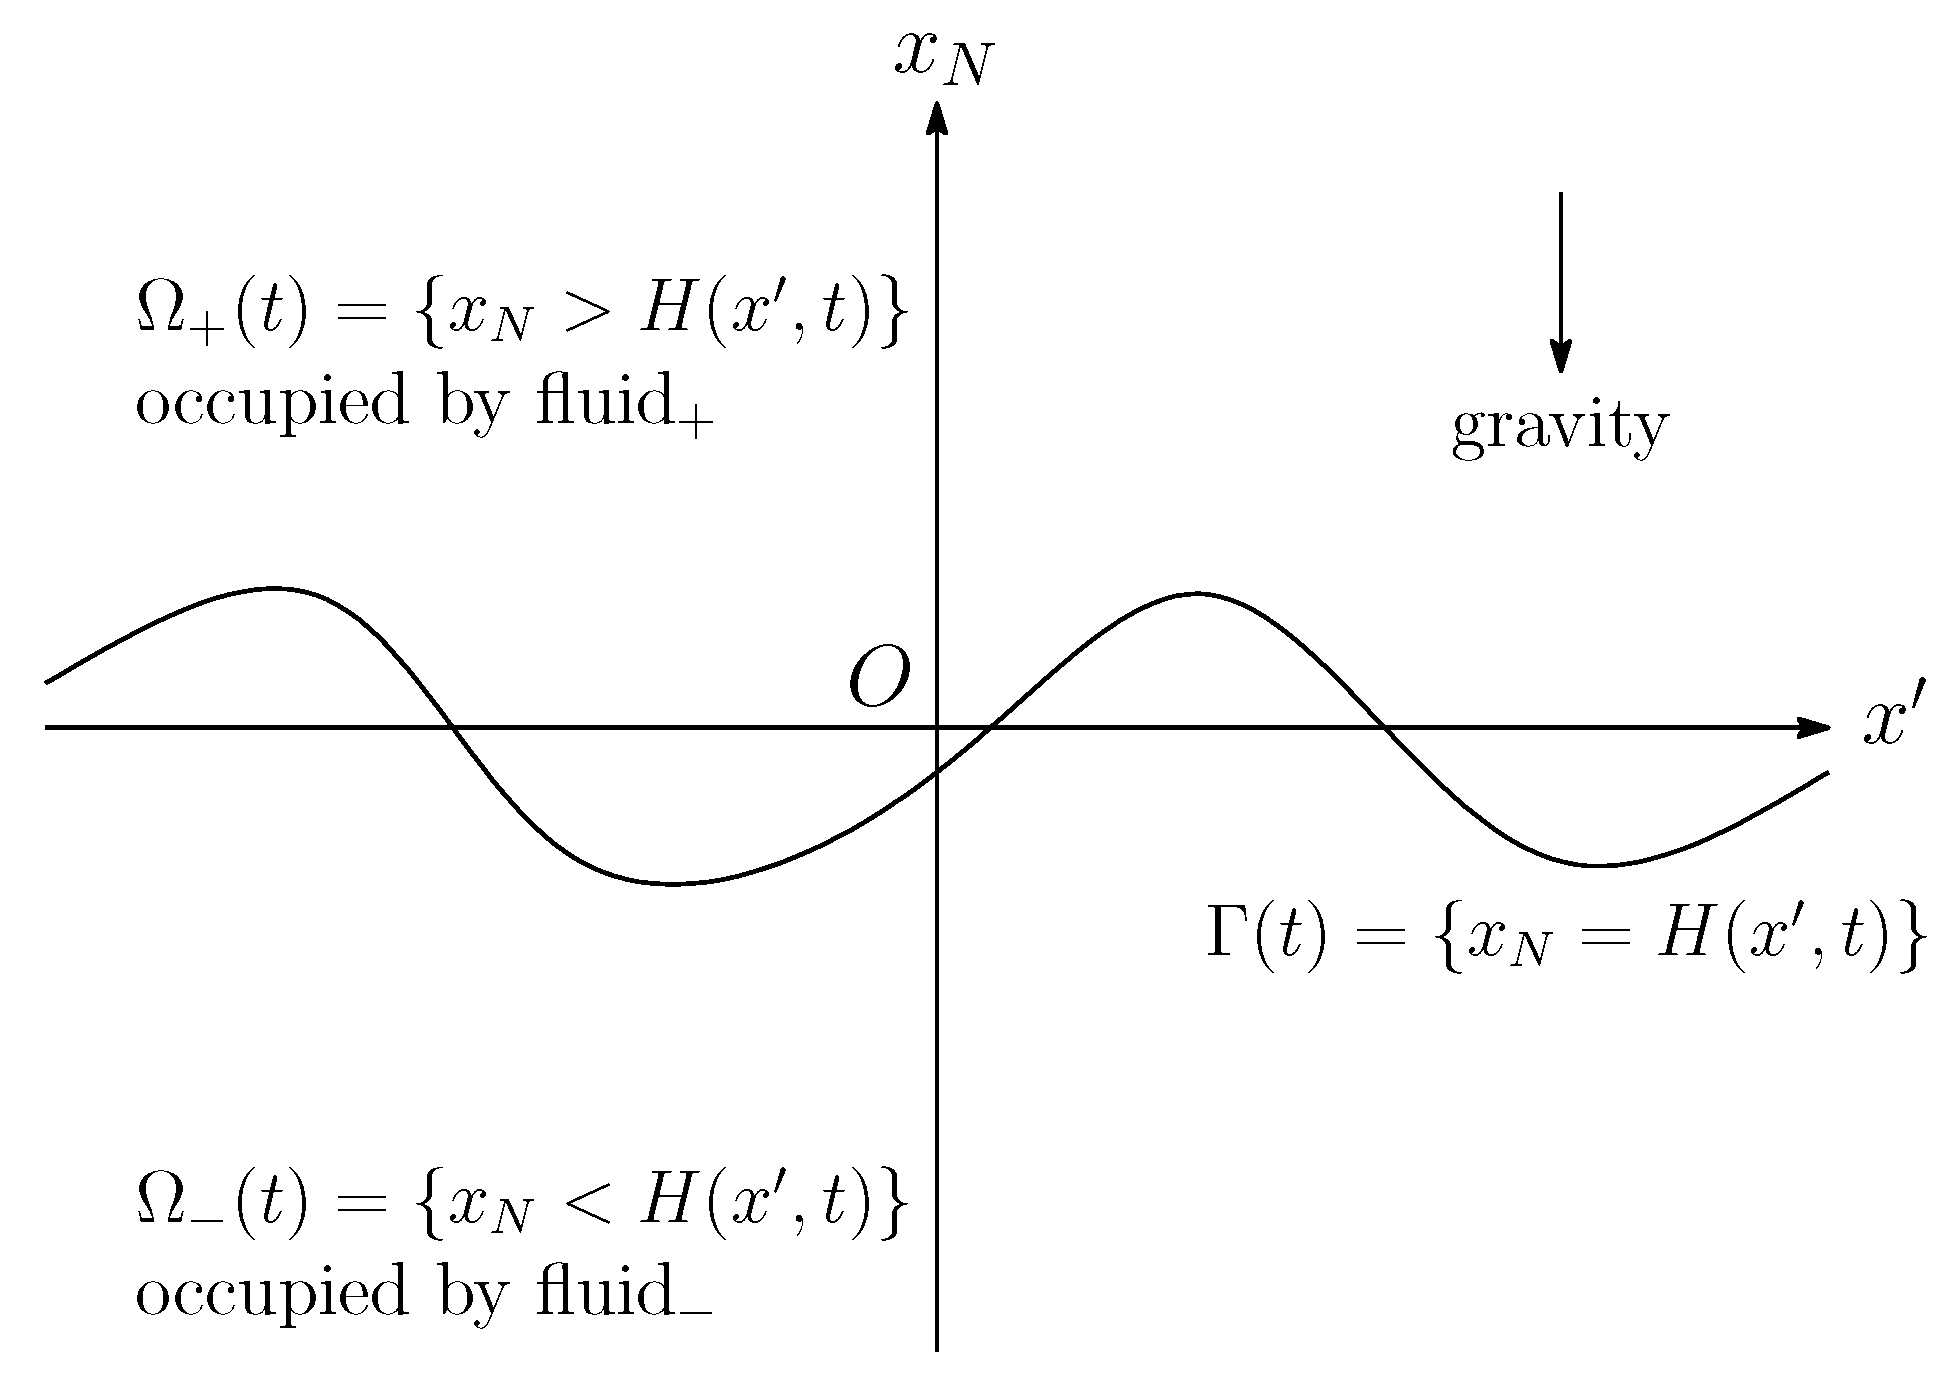
Let us consider the motion of two immiscible, viscous, incompressible capillary fluids, and , in the N-dimensional Euclidean space for . Here the and occupy and , respectively, given by
for time and the so-called height function . Here the height function is unknown and needs to be determined as part of the problem. The fluids are thus separated by the interface
see Figure 1 below. We denote the density of by , while the viscosity coefficient of by . Suppose that and are positive constants throughout this paper. The motion of two fluids is governed by the two-phase Navier-Stokes equations where surface tension is included on the interface. In addition, we allow for gravity to act on the fluids. The two-phase Navier-Stokes equations was studied by Prüss and Simonett [1], and they proved that the Rayleigh–Taylor instability occurs in an -setting when the upper fluid is heavier than the lower one, i.e., . In the present paper, we assume that the lower fluid is heavier than the upper one, i.e., , and show time-decay estimates of - type for some linearized system as the first step in proving global existence results for the two-phase Navier-Stokes equations when .
Figure 1.
The domains and the interface
Let us define for
This paper is concerned with the following linearized system of the two-phase Navier-Stokes equations:
where is a positive constant called the surface tension coefficient and one has set for the indicator function of
Here and respectively denote the velocity field of the fluid and the pressure field of the fluid at position and time , while and are given initial data. Here the superscript stands for the transposition. Note that and is the identity matrix. Let for . Then
while is an matrix whose element is given by . In addition, for matrix-valued functions ,
Let be a function defined on . Then denotes the jump of the quantity f across the interface , that is,
where . Note that on implies . For the acceleration of gravity , the constant is given by
which is positive when .
This paper shows that for some the -norm of satisfies
where (cf. Theorem 5 below for details). In [2], the authors considered linearized one-phase Navier-Stokes equations with surface tension and gravity, that is, they considered the case where there are no fluids in . In this case, the velocity satisfies
The above difference between the two-phase case and the one-phase case arises from asymptotic expansions of zeros of their boundary symbols, also called Lopatinskii determinant, which are functions of and the resolvent parameter . Here is the variables on the Fourier transform side. For the two-phase case, the zeros satisfy
where and are positive constants; for the one-phase case, the zeros satisfy
where are positive constants.
To see the relation between the time decay and the asymptotic expansions of , we consider the fractional power dissipative equation
where is a positive constant and is the fractional Laplacian defined by , , with
Applying the Laplace transform with respect to time t and the Fourier transform to (6) yields the equation
and thus the symbol of the operator has the zero . This zero gives the time decay of solutions to (6) as follows: the solution u of (6) is given by , and then Lemma 9 below yields
Thus the real term in (4), which is the case , yields
in (2); similarly, in (5), which is the case , yields
in (3). Note that in (2) and (3) we also have
which arise from the integration of with respect to , roughly speaking. For more details, see the following sections.
The boundary symbol for (1) can be obtained via solution formulas, which are introduced in Shibata and Shimizu [3] and given in Section 3 below. Then we analyze the asymptotic behavior of zeros of the boundary symbol as mentioned above and combine it with the solution formulas to obtain time-decay estimates of - type for solutions of (1) in the present paper. Thus the solution formulas play a crucial role in proving the result of this paper.
At this point, we introduce previous works for the two-phase flow.
Prüss and Simonett [4] considered the boundary symbol of linearized two-phase Navier-Stokes equations with surface tension, but gravity is not taken into account. In this case, they proved the zeros of the boundary symbol satisfy
where are positive constants.
The local well-posedness for the two-phase Navier-Stokes equations with as above was proved in Prüss and Simonett [5,6]. Note that the local well-posedness holds for any positive constants , that is, the condition is not required. Those results were extended to a class of non-Newtonian fluids in [7]. In addition, ref. [8] considered the two-phase inhomogeneous incompressible viscous flow without surface tension when gravity is not taken into account, and proved the local well-posedness in general domains including the above-mentioned . If are assumed to be layer-like domains, then it is known that the global well-posedness holds when . In fact, it was shown in [9] in a horizontally periodic setting, and also we refer to [10].
Let us recall Shibata and Shimizu [3]. They considered the following two resolvent problems:
and also
We define the sector
Let and . In [3], they obtained the following results: there exists a constant such that, for any with , (7) admits a unique solution , which satisfies
where
for any , (8) admits a unique solution , which satisfies
These results hold for any and play a key role in proving time-decay estimates of solutions for (1) in the present paper.
This paper is organized as follows. The next section introduces the notation used throughout this paper and states the main result of this paper, that is, time-decay estimates of solutions for (1). More precisely, the result is stated in Theorems 1–5. First, Theorem 1 introduces an evolution operator associated with (1), and Theorem 2 gives another evolution operator and its time-decay estimates. Next, we write and decompose , into several terms by using and cut-off functions on the Fourier transform side, see (21) below. Then Theorem 3 gives time-decay estimates for the low frequency part, while Theorem 4 gives time-decay estimates for the high frequency part. Finally, summing up Theorems 1–4, we have Theorem 5, which gives time-decay estimates of - type for the solution of (1). The proofs of Theorems 1, 2, and 5 are standard or elementary, so that they are omitted in the present paper. Section 3 shows the representation formulas of solutions for (1) by the partial Fourier transform with respect to and its inverse transform. Section 4 analyzes the boundary symbol appearing in the representation formulas given in Section 3. Section 5 proves Theorem 3 by using results obtained in Section 3 and Section 4. Section 6 proves Theorem 4 by using results obtained in Section 3 and Section 4.
2. Notation and Main Results
2.1. Notation
First, we introduce function spaces. Let X be a Banach space. Then , , stands for the m-product space of X, while the norm of is usually denoted by instead of for the sake of simplicity. For another Banach space Y, we set . Let be the set of all natural numbers and . Let or . For an open set , , the Lebesgue spaces on G are denoted by with norm , while the Sobolev spaces on G are denoted by , , with norm . Let . In addition, is the set of all functions in whose supports are compact and contained in G, and is the set of all functions on an interval with value X. For any multi-index ,
Let and . Let and be the largest integer less than s. The Sobolev–Slobodeckij spaces on are defined by
Let us define a solenoidal space by
where and
Furthermore, we set
and also .
Next, we define the partial Fourier transform with respect to by
where . Its inverse transform is also defined by
The integral path is defined by
2.2. Main Results
We first introduce the existence of solution operator for (1). This immediately follows from the resolvent estimate (9) and the standard theory of operator semigroups.
Theorem 1.
Let and be any positive constants. Let
with the solution to (7) for . Then the following assertions hold.
- (1)
- For any , .
- (2)
- is an analytic -semigroup on .
- (3)
- For any , is a unique solution to (1) with some pressure .
Let us define projections , by
We set for
One now decomposes the solution of (7) into a solution of parabolic system and a solution of hyperbolic-parabolic coupled system as follows:
It then holds that and . In addition, we set
which implies
For the parabolic part, we have the following theorem by the resolvent estimate (10) and the standard theory of operator semigroups.
Theorem 2.
Let and be any positive constants. Then the following assertions hold.
- (1)
- For any , .
- (2)
- is an analytic -semigroup on .
- (3)
- For any , is a unique solution towith some pressure .
- (4)
- Let and . For any and ,where when and when . Here C is a positive constant independent of t and .
To complete time-decay estimates for and , we further decompose satisfying () as follows: for and , let be the solution to
It then holds that , , and . Let be a function in and satisfy with
In addition, we set and for positive constants and . Let . Together with these cut-off functions, we define for and for an integral path
Furthermore, we set for and given by (13)
The following two theorems are of central importance in this paper. The first one is time-decay estimates for the low frequency part and proved in Section 5 below.
Theorem 3.
Let and suppose that . Then there exists a constant such that the following assertions hold.
- (1)
- For with , let with given in (12) and letIn addition, for and , setThen for anywith some positive constant C independent of t, d, and .
- (2)
- For and , setLet be a constant satisfyingThen for anywith some positive constant C independent of t, d, and .
The second one is time-decay estimates for the high frequency part and proved in Section 6 below.
Theorem 4.
Let and . Suppose that . Then there exist constants and such that for any and
where and C is a positive constant independent of t, d, and . Here is the positive constant given in Theorem 2.
Recalling (21), we have time-decay estimates of - type for the solution of (1) from Theorems 2–4 immediately.
Theorem 5.
Let and suppose that . Then for any and
with a positive constant C independent of t, d, and , where is the positive constant given in Theorem 3.
3. Representation Formulas for Solutions
This section introduces the representation formulas for solutions of (1). In this section, we assume that are any positive constants except for Lemma 3 (2) below. Here we collect several symbols appearing in the representation formulas. Let . For and , we set
where we have chosen a branch cut along the negative real axis and a branch of the square root so that for . In addition,
and also
Except for and E, the above symbols are introduced in (3.3), (3.8), and (3.15) of [3]. Furthermore, the following properties are proved in Lemmas 4.7 and 4.8 of [3].
Lemma 1.
Let and be any positive constants. Then the following assertions hold.
- (1)
- For any and ,with positive constants and depending on ε, but independent of and λ.
- (2)
- Let and . Then for any andwhere C is a positive constant depending on ε, s, and , but independent of and λ.
From Lemma 1 and the Bell formula of derivatives of composite functions, we have
Lemma 2.
Let and be any positive constants.
- (1)
- Let and . Then for any andwhere C is a positive constant depending on ε, s, and , but independent of and λ.
- (2)
- Let and . Then there exists a positive constant , independent of ν and τ, such that for any
3.1. A Representation Formula for the Parabolic Part
In this subsection, we introduce a representation formula for solutions of (15). Note that (15) admits a unique solution for and , and , as discussed in Section 1. Since is dense in for , it suffices to consider in what follows. Our aim is to prove
Proposition 1.
Let and be any positive constants. Suppose that is a solution to (15) for some and . Then there holds
Here stands for the partial Fourier transform of the Nth component of and
with constants and independent of and λ.
Proof.
Let and in this proof. Although we follow calculations in Section 3 of [3], we will achieve a set of equations simpler than (3.6) of [3] in what follows, see (45) below.
Step 1. We compute for the following resolvent problem:
where and are suitable functions on specified in Step 2 below. The restriction of and to are denoted by and , respectively. Let us write the Jth component of by and observe by in . Then (25) can be written as
Let and . Applying the partial Fourier transform to the last system yields
where and . Note that (26) and (27) are respectively equivalent to
From now on, we look for and of the forms: for ,
Multiplying (37) by and summing the resultant formulas yield
where . Combining this equation with the second one of (40) furnishes
We have thus achieved
where
Solving (45), we have
Since , there holds
Step 2. We compute the formula of . Let
be the solutions to the following whole space problems without interface:
where . Set and , and then satisfies
In addition, as discussed in the Appendix A below. Thus are given by and for the solution to
We now see that by (48) with and
Since by , there holds
Combing this property with the above formula of and (A1) in the Appendix A below yields the desired formula of . This completes the proof of Proposition 1. □
3.2. Solution Formulas for the Hyperbolic-Parabolic Part
In this subsection, we introduce solution formulas of , , for (18). System (18) can be written as
coupled with
In what follows, we apply the argumentation in Step 1 for the proof of Proposition 1 in the previous subsection. To this end, we set and in (25). Then and in (44) are given by
Since , we have by ()
Inserting this formula into (50) yields
Solving this equation, we obtain
where we have used with given in (23). At this point, we note the following lemma.
Lemma 3.
- (1)
- Let and be any positive constants. Then there exists a constant such that for any and withwhere and , are positive constants independent of and λ.
- (2)
- Suppose that . Let and with . Then .
Proof.
(1) See Lemma 6.1 of [3].
(2) The proof is similar to Lemma 3.2 of [2], so that the detailed proof may be omitted. □
We continue to calculate the solution formulas for (18). By (53) and (54)
while by (47), (51) and (52)
By the first Equation of (35) and the above formula of , we have
3.3. Representation Formulas for (1)
In this subsection, we give the representation formulas of solutions for (1). To this end, we first consider , , , and given in (20). Together with Proposition 1, inserting and of (54) into and in (19), respectively, yields
Let us define for and
Together with Proposition 1, inserting and of (61) into and , respectively, yields the following formulas: for and
and furthermore,
Summing up the above argumentation, we have obtained the representation formulas of , , , and given in (20) from the formulas of , , , and as above. Furthermore, those representation formulas of , , , and give the representation formulas of solutions for (1) by the relation (21).
Finally, we introduce another useful formula of .
Proof.
The desired relation follows from an elementary calculation, so that the detailed proof may be omitted. □
4. Analysis of Boundary Symbol
We assume throughout this section and analyze mainly the boundary symbol introduced in the last part of the previous section. Note that in (12) is positive by the assumption and that the symbols, defined in the previous section, such as
are used in this section.
4.1. Analysis of Low Frequency Part
In addition, we set
where and are given in Theorem 3 and Lemma 4, respectively. Then
for , given in (12), and the following lemma holds.
Lemma 5.
There exists a constant such that for and .
Proof. Case 1:
. Let . It is clear that
with a sufficiently small and a positive constant C independent of A and .
Next, we estimate from above. Since
there holds
One thus sees that
which implies for when is sufficiently small.
Case 2: . We consider only. Let . We write , that is,
We then observe that
From this, we immediately see that there exists a constant such that
Since , choosing furnishes
In addition,
which implies
In particular,
Next, we estimate from above. By Lemma 2 and (64), we have for
Since , one sees for that
and that . Combining these inequalities with (69) furnishes
which implies for when is sufficiently small.
Case 3: . Let . Then
with a sufficiently small and a positive constant C independent of A and . Since (69) is also valid for when , there holds
It therefore holds that for when is sufficiently small. This completes the proof of Lemma 5. □
By Lemma 5 and Rouché’s theorem, we immediately have
Proposition 2.
Let be the positive constant given in Lemma 5 and . Let K be the region enclosed by . Then has two zeros in K.
Recalling given in Theorem 3, we prove
Lemma 6.
There exists a constant such that for and .
Proof.
We consider only. Let . It is clear that
with a sufficiently small and a positive constant C independent of A and .
Next, we estimate from above. It holds that
which implies
Therefore,
From this, recalling the definition of given in (12), we have
In addition,
Combining these two formulas with (64) shows that
which implies for when is sufficiently small. This completes the proof of Lemma 6. □
We now obtain
Proposition 3.
Let and be the positive constants given in Lemmas 5 and 6, respectively. Then there exists a constant such that the following assertions hold.
- (1)
- Let and K be the region given in Proposition 2. Then
- (2)
- Let and be the regions enclosed by , respectively. Then has a simple zero denoted by in and another simple zero denoted by in .
- (3)
- Let be the derivative of with respect to λ. Then the inequalitieshold for and a positive constant C independent of A.
Remark 1.
The zeros of satisfy
When gravity is not taken into account, i.e., , the asymptotics of the zeros of are obtained in [4] as seen in Section 1.
Proof of Proposition 3.
(1) The desired properties can be proved by an elementary calculation, so that the detailed proof may be omitted.
(2) The result follows from Lemma 6 and Rouché’s theorem immediately.
(3) Since , one has the desired inequalities immediately by direct calculations together with (64). This completes the proof of Proposition 3. □
4.2. Analysis of High Frequency Part
Let us define
Then we have
Proposition 4.
Let . Then there exists a sufficiently large positive number such that the following assertions hold.
Proof.
(1) See Lemma 5.3 of [2].
(2) First, we estimate from below. Since
it holds that
This implies the desired inequality for .
Next, we estimate from below. Recall the formula of in Lemma 4. The asymptotics (71) gives
which implies
Thus, from the formula of in Lemma 4, we see that
This yields the desired inequality of immediately, which completes the proof of Proposition 4. □
Next, we consider for .
Proposition 5.
Let and . Then there exists a sufficiently small positive number such that the following assertions hold.
Proof.
(1) The desired inequalities can be proved by an elementary calculation, so that the detailed proof may be omitted.
(2) By Lemma 1, we see that for and . Then the continuity of and the compactness of implies there exists an . Choosing a sufficiently small , we see that is uniformly continuous on . Thus there exists an such that
which implies the desired inequality of holds. Analogously, the inequality for follows from Lemma 3 (2). This completes the proof of Proposition 5. □
5. Time-Decay Estimates for Low Frequency Part
This section proves Theorem 3. Suppose throughout this section.
Let us denote the points of intersection between and given in (13) by . Then we define
where are given in (62). Let be the positive constant given in Proposition 3 and let . Recalling (20) and the representation formulas in Section 3.3, we have, by Cauchy’s integral theorem and Propositions 2 and 3,
where . Here we have used and given in Theorem 3 and (63), respectively, and the symbols and introduced in Section 3.3. Throughout this section, we use symbols, given in Section 3, such as (22)–(24), (54), (60), in Lemma 4, and , in Proposition 1.
At this point, we introduce several lemmas used in the following argumentation. From Lemmas 4.3 and 4.4 of [2], we have the following two lemmas.
Lemma 7.
Let and . Then there exists a positive constant C such that for any , , and
Lemma 8.
Let and r be the dual exponent of p. Suppose that , , and .
- (1)
- For , , and , setThen there exists a positive constant C, independent of f, such that for anyprovided that and .
- (2)
- For and , setThen there exists a positive constant C, independent of f, such that for anyprovided that .
Next, we introduce time-decay estimates arising in the study of an evolution equation with the fractional Laplacian.
Lemma 9.
Let and . Then the following assertions hold.
- (1)
- Let . Then for any andwith a positive constant C independent of τ and φ.
- (2)
- Let . Then for any andwith a positive constant C independent of τ and φ.
Proof.
(1) See e.g., Lemma 3.1 of [11], Lemma 2.5 of [12].
(2) The desired estimate follows from (1) and Parseval’s identity immediately. This completes the proof of Lemma 9. □
Let be the X-valued Lebesgue spaces on , , for . The following lemma is proved in Theorem 2.3 of [13].
Lemma 10.
Let X be a Banach space and its norm. Suppose that L and n be a non-negative integer and positive integer, respectively. Let and . Let be a -function on with value X and satisfy the following two conditions:
- (1)
- for any multi-index with .
- (2)
- For any multi-index , there exists a positive constant such that
Then there exists a positive constant such that
where .
5.1. Analysis for .
In this subsection, we prove
Theorem 6.
Let and . Then there exists a constant such that for any and
where C is a positive constant independent of t, d, and .
Recalling and given in Proposition 3, we define
Then we immediately obtain.
Lemma 11.
There exists a constant such that for any
with positive constants and independent of , and also
with a positive constant C independent of , where and .
Let . Then, by Lemma 11, we have the following estimates for the symbols of the representation formulas given in Section 3.3: for the height function,
for the fluid velocity,
To prove Theorem 6, we introduce some technical lemma. Let us define the following operators:
and also for
Here it is assumed that the symbols
are infinitely many times differentiable with respect to and holomorphic with respect to for . Then we have
Lemma 12.
Let , , and . Suppose that
and that there exists a constant such that for any
with some positive constant C independent of . Then there exists a constant such that the following assertions hold.
- (1)
- For any andwith some positive constant C independent of t, d, and .
- (2)
- Let or . Then for any andwith some positive constant C independent of t, d, and .
Proof.
Case 1: . By the residue theorem, we have
Recalling , we write this formula as
Combining this formula with Lemma 9 yields
We choose a sufficiently small so that
and thus we have by Parseval’s identity, Proposition 3, and the assumption for
Since , this implies
Applying Lemma 9 to the right-hand side of the last inequality furnishes the desired estimate for . This completes the proof of Case 1.
Case 2: . In the same way as we have obtained (77), we obtain
We choose a sufficiently small so that
for positive constant C and c. Then
which, combined with Lemmas 7 and 9, implies
Since , applying Lemma 8 to the right-hand side of the last inequality shows that the desired estimate for holds. This completes the proof of Case 2.
Case 3: . In the same way as we have obtained (77), we obtain
By (78), we see that
When , it follows from (79) that
Combining this with Lemma 9 yields the desired estimate of for . When , it follows from (79) and Lemmas 7 and 9 that
In this inequality, taking -norm of both sides with respect to furnishes the desired estimate of for . This completes the proof of Case 3.
Case 4: . In the same way as we have obtained (77), we obtain
Combining this with (78) and Lemmas 7 and 9 yields
Lemma 8 thus yields the desired estimate for . This completes the proof of Lemma 12. □
5.2. Analysis for .
In this subsection, we prove
Theorem 7.
Let and . Then there exists a constant such that for any and
where C is a positive constant independent of t, d, and .
To prove Theorem 7, we start with the following lemma.
Lemma 13.
There exists a constant such that for any and
with positive constants and independent of and λ, and also
with a positive constant C independent of and λ, where and .
Proof.
See Lemma 4.9 of [2] for . Then the desired estimates for , , , and follow from the estimates of immediately.
We now estimate . Let . It is clear that by . In what follows, we prove from below. Since for , there holds
It suffices to show that
Let . Then for some . Therefore , since for some positive constant by Lemma 1.
Next, we consider . In this case, and set . Then
and can be written as
Note that for when A is small enough as seen in Case 1 of the proof of Lemma 5, and thus it follows from Lemma 13 that . By this inequality and Lemma 13, we have the following estimates for the symbols of the representation formulas given in Section 3.3: for the height function,
for the fluid velocity
Now, recalling the operators difined in (75) and (76), we introduce the following lemma (cf. [2] (Lemma 4.10) for details).
Lemma 14.
Let , , and . Suppose that there exists a constant such that for any and
with some positive constant C independent of and λ. Then there exists a constant such that the following assertions hold.
- (1)
- For any andwith some positive constant C independent of t, d, and .
- (2)
- Let or . Then for any andwith some positive constant C independent of t, d, and .
5.3. Analysis for .
In this subsection, we prove
Theorem 8.
Let and Then there exists a constant such that for any and
where C is a positive constant independent of t, d, and . Here
Note that for given in (11). By Lemma 1, we have for any and
where and . In addition, similarly to (67), there holds
for a sufficiently small A and , which, combined with and Lemmas 2 and 4, furnishes
By this inequality together with (85) and Lemma 1, we have the following estimates for the symbols of the representation formulas given in Section 3.3: for the height function
for the fluid velocity
and also
We now prove
Lemma 15.
Let , , and . Suppose that there exists a constant such that for any and
with some positive constant of and λ. Then there exists a constant such that the following assertions hold.
- (1)
- For any andwith some positive constant C independent of t, d, and .
- (2)
- Let or . Then for any andwith some positive constant C independent of t, d, and .
Proof.
We here consider , , and only. The desired estimates for
are proved in Lemma 4.13 of [2], and can be proved similarly to the case of .
Case 1: . Since for , there holds
It thus holds that by Lemma 9, Parseval’s identity, and the assumption for
We choose a sufficiently small so that
for positive constants C and c. Then
Let . Since
we see that
Combining this inequality with (89) furnishes
which, combined with Parseval’s identity and Young’s inequality, yields
where .
From now on, we estimate by Lemma 10. By the Leibniz rule and Lemmas 1 and 2, we have for any multi-index and
where is a positive constant independent of and t. Lemma 10 with , , and then furnishes
By direct calculations, we also have
and thus we obtain from these two inequalities
Let us choose the above so that
Then we have
Hence
which implies the desired estimate for holds.
Case 2: . In the same way as we have obtained (89), we obtain
Since it holds by Lemma 1 that for and , we see that
Therefore for and
with positive constants C and c, which, combined with the assumption for and (90), furnishes
One now sees that
and thus for
where for
By the Leibniz rule and Lemmas 1 and 2, we have for any multi-index and
where is a positive constant independent of and t. Lemma 10 with , , and then furnishes
By direct calculations, we also have
Combining these three inequalities yields
which implies for any
Let us choose the above so that
Then we have
Hence
which implies the desired estimate for holds.
Case 3: . In the same way as we have obtained (91), we obtain for
By Parseval’s identity and Young’s inequality,
where . Similarly to in Case 2, we observe for any that
Thus, by choosing
we have
This inequality furnishes the desired estimate for , which completes the proof of Lemma 15. □
5.4. Analysis for .
Similarly to Subsection 4.4 of [2], we can prove by Lemmas 1 and 3 the following theorem.
Theorem 9.
Let . Then there exist constants and such that for any and
where C is a positive constant independent of t, d, and .
5.5. Proof of Theorem 3.
Recalling (72), we observe for that the operators in Theorem 3 are given by
Theorems 6–9 then yields Theorem 3 immediately. This completes the proof of Theorem 3.
6. Time-Decay Estimates for High Frequency Part
This section proves Theorem 4. Suppose throughout this section.
Let us denote the points of intersection between and given in (13) by , and let be the positive constant given in Theorem 3. We define for the positive constant given in Proposition 4. In addition, we set and in Proposition 5. Then we have from Proposition 5 and denote the points of intersection between and by . Note that .
Now we define integral paths and as follows:
where is given in (11). Recalling the symbols (22)–(24) and (54), we have from Propositions 4 and 5 the following lemma.
Lemma 16.
- (1)
- , , and for and , where is defined by (70) with and .
- (2)
- Let and . Then for any it holds that on
Let and . Recalling (20) and the representation formulas in Section 3.3, we have, by Cauchy’s integral theorem and Lemma 16 (1)
Similarly to Section 5 of [2], we can prove the following theorem from Lemmas 1, 3, and 16 by choosing larger if necessary.
Theorem 10.
Let and . Let and . Then for any and
where C and c are positive constants independent of t, d, and .
Theorem 10 with (92) yields Theorem 4 immediately. This completes the proof of Theorem 4.
Funding
This research was funded by JSPS KAKENHI Grant Number JP17K14224.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
Not applicable.
Acknowledgments
The author would like to express his gratitude to Professor Ryo Takada for helpful comments concerning the fractional power dissipative equations and informing him of [11]. He is also indebted to the referees for their valuable comments.
Conflicts of Interest
The authors declare no conflict of interest.
Appendix A
We consider the whole space problems in (49) and compute the representation formulas of and . We define the Fourier transform of and the inverse Fourier transform of by
Let us denote the jth component of by . In Section 2 of [3], we have
The formulas of imply . For , can be written as
and also
where A is given in (22). It holds for that
which, inserted into the above formulas of and , furnishes
Applying to these formulas yields
Let be the sign function, that is,
Then we have
Lemma A1.
Proof.
The first and third formulas follow from the residue theorem. Differentiating the first formula with respect to a, we have the second formula. Analogously the fourth and fifth formulas follow from the third formula. This completes the proof of Lemma A1. □
Recall given in (23), and then
By this relation and Lemma A1, we have
Lemma A2.
Let and . Let be any positive constants. Then for any with
Together with the above formulas of , , , and , we obtain by Lemmas A1 and A2
This completes the proof of the appendix.
References
- Prüss, J.; Simonett, G. On the Rayleigh-Taylor instability for the two-phase Navier-Stokes equations. Indiana Univ. Math. J. 2010, 59, 1853–1871. [Google Scholar] [CrossRef] [Scilit]
- Saito, H.; Shibata, Y. On decay properties of solutions to the Stokes equations with surface tension and gravity in the half space. J. Math. Soc. Jpn. 2016, 68, 1559–1614. [Google Scholar] [CrossRef] [Scilit]
- Shibata, Y.; Shimizu, S. Maximal Lp-Lq regularity for the two-phase Stokes equations; model problems. J. Differ. Eq. 2011, 251, 373–419. [Google Scholar] [CrossRef] [Scilit]
- Prüss, J.; Simonett, G. Analysis of the boundary symbol for the two-phase Navier-Stokes equations with surface tension. Banach Center Publications 2009, 86, 265–285. [Google Scholar]
- Prüss, J.; Simonett, G. On the two-phase Navier-Stokes equations with surface tension. Interfaces Free Bound. 2010, 12, 311–345. [Google Scholar] [CrossRef] [Scilit]
- Prüss, J.; Simonett, G. Analytic solutions for the two-phase Navier-Stokes equations with surface tension and gravity. In Parabolic Problems; Progress in Nonlinear Differential Equations and Their Applications; Springer: Basel, Switzerland, 2011; Volume 80, pp. 507–540. [Google Scholar]
- Hieber, M.; Saito, H. Strong solutions for two-phase free boundary problems for a class of non-Newtonian fluids. J. Evol. Eq. 2017, 17, 335–358. [Google Scholar] [CrossRef] [Scilit]
- Saito, H.; Shibata, Y.; Zhang, X. Some free boundary problem for two-phase inhomogeneous incompressible flows. SIAM J. Math. Anal. 2020, 52, 3397–3443. [Google Scholar] [CrossRef] [Scilit]
- Wang, Y.; Tice, I.; Kim, C. The viscous surface-internal wave problem: Global well-posedness and decay. Arch. Ration. Mech. Anal. 2014, 212, 1–92. [Google Scholar] [CrossRef] [Scilit]
- Xu, L.; Zhang, Z. On the free boundary problem to the two viscous immiscible fluids. J. Differ. Eq. 2010, 248, 1044–1111. [Google Scholar] [CrossRef] [Scilit]
- Miao, C.; Yuan, B.; Zhang, B. Well-posedness of the Cauchy problem for the fractional power dissipative equations. Nonlinear Anal. 2008, 68, 461–484. [Google Scholar] [CrossRef] [Scilit]
- Yamamoto, M.; Sugiyama, Y. Asymptotic expansion of solutions to the drift-diffusion equation with fractional dissipation. Nonlinear Anal. 2016, 141, 57–87. [Google Scholar] [CrossRef] [Scilit]
- Shibata, Y.; Shimizu, S. A decay property of the Fourier transform and its application to the Stokes problem. J. Math. Fluid Mech. 2001, 3, 213–230. [Google Scholar] [CrossRef] [Scilit]
Publisher’s Note: MDPI stays neutral with regard to jurisdictional claims in published maps and institutional affiliations. |
© 2021 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).