Article

Optimal Control of an Eco-Epidemiological Reaction-Diffusion Model

1
School of Mathematics and Statistics, Changchun University of Technology, Changchun 130012, China
2
Department of Mathematics, Dalian Minzu University, Dalian 116600, China
*
Author to whom correspondence should be addressed.
Mathematics 2025, 13(13), 2069; https://doi.org/10.3390/math13132069
Submission received: 29 May 2025 / Revised: 18 June 2025 / Accepted: 20 June 2025 / Published: 22 June 2025

Abstract

In this paper, a prey–predator diffusion model with isolation and drug treatment control measures for prey infection is studied. The main objective is to find an optimal control that minimizes the population density of infected prey and the costs of isolation and drug treatment for infected prey. Through analysis, the existence and uniqueness of weak solution, as well as the existence and local uniqueness of optimal controls are proven. The first-order necessary condition is derived, and the feasibility of the theoretical proof is verified through numerical simulations.

1. Introduction

In recent years, remarkable progress has been made in interdisciplinary research between ecology and mathematics. Through the construction of differential equation systems, researchers have conducted in-depth investigations into complex behaviors such as species interactions, disease transmission, and resource competition. With the increasingly widespread application of optimal control theory in biomathematics, scholars have gradually focused on how to design optimal strategies within the framework of mathematical models to achieve the collaborative optimization of ecological balance and resource utilization. Against this research background, the close interaction between prey and predator has become a core research issue.
In natural ecosystems, the interactions between prey and predator are often influenced by diseases, especially since the population dynamics of a prey population after infection may differ significantly from those in a healthy state. Therefore, considering the factor of disease infection in prey populations can significantly increase the complexity of prey–predator model and make the research more realistic. In recent years, the application of epidemiology in population biology has received extensive attention and made important progress.
In the study of the dynamic behavior of prey–predator ordinary differential equation model with infected prey, the main focus is on the equilibrium points of the model, their stability, and the system’s response to external disturbances. By analyzing the equilibrium points (such as steady states) and their stability (such as local or global stability), the long-term behavioral patterns of prey–predator models with infected prey are revealed. For example, in 1999, Chattopadhyay, Joydev, and Ovide Arino [1] assumed that the disease only spreads within the prey population, is non-hereditary, and infected prey cannot recover or develop immunity, and the predator population primarily preys on infected prey. They mainly investigated theoretical issues such as the existence and boundedness of solutions, as well as the stability of equilibrium points. Additionally, they simplified the three-dimensional system to a two-dimensional system for analysis and generalized the results back to the original system. In 2001, Xiao, Y. and Chen, L [2] studied a class of prey–predator model where prey is infected and predators prey on infected prey, introducing time-delay factors, particularly the gestational delay of predator. Using delay differential equations, they analyzed non-negativity, the global stability of solutions, permanence, and the impact of time delays on system stability. Notably, they also explored Hopf bifurcation phenomena caused by time delays and demonstrated the dual role of time delays in system stability (both destabilizing and stabilizing effects). In 2011, Niu X, Zhang T, Teng Z [3] investigated a non-autonomous eco-epidemiological model involving infected prey, where the parameters of the ecosystem change over time. The research focused on the asymptotic behavior of the system, especially the stability and periodicity of long-term behavior, and explored the long-term dynamic effects of disease transmission on prey and predator populations.
However, ordinary differential equation (ODE) models overlook the impact of spatial heterogeneity on research, which has motivated researchers to introduce spatial distribution into models and construct more complex partial differential equation (PDE) models. For example, in 2010, Li, Jianjun, and Wenjie Gao [4] studied a class of prey–predator reaction-diffusion model with infected prey. In 2018, Pan M, Yang J, Lin Z [5] analyzed a non-autonomous eco-epidemiological diffusion model involving infected prey, and the model is shown as follows:
S t d I S = Λ ( t ) β ( t ) S I d ( t ) S , x Ω , t > 0 , I t d I I = β ( t ) S I c ( t ) I α ( t ) P I , x Ω , t > 0 , P t d P P = P ( r ( t ) b ( t ) P ) + k ( t ) α ( t ) P I , x Ω , t > 0 , η S = η I = η P = 0 , x Ω , t > 0 , S ( x , 0 ) = S 0 ( x ) 0 , I ( x , 0 ) = I 0 ( x ) 0 , P ( x , 0 ) = P 0 ( x ) 0 , x Ω ¯ .
Here, S is the population density of susceptible prey, I is the population density of infected prey, P is the population density of predator, d I are the diffusion coefficients of susceptible prey and infected prey populations, respectively, d P is the diffusion coefficient of predator population, Λ ( t ) is the recruitment rate of the prey population at time t (including birth rate and migration rate), β ( t ) is the conversion rate of susceptible prey to infected prey at time t, d ( t ) is the mortality rate of susceptible prey at time t, c ( t ) is the mortality rate of infected prey at time t, α ( t ) is the predation rate of predator preying on infected prey at time t, r ( t ) is the intrinsic growth rate of the predator population at time t, 1 b ( t ) is the environmental maximum carrying capacity of the predator population at time t, k ( t ) is the conversion rate of predator preying on infected prey into predators at time t, x is the spatial location, Ω is a fixed and bounded domain in R N with smooth boundary Ω , and S 0 ( x ) , I 0 ( x ) , P 0 ( x ) are the initial values of the population densities of susceptible prey, infected prey, and predator, respectively. This study mainly analyzes the impact of disease transmission in the prey population on the long-term dynamic behavior of the system. The results show that disease transmission is dominated by β ( t ) when the conversion rate β ( t ) is large enough, and the disease spreads; conversely, it dies out.
With the deepening understanding of disease transmission mechanisms in ecosystems, control measures such as isolation and treatment have increasingly attracted the attention of scholars as prevention and control measures. These control strategies can not only reduce the spread rate of diseases in prey populations but also indirectly influence the dynamic changes of predator populations by optimizing the health status of prey. Therefore, how to design and optimize these control strategies through optimal control methods has become an important topic in current interdisciplinary research between ecology and mathematics. For example, in 2018, RUD Amalia and DK Arif [6] proposed a prey–predator mathematical model with infection and harvesting, where infection and harvesting only occur in the prey population, assuming that prey infections do not spread to predator. Using Pontryagin’s maximum principle, they explored the optimal control problem aimed at maximizing the density of susceptible prey populations while minimizing control costs. In the same year, JSH Simon and JFT Rabago [7] studied the optimal control problem of a prey-predator model with infected prey. Considering disease transmission in the prey population, they investigated the optimal control problem targeting the minimization of both the density of infected prey and control costs, and conducted numerical simulations using numerical methods. In 2019, A Hugo and E Simanjilo [8] studied an eco-epidemiological model with isolation control strategies, as shown in the following model:
S t = r S ( 1 S + I k ) ( 1 u 1 ) β S I p 1 S Y m + S , I t = ( 1 u 1 ) β S I ( 1 u 2 ) p 2 I Y m + I ( a + e 1 ) I , Y t = q p 1 S Y m + S + ( 1 u 2 ) p 2 I Y m + I ( a + e 1 ) I e 2 Y .
Among them, S is the population density of susceptible prey, I is the population density of infected prey, and Y is the population density of the predator, respectively. r is the intrinsic growth rate, k is the environmental carrying capacity, β is the rate of transmission, m is half-saturation constant, and p 1 , p 2 are the predation coefficients with susceptible prey and infected prey, respectively. a is the death rate caused by disease or by predation, e 1 , e 2 are the natural death rate and the predator’s death rate, respectively. q is the efficiency with which prey is converted into predator. u 1 ( x , t ) is the isolation control rate for susceptible prey and infected prey, and u 2 ( x , t ) is the isolation control rate for infected prey and predator, respectively. t represents time and x represents the spatial location. The main research objective is to find the control functions u 1 ( x , t ) and u 2 ( x , t ) that minimize both the density of the infected prey population and the control costs. The objective functional is defined in the following form:
J = 0 t f ( B I + 1 2 A 1 u 1 2 + 1 2 A 2 u 2 2 ) d t .
Among them, t f is the final time. B is the cost required for infected prey, and A 1 , A 2 are the relative cost weights corresponding to the two control functions, respectively. The study results indicate that the isolation of infected individuals plays a crucial role in disease elimination. In 2024, Mekonen Kassahun Getnet and Abayneh Fentie Bezabih [9] studied a scenario where both prey and predator populations are infected, with the specific model described as follows:
s t = r s ( 1 s + I k ) ( 1 u 1 ) β s I p 1 s y + u 2 I , I t = ( 1 u 1 ) β s I p 2 I y ( u 2 + δ 1 ) I , y t = q p 1 S Y + q p 2 I y ( 1 u 1 ) α y z μ y + u 2 z , z t = ( 1 u 1 ) α y z ( u 2 + δ 2 ) z .
Among them, s is the population density of susceptible prey, I is the population density of infected prey, y is the population density of susceptible predator, and z is the population density of infected predator, respectively. r is the intrinsic growth rate, k is the environmental carrying capacity, β is the rate of transmission, p 1 , p 2 are the predation coefficients with susceptible prey and infected prey, respectively. δ 1 , δ 2 are the fatality rates of infected prey and infected predator, respectively. q is the transformation of eaten prey to predation, α is the convolution rate, and μ is the natural death rate of the susceptible predator, respectively. u 1 ( x , t ) represents preventive measures such as isolation, patient tracking, and reducing interaction rates with infected individuals, u 2 ( x , t ) denotes providing medical care for all infected cases, respectively. t represents time, x represents the spatial location. The main research objective is to find the control functions u 1 ( x , t ) and u 2 ( x , t ) that minimize the population densities of infected prey and predator, as well as the control costs. The objective functional is defined in the following form:
J ( u 1 , u 2 ) = 0 t f ( c 1 I ( t ) + c 2 z ( t ) + 1 2 i = 1 2 b i u i 2 ) d t .
Among them, t f is the final time. c 1 , c 2 correspond to the weights of infected prey and infected predator, respectively, b 1 , b 2 correspond to the relative costs necessary for control, respectively. Numerical simulations using numerical methods shown that the control effect of u 1 is superior to that of u 2 .
Considering the impact of spatial heterogeneity on the research, we introduce spatial distribution into the model and construct a more complex partial differential model. In 2019, TY Miyaoka, S Lenhart, and JFCA Meyer [10] investigated the optimization of vaccination strategies in a vector-borne reaction-diffusion model to address Zika virus transmission. In 2020, F Dai and B Liu [11] studied the optimal control problem in a general reaction-diffusion eco-epidemiological model where prey may be infected. By integrating prey-predator dynamics with disease transmission in prey, reaction-diffusion equations were used to describe the spatial and temporal evolution of populations and diseases. Through optimal control theory, the results shown that adopting optimal control strategies can effectively reduce disease transmission in prey populations and improve the overall stability of the prey–predator system. In 2020, PT Sowndarrajan, N Nyamoradi, and L Shangerganesh [12] conducted a mathematical analysis of optimal control problems in a prey–predator model with infected prey, considering disease transmission in prey populations and examining how different optimal control strategies affect the dynamics of predator and prey populations. In 2024, ES Baranovskii, RV Brizitskii, and ZY Saritskaia [13] studied the optimal control problem for a more general reaction-diffusion model. However, their paper focused on a single time-independent equation, while this paper investigates a class of coupled systems comprising three time-dependent convection-diffusion equations.
In this paper, we study the optimal control problem of a class of prey–predator dispersal model with isolation and treatment of predator infection, and the problem equation is as follows:
S t d S S = A S ( 1 u 1 ) β S I d S η 1 S Y + u 2 I , ( x , t ) Q T ,
I t d I I = ( 1 u 1 ) β S I c I η 2 I Y u 2 I , ( x , t ) Q T ,
Y t d Y Y = r Y ( 1 Y k ) + p 1 η 1 S Y + p 2 η 2 I Y , ( x , t ) Q T ,
S n = I n = Y n = 0 , ( x , t ) Γ ,
S ( x , 0 ) = S 0 ( x ) , I ( x , 0 ) = I 0 ( x ) , Y ( x , 0 ) = Y 0 ( x ) , x Ω ,
where Ω is a bounded smooth domain of R N , Q T = Ω × ( 0 , T ) , Γ = Ω × ( 0 , T ) . Furthermore, d S , d I , d Y , A , β , d , η 1 , c , η 2 , r , p 1 , p 2 , u 1 , u 2 L ( Q T ) , S 0 ( x ) , I 0 ( x ) , Y 0 ( x ) L ( Ω ) , d S , d I , d Y , A   β , d , η 1 , c , η 2 , r , k , p 1 , p 2 , S 0 ( x ) , I 0 ( x ) , Y 0 ( x ) are all nonnegative functions and k is a function which is greater than zero.
The variable t represents time, x represents the spatial location. The functions S, I, and Y represent the densities of the susceptible prey, the infected prey, and the predator, respectively. The functions d S , d I , and d Y represent the diffusion coefficient of susceptible prey, the infected prey, and the predator, respectively. The function A represents the birth rate of susceptible prey. The function β represents the infection rate of susceptible prey. The function d represents the death rate for susceptible prey. The function η 1 , η 2 represent the prey rate of susceptible prey and infected prey, respectively. The function c represents the natural and disease-induced death rate for infected prey. The function r represents the growth rate of the predator. The function k represents the carrying capacity for the predator. The functions p 1 , p 2 represent the conversion rate of a predator which is susceptible prey to another predator and infected prey to predator, respectively. The function S 0 ( x ) , I 0 ( x ) , Y 0 ( x ) represent the initial value of the population density of susceptible prey, infected prey, and predator, respectively.
The function u 1 ( x , t ) represents the isolation rate of infected prey, and the function u 2 ( x , t ) represents the cure rate of drug treatment for infected prey, respectively.
Suppose u = ( u 1 , u 2 ) is the control, and the admissible control set U a d is defined by
U a d = { u = ( u 1 , u 2 ) L 2 ( Q T ) , 0 u i M i , i = 1 , 2 } .
where M i represents the upper bound of control u i , i = 1 , 2 .
The objective functional is defined by
J ( u 1 , u 2 ) = 0 T Ω w I ( x , t ) + 1 2 a 1 u 1 2 ( x , t ) + 1 2 a 2 u 2 2 ( x , t ) d x d t ,
where u U a d , w , a 1 , a 2 R + , w represents the weight factor, a 1 is the price for isolating infected prey, and a 2 is the price for drug treatment for susceptible and infected prey, respectively. The functional J represents the population density and isolation of infected forage populations, as well as the cost of treatment. Our goal is to seek u = ( u 1 , u 2 ) such that the objective function J reaches its minimum.
To simplify the following proof process, the system (1)–(5) is denoted in the following form:
z 1 t d 1 z 1 = b 1 z 1 ( 1 u 1 ) b 2 z 1 z 2 b 3 z 1 z 3 + u 2 z 2 , ( x , t ) Q T ,
z 2 t d 2 z 2 = c 1 z 2 + ( 1 u 1 ) b 2 z 1 z 2 c 2 z 2 z 3 u 2 z 2 , ( x , t ) Q T ,
z 3 t d 3 z 3 = e 1 z 3 e 2 z 3 2 + e 3 z 1 z 3 + e 4 z 2 z 3 , ( x , t ) Q T ,
z 1 n = z 2 n = z 3 n = 0 , ( x , t ) Γ ,
z 1 ( x , 0 ) = z 1 , 0 ( x ) , z 2 ( x , 0 ) = z 2 , 0 ( x ) , z 3 ( x , 0 ) = z 3 , 0 ( x ) , x Ω ,
J ( u 1 , u 2 ) = 0 T Ω w z 2 ( x , t ) + 1 2 a 1 u 1 2 ( x , t ) + 1 2 a 2 u 2 2 ( x , t ) d x d t ,
Among them, the function z i , i = 1 , 2 , 3 represents the functions S , I , and Y, respectively. The function d i , i = 1 , 2 , 3 represents the function d S , d I , and d Y , respectively. The function b i , i = 1 , 2 , 3 represents the functions A d , β , and η 1 , respectively. The function c i , i = 1 , 2 represents the functions c and η 2 , respectively. The function e i , i = 1 , 2 , 3 , 4 represents the functions r , r k , p 1 η 1 , and p 2 η 2 , respectively. Due to the strong coupling nature of the system of equations, studying the well-posedness, optimal control problems, and numerical calculations of this system presents certain difficulties and complexities.
The paper is organized as follows. In Section 2, we establish the well-posedness of the system (8)–(12). In Section 3, we prove the existence of the optimal controls, derive the first order necessary condition and obtain the formula of the optimal control by optimality system. In Section 4, we prove the local uniqueness of the optimal control. In Section 5, we present numerical experiments for Neumann boundary condition. In Section 6, we provide a summary of the key findings from this study and outline potential directions for future research.

2. The Well-Posedness of the System

In this section, we give the definition of weak solutions of the system (8)–(12).
Definition 1.
We call z = ( z 1 , z 2 , z 3 ) ( C ( [ 0 , T ] ; L 2 ( Ω ) ) L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) ) 3 a weak solution of the problem (8)–(12), if for any ϕ = ( ϕ 1 , ϕ 2 , ϕ 3 ) ( L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) ) 3 with ϕ i t L 2 ( Q T ) , ϕ i n = 0 and ϕ i ( x , T ) = 0 , i = 1 , 2 , 3 , the following equalities hold
Q T z 1 ϕ 1 t d x d t Ω z 1 , 0 ( x ) ϕ 1 ( x , 0 ) d x + d 1 Q T z 1 · ϕ 1 d x d t = Q T b 1 z 1 ( 1 u 1 ) b 2 z 1 z 2 b 3 z 1 z 3 + u 2 z 2 ϕ 1 d x d t , Q T z 2 ϕ 2 t d x d t Ω z 2 , 0 ( x ) ϕ 2 ( x , 0 ) d x + d 2 Q T z 2 · ϕ 2 d x d t = Q T c 1 z 2 + ( 1 u 1 ) b 2 z 1 z 2 c 2 z 2 z 3 u 2 z 2 ϕ 2 d x d t , Q T z 3 ϕ 3 t d x d t Ω z 3 , 0 ( x ) ϕ 3 ( x , 0 ) d x + d 3 Q T z 3 · ϕ 3 d x d t = Q T ( e 1 z 3 e 2 z 3 2 + e 3 z 1 z 3 + e 4 z 2 z 3 ) ϕ 3 d x d t .
Lemma 1
([14]). Let B 1 B 2 B 3 be three Banach spaces. Assume that B 1 B 2 B 3 . Then,
{ u L p ( 0 , T ; B 1 ) : u t L q ( 0 , T ; B 3 ) } L p ( 0 , T ; B 2 ) , 1 < p , q < .
Lemma 2.
For u L ( Ω ) , there exists a sequence { u n } n = 1 C 0 ( Ω ) , such that
u n L ( Ω ) u L ( Ω ) ,
and
u n u , i n L ( Ω ) .
Proof. 
For ϵ > 0 , let J ϵ ( x ) be a mollifier such that
J ϵ ( x ) = 0 , | x | ϵ , and R n J ϵ ( x ) d x = 1 .
Take δ > 0 such that
Ω δ : = { x Ω ; dist ( x , Ω ) < δ } ϕ .
Define
u δ ( x ) = u ( x ) , x Ω δ , 0 , x R n Ω δ .
For 0 < ϵ < δ , define
u ϵ δ ( x ) = R n J ϵ ( x y ) u δ ( y ) d y = R n J ϵ ( y ) u δ ( x y ) d y , x R n .
From (14)–(16), we have
u ϵ δ L ( R n )     u δ L ( R n )     u L ( Ω ) .
By Theorem 2.29 in [15], we have
u ϵ δ ( x ) C 0 ( Ω ) and lim ϵ 0 + u ϵ δ u δ L 2 ( Ω ) = 0 .
For any φ L 1 ( Ω ) , there exists a sequence φ k C 0 ( Ω ) , such that
lim k φ k φ L 1 ( Ω ) = 0 .
From (15), (17), and (18), we have
lim ¯ δ 0 + lim ¯ ϵ 0 + Ω ( u ϵ δ u ) φ d x lim ¯ δ 0 + lim ¯ ϵ 0 + Ω ( u ϵ δ u δ ) φ k d x + Ω ( u ϵ δ u ) ( φ φ k ) d x + Ω ( u δ u ) φ d x 2 u L ( Ω ) Ω φ φ k d x .
It follows from (19) and (20) that
lim δ 0 + lim ϵ 0 + Ω ( u ϵ δ u ) φ d x = 0 .
For i , j = 1 , 2 , , take δ i = δ i , ϵ j i = δ i j + 1 . Then,
lim i lim j Ω ( u ϵ j i δ i u ) φ d x = 0 .
By using a diagonal selection, we have
lim n Ω ( u n u ) φ d x = 0 .
where u n = u ϵ n n δ n , n = 1 , 2 , . The proof is completed from (17), (18), and (21).  □
Next, we give the well-posedness of the problem (8)–(12).
Theorem 1.
For small enough T > 0 , there exists a uniquely weak positive solution z to the problem (8)–(12), such that for i = 1 , 2 , 3 , z i t L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) and
z i L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) + z i t L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) C ,
where C is depending on T, z i , 0 ( x ) L ( Ω ) , b 2 L ( Q T ) , e 1 L ( Q T ) , e 3 L ( Q T ) , e 4 L ( Q T ) with i = 1 , 2 , 3 . Moreover, it still holds that
0 z i H i e τ i T , i = 1 , 2 , 3 ,
where
H 1 = z 1 , 0 ( x ) L ( Ω ) , H 2 = z 2 , 0 ( x ) L ( Ω ) , H 3 = z 3 , 0 ( x ) L ( Ω ) ,
τ 1 = e b 2 H 1 L ( Q T ) , τ 2 = e b 2 H 1 L ( Q T ) , τ 3 = e 1 + e 3 H 1 e + e 4 H 2 e L ( Q T ) .
Proof. 
For i = 1 , 2 , 3 , α = 1 , 2 , k = 1 , 2 , 3 , 4 , and any ( x , t ) Q T , it follows from Lemma 2 that there exist nonnegative sequences { d i ( n ) } n = 1 , { b i ( n ) } n = 1 , { c α ( n ) } n = 1 , { e k ( n ) } n = 1 C 0 ( Q T ) , { z i , 0 ( n ) } n = 1 C 0 ( Ω ) , such that
d i ( n ) L ( Q T ) d i L ( Q T ) , b i ( n ) L ( Q T ) b i L ( Q T ) , c α ( n ) L ( Q T ) c α L ( Q T ) ,
e k ( n ) L ( Q T ) e k L ( Q T ) , z i , 0 ( n ) ( x ) L ( Ω ) z i , 0 ( x ) L ( Ω )
and
d i ( n ) d i , b i ( n ) b i , c α ( n ) c α , e k ( n ) e k , in L ( Q T ) , as n ,
z i , 0 ( n ) ( x ) z i , 0 ( x ) , in L 2 ( Ω ) , as n .
For i = 1 , 2 , 3 , consider the following system
z i ( n ) t d i ( n ) z i ( n ) = g i ( x , t , z ( n ) ) , ( x , t ) Q T ,
z i ( n ) n = 0 , ( x , t ) Γ ,
z i ( n ) ( x , 0 ) = z i , 0 ( n ) ( x ) , x Ω ,
where
g 1 ( x , t , γ ) = b 1 ( n ) γ 1 ( 1 u 1 ( n ) ) b 2 ( n ) γ 1 γ 2 b 3 ( n ) γ 1 γ 3 + u 2 ( n ) γ 2 , g 2 ( x , t , γ ) = c 1 ( n ) γ 2 + ( 1 u 1 ( n ) ) b 2 ( n ) γ 1 γ 2 c 2 ( n ) γ 2 γ 3 u 2 ( n ) γ 2 , g 3 ( x , t , γ ) = e 1 ( n ) γ 3 e 2 ( n ) γ 3 2 + e 3 ( n ) γ 1 γ 3 + e 4 ( n ) γ 2 γ 3 .
Define
z ¯ = ( H 1 e τ 1 t , H 2 e τ 2 t , H 3 e τ 3 t ) , z ̲ = ( 0 , 0 , 0 ) .
where H 1 , H 2 , H 3 , τ 1 , τ 2 , τ 3 are defined as (24) and (25).
Take T 1 e b 2 H 1 . By computation, one can see that for any γ with z ̲ i γ i z ¯ i and (33), we have
z ¯ i t d i ( n ) z ¯ i g i ( t , x , γ ) , z ̲ i t d i ( n ) z ̲ i g i ( t , x , γ ) , ( x , t ) Q T , z ¯ i n 0 , z ̲ i n 0 , ( x , t ) Γ , z ¯ i , 0 ( x ) = H i z i , 0 ( n ) ( x ) , z ̲ i , 0 ( x ) z i , 0 ( n ) ( x ) , x Ω .
Hence, z ¯ and z ̲ are the upper solution and the lower solution of the system (30)–(32), respectively. Hence, it follows from [16] that there exists a unique solution z ( n ) = ( z 1 ( n ) , z 2 ( n ) , z 3 ( n ) ) ( C ( Q ¯ T ) C 2 ( Q T ) ) 3 such that
z i ̲ z i ( n ) z i ¯ , i = 1 , 2 , 3 .
That is to say,
0 z i ( n ) H i e τ i T , i = 1 , 2 , 3 .
Multiplying the Equation (30) by z 1 ( n ) and integrating by parts over Ω × ( 0 , t ) with 0 < t < T , we get
1 2 Ω z 1 ( n ) ( x , t ) 2 d x + d 1 0 T Ω | z 1 ( n ) ( x , t ) | 2 d x d t 1 2 Ω ( z 1 , 0 ( n ) ( x ) ) 2 d x + 0 T Ω b 1 ( n ) z 1 ( n ) ( 1 u 1 ( n ) ) b 2 ( n ) z 1 ( n ) z 2 ( n ) b 3 ( n ) z 1 ( n ) z 3 ( n ) + u 2 ( n ) z 2 ( n ) z 1 ( n ) d x d t .
It follows from (26)–(27) and (34) that
sup 0 t T Ω z 1 ( n ) ( x , t ) 2 d x + d 1 0 T Ω | z 1 ( n ) ( x , t ) | 2 d x d t C .
For any φ L 2 ( ( 0 , T ) ; H 0 1 ( Ω ) ) , we have
0 T Ω z 1 ( n ) t φ d x d t = d 1 0 T Ω z 1 ( n ) φ d x d t + 0 T Ω b 1 ( n ) z 1 ( n ) ( 1 u 1 ( n ) ) b 2 ( n ) z 1 ( n ) z 2 ( n ) b 3 ( n ) z 1 ( n ) z 3 ( n ) + u 2 ( n ) z 2 ( n ) φ d x d t d 1 0 T Ω z 1 ( n ) · φ d x d t + C φ L 2 ( Q T ) C ( φ L 2 ( Q T ) + φ L 2 ( Q T ) ) C ( φ L 2 ( ( 0 , T ) ; H 0 1 ( Ω ) ) )
due to (26)–(27), (34), and (35). Hence, we have
z 1 ( n ) t L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) C .
Similarly, one can get
sup 0 t T Ω z 2 ( n ) ( x , t ) 2 d x + d 2 0 T Ω | z 2 ( n ) ( x , t ) | 2 d x d t + z 2 ( n ) t L 2 ( ( 0 , t ) ; H 1 ( Ω ) ) C ,
and
sup 0 t T Ω z 3 ( n ) ( x , t ) 2 d x + d 3 0 T Ω | z 3 ( n ) ( x , t ) | 2 d x d t + z 3 ( n ) t L 2 ( ( 0 , t ) ; H 1 ( Ω ) ) C .
Hence, it follows from Lemma 1, Lemma C.1 in [17] and (34)–(38), that there exist subsequences of { n } n = 1 , denoted by { n j } j = 1 , and a function z = ( z 1 , z 2 , z 3 ) ( C ( [ 0 , T ] ; L 2 ( Ω ) ) L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) ) 3 with z ( L ( Q T ) ) 3 and z t ( L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) 3 , such that for i = 1 , 2 , 3 ,
z i ( n j ) z i in L 2 ( Q T ; R n ) , z i ( n j ) t z i t in L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) , a s j ,
z i ( n j ) z i in L 2 ( Q T ) , z i ( n j ) z i in L ( Q T ) , a s j .
Since z ( n j ) is the solution to the system (30)–(32), for any ϕ i C ( Q T ¯ ) with ϕ i n = 0 and ϕ i ( x , T ) = 0 ( i = 1 , 2 , 3 ) , we have the following equalities hold
Q T z 1 ( n j ) ϕ 1 t d x d t Ω z 1 , 0 ( n j ) ( x ) ϕ 1 ( x , 0 ) d x + d 1 Q T z 1 ( n j ) · ϕ 1 d x d t = Q T b 1 ( n j ) z 1 ( n j ) ( 1 u 1 ( n j ) ) b 2 ( n j ) z 1 ( n j ) z 2 ( n j ) b 3 ( n j ) z 1 ( n j ) z 3 ( n j ) + u 2 ( n j ) z 2 ( n j ) ϕ 1 d x d t .
Similarly, we have
Q T z 2 ( n j ) ϕ 2 t d x d t Ω z 2 , 0 ( n j ) ( x ) ϕ 2 ( x , 0 ) d x + d 2 Q T z 2 ( n j ) · ϕ 2 d x d t = Q T c 1 ( n j ) z 2 ( n j ) + ( 1 u 1 ( n j ) ) b 2 ( n j ) z 1 ( n j ) z 2 ( n j ) c 2 ( n j ) z 2 ( n j ) z 3 ( n j ) u 2 ( n j ) z 2 ( n j ) ϕ 2 d x d t
and
Q T z 3 ( n j ) ϕ 3 t d x d t Ω z 3 , 0 ( n j ) ( x ) ϕ 3 ( x , 0 ) d x + d 3 Q T z 3 ( n j ) · ϕ 3 d x d t = Q T e 1 ( n j ) z 3 ( n j ) e 2 ( n j ) ( z 3 ( n j ) ) 2 + e 3 ( n j ) z 1 ( n j ) z 3 ( n j ) + e 4 ( n j ) z 2 ( n j ) z 3 ( n j ) ϕ 3 d x d t .
Letting n in (41)–(43), we can get from (28)–(29), (39), and (40) that
Q T z 1 ϕ 1 t d x d t Ω z 1 , 0 ( x ) ϕ 1 ( x , 0 ) d x + d 1 Q T z 1 · ϕ 1 d x d t = Q T b 1 z 1 ( 1 u 1 ) b 2 z 1 z 2 b 3 z 1 z 3 + u 2 z 2 ϕ 1 d x d t ,
Q T z 2 ϕ 2 t d x d t Ω z 2 , 0 ( x ) ϕ 2 ( x , 0 ) d x + d 2 Q T z 2 · ϕ 2 d x d t = Q T c 1 z 2 + ( 1 u 1 ) b 2 z 1 z 2 c 2 z 2 z 3 u 2 z 2 ϕ 2 d x d t ,
and
Q T z 3 ϕ 3 t d x d t Ω z 3 , 0 ( x ) ϕ 3 ( x , 0 ) d x + d 3 Q T z 3 · ϕ 3 d x d t = Q T e 1 z 3 e 2 z 3 2 + e 3 z 1 z 3 + e 4 z 2 z 3 ϕ 3 d x d t .
Since z ( C ( [ 0 , T ] ; L 2 ( Ω ) ) L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) ) 3 , we can extend the space of the test function from ( C ( Q T ¯ ) ) 3 to ( L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) ) 3 with ϕ t ( L 2 ( Q T ) ) 3 .
Hence, z is the solution of the system (8)–(12). Furthermore, we can obtain the estimates (22) and (23) from (35)–(40).
Next, we prove the uniqueness.
Let z ˜ ( n ) = ( z ˜ 1 ( n ) , z ˜ 2 ( n ) , z ˜ 3 ( n ) ) and z ^ ( n ) = ( z ^ 1 ( n ) , z ^ 2 ( n ) , z ^ 3 ( n ) ) be two solutions of the system (30)–(32). Denote v = z ˜ ( n ) z ^ ( n ) . Then, v = ( v 1 , v 2 , v 3 ) satisfies the following system:
v 1 t d 1 ( n ) Δ v 1 = b 1 ( n ) v 1 ( 1 u 1 ( n ) ) b 2 ( n ) v 1 z ˜ 2 ( n ) ( 1 u 1 ( n ) ) b 2 ( n ) z 1 ^ ( n ) v 2 b 3 ( n ) v 1 z 3 ˜ ( n ) b 3 ( n ) z 1 ^ ( n ) v 3 + u 2 ( n ) v 2 , ( x , t ) Q T , v 2 t d 2 ( n ) Δ v 2 = c 1 ( n ) v 2 + ( 1 u 1 ( n ) ) b 2 ( n ) v 2 z 1 ˜ ( n ) ( 1 u 1 ( n ) ) b 2 ( n ) v 1 z 2 ^ ( n ) c 2 ( n ) v 2 z 3 ˜ ( n ) c 2 ( n ) z 2 ^ ( n ) v 3 u 2 ( n ) v 2 , ( x , t ) Q T , v 3 t d 3 ( n ) Δ v 3 = e 1 ( n ) v 3 e 2 ( n ) v 3 ( z 3 ˜ ( n ) + z 3 ^ ( n ) ) + e 3 ( n ) v 3 z 1 ˜ ( n ) + e 3 ( n ) v 1 z 3 ^ ( n ) + e 4 ( n ) v 3 z 2 ˜ ( n ) + e 4 ( n ) v 2 z 3 ^ ( n ) , ( x , t ) Q T , v 1 n = v 2 n = v 3 n = 0 , ( x , t ) Γ , v 1 ( x , 0 ) = v 2 ( x , 0 ) = v 3 ( x , 0 ) = 0 , x Ω .
Multiply (44) by v 1 to get
1 2 Ω v 1 2 ( x , t ) d x + d 1 0 T Ω v 1 2 d x d s C 0 T Ω v 1 2 + v 2 2 + v 3 2 d x d s
due to (23). Similarly, we have
1 2 Ω v 2 2 ( x , t ) d x + d 2 0 T Ω | v 2 | 2 d x d s C 0 T Ω ( v 1 2 + v 2 2 + v 3 2 ) d x d s ,
and
1 2 Ω v 3 2 ( x , t ) d x + d 3 0 T Ω | v 3 | 2 d x d s C 0 T Ω ( v 1 2 + v 2 2 + v 3 2 ) d x d s .
From (45)–(47), we can get
Ω ( v 1 2 + v 2 2 + v 3 2 ) ( x , t ) d x C 0 t Ω ( v 1 2 + v 2 2 + v 3 2 ) ( x , s ) d s .
By the Grownwall inequality, we have
Ω ( v 1 2 + v 2 2 + v 3 2 ) ( x , t ) d x 0 .
Hence, it can yield
v 1 = v 2 = v 3 = 0 .
The proof is completed. □

3. The Necessary Condition of the Optimal Control Problem

In this section, we study the optimal control problem of the system (8)–(12). Firstly, we prove the existence of the optimal control. Next, we derive the necessary condition of the optimal control problem and obtain the formula of the optimal control.

3.1. The Existence of the Optimal Control Problem

In this subsection, we prove the existence of the optimal control.
Theorem 2.
Suppose u = ( u 1 , u 2 ) , then there exists an optimal control u = ( u 1 , u 2 ) such that
J ( u ) = J ( u 1 , u 2 ) = inf ( u 1 , u 2 ) U a d J ( u 1 , u 2 ) ,
where U a d is defined as (6).
Proof. 
Since the control u 1 , u 2 and the state z 1 , z 2 , z 3 are uniformly bounded, there exists a sequence { ( u 1 ( n ) , u 2 ( n ) } n = 1 U a d such that
lim n J ( u 1 ( n ) , u 2 ( n ) ) = inf ( u 1 , u 2 ) U a d J ( u 1 , u 2 ) .
Denote by ( z 1 ( n ) , z 2 ( n ) , z 3 ( n ) ) the solution of the problem (8)–(12) with u 1 = u 1 ( n ) , u 2 = u 2 ( n ) .
By Theorem 1, we obtain
| | z i ( n ) | | L ( Q T ) + | | z i ( n ) | | L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) + z i ( n ) t L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) C , i = 1 , 2 , 3 ,
where C is a positive constant independent of n. Thus, there exists a subsequence of { n } n = 1 , denoted by { n i } i = 1 , and ( u 1 , u 2 ) U a d , ( z 1 , z 2 , z 3 ) L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) 3 with ( ( z 1 ) t , ( z 2 ) t , ( z 3 ) t ) L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) 3 , such that
( u 1 ( n i ) , u 2 ( n i ) ) ( u 1 , u 2 ) in ( L ( Q T ) ) 2 as i ,
( z 1 ( n i ) , z 2 ( n i ) , z 3 ( n i ) ) ( z 1 , z 2 , z 3 ) in L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) 3 as i ,
( ( z 1 ( n i ) ) t , ( z 2 ( n i ) ) t , ( z 3 ( n i ) ) t ) ( ( z 1 ) t , ( z 2 ) t , ( z 3 ) t ) in L 2 ( ( 0 , T ) ; H 1 ( Ω ) ) 3 as i .
From (51) and (52), we get
( z 1 ( n i ) , z 2 ( n i ) , z 3 ( n i ) ) ( z 1 , z 2 , z 3 ) in ( L 2 ( Q T ) ) 3 as i .
Since ( z 1 ( n i ) , z 2 ( n i ) , z 3 ( n i ) ) is the weak solution of the problem (8)–(12) with u 1 = u 1 ( n i ) , u 2 = u 2 ( n i ) ( i = 1 , 2 , 3 ) , for any ( ϕ 1 , ϕ 2 , ϕ 3 ) ( C ( Q T ¯ ) ) 3 with ϕ 1 n = ϕ 2 n = ϕ 3 n = 0 and ϕ 1 ( x , T ) = ϕ 2 ( x , T ) = ϕ 3 ( x , T ) = 0 , we have
Q T z 1 ( n i ) ϕ 1 t d x d t Ω z 1 , 0 ( x ) ϕ 1 ( x , 0 ) d x + d 1 Q T z 1 ( n i ) · ϕ 1 d x d t = Q T b 1 z 1 ( n i ) ( 1 u 1 ( n i ) ) b 2 z 1 ( n i ) z 2 ( n i ) b 3 z 1 ( n i ) z 3 ( n i ) + u 2 ( n i ) z 2 ( n i ) ϕ 1 d x d t .
Similarly, we have
Q T z 2 ( n i ) ϕ 2 t d x d t Ω z 2 , 0 ( x ) ϕ 2 ( x , 0 ) d x + d 2 Q T z 2 ( n i ) · ϕ 2 d x d t = Q T c 1 z 2 ( n i ) + ( 1 u 1 ( n i ) ) b 2 z 1 ( n i ) z 2 ( n i ) c 2 z 2 ( n i ) z 3 ( n i ) u 2 ( n i ) z 2 ( n i ) ϕ 2 d x d t ,
and
Q T z 3 ( n i ) ϕ 3 t d x d t Ω z 3 , 0 ( x ) ϕ 3 ( x , 0 ) d x + d 3 Q T z 3 ( n i ) · ϕ 3 d x d t = Q T e 1 z 3 ( n i ) e 2 ( z 3 ( n i ) ) 2 + e 3 z 1 ( n i ) z 3 ( n i ) + e 4 z 2 ( n i ) z 3 ( n i ) ϕ 3 d x d t .
Letting i , we get
Q T z 1 ϕ 1 t d x d t Ω z 1 , 0 ( x ) ϕ 1 ( x , 0 ) d x + d 1 Q T z 1 · ϕ 1 d x d t = Q T b 1 z 1 ( 1 u 1 ) b 2 z 1 z 2 b 3 z 1 z 3 + u 2 z 2 ϕ 1 d x d t ,
Q T z 2 ϕ 2 t d x d t Ω z 2 , 0 ( x ) ϕ 2 ( x , 0 ) d x + d 2 Q T z 2 · ϕ 2 d x d t = Q T c 1 z 2 + ( 1 u 1 ) b 2 z 1 z 2 c 2 z 2 z 3 u 2 z 2 ϕ 2 d x d t ,
and
Q T z 3 ϕ 3 t d x d t Ω z 3 , 0 ( x ) ϕ 3 ( x , 0 ) d x + d 3 Q T z 3 · ϕ 3 d x d t = Q T e 1 z 3 e 2 ( z 3 ) 2 + e 3 z 1 z 3 + e 4 z 2 z 3 ϕ 3 d x d t .
from (50) and (53).
Hence, z = ( z 1 , z 2 , z 3 ) is the weak solution the problem (8)–(12) with u 1 = u 1 , u 2 = u 2 .
By the weak semi-continuity of L 2 norm, we can obtain
lim ̲ i J u 1 n i , u 2 n i = lim ̲ i 0 T Ω w z 2 ( n i ) + 1 2 a 1 ( u 1 ( n i ) ) 2 + 1 2 a 2 ( u 2 ( n i ) ) 2 d x d t 0 T Ω w z 2 + 1 2 a 1 ( u 1 ) 2 + 1 2 a 2 ( u 2 ) 2 d x d t = J ( u 1 , u 2 ) .
It follows from (49) that
J ( u 1 , u 2 ) lim ̲ i J ( u 1 ( n i ) , u 2 ( n i ) ) = lim i J ( u 1 ( n i ) , u 2 ( n i ) ) = inf ( u 1 , u 2 ) U a d J ( u 1 , u 2 ) .
The proof is completed. □

3.2. The First Order Necessary Condition

In this subsection, we study the first order necessary condition.
First of all, we consider the following problem.
w 1 t d 1 Δ w 1 = a 11 w 1 + a 12 w 2 + a 13 w 3 + f 1 , ( x , t ) Q T ,
w 2 t d 2 Δ w 2 = a 21 w 1 + a 22 w 2 + a 23 w 3 + f 2 , ( x , t ) Q T ,
w 3 t d 3 Δ w 3 = a 31 w 1 + a 32 w 2 + a 33 w 3 + f 3 , ( x , t ) Q T ,
w 1 n = w 2 n = w 3 n = 0 , ( x , t ) Γ ,
w 1 ( x , 0 ) = w 0 , 1 , w 2 ( x , 0 ) = w 0 , 2 , w 3 ( x , 0 ) = w 0 , 3 , x Ω ,
where a i j L ( Q T ) , f i L 2 ( Q T ) , w 0 , i H 1 ( Ω ) for i , j = 1 , 2 , 3 .
Next, we give the following lemma.
Lemma 3.
There exists a uniquely solution ( w 1 , w 2 , w 3 ) ( W 2 2 , 1 ( Q T ) ) 3 to the problem (54)–(58) such that
| | w 1 | | W 2 2 , 1 ( Q T ) + | | w 2 | | W 2 2 , 1 ( Q T ) + | | w 3 | | W 2 2 , 1 ( Q T ) C | | f 1 | | L 2 ( Q T ) + | | f 2 | | L 2 ( Q T ) + | | f 3 | | L 2 ( Q T ) + | | w 0 , 1 | | H 1 ( Ω ) + | | w 0 , 2 | | H 1 ( Ω ) + | | w 0 , 3 | | H 1 ( Ω ) ,
where C is depending on Ω , T , | | a i j | | L ( Q T ) , i , j = 1 , 2 , 3 .
In addition, if w 0 , i L ( Ω ) and f i L ( Q T ) for i = 1 , 2 , 3 , then we have
| | w 1 | | L ( Q T ) + | | w 2 | | L ( Q T ) + | | w 3 | | L ( Q T ) H e τ T ,
where
H = max i = 1 , 2 , 3 { | | w 0 , i | | L ( Ω ) , | | f i | | L ( Q T ) } , τ = max i = 1 , 2 , 3 { j = 1 3 | | a i j | | L ( Q T ) + 1 } .
Proof. 
We only prove (59).
Define
( w ¯ 1 , w ¯ 2 , w ¯ 3 ) = ( H e τ t , H e τ t , H e τ t ) , ( w ̲ 1 , w ̲ 2 , w ̲ 3 ) = ( H e τ t , H e τ t , H e τ t ) .
where H , τ are defined as (60) and (61). Similar to the proof of (34), we have
w ̲ i w i w ¯ i , i = 1 , 2 , 3 .
The proof is completed. □
Theorem 3.
Assume u = ( u 1 , u 2 ) is the optimal control, denote by z = ( z 1 , z 2 , z 3 ) the solution to the problem (8)–(12) with u 1 = u 1 , u 2 = u 2 . Let P = ( P 1 , P 2 , P 3 ) be the solution to the following problem
P 1 t d 1 Δ P 1 = a 11 P 1 + a 21 P 2 + a 31 P 3 , ( x , t ) Q T ,
P 2 t d 2 Δ P 2 = a 12 P 1 + a 22 P 2 + a 32 P 3 + w , ( x , t ) Q T ,
P 3 t d 3 Δ P 3 = a 13 P 1 + a 23 P 2 + a 33 P 3 , ( x , t ) Q T ,
P 1 n = P 2 n = P 3 n = 0 , ( x , t ) Γ ,
P 1 ( x , T ) = P 2 ( x , T ) = P 3 ( x , T ) = 0 , x Ω ,
where
a 11 = b 1 ( 1 u 1 ) b 2 z 2 b 3 z 3 , a 12 = ( 1 u 1 ) b 2 z 1 + u 2 , a 13 = b 3 z 1 , a 21 = ( 1 u 1 ) b 2 z 2 , a 22 = c 1 + ( 1 u 1 ) b 2 z 1 c 2 z 3 u 2 , a 23 = c 2 z 2 , a 31 = e 3 z 3 , a 32 = e 4 z 3 , a 33 = e 1 2 e 2 z 3 + e 3 z 1 + e 4 z 2 .
Then, for any u = ( u 1 , u 2 ) U a d , it holds that
Q T q 1 b 2 z 1 z 2 ( P 1 P 2 ) + a 1 u 1 + q 2 z 2 ( P 1 P 2 ) + a 2 u 2 d x d t 0 .
Proof. 
For any u = ( u 1 , u 2 ) U a d , denote q = ( q 1 , q 2 ) = ( u 1 u 1 , u 2 u 2 ) . For n = 1 , 2 , , denote by z ( n ) = ( z 1 ( n ) , z 2 ( n ) , z 3 ( n ) ) the solution of the problem (8)–(12) with u = u + 1 n q . Denote v ( n ) = ( v 1 ( n ) , v 2 ( n ) , v 3 ( n ) ) = z ( n ) z , then v ( n ) satisfies
v 1 ( n ) t d 1 Δ v 1 ( n ) = b 1 v 1 ( n ) ( 1 u 1 ) b 2 z 2 ( n ) v 1 ( n ) ( 1 u 1 ) b 2 z 1 v 2 ( n ) + 1 n q 1 b 2 z 1 ( n ) z 2 ( n ) b 3 v 1 ( n ) z 3 ( n ) b 3 v 3 ( n ) z 1 + u 2 v 2 ( n ) + 1 n q 2 z 2 ( n ) , ( x , t ) Q T , v 2 ( n ) t d 2 Δ v 2 ( n ) = c 1 v 2 ( n ) + ( 1 u 1 ) b 2 z 2 ( n ) v 1 ( n ) + ( 1 u 1 ) b 2 z 1 v 2 ( n ) 1 n q 1 b 2 z 1 ( n ) z 2 ( n ) c 2 v 2 ( n ) z 3 ( n ) c 2 v 3 ( n ) z 2 u 2 v 2 ( n ) 1 n q 2 z 2 ( n ) , ( x , t ) Q T , v 3 ( n ) t d 3 Δ v 3 ( n ) = e 1 v 3 ( n ) e 2 v 3 ( n ) ( z 3 ( n ) + z 3 ) + e 3 v 1 ( n ) z 3 ( n ) + e 3 z 1 v 3 ( n ) + e 4 v 2 ( n ) z 3 ( n ) + e 4 z 2 v 3 ( n ) , ( x , t ) Q T , v 1 ( n ) n = v 2 ( n ) n = v 3 ( n ) n = 0 , ( x , t ) Γ , v 1 ( n ) ( x , 0 ) = v 2 ( n ) ( x , 0 ) = v 3 ( n ) ( x , 0 ) = 0 , x Ω .
From Lemma 3, v ( n ) ( W 2 2 , 1 ( Q T ) L ( Q T ) ) 3 and
v 1 ( n ) L 2 ( Q T ) + v 2 ( n ) L 2 ( Q T ) + v 3 ( n ) L 2 ( Q T ) 1 n C ,
we can obtain
z ( n ) z in ( L 2 ( Q T ) ) 3 as n .
Denote Ψ ( n ) = n v ( n ) . Then, Ψ ( n ) ( W 2 2 , 1 ( Q T ) L ( Q T ) ) 3 is the solution of the following system
Ψ 1 ( n ) t d 1 Δ Ψ 1 ( n ) = b 1 Ψ 1 ( n ) ( 1 u 1 ) b 2 z 2 ( n ) Ψ 1 ( n ) ( 1 u 1 ) b 2 z 1 Ψ 2 ( n ) + q 1 b 2 z 1 ( n ) z 2 ( n ) b 3 Ψ 1 ( n ) z 3 ( n ) b 3 Ψ 3 ( n ) z 1 + u 2 Ψ 2 ( n ) + q 2 z 2 ( n ) , ( x , t ) Q T ,
Ψ 2 ( n ) t d 2 Δ Ψ 2 ( n ) = c 1 Ψ 2 ( n ) + ( 1 u 1 ) b 2 z 2 ( n ) Ψ 1 ( n ) + ( 1 u 1 ) b 2 z 1 Ψ 2 ( n ) q 1 b 2 z 1 ( n ) z 2 ( n ) c 2 Ψ 2 ( n ) z 3 ( n ) c 2 Ψ 3 ( n ) z 2 u 2 Ψ 2 ( n ) q 2 z 2 ( n ) , ( x , t ) Q T ,
Ψ 3 ( n ) t d 3 Δ Ψ 3 ( n ) = e 1 Ψ 3 ( n ) e 2 Ψ 3 ( n ) ( z 3 ( n ) + z 3 ) + e 3 Ψ 1 ( n ) z 3 ( n ) + e 3 z 1 Ψ 3 ( n ) + e 3 Ψ 2 ( n ) z 3 ( n ) + e 4 z 2 Ψ 3 ( n ) , ( x , t ) Q T ,
Ψ 1 ( n ) n = Ψ 2 ( n ) n = Ψ 3 ( n ) n = 0 , ( x , t ) Γ ,
Ψ 1 ( n ) ( x , 0 ) = Ψ 2 ( n ) ( x , 0 ) = Ψ 3 ( n ) ( x , 0 ) = 0 , x Ω .
From Lemma 3, we know that there exists a subsequence of { Ψ ( n ) } n = 1 , denoted by itself, and Ψ ( W 2 2 , 1 ( Q T ) L ( Q T ) ) 3 such that
Ψ ( n ) Ψ in ( L 2 ( Q T ) ) 3 , Ψ ( n ) Ψ in ( L 2 ( Q T ; R N ) 3 , a s n .
Since Ψ ( n ) is the weak solution of the system (68)–(72), we have for any ϕ = ( ϕ 1 , ϕ 2 , ϕ 3 ) ( C ( Q ¯ T ) ) 3 with ϕ 1 n = ϕ 2 n = ϕ 3 n = 0 and ϕ 1 ( x , T ) = ϕ 2 ( x , T ) = ϕ 3 ( x , T ) = 0 ,
Q T Ψ 1 ( n ) ϕ 1 t d x d t + d 1 Q T Ψ 1 ( n ) · ϕ 1 d x d t = Q T ( b 1 Ψ 1 ( n ) ( 1 u 1 ) b 2 z 2 ( n ) Ψ 1 ( n ) ( 1 u 1 ) b 2 z 1 Ψ 2 ( n ) + q 1 b 2 z 1 ( n ) z 2 ( n ) b 3 Ψ 1 ( n ) z 3 ( n ) b 3 Ψ 3 ( n ) z 1 + u 2 Ψ 2 ( n ) + q 2 z 2 ( n ) ) ϕ 1 d x d t ,
Similarly, we have
Q T Ψ 2 ( n ) ϕ 2 t d x d t + d 2 Q T Ψ 2 ( n ) · ϕ 2 d x d t = Q T ( c 1 Ψ 2 ( n ) + ( 1 u 1 ) b 2 z 2 ( n ) Ψ 1 ( n ) + ( 1 u 1 ) b 2 z 1 Ψ 2 ( n ) q 1 b 2 z 1 ( n ) z 2 ( n ) c 2 Ψ 2 ( n ) z 3 ( n ) c 2 Ψ 3 ( n ) z 2 u 2 Ψ 2 ( n ) q 2 z 2 ( n ) ) ϕ 2 d x d t ,
and
Q T Ψ 3 ( n ) ϕ 3 t d x d t + d 3 Q T Ψ 3 ( n ) · ϕ 3 d x d t = Q T e 1 Ψ 3 ( n ) e 2 Ψ 3 ( n ) ( z 3 ( n ) + z 3 ) + e 3 Ψ 1 ( n ) z 3 ( n ) + e 3 z 1 Ψ 3 ( n ) + e 3 Ψ 2 ( n ) z 3 ( n ) + e 4 z 2 Ψ 3 ( n ) ϕ 3 d x d t .
Letting n in the above equalities, we can get from (67) and (73) that
Q T Ψ 1 ϕ 1 t d x d t + d 1 Q T Ψ 1 · ϕ 1 d x d t = Q T ( b 1 Ψ 1 ( 1 u 1 ) b 2 z 2 Ψ 1 ( 1 u 1 ) b 2 z 1 Ψ 2 + q 1 b 2 z 1 z 2 b 3 Ψ 1 z 3 b 3 Ψ 3 z 1 + u 2 Ψ 2 + q 2 z 2 ) ϕ 1 d x d t ,
Similarly, we have
Q T Ψ 2 ϕ 2 t d x d t + d 2 Q T Ψ 2 · ϕ 2 d x d t = Q T ( c 1 Ψ 2 + ( 1 u 1 ) b 2 z 2 Ψ 1 + ( 1 u 1 ) b 2 z 1 Ψ 2 q 1 b 2 z 1 z 2 c 2 Ψ 2 z 3 c 2 Ψ 3 z 2 u 2 Ψ 2 q 2 z 2 ) ϕ 2 d x d t ,
and
Q T Ψ 3 ϕ 3 t d x d t + d 3 Q T Ψ 3 · ϕ 3 d x d t = Q T e 1 Ψ 3 2 e 2 Ψ 3 z 3 + e 3 Ψ 1 z 3 + e 3 z 1 Ψ 3 + e 3 Ψ 2 z 3 + e 4 z 2 Ψ 3 ϕ 3 d x d t .
Hence, Ψ = ( ψ 1 , ψ 2 , ψ 3 ) is the solution of the following system
Ψ 1 t d 1 Δ Ψ 1 = b 1 Ψ 1 ( 1 u 1 ) b 2 z 2 Ψ 1 ( 1 u 1 ) b 2 z 1 Ψ 2 + q 1 b 2 z 1 z 2 b 3 Ψ 1 z 3 b 3 Ψ 3 z 1 + u 2 Ψ 2 + q 2 z 2 , ( x , t ) Q T , Ψ 2 t d 2 Δ Ψ 2 = c 1 Ψ 2 + ( 1 u 1 ) b 2 z 2 Ψ 1 + ( 1 u 1 ) b 2 z 1 Ψ 2 q 1 b 2 z 1 z 2 c 2 Ψ 2 z 3 c 2 Ψ 3 z 2 u 2 Ψ 2 q 2 z 2 , ( x , t ) Q T , Ψ 3 t d 3 Δ Ψ 3 = e 1 Ψ 3 2 e 2 Ψ 3 z 3 + e 3 Ψ 1 z 3 + e 3 z 1 Ψ 3 + e 3 Ψ 2 z 3 + e 4 z 2 Ψ 3 , ( x , t ) Q T , Ψ 1 n = Ψ 2 n = Ψ 3 n = 0 , ( x , t ) Γ , Ψ 1 ( x , 0 ) = Ψ 2 ( x , 0 ) = Ψ 3 ( x , 0 ) = 0 , x Ω .
By computation, we have
J ( u + 1 n q ) J ( u ) = 0 T Ω w z 2 ( n ) w z 2 + 1 2 a 1 ( u 1 + 1 n q 1 ) 2 ( u 1 ) 2 + 1 2 a 2 ( u 2 + 1 n q 2 ) 2 ( u 2 ) 2 d x d t = 0 T Ω w v 2 ( n ) + 1 2 a 1 ( 2 n u 1 q 1 + 1 n 2 q 1 2 ) + 1 2 a 2 ( 2 n u 2 q 2 + 1 n 2 q 2 2 ) d x d t .
It follows from (67) and (73) that
J ( u + 1 n q ) J ( u ) 1 / n = 0 T Ω w Ψ 2 ( n ) + 1 2 a 1 ( 2 u 1 q 1 + 1 n q 1 2 ) + 1 2 a 2 ( 2 u 2 q 2 + 1 n q 2 2 ) d x d t .
Then, we can get
lim n J ( u + 1 n q ) J ( u ) 1 / n = 0 T Ω ( w Ψ 2 + a 1 u 1 q 1 + a 2 u 2 q 2 ) d x d t .
Since ( P 1 , P 2 , P 3 ) is the solution to the system (62)–(66), we have
0 = Q T ( Ψ 1 P 1 t + d 1 Ψ 1 · P 1 a 11 Ψ 1 P 1 a 21 Ψ 1 P 2 a 31 P 3 Ψ 1 ) d x d t ,
Q T w Ψ 2 d x d t = Q T ( Ψ 2 P 2 t + d 2 Ψ 2 · P 2 a 12 Ψ 2 P 1 a 22 Ψ 2 P 2 a 32 P 3 Ψ 2 ) d x d t ,
0 = Q T ( Ψ 3 P 3 t + d 3 Ψ 3 · P 3 a 13 Ψ 3 P 1 a 23 Ψ 3 P 2 a 33 P 3 Ψ 3 ) d x d t .
Summing up the equations (75)–(77), we can obtain
Q T w Ψ 2 d x d t = Q T ( ( Ψ 1 P 1 t d 1 Ψ 1 · P 1 ) + ( Ψ 2 P 2 t d 2 Ψ 2 · P 2 ) + ( Ψ 3 P 3 t d 3 Ψ 3 · P 3 ) i , j = 1 3 a i j Ψ j P i ) d x d t , = Q T ( P 1 ( Ψ 1 t d 1 Ψ 1 ) + P 2 ( Ψ 2 t d 2 Ψ 2 ) + P 3 ( Ψ 3 t d 3 Ψ 3 ) i , j = 1 3 a i j Ψ j P i ) d x d t , = Q T ( q 1 b 2 z 1 z 2 + q 2 z 2 ) P 1 ( q 1 b 2 z 1 z 2 + q 2 z 2 ) P 2 d x d t .
Combining (74) with (78), we have
lim n J ( u + 1 n q ) J ( u ) 1 / n = Q T b 2 z 1 z 2 ( P 1 P 2 ) + a 1 u 1 q 1 + z 2 ( P 1 P 2 ) + a 2 u 2 q 2 d x d t .
Since J ( u ) = inf u U a d J ( u ) , we get
lim n J ( u + 1 n q ) J ( u ) 1 / n 0 .
Hence, it holds that
Q T b 2 z 1 z 2 ( P 1 P 2 ) + a 1 u 1 q 1 + z 2 ( P 1 P 2 ) + a 2 u 2 q 2 d x d t 0 .
The proof is completed. □
From Theorem 3, we can get the formula of the optimal control by standard argument [18].
Corollary 1.
If u = ( u 1 , u 2 ) is an optimal control, then
u 1 = min { M 1 , b 2 a 1 z 1 z 2 ( P 2 P 1 ) + } , u 2 = min { M 2 , 1 a 2 z 2 ( P 2 P 1 ) + } .
where ( z 1 , z 2 , z 3 , P 1 , P 2 , P 3 ) is a solution of the optimality system
z 1 t d 1 z 1 = b 1 z 1 ( 1 min { M 1 , b 2 a 1 z 1 z 2 ( P 2 P 1 ) + } ) b 2 z 1 z 2 b 3 z 1 z 3 + min { M 2 , 1 a 2 z 2 ( P 2 P 1 ) + } z 2 , ( x , t ) Q T ,
z 2 t d 2 z 2 = c 1 z 2 + ( 1 min { M 1 , b 2 a 1 z 1 z 2 ( P 2 P 1 ) + } ) b 2 z 1 z 2 c 2 z 2 z 3 min { M 2 , 1 a 2 z 2 ( P 2 P 1 ) + } z 2 , ( x , t ) Q T ,
z 3 t d 3 z 3 = e 1 z 3 e 2 z 3 2 + e 3 z 1 z 3 + e 4 z 2 z 3 , ( x , t ) Q T ,
P 1 t d 1 Δ P 1 = a 11 P 1 + a 21 P 2 + a 31 P 3 , ( x , t ) Q T ,
P 2 t d 2 Δ P 2 = a 12 P 1 + a 22 P 2 + a 32 P 3 + w , ( x , t ) Q T ,
P 3 t d 3 Δ P 3 = a 13 P 1 + a 23 P 2 + a 33 P 3 , ( x , t ) Q T ,
z 1 n = z 2 n = z 3 n = 0 , ( x , t ) Γ ,
P 1 n = P 2 n = P 3 n = 0 , ( x , t ) Γ ,
z 1 ( x , 0 ) = z 1 , 0 ( x ) , z 2 ( x , 0 ) = z 2 , 0 ( x ) , z 3 ( x , 0 ) = z 3 , 0 ( x ) , x Ω ,
P 1 ( x , T ) = P 2 ( x , T ) = P 3 ( x , T ) = 0 , x Ω .

4. The Local Uniqueness of the Optimal Control

In this section, we prove the uniqueness of the solution to the optimality system (80)–(89) when T is sufficiently small.
Theorem 4.
There exists a positive constant Λ, such that if T is sufficiently small, the optimality system (80)–(89) has only one solution.
Proof. 
Take T < 1 . Assume ( z ˜ 1 , z ˜ 2 , z ˜ 3 , P ˜ 1 , P ˜ 2 , P ˜ 3 ) and ( z ¯ 1 , z ¯ 2 , z ¯ 3 , P ¯ 1 , P ¯ 2 , P ¯ 3 ) are two solutions of the optimality system (80)–(89). From Theorem 1, we have
z ˜ i L ( Q T ) C 1 , z ¯ i L ( Q T ) C 1 , i = 1 , 2 , 3 ,
where C 1 is a positive constant independent of T. From Theorem 4, we have
P ˜ i L ( Q T ) C 2 , P ¯ i L ( Q T ) C 2 , i = 1 , 2 , 3 ,
where C 2 is a positive constant independent of T. Let
z ˜ 1 = e λ t ξ ˜ 1 , z ˜ 2 = e λ t ξ ˜ 2 , z ˜ 3 = e λ t ξ ˜ 3 , P ˜ 1 = e λ t ζ ˜ 1 , P ˜ 2 = e λ t ζ ˜ 2 , P ˜ 3 = e λ t ζ ˜ 3 ,
z ¯ 1 = e λ t ξ ¯ 1 , z ¯ 2 = e λ t ξ ¯ 2 , z ¯ 3 = e λ t ξ ¯ 3 , P ¯ 1 = e λ t ζ ¯ 1 , P ¯ 2 = e λ t ζ ¯ 2 , P ¯ 3 = e λ t ζ ¯ 3 .
where λ > 0 is to be determined.
From (79), define
u ˜ 1 = min { M 1 , b 2 a 1 z ˜ 1 z ˜ 2 ( P ˜ 2 P ˜ 1 ) + } , u ˜ 2 = min { M 2 , 1 a 2 z ˜ 2 ( P ˜ 2 P ˜ 1 ) + } ,
u ¯ 1 = min { M 1 , b 2 a 1 z ¯ 1 z ¯ 2 ( P ¯ 2 P ¯ 1 ) + } , u ¯ 2 = min { M 2 , 1 a 2 z ¯ 2 ( P ¯ 2 P ¯ 1 ) + } .
Take (92)–(95) into the equations (80), we obtain
λ ξ ˜ 1 + ξ ˜ 1 t d 1 ξ ˜ 1 = b 1 ξ ˜ 1 ( 1 u ˜ 1 ) b 2 e λ t ξ ˜ 1 ξ ˜ 2 b 3 e λ t ξ ˜ 1 ξ ˜ 3 + u ˜ 2 ξ ˜ 2 , λ ξ ¯ 1 + ξ ¯ 1 t d 1 ξ ¯ 1 = b 1 ξ ¯ 1 ( 1 u ¯ 1 ) b 2 e λ t ξ ¯ 1 ξ ¯ 2 b 3 e λ t ξ ¯ 1 ξ ¯ 3 + u ¯ 2 ξ ¯ 2 .
Hence, we have
λ ( ξ ˜ 1 ξ ¯ 1 ) + ( ξ ˜ 1 ξ ¯ 1 ) t d 1 ( ξ ˜ 1 ξ ¯ 1 ) = b 1 ( ξ ˜ 1 ξ ¯ 1 ) b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 1 ξ ˜ 2 ( 1 u ¯ 1 ) ξ ¯ 1 ξ ¯ 2 b 3 e λ t ( ξ ˜ 1 ξ ˜ 3 ξ ¯ 1 ξ ¯ 3 ) + ( u ˜ 2 ξ ˜ 2 u ¯ 2 ξ ¯ 2 ) .
Similarly, we have
λ ( ξ ˜ 2 ξ ¯ 2 ) + ( ξ ˜ 2 ξ ¯ 2 ) t d 2 ( ξ ˜ 2 ξ ¯ 2 ) = c 1 ( ξ ˜ 2 ξ ¯ 2 ) + b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 1 ξ ˜ 2 ( 1 u ¯ 1 ) ξ ¯ 1 ξ ¯ 2 c 2 e λ t ( ξ ˜ 2 ξ ˜ 3 ξ ¯ 2 ξ ¯ 3 ) ( u ˜ 2 ξ ˜ 2 u ¯ 2 ξ ¯ 2 ) , λ ( ξ ˜ 3 ξ ¯ 3 ) + ( ξ ˜ 3 ξ ¯ 3 ) t d 3 ( ξ ˜ 3 ξ ¯ 3 ) = e 1 ( ξ ˜ 3 ξ ¯ 3 ) e 2 e λ t ( ξ ˜ 3 2 ξ ¯ 3 2 ) + e 3 e λ t ( ξ ˜ 1 ξ ˜ 3 ξ ¯ 1 ξ ¯ 3 ) + e 4 e λ t ( ξ ˜ 2 ξ ˜ 3 ξ ¯ 2 ξ ¯ 3 ) , λ ( ζ ˜ 1 ζ ¯ 1 ) ( ζ ˜ 1 ζ ¯ 1 ) t d 1 ( ζ ˜ 1 ζ ¯ 1 ) = b 1 ( ζ ˜ 1 ζ ¯ 1 ) b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 2 ζ ˜ 1 ( 1 u ¯ 1 ) ξ ¯ 2 ζ ¯ 1 b 3 e λ t ( ξ ˜ 3 ζ ˜ 1 ξ ¯ 3 ζ ¯ 1 ) + b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 2 ζ ˜ 2 ( 1 u ¯ 1 ) ξ ¯ 2 ζ ¯ 2 + e 3 e λ t ( ξ ˜ 3 ζ ˜ 3 ξ ¯ 3 ζ ¯ 3 ) , λ ( ζ ˜ 2 ζ ¯ 2 ) ( ζ ˜ 2 ζ ¯ 2 ) t d 2 ( ζ ˜ 2 ζ ¯ 2 ) = c 1 ( ζ ˜ 2 ζ ¯ 2 ) b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 1 ζ ˜ 1 ( 1 u ¯ 1 ) ξ ¯ 1 ζ ¯ 1 + ( u ˜ 2 ζ ˜ 1 u ¯ 2 ζ ¯ 1 ) + b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 1 ζ ˜ 2 ( 1 u ¯ 1 ) ξ ¯ 1 ζ ¯ 2 c 2 e λ t ( ξ ˜ 3 ζ ˜ 2 ξ ¯ 3 ζ ¯ 2 ) ( u ˜ 2 ζ ˜ 2 u ¯ 2 ζ ¯ 2 ) + e 4 e λ t ( ξ ˜ 3 ζ ˜ 3 ξ ¯ 3 ζ ¯ 3 ) , λ ( ζ ˜ 3 ζ ¯ 3 ) ( ζ ˜ 3 ζ ¯ 3 ) t d 3 ( ζ ˜ 3 ζ ¯ 3 ) = b 3 e λ t ( ξ ˜ 1 ζ ˜ 1 ξ ¯ 1 ζ ¯ 1 ) c 2 e λ t ( ξ ˜ 2 ζ ˜ 2 ξ ¯ 2 ζ ¯ 2 ) + e 1 ( ζ ˜ 3 ζ ¯ 3 ) 2 e 2 e λ t ( ξ ˜ 3 ζ ˜ 3 ξ ¯ 3 ζ ¯ 3 ) + e 3 e λ t ( ξ ˜ 1 ζ ˜ 3 ξ ¯ 1 ζ ¯ 3 ) + e 4 e λ t ( ξ ˜ 2 ζ ˜ 3 ξ ¯ 2 ζ ¯ 3 ) .
Denote l 1 = ξ ˜ 1 ξ ¯ 1 , l 2 = ξ ˜ 2 ξ ¯ 2 , l 3 = ξ ˜ 3 ξ ¯ 3 , m 1 = ζ ˜ 1 ζ ¯ 1 , m 2 = ζ ˜ 2 ζ ¯ 2 , m 3 = ζ ˜ 3 ζ ¯ 3 . Then ( l 1 , l 2 , l 3 , m 1 , m 2 , m 3 ) satisfies the following system
λ l 1 + l 1 t d 1 l 1 = a 11 l 1 + a 12 l 2 + a 13 l 3 + h 1 , ( x , t ) Q T ,
λ l 2 + l 2 t d 2 l 2 = a 21 l 1 + a 22 l 2 + a 23 l 3 + h 2 , ( x , t ) Q T , λ l 3 + l 3 t d 3 l 3 = a 31 l 1 + a 32 l 2 + a 33 l 3 + h 3 , ( x , t ) Q T ,
λ m 1 m 1 t d 1 m 1 = a 41 l 1 + a 42 l 2 + a 43 l 3 + a 44 m 1 + a 45 m 2 + a 46 m 3 + h 4 , ( x , t ) Q T ,
λ m 2 m 2 t d 2 m 2 = a 51 l 1 + a 52 l 2 + a 53 l 3 + a 54 m 1 + a 55 m 2 + a 56 m 3 + h 5 , ( x , t ) Q T , λ m 3 m 3 t d 3 m 3 = a 61 l 1 + a 62 l 2 + a 63 l 3 + a 64 m 1 + a 65 m 2 + a 66 m 3 + h 6 , ( x , t ) Q T , l 1 n = l 2 n = l 3 n = m 1 n = m 2 n = m 3 n = 0 , ( x , t ) Γ , l 1 ( x , 0 ) = l 2 ( x , 0 ) = l 3 ( x , 0 ) = m 1 ( x , T ) = m 2 ( x , T ) = m 3 ( x , T ) = 0 , x Ω ,
where
a 11 = b 1 b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 2 b 3 e λ t ξ ˜ 3 , a 12 = b 2 e λ t ( 1 u ˜ 1 ) ξ ¯ 1 + u ˜ 2 , a 13 = b 3 e λ t ξ ¯ 1 , h 1 = b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 1 ξ ¯ 2 + ( u ˜ 2 u ¯ 2 ) ξ ¯ 2 , a 21 = b 2 e λ t ( 1 u ˜ 1 ) ξ ˜ 2 , a 22 = c 1 + b 2 e λ t ( 1 u ˜ 1 ) ξ ¯ 1 c 2 e λ t ξ ˜ 3 u ˜ 2 , a 23 = c 2 e λ t ξ ¯ 2 , h 2 = b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 1 ξ ¯ 2 ( u ˜ 2 u ¯ 2 ) ξ ¯ 2 , a 31 = e 3 e λ t ξ ˜ 3 , a 32 = e 4 e λ t ξ ˜ 3 , a 33 = e 1 e 2 e λ t ( ξ ˜ 3 + ξ ¯ 3 ) + e 3 e λ t ξ ¯ 1 + e 4 e λ t ξ ¯ 2 , h 3 = 0 , a 41 = 0 , a 42 = b 2 e λ t ( 1 u ˜ 1 ) ζ ˜ 1 + b 2 e λ t ( 1 u ˜ 1 ) ζ ˜ 2 , a 43 = b 3 e λ t ζ ˜ 1 + e 3 e λ t ξ ˜ 3 , a 44 = b 1 b 2 e λ t ( 1 u ˜ 1 ) ξ ¯ 2 b 3 e λ t ξ ¯ 3 , a 45 = b 2 e λ t ( 1 u ˜ 1 ) ξ ¯ 2 , a 46 = e 3 e λ t ξ ¯ 3 , h 4 = b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 2 ζ ¯ 1 + b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 2 ζ ¯ 2 , a 51 = b 2 e λ t ( 1 u ˜ 1 ) ζ ¯ 1 + b 2 e λ t ( 1 u ˜ 1 ) ζ ˜ 2 , a 52 = 0 , a 53 = c 2 e λ t ζ ˜ 2 + e 4 e λ t ζ ˜ 3 , a 54 = ( 1 u ˜ 1 ) ξ ¯ 1 + u ˜ 2 , a 55 = c 1 + b 2 e λ t ( 1 u ˜ 1 ) ξ ¯ 1 + c 2 e λ t ξ ¯ 3 u ˜ 2 , a 56 = e 4 e λ t ξ ¯ 3 , h 5 = b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 1 ζ ¯ 1 + ( u ˜ 2 u ¯ 2 ) ζ ¯ 1 + b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 1 ζ ¯ 2 ( u ˜ 2 u ¯ 2 ) ζ ¯ 2 , a 61 = b 3 e λ t ζ ˜ 1 + e 3 e λ t ζ ˜ 3 , a 62 = c 2 e λ t ζ ˜ 2 + e 4 e λ t ζ ˜ 3 , a 63 = 2 e 2 e λ t ζ ˜ 3 , a 64 = b 3 e λ t ξ ¯ 1 , a 65 = c 2 e λ t ξ ¯ 2 , a 66 = e 1 2 e 2 e λ t ξ ¯ 3 + e 3 e λ t ξ ¯ 1 + e 4 e λ t ξ ¯ 2 , h 6 = 0 .
Note that from (90)–(95) that
| u ˜ 1 u ¯ 1 | b 2 a 1 | z 1 ˜ z 2 ˜ ( P ˜ 2 P ˜ 1 ) z 1 ¯ z 2 ¯ ( P ¯ 2 P ¯ 1 ) | b 2 a 1 | z 1 ˜ z 2 ˜ ( P ˜ 2 P ˜ 1 ) ( P ¯ 2 P ¯ 1 ) + z 1 ˜ ( P ¯ 2 P ¯ 1 ) ( z 2 ˜ z 2 ¯ ) + z 2 ¯ ( P ¯ 2 P ¯ 1 ) ( z 1 ˜ z 1 ¯ ) | b 2 a 1 | z 1 ˜ z 2 ˜ ( P ˜ 2 P ¯ 2 ) ( P ˜ 1 P ¯ 1 ) + z 1 ˜ ( P ¯ 2 P ¯ 1 ) e λ t ( ξ ˜ 2 ξ ¯ 2 ) + z 2 ¯ ( P ¯ 2 P ¯ 1 ) e λ t ( ξ ˜ 1 ξ ¯ 1 ) | b 2 a 1 | z 1 ˜ z 2 ˜ e λ t ( m 2 m 1 ) + z 1 ˜ ( P ¯ 2 P ¯ 1 ) e λ t l 2 + z 2 ¯ ( P ¯ 2 P ¯ 1 ) e λ t l 1 | C e λ t | l 1 | + e λ t | l 2 | + e λ t ( | m 2 | + | m 1 | ) .
and
| u ˜ 2 u ¯ 2 | 1 a 2 | z 2 ˜ ( P ˜ 2 P ˜ 1 ) z 2 ¯ ( P ¯ 2 P ¯ 1 ) | 1 a 2 | z 2 ˜ ( P ˜ 2 P ˜ 1 ) ( P ¯ 2 P ¯ 1 ) + ( P ¯ 2 P ¯ 1 ) ( z 2 ˜ z 2 ¯ ) | 1 a 2 | z 2 ˜ ( P ˜ 2 P ¯ 2 ) ( P ˜ 1 P ¯ 1 ) + ( P ¯ 2 P ¯ 1 ) ( z 2 ˜ z 2 ¯ ) | 1 a 2 | z 2 ˜ e λ t ( m 2 m 1 ) + ( P ¯ 2 P ¯ 1 ) e λ t l 2 | C e λ t | l 2 | + e λ t ( | m 2 | + | m 1 | ) .
where C is a constant that does not depend on λ , t , T . Multiply (96) by l 1 and integrate by parts to get
Q T ( λ l 1 2 + l 1 t l 1 d 1 l 1 l 1 ) d x d t = λ Q T l 1 2 d x d t + 1 2 Ω l 1 2 ( x , T ) d x + d 1 Q T | l 1 | 2 d x d t = Q T ( a 11 l 1 2 + a 12 l 1 l 2 + a 13 l 1 l 3 + h 1 l 1 ) d x d t C Q T ( l 1 2 + l 2 2 + l 3 2 + h 1 2 ) d x d t .
Note that from (90)–(91) and (98)–(99), we have
Q T h 1 2 d x d t = Q T b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 1 ξ ¯ 2 ( u ˜ 2 u ¯ 2 ) ξ ¯ 2 2 d x d t C Q T e λ t ( u ¯ 1 u ˜ 1 ) ( u ˜ 2 u ¯ 2 ) 2 d x d t C Q T ( l 1 2 ) d x d t .
From (100) and (101), we have
λ Q T l 1 2 d x d t C Q T ( l 1 2 + l 2 2 + l 3 2 ) d x d t .
Similarly, we can obtain
λ Q T l 2 2 d x d t C Q T ( l 1 2 + l 2 2 + l 3 2 ) d x d t .
and
λ Q T l 3 2 d x d t C Q T ( l 1 2 + l 2 2 + l 3 2 ) d x d t .
Multiply (97) by m 1 and integrate by parts to get
Q T ( λ m 1 2 m 1 t m 1 d 1 m 1 m 1 ) d x d t = λ Q T m 1 2 d x d t + 1 2 Ω m 1 2 ( x , 0 ) d x + Q T | m 1 | 2 d x d t = Q T ( a 41 l 1 m 1 + a 42 l 2 m 1 + a 43 l 3 m 1 + a 44 m 1 2 + a 45 m 2 m 1 + a 46 m 3 m 1 + h 4 m 1 ) d x d t C Q T ( | a 41 | l 1 2 + | a 42 | l 2 2 + | a 43 | l 3 2 ) + ( i = 1 6 | a 4 i | + e 2 λ t ) m 1 2 + | a 45 | m 2 2 + | a 46 | m 3 2 + e 2 λ t h 4 2 d x d t C Q T e 2 λ t ( l 1 2 + l 2 2 + l 3 2 + m 1 2 ) + ( m 1 2 + m 2 2 + m 3 2 ) + e 2 λ t h 4 2 d x d t .
Due to the boundedness of P ¯ 1 , we have
Q T e 2 λ t h 4 2 d x d t = Q T e 2 λ t b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 2 ζ ¯ 1 + b 2 e λ t ( u ¯ 1 u ˜ 1 ) ξ ¯ 2 ζ ¯ 2 2 d x d t C Q T ( u ¯ 1 u ˜ 1 ) ξ ¯ 2 ( ζ ¯ 2 ζ ¯ 1 ) 2 d x d t C Q T e 2 λ t ( l 1 2 + l 2 2 ) + ( m 1 2 + m 2 2 ) d x d t .
From (105) and (106), we have
λ Q T m 1 2 d x d t C Q T e 2 λ t ( l 1 2 + l 2 2 + l 3 2 + m 1 2 ) d x d t + C Q T ( m 1 2 + m 2 2 + m 3 2 ) d x d t .
Similarly, we have
λ Q T m 2 2 d x d t C Q T e 2 λ t ( l 1 2 + l 2 2 + l 3 2 + m 2 2 ) d x d t + C Q T ( m 1 2 + m 2 2 + m 3 2 ) d x d t .
and
λ Q T m 3 2 d x d t C Q T e 2 λ t ( l 1 2 + l 2 2 + l 3 2 + m 3 2 ) d x d t + C Q T ( m 1 2 + m 2 2 + m 3 2 ) d x d t .
It follows from (102)–(104) and (107)–(109) that
λ Q T ( l 1 2 + l 2 2 + l 3 2 + m 1 2 + m 2 2 + m 3 2 ) d x d t ( C 1 + C 2 e 2 λ t ) Q T ( l 1 2 + l 2 2 + l 3 2 + m 1 2 + m 2 2 + m 3 2 ) d x d t .
Take λ > C 1 + C 2 e 2 λ t and Λ = min { 1 2 λ ln λ C 1 C 2 , 1 } , then for 0 < T < Λ , we have
Q T ( l 1 2 + l 2 2 + l 3 2 + m 1 2 + m 2 2 + m 3 2 ) d x d t = 0 .
then we have
l 1 = l 2 = l 3 = m 1 = m 2 = m 3 = 0 .
which implies
ξ ˜ 1 = ξ ¯ 1 , ξ ˜ 2 = ξ ¯ 2 , ξ ˜ 3 = ξ ¯ 3 , ζ ˜ 1 = ζ ¯ 1 , ζ ˜ 2 = ζ ¯ 2 , ζ ˜ 3 = ζ ¯ 3 .
Hence,
z ˜ 1 = z ¯ 1 , z ˜ 2 = z ¯ 2 , z ˜ 3 = z ¯ 3 , P ˜ 1 = P ¯ 1 , P ˜ 2 = P ¯ 2 , P ˜ 3 = P ¯ 3 .
The proof is completed. □
From Corollary 1 and Theorem 4, one can get the uniqueness of the optimal control to the problem min ( u 1 , u 2 ) U a d J ( u 1 , u 2 ) if T is sufficiently small.

5. Numerical Experiments

In this section, we use the finite difference method to numerically simulate the optimal control problem for the prey–predator model with disease in prey.
Firstly, we briefly describe the numerical procedure used to solve the optimal control problem in Algorithm 1.
Algorithm 1 Iterative algorithm
  • Input d S , d I , d Y , A , β , d , η 1 , c , η 2 , r , k , p 1 , p 2 , a 1 , a 2 , w , M 1 , M 2 , S 0 ( x ) , I 0 ( x ) , Y 0 ( x ) .
  • Initialize the control variables u i ( k ) = 0 , i = 1 , 2 , k = 0 .
  • With the known controls u i ( k ) , solve the state variables S ( k + 1 ) , I ( k + 1 ) , Y ( k + 1 ) by the forward difference method.
  • With the known controls u i ( k ) and the state variables S ( k + 1 ) , I ( k + 1 ) , Y ( k + 1 ) , solve the adjoint variables P i ( k + 1 ) , i = 1 , 2 , 3 by the backward difference method.
  • Using the state variables S ( k + 1 ) , I ( k + 1 ) , Y ( k + 1 ) and the adjoint variables P i ( k + 1 ) , update the optimal control variables u i ( k + 1 ) = 0 , i = 1 , 2 by using the relation u 1 = min { M 1 , β S I a 1 ( P 2 ( k + 1 ) P 1 ( k + 1 ) ) + } , u 2 = min { M 2 , I a 2 ( P 2 ( k + 1 ) P 1 ( k + 1 ) ) + } .
  • If | u i ( k + 1 ) u i ( k ) | < ϵ , output the results. Otherwise, set k = k + 1 and repeat from step 3.
Before performing the numerical simulations, it is necessary to determine the values of the parameters that appear in models (1)–(5) and (62)–(66). We make appropriate assumptions about the values of these parameters. For clarity, the values of the parameters are listed in the following table.
The numerical experiments are carried out in the unit square domain Q T = ( 0 , 1 ) × ( 0 , 1 ) .
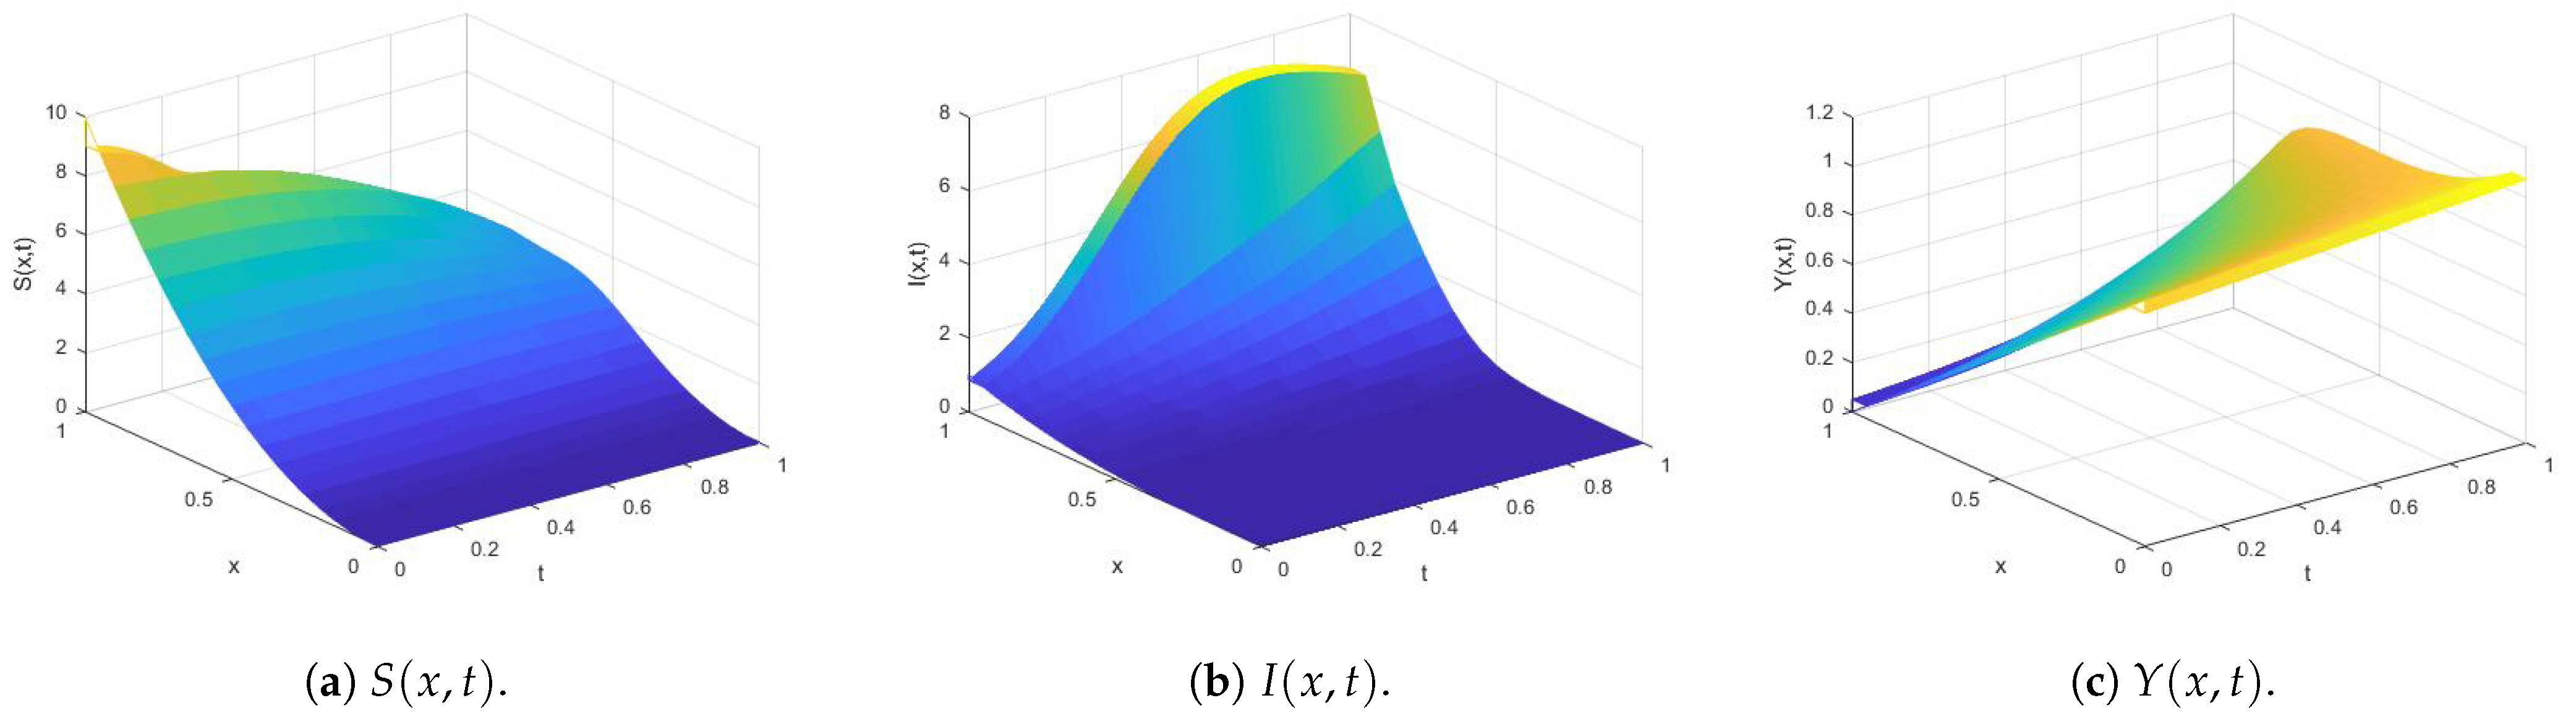
By using the above iterative method, we numerically solve the optimal harvesting problem under the Neumann boundary condition with the parameters listed in Table 1. The optimal controls are shown in Figure 1, and the optimal states are shown in Figure 2.
In Figure 1a, u 1 ( x , t ) represents optimal control of the isolation treatment of infected prey. In Figure 1b, u 2 ( x , t ) represents optimal control of drug treatment of infected prey.
In Figure 2a, S ( x , t ) represents the densities of the susceptible prey. In Figure 2b, I ( x , t ) represents the densities of the infected prey. In Figure 2c, Y ( x , t ) represents the densities of the predator.

6. Conclusions

In this paper, a prey–predator diffusion model with isolated and drug treatment control measures for prey infection is studied. This coupled parabolic model simulates the interaction between susceptible prey, infected prey, and predator populations. In this model, we aim to find the optimal control pair under boundary conditions so that the population density of the infected population and the cost of isolation and treatment are minimized. Through mathematical analysis, we proved the existence and uniqueness of the weak solution to the model, derived the first-order necessary conditions for the optimal control, further demonstrated the existence and local uniqueness of the optimal control, and verified the feasibility of the model’s optimal control strategy through numerical simulations. In the future, the model can be further expanded by introducing stochastic factors to better reflect the uncertainties in the real world, especially in the context of disease transmission. The results of this study are of great significance to the fields of ecological modeling, epidemiology, and public health. By optimizing control measures, this study provides theoretical references for how to efficiently manage disease outbreaks in animal populations and formulate more effective control policies and intervention measures in different ecological and epidemiological contexts.

Author Contributions

Conceptualization, F.X.; Investigation, Y.N.; Writing—original draft, X.L.; Writing—review & editing, R.D. All authors have read and agreed to the published version of the manuscript.

Funding

This study was supported by the National Natural Science Foundation of China (12401287, 12160145).

Data Availability Statement

No data were used to support the findings of this study.

Conflicts of Interest

The authors declare that they have no conflicts of interest.

Main Notation Description

In this section, we will explain the parameters involved in this paper one by one.
SThe population density of the susceptible prey
IThe population density of the infected prey
YThe population density of the predator
d S The diffusion coefficient of the susceptible prey
d I The diffusion coefficient of the infected prey
d Y The diffusion coefficient of the predator
AThe birth rate of susceptible prey
β The infection rate of susceptible prey
dThe death rate for susceptible prey
η 1 The prey rate of susceptible prey
cThe natural and disease-induced death rate for infected prey
η 2 The prey rate of infected prey
rThe growth rate of predator
kThe carrying capacity for predator
p 1 The conversion rate of predatory susceptible prey to predator
p 2 The conversion rate of predator infected prey to predator
S 0 ( x ) The initial value of the population densitie of susceptible prey
I 0 ( x ) The initial value of the population densitie of infected prey
Y 0 ( x ) The initial value of the population densitie of predator
u 1 The isolation rate of infected prey
u 2 The cure rate of drug treatment for infected prey
U a d The admissible control set
M i The upper bound of control u i , i = 1 , 2
wThe weight factor
a 1 The price for isolating infected prey
a 2 The price for drug treatment for susceptible and infected prey
z 1 It respectively represents the function S
z 2 It respectively represents the function I
z 3 It respectively represents the function Y
d 1 It respectively represents the function d S
d 2 It respectively represents the function d I
d 3 It respectively represents the function d Y
b 1 It respectively represents the function A d
b 2 It respectively represents the function β
b 3 It respectively represents the function η 1
c 1 It respectively represents the function c
c 2 It respectively represents the function η 2
e 1 It respectively represents the function r
e 2 It respectively represents the function r k
e 3 It respectively represents the function p 1 η 1
e 4 It respectively represents the function p 2 η 2
z 1 , 0 ( x ) It respectively represents the function S 0 ( X )
z 2 , 0 ( x ) It respectively represents the function I 0 ( X )
z 3 , 0 ( x ) It respectively represents the function Y 0 ( X )

References

  1. Chattopadhyay, J.; Arino, O. A predator-prey model with disease in the prey. Nonlinear Anal. 1999, 36, 747–766. [Google Scholar] [CrossRef] [Scilit]
  2. Xiao, Y.; Chen, L. Modeling and analysis of a predator-prey model with disease in the prey. Math. Biosci. 2001, 171, 59–82. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  3. Niu, X.; Zhang, T.; Teng, Z. The asymptotic behavior of a nonautonomous eco-epidemic model with disease in the prey. Appl. Math. Model. 2011, 35, 457–470. [Google Scholar] [CrossRef] [Scilit]
  4. Li, J.; Gao, W. Analysis of a prey-predator model with disease in prey. Appl. Math. Comput. 2010, 217, 4024–4035. [Google Scholar] [CrossRef] [Scilit]
  5. Pan, M.; Yang, J.; Lin, Z. Analysis of a nonautonomous eco-epidemic diffusive model with disease in the prey. Math. Methods Appl. Sci. 2018, 41, 1796–1808. [Google Scholar] [CrossRef] [Scilit]
  6. Amalia, R.U.D.; Arif, D.K. Optimal control of predator-prey mathematical model with infection and harvesting on prey. J. Phys. Conf. Ser. 2018, 974, 012050. [Google Scholar] [CrossRef] [Scilit]
  7. Simon, J.S.H.; Rabago, J.F.T. Optimal control for a predator-prey model with disease in the prey population. Malays. J. Math. Sci. 2018, 12, 269–285. [Google Scholar]
  8. Hugo, A.; Simanjilo, E. Analysis of an eco-epidemiological model under optimal control measures for infected prey. Appl. Appl. Math. 2019, 14, 117–138. [Google Scholar]
  9. Mekonen, K.G.; Bezabih, A.F.; Rao, K.P. Mathematical Modeling of Infectious Disease and Prey-Predator Interaction with Optimal Control. Int. J. Math. Math. Sci. 2024, 2024, 5444627. [Google Scholar] [CrossRef] [Scilit]
  10. Miyaoka, T.Y.; Lenhart, S.; Meyer, J.F.C.A. Optimal control of vaccination in a vector-borne reaction-diffusion model applied to Zika virus. J. Math. Biol. 2019, 79, 1077–1104. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  11. Dai, F.; Liu, B. Optimal control problem for a general reaction-diffusion eco-epidemiological model with disease in prey. Appl. Math. Model. 2020, 88, 1–20. [Google Scholar] [CrossRef] [Scilit]
  12. Sowndarrajan, P.T.; Nyamoradi, N.; Shangerganesh, L.; Manimaran, J. Mathematical analysis of an optimal control problem for the predator-prey model with disease in prey. Optim. Control Appl. Methods 2020, 41, 1495–1509. [Google Scholar] [CrossRef] [Scilit]
  13. Baranovskii, E.S.; Brizitskii, R.V.; Saritskaia, Z.Y. Optimal control problems for the reaction-diffusion-convection equation with variable coefficients. Nonlinear Anal. Real World Appl. 2024, 75, 103979. [Google Scholar] [CrossRef] [Scilit]
  14. Simon, J. Compact sets in Lp(0, T; B). Ann. Mat. Pura Appl. 1987, 146, 65–96. [Google Scholar] [CrossRef] [Scilit]
  15. Adams, R.A.; Fournier, J.J.F. Sobolev Spaces; Elsevier: Amsterdam, The Netherlands, 2003. [Google Scholar]
  16. Pao, C.V. Nonlinear Parabolic and Elliptic Equations; Springer: Berlin/Heidelberg, Germany, 2012. [Google Scholar]
  17. Lions, P.L. Mathematical Topics in Fluid Mechanics; Incompressible Models; Clarendon Press: Oxford, UK, 1996; Volume I. [Google Scholar]
  18. Tröltzsch, F. Optimal Control of Partial Differential Equations: Theory, Methods, and Applications; American Mathematical Society: Providence, RI, USA, 2010; Volume 112. [Google Scholar]
Figure 1. Optimal control of the treatment measures for infected prey.
Mathematics 13 02069 g001
Figure 2. Optimal states of the densities of the respective populations.
Mathematics 13 02069 g002
Table 1. The values of the model parameters.
ParameterValueSourceParameterValueSource
d S 0.0001[11] d I 0.0002[11]
d Y 0.00006[11]A0.5Assumed
β 0.7[12]d0.2Assumed
η 1 0.33[12]c0.7[12]
η 2 0.44[12]r0.12Assumed
k100Assumed p 1 0.525[12]
p 2 0.525[12] a 1 0.5Assumed
a 2 0.2Assumedw0.04[12]
M 1 0.4Assumed M 2 0.2Assumed
S 0 ( x ) 10 x 2 Assumed I 0 ( x ) x 3 Assumed
Y 0 ( x ) 1 x Assumed ϵ 0.00001 Assumed
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.