


Abstract
Recent literature and empirical evidence reveal that, compared to advanced economies (AEs), most emerging market economies (EMEs) exhibit much lower volatilities of unemployment rate, and they link these differences to the larger size of informal economies in EMEs. As a representative EME, real data indicate that China also exhibits a lower volatility of unemployment rate, while the size of informal economy in China is quite small. Therefore, we argue that it is the large size of unregistered employment, not the size of informal economy, that plays the key role in explaining the lower volatility of unemployment rate in China. We constructed a DSGE model incorporating unregistered employment and revised Nash wage bargaining to support our hypothesis. We found that there exist “diminishing effects” to the deviations of unemployment rate triggered by shocks under bigger size of unregistered employment condition. The standard deviation of unemployment rate has negative correlation with the size of unregistered employment, which means identical shocks will induce lower volatility of unemployment rate under larger size of unregistered employment condition. We conclude that the costs of unregistered employment far outweigh their benefits and, facing a complicated, changeable and deteriorating external environment, a labor market without such distortion of employment is more beneficial for the sustainable development of the Chinese labor market.
1. Introduction
Recent literature and empirical evidence reveal that, compared to advanced economies (AEs), most emerging market economies (EMEs) exhibit much lower absolute and relative volatilities (with respect to output) of unemployment rate. For instance, using the data of 14 EMEs and 14 AEs from 1980 Q1–2018 Q2, Horvath and Yang [1] find that the mean absolute and relative standard deviations of unemployment rate in 14 EMEs are 9.26 and 4.63 (see Table 1), much lower than the means of 14 AEs (11.03, 7.74), and they link these differences to the larger size of informal economies in EMEs. As a representative EME, real data indicate that China also exhibits the distinct unemployment rate dynamics with a lower absolute volatility (0.023) and relative volatility (1.92) compared to Australia and USA, representative AEs (see Table 2). While as estimated by the insightful paper of Schneider et al. [2], the size of informal economy in China is quite small, ranking 9th among 151 countries and even much smaller than most AEs. Therefore, we argue that the size of informal economy cannot explain the distinct unemployment rate dynamics of China.
Table 1.
Unemployment rate dynamics and informalities of 14 EMEs and 14 AEs.
Table 2.
Unemployment rate dynamics and informality of China.
We hypothesize that the large size of unregistered employment may be an alternative and play the key role in explaining the distinct unemployment rate dynamics of China. The unregistered employment refers to the phenomenon that a proportion of registered unemployment workers are actually employed by firms that can earn incomes. The immediate cause for the existence of unregistered employment is the “moral risk” under information asymmetry and imperfect labor regulation environment [3]. For unregistered employment workers, they can earn wages from firms, which is an opportunity to survive, and they can also receive unemployment benefits from the government at the same time. While for firms, hiring unregistered employment workers means cost reductions, they can pay only a portion of wage to unregistered employment workers with the same labor inputs, but without paying various social insurances compared with formal employees. Therefore, these “mutual benefits”, together with the rigidity and weak enforcement of labor regulation in China, promote the existence of unregistered employment. The unregistered employment was considered to be a unique and temporary phenomenon during the economic transition periods [4], however, it has proved to be quite common in China [5]. Although there have been no official data, we can still confirm the existence of a large number of unregistered employment workers in China from regional surveys or literature. For instance, a survey conducted by the Nanjing Municipal Labor and Social Security Department in 1997 found that about 40% registered unemployment workers actually were working in Nanjing. A joint survey conducted by the Chinese Academy of Labor Sciences and the World Bank in 1998 found the proportion was about 46.8% in Wuhan and Shenyang. Lu and Tian [6] found the proportion was more than 40% in Shanghai, based on the survey data of Shanghai, 2005.
The unregistered employment in this paper is quite different from the conventional informal economy literature [7,8]. In these papers, workers are divided into formally employed workers, informally employed workers and unemployed workers. While in our paper, workers are classified into three categories: formally employed workers, registered unemployment workers who actually have jobs (unregistered employment workers) and registered unemployment workers with no jobs that coincide with the definition of unregistered employment and the reality of China. This setting is extremely important as it adds a new choice for workers and changes the structure of Nash wage bargaining while is ignored.
As a widely used macroeconomic analysis framework, DSGE has advantages in dealing with the volatilities of variables; therefore, we construct a DSGE model incorporating unregistered employment and revised Nash wage bargaining to investigate the effects of unregistered employment on the distinct unemployment rate dynamics of China. We find that the standard deviation of unemployment rate has negative correlation with the size of unregistered employment, which means identical shocks will induce lower volatility of unemployment rate under the larger size of unregistered employment condition. These findings support our hypothesis that it is the large size of unregistered employment, not the size of informal economy, that plays the key role in explaining the lower volatility of unemployment rate in China. We also analyze the tradeoffs of unregistered employment, and we conclude that the costs of unregistered employment far outweigh its benefits. A labor market without such distortion of employment is more beneficial for the sustainable development of the Chinese labor market.
This paper relates to the literature on unemployment rate dynamics. The Diamond–Mortensen–Pissarides search-matching model (DMP) pioneered by Diamond [9], Mortensen [10] and Pissarides [11] reasonably explains the “labor market friction” where job vacancy and unemployment coexist and provide a framework for studying unemployment rate dynamics. Since then, the DMP search-matching model has become a standard theoretical model and is quite popular in analyzing unemployment problems. However, Shimer [12] argues that the conventional DMP search-matching model cannot generate the observed high degree of unemployment rate dynamics in response to shocks of a plausible magnitude due to the Nash wage bargaining settings, where employees receive a constant fraction of the match surplus. Solving Shimer’s argument, one strand of the literature upholds the correctness of the DMP search-matching model, e.g., Hagedorn and Manovskii [13] recalibrate the value of non-market activity and the bargaining weights and find that the model is consistent with the data. Another strand modifies the traditional DMP search-matching model, e.g., by introducing real wage rigidity [12], staggered multi-period Nash wage bargaining [14] or alternating offer bargaining [15]. An explosion of recent literature also incorporates labor market frictions into DSGE model to better explain the dynamics of the business cycle [16]. This kind of augmented DSGE model performs well in analyzing the unemployment rate dynamics in response to various shocks; however, there is little literature focused on the distinct unemployment rate dynamics of China, and no theoretical DSGE model with unregistered employment and revised Nash wage bargaining has been constructed before.
This paper also relates to the literature on China’s unemployment problems. The related literature concentrates on the following four aspects: the characteristics and determinants of China’s unemployment [17], the status of China’s unemployment [18]; the links between economic growth and China’s unemployment [19] and the countermeasures to promote employment and reduce China’s unemployment rate [20]. However, the existing research literature focuses on qualitative analyses; therefore, it lacks quantitative analyses and also ignores the importance of unregistered employment on the unemployment rate dynamics of China.
Finally, this paper adds to the large literature on explaining the differences in business cycle volatilities between EMEs and AEs. For instance, compared to AEs, EMEs seems to exhibit higher fluctuations on consumption relative to output [21], higher output volatilities but lower employment fluctuations [8], lower absolute and relative volatilities of unemployment rate [1]. This paper focuses on the unemployment rate dynamics while, as mentioned earlier, existing literature links the distinct unemployment rate dynamics in EMEs to the larger size of informal economies, whereas this paper identifies the role of unregistered employment and provides a new perspective for understanding the distinct unemployment rate dynamics in EMEs.
This paper contributes to the literature in three ways. First, in terms of research subject, we explain the lower absolute and relative volatilities of unemployment rate in China from the perspective of unregistered employment which the previous literature rarely studied. Second, in terms of research method, we introduce unregistered employment and revised Nash wage bargaining into DSGE model that made our model more in line with the situation of China’s labor market. Third, in terms of research results, we identify the important role of unregistered employment on unemployment rate dynamics of China and put forward policy recommendations to cope with this labor market distortion for the sustainable development of the Chinese labor market.
The remainder of this paper is organized as follows: we describe and estimate the DSGE model in Section 2. In Section 3, we present the model fit and apply this model to investigate the effects of unregistered employment on unemployment rate dynamics of China. In Section 4, we discuss the main findings and also analyze the tradeoffs of unregistered employment. Section 5 is the conclusion and implications.
2. The DSGE Model
2.1. Household
In the open economy, there exists a representative household that has a unit measure of workers. We denote as the portion of formally employed workers at time , and they earn real wage . The remaining portion of workers is in the status of unemployment; then unemployment rate equals . Among the unemployment workers, a portion of workers under-report their employment, and they are in the status of unregistered employment. The number of unregistered employment workers is non-optimization based; it depends on the rigidity and enforcement of China’s labor regulation; therefore, we assume it follows an exogenous progress: . Moreover, we assume firms pay only a portion of real wage , to unregistered employment workers without modeling the detailed types of cost reductions. For registered unemployment workers with no jobs, we assume they earn zero income. In each period, the representative household makes decisions on consumption, labor supply, investment and different bonds holding. They earn wages, own capital and rent to firms at a total capital return rate , get interests from different bonds holding, own firms and earn revenues and pay a lump-sum tax to the government. The representative household obtains separable utilities from consumption and leisure and will always maximize life utilities subject to real budget constraint and capital accumulation equation:
where denotes the real consumption; denotes the aggregate labor supply:; denotes the aggregate price level of final consumption goods; denotes the aggregate price level of final investment goods; denotes the domestic bonds holding; denotes the foreign bonds holding; denotes the exchange rate; denotes the portion of domestic bonds holding: ; is the quadratic portfolio adjustment cost following Chang et al. [22]; denotes the real investment; denotes the exogenous investment-specific technology shock: ; is the real investment adjustment cost following Christiano et al. [23]; denotes the domestic interest rate; and denotes the external interest rate that follows an exogenous process: . By solving Equation (1), we get the first-order conditions:
where and denote the Lagrangian multipliers for real budget constraint and capital accumulation equation, respectively, and denotes the inflation rate at time : .
2.2. Firms
2.2.1. Final Goods Firms
There exist two competitive final goods firms in the economy. One firm produces the final consumption goods using domestic final consumption goods and imported final consumption goods : . The other firm produces the final investment goods using domestic final investment goods and imported final investment goods . The two competitive firms will always maximize profits subject to respective production function:
where denotes the price of domestic final consumption (investment) goods and denotes the price of imported final consumption (investment) goods. By solving Equation (3), we get the first-order conditions:
2.2.2. Domestic Final Goods Firm
Domestic final goods are produced by a representative firm in the economy. This competitive domestic final goods firm buys intermediate domestic goods at price and manufactures domestic final goods : , where denotes the exogenous markup of domestic goods market: . The competitive domestic final goods firm will always maximize profits subject to production function:
By solving Equation (5), we get the demand equation for domestic intermediate goods : .
2.2.3. Domestic Intermediate Goods Firms
Domestic intermediate goods are produced by a continuum of domestic intermediate goods firms, indexed by . Each intermediate goods firm produces a different intermediate good monopolistically using identical Cobb-Douglas function:, where denotes the exogenous technology level: , is the capital rented from household at the capital return rate , is the total labor input that is composed by formally employed workers and unregistered employment workers . In each period, the representative monopolistic intermediate goods firm decides the formally employed workers input , capital input , and hiring unregistered employment workers (as it is always beneficial) to minimize cost subject to production function:
We denote as the marginal cost, and by solving Equation (6), we get the following equations:
Next, we introduce Calvo [24] price rigidity into our model. In each period, only a constant portion of domestic intermediate goods firms can reoptimize price after receiving “price-change signal” and the remaining portion of intermediate goods firms are not allowed to reoptimize prices freely. Furthermore, firms that cannot reoptimize prices are allowed to partially index prices to past inflation of domestic final goods, and the indexation is controlled by . The representative intermediate goods firm that last reoptimize the price to at time t will always maximize life-sum real profits subject to the demand function of its product:
By solving Equation (8), we get the first-order conditions:
where , are auxiliary variables to compute the optimal price , and , .
2.2.4. Importing Firms
There exists a continuum of foreign countries in the world, indexed by . Moreover, there exist two types of importing firms in the economy. One type is a continuum of importing firms that buy differentiated imported goods at price (expressed in domestic currency) while selling them at price . The other type is a representative, competitive final importing firm that aggregates the differentiated imported goods into imported final goods : , where denotes the exogenous markup of the import goods market: . The representative final importing firm will always maximize profits subject to its production function:
By solving Equation (10), we get the demand equation for differentiated imported goods : .
The continuum of importing firms that buy differentiated imported goods also face the optimal price setting problem, and we introduce Calvo price rigidity as in Section 2.2.3. In each period, only a constant portion of importing firms can reoptimize price after receiving “price-change signal”, and the remaining portion of importing firms are not allowed to reoptimize prices freely but are allowed to partially index prices to past inflation of the imported final goods, which we define as , and the indexation is controlled by . The representative importing firm that last reoptimizes price to at time t will always maximize life-sum real profits subject to the demand function of its product:
where , and by solving Equation (11), we get the first-order conditions:
where , are auxiliary variables to compute the optimal price , and .
2.2.5. Exporting Firms
There exist two types of exporting firms in the economy. One type is a continuum of exporting firms that buy domestic final goods at price while selling them at price . The other type is a representative, competitive final exporting firm that aggregates into exported final goods . We can derive the demand equation for : where is the price of exported final goods expressed in domestic currency, is the exogenous markup of the export goods market: . is the quantity of exported final goods that satisfies the equation of , where is the world output that follows an exogenous process: . Moreover, we define as the total export, then . Finally, the world inflation also follows an exogenous process: .
The continuum of exporting firms also face optimal price setting problem the same as importing firms. In each period, only a constant portion of exporting firms can reoptimize price after receiving “price-change signal” and the remaining portion of exporting firms are not allowed to reoptimize prices freely but are allowed to partially index prices to past world inflation, which is , and the indexation is controlled by . The representative exporting firm that last reoptimizes price to at time t will always maximize life-sum real profits subject to the demand function of its product:
where , and by solving Equation (13), we get the first-order conditions:
where , are auxiliary variables to compute the optimal price , and .
2.3. Nash Bargaining and Real Wage Rigidity
Consistent with existing literature, the real wage is determined through period-by-period Nash bargaining between firms and workers in our model, and we assume only formally employed workers have wage bargaining power and they renegotiate real wages with domestic intermediate goods firms each period. At the beginning of period t, there is an exogenous proportion of formally employed workers that are separated from the existing working relationships, and since unregistered employment workers have no job securities, we assume they all separate from the existing working relationships. Therefore, at the beginning of period t, only formally employed workers have jobs and the number of jobless individuals who are available for hire is equal to . In addition, domestic intermediate goods firms would hire formally employed workers, unregistered employment workers, along with the existing formally employed workers to produce at period t. We denote as the representative formally employed worker’s surplus from the existing match; then the equation for is:
where denotes the job-finding rate of formal work at period : , denotes the job-finding rate of informal work at period : , denotes the surplus from the perspective of unregistered employment workers, and denotes the surplus from the perspective of unemployment workers with no jobs. Equation (15) can be interpreted as the total surplus from the existing match that the representative formally employed worker calculates. At period , she earns real wage but suffers an opportunity cost measured by the marginal rate of substitution. At period , she has probability of maintaining the existing match and probability of rematching and obtaining the surplus , probability of matching the informal work and obtaining the surplus , and probability of turning into unemployment worker with no jobs and obtaining the surplus . For the surpluses of and , we have:
Therefore, the net surplus to the representative formally employed worker from existing match, which we denote as , is:
For the domestic intermediate goods firms, we assume they can replace any existing formally employed worker after paying a hiring cost : . Note that this setting is the same as in Blanchard and Galí [25] and Galí [26] but different with canonical DMP search-matching framework as vacancies are assumed to be filled immediately by paying the hiring cost. Therefore, the representative intermediate domestic goods firm would be willing to pay a maximum real wage up to a premium given by the hiring cost: , while the representative formally employed worker would accept a minimum real wage that equals the difference between real wage and net surplus: , otherwise the formal work has no longer attraction. Any real wage lies in this wage band [], guaranteeing that both positive net surplus for firm and formally employed worker can make the real wage bargaining succeed.
While as indicated by Shimer [12], the mechanism for wage determination within period-by-period Nash bargaining induces too much volatility in wages, therefore, it cannot generate the observed high degree of unemployment rate dynamics in response to shocks of a plausible magnitude. To solve this problem, large amounts of literature demonstrate that (real) wage rigidity may play a key role [14,27]. We introduce real wage rigidity by making real wage depend on a weighted average of lagged real wage and current symmetric Nash bargaining real wage inspired by Hall [27]:
where measures the degree of real wage rigidity, and denotes the symmetric Nash bargaining real wage that lies at the center of the above wage band: , which also means the intermediate domestic goods firm and formally employed worker will share the same net surplus: .
2.4. Monetary Authority
Monetary policy is controlled by the monetary authority under the widely used Taylor role:
2.5. Government
For government expenditure , we set it as a proportion of GDP following Christiano et al. [28]: , where the ratio follows an exogenous process: . In each period, the government balances its budget by issuing domestic bonds and the lump-sum tax received from household:
Fiscal policy is designed so that the lump-sum tax will increase if the government debt exceeds its steady-state level:
Finally, according to the model economy, balance of payment will evolve as follows:
To sum up, we construct a DSGE model with 5 sectors, 11 shocks and 52 parameters to study the impacts of unregistered employment on the unemployment rate dynamics of China. We convert all the nominal variables into real variables to prevent unit root problems when solving this DSGE model. We put all the relevant equations in the Appendix A and solve this DSGE model using Dynare (4.6.1 version). We estimate the values of 52 parameters using a mixed method of calibration and Bayesian estimation as we discuss below.
2.6. Model Estimation
We calibrate the values of 18 parameters that are consistent with canonical DSGE papers, and the details are reported in Table 3. The consumption habit formation parameter h is fixed at 0.7. The discount factor is fixed at 0.99. The quadratic portfolio adjustment cost coefficient is fixed at 0.6. The labor utility constant is fixed at 0.1. The real investment adjustment cost constant is fixed at 0.25. The Frisch elasticity is fixed at 2. The capital depreciation parameter is fixed at 0.025. The capital share of product function is fixed at 0.4. The fiscal role coefficient is fixed at 0.05. The exogenous job separation rate is fixed at 0.1. The wage rate of unregistered employment workers is fixed at 0.6, which means hiring an unregistered employment worker is a 40% cost reduction for firms. The reason for this calibration is that, in China, firms should pay endowment insurance (21% of wage), medical insurance (9% of wage), unemployment insurance (2% of wage), employment injury insurance (0.5% of wage), maternity insurance (0.5% of wage) and housing provident fund (5–12% of wage) for formally employed workers, which is a total of about 40% of wage, while need not pay for unregistered employment workers. The curvature of hiring cost function is fixed at 1. The coefficient parameters in monetary policy , are fixed at 1.5, 0.25, respectively. Home bias in domestic consumption and investment , are fixed at 0.75, 0.84, respectively. The steady-state ratio of domestic bonds holding and markup of domestic goods market are fixed at 0.9, 10/9, respectively.
Table 3.
Parameter calibration.
The remaining 34 parameters’ values are estimated by the Bayesian approach using 7 Chinese macroeconomic data that are real GDP per capita, real consumption per capita, real government expenditure per capita, real export of goods per capita, real import of goods per capita, domestic inflation, and unemployment rate from 2002:1 to 2019:4. The data we used are available from the National Bureau of Statistics, CSMAR database, and IMF database. The original data of real GDP per capita, real consumption per capita, real government expenditure per capita, real export of goods per capita, real import of goods per capita, and unemployment rate are seasonally adjusted using X-13 in Eviews, then taken logarithm and one-sided HP-filter in Matlab to obtain demeaned cycle components. The original stable data of aggregate inflation data are used directly. Accordingly, the observation equations are set as follows to match the model variables:
To conduct Bayesian estimation, we select the prior distributions of parameters, mainly referring to Burriel et al. [34], Christiano et al. [28], Sheen and Wang [35], and Wang et al. [36]. The parameter Bayesian estimation results are reported in Table 4, and we omit detailed descriptions.
Table 4.
Parameter Bayesian estimation.
3. Results
3.1. Model Fit
After model construction and estimation, we assess model fit to test whether the estimated DSGE can account for the Chinese business cycle, and the results are shown in Table 5. We can see that the model matches real data well and successfully reproduces the business cycle moments we need, including standard deviations of real output and unemployment, relative unemployment rate volatility and unemployment rate counter-cyclicality.
Table 5.
Business cycle moments of China: real data versus baseline model.
3.2. Impulse Response Function (IRF)
We apply this DSGE model from the impulse response function to present the responses of unemployment rate when shocks hit the economy, and we also vary the size of unregistered employment workers to see the changes in these responses. Moreover, these results help us to identify the rule of unregistered employment on the distinct unemployment rate dynamics of China.
In the baseline DSGE model, the steady-state number of unregistered employment workers is set to be 0.016 that coincide with real data and literature. In this section, we set two other values to present the role of unregistered employment and the differences in unemployment rate deviations when identical shocks hit the economy. The steady-state number of unregistered employment workers is set to be 0.024 that represents a larger size of unregistered employment, and 0.008 that represents a smaller size of unregistered employment.
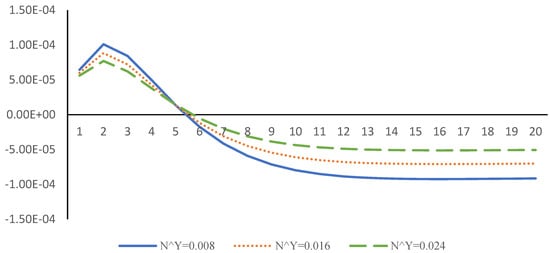
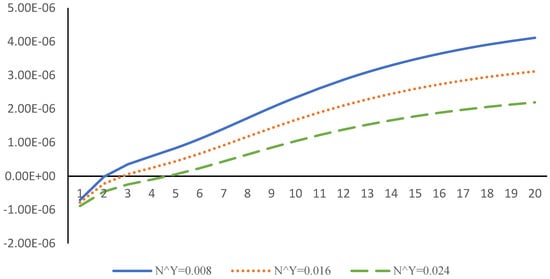
Below, Figure 1 and Figure 2 are the impulse response results of unemployment rate under three different steady-state numbers of unregistered employment workers. Vertical axis is the deviations of unemployment rate from steady-state, and according to Figure 1 and Figure 2, we can clearly confirm that there exist “diminishing effects” to the deviations of unemployment rate triggered by shocks under bigger size of unregistered employment condition. In other words, the standard deviation of unemployment rate has negative correlation with the size of unregistered employment, which means identical shocks will induce lower volatility of unemployment rate under larger size of unregistered employment condition. For space limitation, we only present the impulse response results of two representative shocks, while these results are indeed robust as we also find these “diminishing effects” when the other 9 shocks hit the economy.
Figure 1.
IRF of unemployment rate to foreign interest rate shock.
Figure 2.
IRF of unemployment rate to world output shock.
Finally, we remove unregistered employment from the baseline model (by setting ) and report the simulated unemployment rate moments of modified model in Table 6. According to Table 6, we see that the absolute volatility of unemployment rate increases to 0.082, which is significantly larger than Australia (0.054). Moreover, the relative volatility to output also increases to 3.73, which is more than twice compared to the real data.
Table 6.
Unemployment moments of China: real data versus modified model.
All these results support our hypothesis that it is the large size of unregistered employment, not the size of informal economy, that plays the key role in explaining the lower volatility of unemployment rate in China.
4. Discussion
We hypothesize that, for China, it is the large size of unregistered employment that plays the key role in explaining the distinct unemployment rate dynamics of China, and we construct a DSGE model with unregistered employment to support this hypothesis. Compared to other macroeconomic analysis frameworks, the DSGE model is the most widely used model when dealing with volatilities of variables. Moreover, through the impulse response function of the DSGE model, we can get the volatilities of unemployment rate when various important shocks hit the economy, and by removing unregistered employment from the baseline model, we can identify its role. The DSGE model incorporating unregistered employment and revised Nash wage bargaining is just the most suitable model for testing our hypothesis.
Next, we discuss the trade-offs of unregistered employment. In the previous section, we identify the “diminishing effects” of unregistered employment, making unemployment rate less volatile when shocks hit the economy, helping to stabilize the domestic economy and not depart too much from its steady-state level. However, we argue that the benefits are limited in the sense that they should even not exist, while the costs of unregistered employment are indeed huge.
The unregistered employment is born in an imperfect labor regulation environment and crowds out formal work opportunities. Therefore, for households, they could have been employed formally and obtained more wages and social insurances. For government, it pays unemployment benefits to unregistered employment workers while they are not “real unemployed”, and these payments, combined with tax avoidances due to unregistered employment, heavily increase fiscal burden. Furthermore, the existence of unregistered employment makes unemployment largely mismeasured and misleads policymakers as accurate identification of “real unemployed” is always a premise for formulating relevant policies. Therefore, we conclude that the costs of unregistered employment far outweigh its benefits and should be eliminated in the development process.
5. Conclusions
The main purpose of this paper is to understand the lower absolute and relative volatilities of China’s unemployment rate. Different from the existing literature that links distinct unemployment rate dynamics of EMEs to the larger size of informal economies, we hypothesize that the large size of unregistered employment may be an alternative and play the key role in explaining the distinct unemployment rate dynamics of China. By a DSGE model incorporating unregistered employment and revised Nash wage bargaining, we confirm that there exist “diminishing effects” to the deviations of unemployment rate triggered by shocks under bigger size of unregistered employment condition. The standard deviation of unemployment rate has negative correlation with the size of unregistered employment which means identical shocks will induce lower volatility of unemployment rate under larger size of unregistered employment condition.
We also analyze the tradeoffs of unregistered employment that shed light on policy recommendations. We conclude that the costs of unregistered employment far outweigh its benefits and should be eliminated in the development process. Facing a complicated, changeable and deteriorating external environment, our results have important implications for the sustainable development of the Chinese labor market. We recommend that the Chinese government should focus on turning unregistered employment into formal employment. The Chinese government should improve the urban employment registration system, investigate the scale of unregistered employment, strengthen the supervision of enterprises and the job market, gradually eliminate unregistered employment and turn unregistered employment into formal employment. A labor market without such distortion of employment is indeed more beneficial for the sustainable development of the Chinese labor market.
Finally, we reveal the limitations and future research directions associated with this paper. First, we identify the role of unregistered employment on distinct unemployment rate of China but lack international perspective. For most EMEs with lower absolute and relative volatilities of unemployment rate, the role of unregistered employment is still not confirmed. Second, we use current symmetric Nash real wage bargaining in the DSGE model, while alternative real wage bargaining modeling methods, such as staggered multi-period Nash wage bargaining and alternating offer bargaining, or alternative macroeconomic analysis framework, can also be applied for robustness check. In the future, we will try alternative modeling methods and calibrate this DSGE model to more EMEs to confirm the role of unregistered employment in understanding the lower unemployment rate volatilities of EMEs.
Funding
This research was funded by the National Natural Science Foundation of China, grant number 71773079.
Data Availability Statement
Not applicable.
Conflicts of Interest
The authors declare no conflict of interest. The funders had no role in the design of the study; in the collection, analyses or interpretation of data; in the writing of the manuscript; or in the decision to publish the results.
Appendix A
This Appendix presents the relevant equations of the DSGE model.
- 1.
- 2.
- 3.
- 4.
- 5.
- 6.
- 7.
- 8.
- 9.
- 10.
- 11.
- 12.
- 13.
- 14.
- 15.
- 16.
- 17.
- 18.
- 19.
- 20.
- 21.
- 22.
- 23.
- 24.
- 25.
- 26.
- 27.
- 28.
- 29.
- 30.
- 31.
- 32.
- 33.
- 34.
- 35.
- 36.
- 37.
- 38.
- 39.
- 40.
- ,
- 41.
- 42.
- 43.
- 44.
- 45.
- 46.
- 47.
- 48.
- 49.
- 50.
- 51.
- 52.
- 53.
References
- Horvath, J.; Yang, G.Y. Unemployment Dynamics and Informality in Small Open Economies. Eur. Econ. Rev. 2021, 141, 103949. [Google Scholar] [CrossRef] [Scilit]
- Schneider, F.; Buehn, A.; Montenegro, C.E. Shadow Economies All Over the World: New Estimates for 162 Countries from 1999 to 2007. In Handbook on the Shadow Economy; Edward Elgar Publishing: Cheltenham, UK, 2011; pp. 9–77. [Google Scholar]
- Yuan, Z.G.; Lu, M. Theoretical Analysis on Implicit Employment. Zhejiang Soc. Sci. 1999, 1, 12–16. [Google Scholar]
- Wei, H.Q.; Cai, S.X. Theoretical Analysis of Implicit Employment. J. Cent. Univ. Financ. Econ. 1999, 5, 10–14. [Google Scholar]
- Xiang, P.; Zhao, D.; Xie, S.Y. The Effect of Minimum Wage on Formal and Informal Sectors’ Wage and Employment. J. Quant. Tech. Econ. 2016, 10, 94–109. [Google Scholar]
- Lu, M.; Tian, S.C. Explicit Unemployment or Implicit Employment?—Evidence from Shanghai Household Survey Data. Manag. World 2008, 1, 48–56. [Google Scholar]
- Fernández, A.; Meza, F. Informal Employment and Business Cycles in Emerging Economies: The case of Mexico. Rev. Econ. Dyn. 2015, 18, 381–405. [Google Scholar] [CrossRef] [Scilit]
- Leyva, G.; Urrutia, C. Informality, Labor Regulation, and the Business Cycle. J. Int. Econ. 2020, 126, 103340. [Google Scholar] [CrossRef] [Scilit]
- Diamond, P.A. Aggregate Demand Management in Search Equilibrium. J. Political Econ. 1982, 90, 881–894. [Google Scholar] [CrossRef] [Scilit]
- Mortensen, D.T. Property Rights and Efficiency in Mating, Racing, and Related Games. Am. Econ. Rev. 1982, 72, 968–979. [Google Scholar]
- Pissarides, C.A. Short-run Equilibrium Dynamics of Unemployment, Vacancies, and Real Wages. Am. Econ. Rev. 1985, 74, 676–690. [Google Scholar]
- Shimer, R. The Cyclical Behavior of Equilibrium Unemployment and Vacancies. Am. Econ. Rev. 2005, 95, 25–49. [Google Scholar] [CrossRef] [Scilit]
- Hagedorn, M.; Manovskii, I. The Cyclical Behavior of Equilibrium Unemployment and Vacancies Revisited. Am. Econ. Rev. 2008, 98, 1692–1706. [Google Scholar] [CrossRef] [Scilit]
- Gertler, M.; Trigari, A. Unemployment Dynamics with Staggered Nash Wage Bargaining. J. Political Econ. 2009, 117, 38–86. [Google Scholar] [CrossRef] [Scilit]
- Christiano, L.J.; Eichenbaumz, M.S.; Trabandt, M. Unemployment and Business Cycles. Econometrica 2016, 84, 1523–1569. [Google Scholar] [CrossRef] [Scilit]
- Christiano, L.J.; Trabandt, M.; Walentin, K. Involuntary Unemployment and the Business Cycle. Rev. Econ. Dyn. 2021, 39, 26–54. [Google Scholar] [CrossRef] [Scilit]
- Yang, S.L.; Yao, J. Research on the Unemployment Risk Change of China’s Floating Population and Its Proximate Determinants. Chin. J. Popul. Sci. 2020, 3, 33–46. [Google Scholar]
- Cai, F. China’s Labor Market Development and Employment Changes. Econ. Res. J. 2007, 7, 4–14. [Google Scholar]
- Cai, F.; Du, Y.; Gao, W.S. Employment Elasticity, NAIRU, and Macroeconomic Policies. Econ. Res. J. 2004, 9, 18–25. [Google Scholar]
- Guo, C.L. Fiscal Expansion, Heterogeneous Firms, and Employment in Urban China. Econ. Res. J. 2018, 5, 88–102. [Google Scholar]
- Horvath, J. Business Cycles, Informal Economy, and Interest Rates in Emerging Countries. J. Macroecon. 2018, 55, 96–116. [Google Scholar] [CrossRef] [Scilit]
- Chang, C.; Liu, Z.; Spiegel, M.M. Capital Controls and Optimal Chinese Monetary Policy. J. Monet. Econ. 2015, 74, 1–15. [Google Scholar] [CrossRef] [Scilit]
- Christiano, L.J.; Trabandt, M.; Walentin, K. Introducing Financial Frictions and Unemployment into a Small Open Economy Model. J. Econ. Dyn. Control. 2011, 35, 1999–2041. [Google Scholar] [CrossRef] [Scilit]
- Calvo, G.A. Staggered Prices in a Utility-maximizing Framework. J. Monet. Econ. 1983, 12, 383–398. [Google Scholar] [CrossRef] [Scilit]
- Blanchard, O.; Galí, J. Labor Markets and Monetary Policy: A New-Keynesian Model with Unemployment. Am. Econ. J. Macroecon. 2010, 2, 1–30. [Google Scholar] [CrossRef] [Scilit]
- Galí, J. Monetary Policy and Unemployment. In Handbook of Monetary Economics; Elsevier: Amsterdam, The Netherlands, 2010; pp. 487–546. [Google Scholar]
- Hall, R.E. Employment Dynamics with Equilibrium Wage Stickiness. Am. Econ. Rev. 2005, 95, 50–65. [Google Scholar] [CrossRef] [Scilit]
- Christiano, L.J.; Motto, R.; Rostagno, M. Risk Shocks. Am. Econ. Rev. 2014, 104, 27–65. [Google Scholar] [CrossRef] [Scilit]
- Wang, B.; Li, L.; Hao, D.P. Monetary Policy Uncertainty, Default Risks, and Macroeconomic Dynamics. Econ. Res. J. 2019, 3, 119–134. [Google Scholar]
- Wang, L.Y.; Ji, Y. Fiscal Volatility and Fiscal Roles: Based on Open Economy DSGE Model. Econ. Res. J. 2019, 6, 121–135. [Google Scholar]
- Mei, D.Z.; Zhao, X.J. Country Portfolio and Business Cycle Transmission. Econ. Res. J. 2015, 4, 62–76. [Google Scholar]
- Li, X.Y. Dynamic Stochastic General Equilibrium Model: Theory, Methodology, and Dynare Practice, 1st ed.; Tsinghua University Press: Beijing, China, 2018. [Google Scholar]
- Kang, L.; Gong, L.T. Financial Frictions, Net Worth of Bank, and Transmission of International Crisis: Based on Multi-sector DSGE Model Analysis. Econ. Res. J. 2014, 5, 147–159. [Google Scholar]
- Burriel, P.; Fernández-Villaverde, J.; Rubio-Ramírez, J.F. MEDEA: A DSGE Model for the Spanish Economy. SERIEs 2010, 1, 175–243. [Google Scholar] [CrossRef] [Scilit]
- Sheen, J.; Wang, B.Z. An Estimated Small Open Economy Model with Labour Market Frictions. In Dynare Working Papers Series; CEPREMAP: Paris, France, 2014. [Google Scholar]
- Wang, X.; Wang, L.; Peng, Y.L.; Song, X.F. Comparative Study of China’s Monetary Policy Roles: On the Perspective of Three Roles Based on the DSGE Model. Econ. Res. J. 2017, 9, 24–38. [Google Scholar]
- Deng, H.L.; Chen, L.Y. Labor Productivity Shock, Wage Stickiness, and Real Business Cycle in China. China Ind. Econ. 2019, 1, 23–42. [Google Scholar]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2022 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).