


Abstract
This study conducts a bibliometric analysis of the scientific literature on digital, automated, and AI-assisted accounting systems. The data include documents listed in the Web of Science and Scopus databases. The analysis identifies the main authors, countries/territories, sources, and thematic trends. The results reveal that the scientific output within this research field has increased since 2018, emphasising the integration of artificial intelligence (AI), robotic process automation, and blockchain technologies in accounting. The findings also suggest that automation enhances efficiency, accuracy, and reliability while also raising concerns about ethics, cybersecurity, and job displacement. This study evaluates the accounting research from early discussions on information systems and automation to current topics such as digital transformation, sustainability, and intelligent decision-making. Furthermore, it contributes to the understanding of the scientific development of digital accounting and addresses future research directions involving AI and machine learning for predictive analytics and fraud detection, blockchain for secure and transparent accounting systems, sustainability through the integration of ESG reporting, and interdisciplinary collaboration between accounting, computer science, and business management to develop intelligent financial systems. The findings provide insights for academics and practitioners aiming to understand the ongoing digital transformation of accounting systems.
1. Introduction
Discussion about accounting system automation is a relevant issue in the accounting literature and practice. In the 1950s, when some automated systems became available in accounting, aspects related to their adoption to record, organise, process, and produce readable information ready for decision-making became a relevant topic related to companies’ accounting procedures in digitalisation. Furthermore, the development of Integrated Data Processing (IDP) was an opportunity to improve automated accounting procedures and to change companies’ ways of business, from pricing management and client management to the overall internal processes, leading to cost reduction (Keenoy, 1958).
Moreover, the emergence of the electronic computer led to concerns and fears among professionals due to the extensive relevance given to electronic data processing (Carlson, 1957). Additionally, automated accounting systems heightened fears among professionals about job displacement. However, with the advent of electronic devices and information systems able to record, organise, and process large amounts of financial data, business operations became increasingly complex. At the same time, information systems evolved exponentially, becoming more sophisticated and capable of producing highly detailed financial documents that enhanced the understandability of financial reports and the reliability of financial statements while requiring fewer accounting professionals. As a result, information systems now provide the most useful information for firms’ stakeholders in their decision-making processes, fulfilling the main goal of financial reporting (Financial Accounting Standards Board, 2016; International Accounting Standards Board, 2018).
The faster development of information systems and artificial intelligence (AI), robotic process automation (RPA), and computer-coded and rule-based software robots to automate specific human tasks (Deloitte, 2018) represents a great deal of opportunities. However, the adoption of such technologies in accounting reshapes accounting systems, imposes new paradigms, and breaks arrangements between the speed, cost, and quality of accounting information, implying a growing impact of new technologies on overall business operations (Schatsky et al., 2015) while introducing a set of risks for the accountancy industry. However, the opportunities seem to surpass the threats, as accounting software developers are proceeding in developing software tailored to use accounting data to produce intelligent reports, enabling accountants to make informed decisions and deliver greater value to their clients (Association of Chartered Certified Accountants, 2013) and increasing their available time to focus on advisory services and other higher-value work (Jariwala, 2015).
Despite the development of information systems and their adoption in accountancy, the growing complexity of international business operations represents a source of additional noise in accounting systems. Nevertheless, automation aligns with the needs of accounting and finance, where a high degree of accuracy and consistency is essential. Many accounting tasks remain repetitive and manual, often involving transaction processing and data integration from fragmented systems, which require extensive data manipulation and report generation. RPA is leading the way, rapidly contributing to digitalising companies’ business operations (Deloitte, 2018).
Technological developments are expected to reshape the accountancy profession (Association of Chartered Certified Accountants, 2013). Furthermore, despite the likely disruption, specifically among employees, the adoption of automated accounting procedures enhances work quality and accuracy, thereby saving accountants time (Fernández & Aman, 2018), improving outcomes, and heightening employee performance through high-performing hybrid teams of humans and robots (Ernst & Young Global Limited, 2019).
Therefore, digital accounting, automation, and AI-assisted accounting seem to be a game-changer for accounting and finance services, leading to further challenges for companies and employees. However, positive outcomes are expected, mainly in efficiency and effectiveness gains in the overall business operations.
Although accounting has continuously evolved with technological progress, developments in automation, AI, and blockchain have accelerated the digital transformation in accounting systems. Previous studies have addressed aspects such as automation and information systems, but they seem to lack an integrated understanding of the development of the research stream and emerging themes. Consequently, this study aims to address this issue by conducting a bibliometric analysis of the scientific literature on digital, automated, and AI-assisted accounting. Moreover, this research seeks to explore what is known and what work has been conducted in the research stream in the scientific literature, providing a further set of future research lines. To achieve this goal, bibliometric performance and science mapping methods are employed. Specifically, the most relevant authors, countries/territories, sources, affiliations, and cited documents are identified. An evaluation of the conceptual structure of the research field is also conducted.
The increasing adoption of automated procedures in the accountancy services industry presents an opportunity to add value for clients. However, despite being a popular topic among accounting professionals and companies, there is still limited scientific literature on this subject. This study aims to address this issue by providing further insights and guidance on the current state of accounting system digitalisation and automation.
2. Literature Review
2.1. The Concept of Digital Accounting
Organisations require accounting to address short-, medium-, and long-term problems in different areas, such as costs, cash flow, and expenditure. However, when it comes to long-term planning, accounting plays a crucial role in developing a strategic plan in the context of global and dynamic markets. In recent years, accounting has evolved in response to various scenarios in which investor confidence in capital markets has been severely shaken by accounting scandals (Adler & Chaston, 2002). The constant demands placed on this field of knowledge, particularly in times of crisis, have driven digitalisation forward. These digital advances have quickly impacted all aspects of personal and professional life (Parra-Sánchez & Talero-Sarmiento, 2024). The accounting environment has not escaped this rule either, as the digitalisation era has also been affected by the emergence of certain laws obliging business owners to keep all accounting records safe for a specific period. These regulations have led organisations to remodel their accounting methods for economic and financial reporting, integrating technology into their processes. Consequently, companies have been encouraged to invest more in technologies, such as the internet and digital interfaces, which can increase the productivity of their employees, particularly those in the accounting (Chulanov et al., 2022). The increased use of the internet in accounting is related to the greater demand for speed in accounting reporting. This has led companies to invest more in auditing software applications that can collect, organise, process, evaluate, and present financial data in a more appealing way (Curtis et al., 2009). Technological advances, particularly in accounting, have greatly improved accounting methods. Accounting and technology have always developed in parallel, and nowadays, the two fields are closely linked (Spilnyk et al., 2022). Banks have started using technology to transfer money in order to reduce costs, errors, and fraud. The results show that digital accounting enables today’s managers and students to understand the types of intervention needed to optimise spending on infrastructure and factories (Chen et al., 2024).
With the expansion of business, accounting and technology have become more integrated, and the emergence of global companies has led to the development of accounting software designed to meet their organisational needs (Azzari et al., 2020). Moreover, technological advances have impacted almost every aspect of accounting. For instance, the internet enables the exchange of accounting and financial information, while accounting and finance play a role in business control. To manage daily operations, such as accounting and project management, organisations rely on software systems like Enterprise Resource Planning (ERP). Over the years, ERP has been continuously updated and refined to keep pace with technological, economic, and customer-oriented developments (Genete & Tugui, 2008). Currently, software developers are working on solutions that aim to integrate and automate digital accounting functions, a long-term process that requires substantial financial investment. However, by updating ERP systems, developers aim to reduce tax evasion, eliminate human errors, standardise processes, and strengthen internal control (Chiu et al., 2019). To keep pace with the digitalisation of their working environment, accountants must review and adapt their working methods and client approaches, recognising that their skills and practices cannot remain static. They need to evolve in line with technological progress because developments once considered extraordinary, such as AI and advanced robotics, are now becoming a reality (Rindasu, 2017).
2.2. The Concept of Automated Accounting
Accounting is commonly defined as the process of recording, summarising, and analysing financial transactions to provide information useful for making business decisions. This definition is widely accepted and reflects the main objective of financial reporting, which is to provide relevant information to stakeholders for decision-making (Financial Accounting Standards Board, 2016; International Accounting Standards Board, 2018). Automated accounting, on the other hand, implies the use of software and technological tools to perform traditional manual accounting tasks, reducing manual intervention. It involves an automation process with several layers, including functions such as data entry, transaction recording, reconciliations, and complex processes, like financial reporting and auditing. Automated software in accounting enables the input, processing, and output of data to streamline repetitive, routine tasks, resulting in efficiency and effectiveness improvements (Cooper et al., 2019). Technological development has enabled the automation of accounting systems by integrating software robots and AI into existing systems, improving efficiency and reliability through enhanced interaction between firm departments and remote automated monitoring (Gnatiuk et al., 2023). It further freed accounting and management staff from routine work so that they can focus on creative processes (Slavinskaitė, 2022), saving time and labour resources while ensuring accurate financial information (Gahramanov, 2022).
Automated accounting reduces time and organisational costs (Resler, 2013) since the use of RPA and AI helps with repetitive tasks, significantly enhancing the efficiency and accuracy of accounting operations. However, it also implies costs that must be considered, namely, technical, professional, and managerial factors necessary for successful implementation (Cooper et al., 2019; Gnatiuk et al., 2023; Ponomareva & Matiushko, 2021). Moreover, it facilitates data management and more accurate reporting, providing better control over accounting operations, correcting errors, ensuring compliance, and enhancing trust in the reliability of financial data. This, in turn, allows for optimising and improving work processes, enabling timely management decisions within companies (Chipriyanova & Krasteva-Hristova, 2023; Łada & Martinek-Jaguszewska, 2023).
2.3. Bibliometric Analysis in Accounting
Bibliometric analyses applied to the field of accounting have revealed relevant indicators of the quality and evolution of publications in reference journals (Araújo et al., 2014; Chiu et al., 2019; Chung et al., 1992; Mohanty, 2019; Moya & Prior, 2008). In this context, it is important to examine the various types of research to assess why bibliometric studies within specific subfields of accounting remain relatively limited. Bibliometric research in this area began in 1992 (Chung et al., 1992), with exponential growth in 2019 and 2020, which recorded the highest number of publications. The last article published in 2021 addressed the topic of accounting and the management of natural resource consumption. It employed a bibliometric approach to conduct a systematic review of studies on accounting and management of natural resource consumption using the input–output method. The results indicate that significant contributions have been made to the development of this research field, both in terms of quantity and quality of academic output.
Bibliometric analyses in accounting have been categorised into themes such as management accounting (Balstad & Berg, 2020; Beuren et al., 2015; Hülle et al., 2011; Olusanmi et al., 2021), auditing (Handoko & Mardian, 2021; Ismayilov, 2020), information technology and emerging technologies in accounting (S. Kumar et al., 2020), tax accounting (Henrique et al., 2021), business (Cortés-Sánchez, 2020), key account management (P. Kumar et al., 2019), international accounting (da Silva & Niyama, 2019), accountability (Faria Duarte & Zouain, 2019), teaching and the profession (da Costa & Nogueira, 2016; Nolli et al., 2020), accounting information systems (Chiu et al., 2019), accounting and costs in agribusiness (Guimarães et al., 2019; Mohanty, 2019; Moraes et al., 2016), lobbying activity in accounting regulation (Azevedo, 2018), regulatory changes (Garcia et al., 2016), and environmental accounting (Dos Santos Teixeira & De Souza Ribeiro, 2014; Schaltegger et al., 2013; Yamaguchi et al., 2015) (Table 1).
Table 1.
Bibliometric prior studies in accounting.
3. Methodology
This study used a bibliometric approach to examine the development of the scientific literature on digital, automated, and AI-assisted accounting. This approach was chosen to ensure methodological rigour, transparency, and replicability. It enabled the analysis of a large number of publications in a structured way, facilitating the identification of interconnections within and across research streams (Zupic & Čater, 2015). Furthermore, it assisted in tracing the evolution of the field and pinpointing emerging areas of research (Donthu et al., 2021).
This study adheres to the guidelines set out by (Cobo et al., 2011; Marzi et al., 2025; Zupic & Čater, 2015) and is consistent with previous studies from various research areas.
Data for the analysis were retrieved from Web of Science (WoS) and Scopus on 5 January 2025. These databases were selected based on their recognised data reliability (Mongeon & Paul-Hus, 2016), suitability for bibliometric analysis, and frequent use in previous studies (Azzari et al., 2020; Handoyo, 2024; Merigo & Yang, 2017; Merigó & Yang, 2017; Poje & Zaman Groff, 2022). The search focused on documents classified as “article”, written in English, and addressing topics such as digital accounting, automated accounting, and artificial intelligence within the scope of accounting systems. Table 2 presents the search criteria.
Table 2.
Search criteria.
A total of 362 documents were retrieved from the WoS (252) and Scopus (110) databases. These documents were screened to assess their relevance to this study’s objectives. Titles, keywords, and abstracts were manually reviewed to ensure alignment with the inclusion criteria. During this process, 82 duplicate records and 72 unrelated documents were identified and excluded from the analysis. The final set of documents included in the analysis comprised 208 records.
The data were analysed using R Statistical Software v 4.4.3 (R Core Team, 2025) with the support of the Bibliometrix package (Aria & Cuccurullo, 2017). The bibliometric analysis involved a performance evaluation (Cobo et al., 2011; van Raan, 2005; White & McCain, 1998) and a science mapping (Cobo et al., 2011; Noyons et al., 1999; Zupic & Čater, 2015) to explore the structure and evolution of the research field.
4. Results
Following the methodological approach, the data were computed, and the main information about the publishing output was extracted, as shown in Table 3.
Table 3.
Main information about the data.
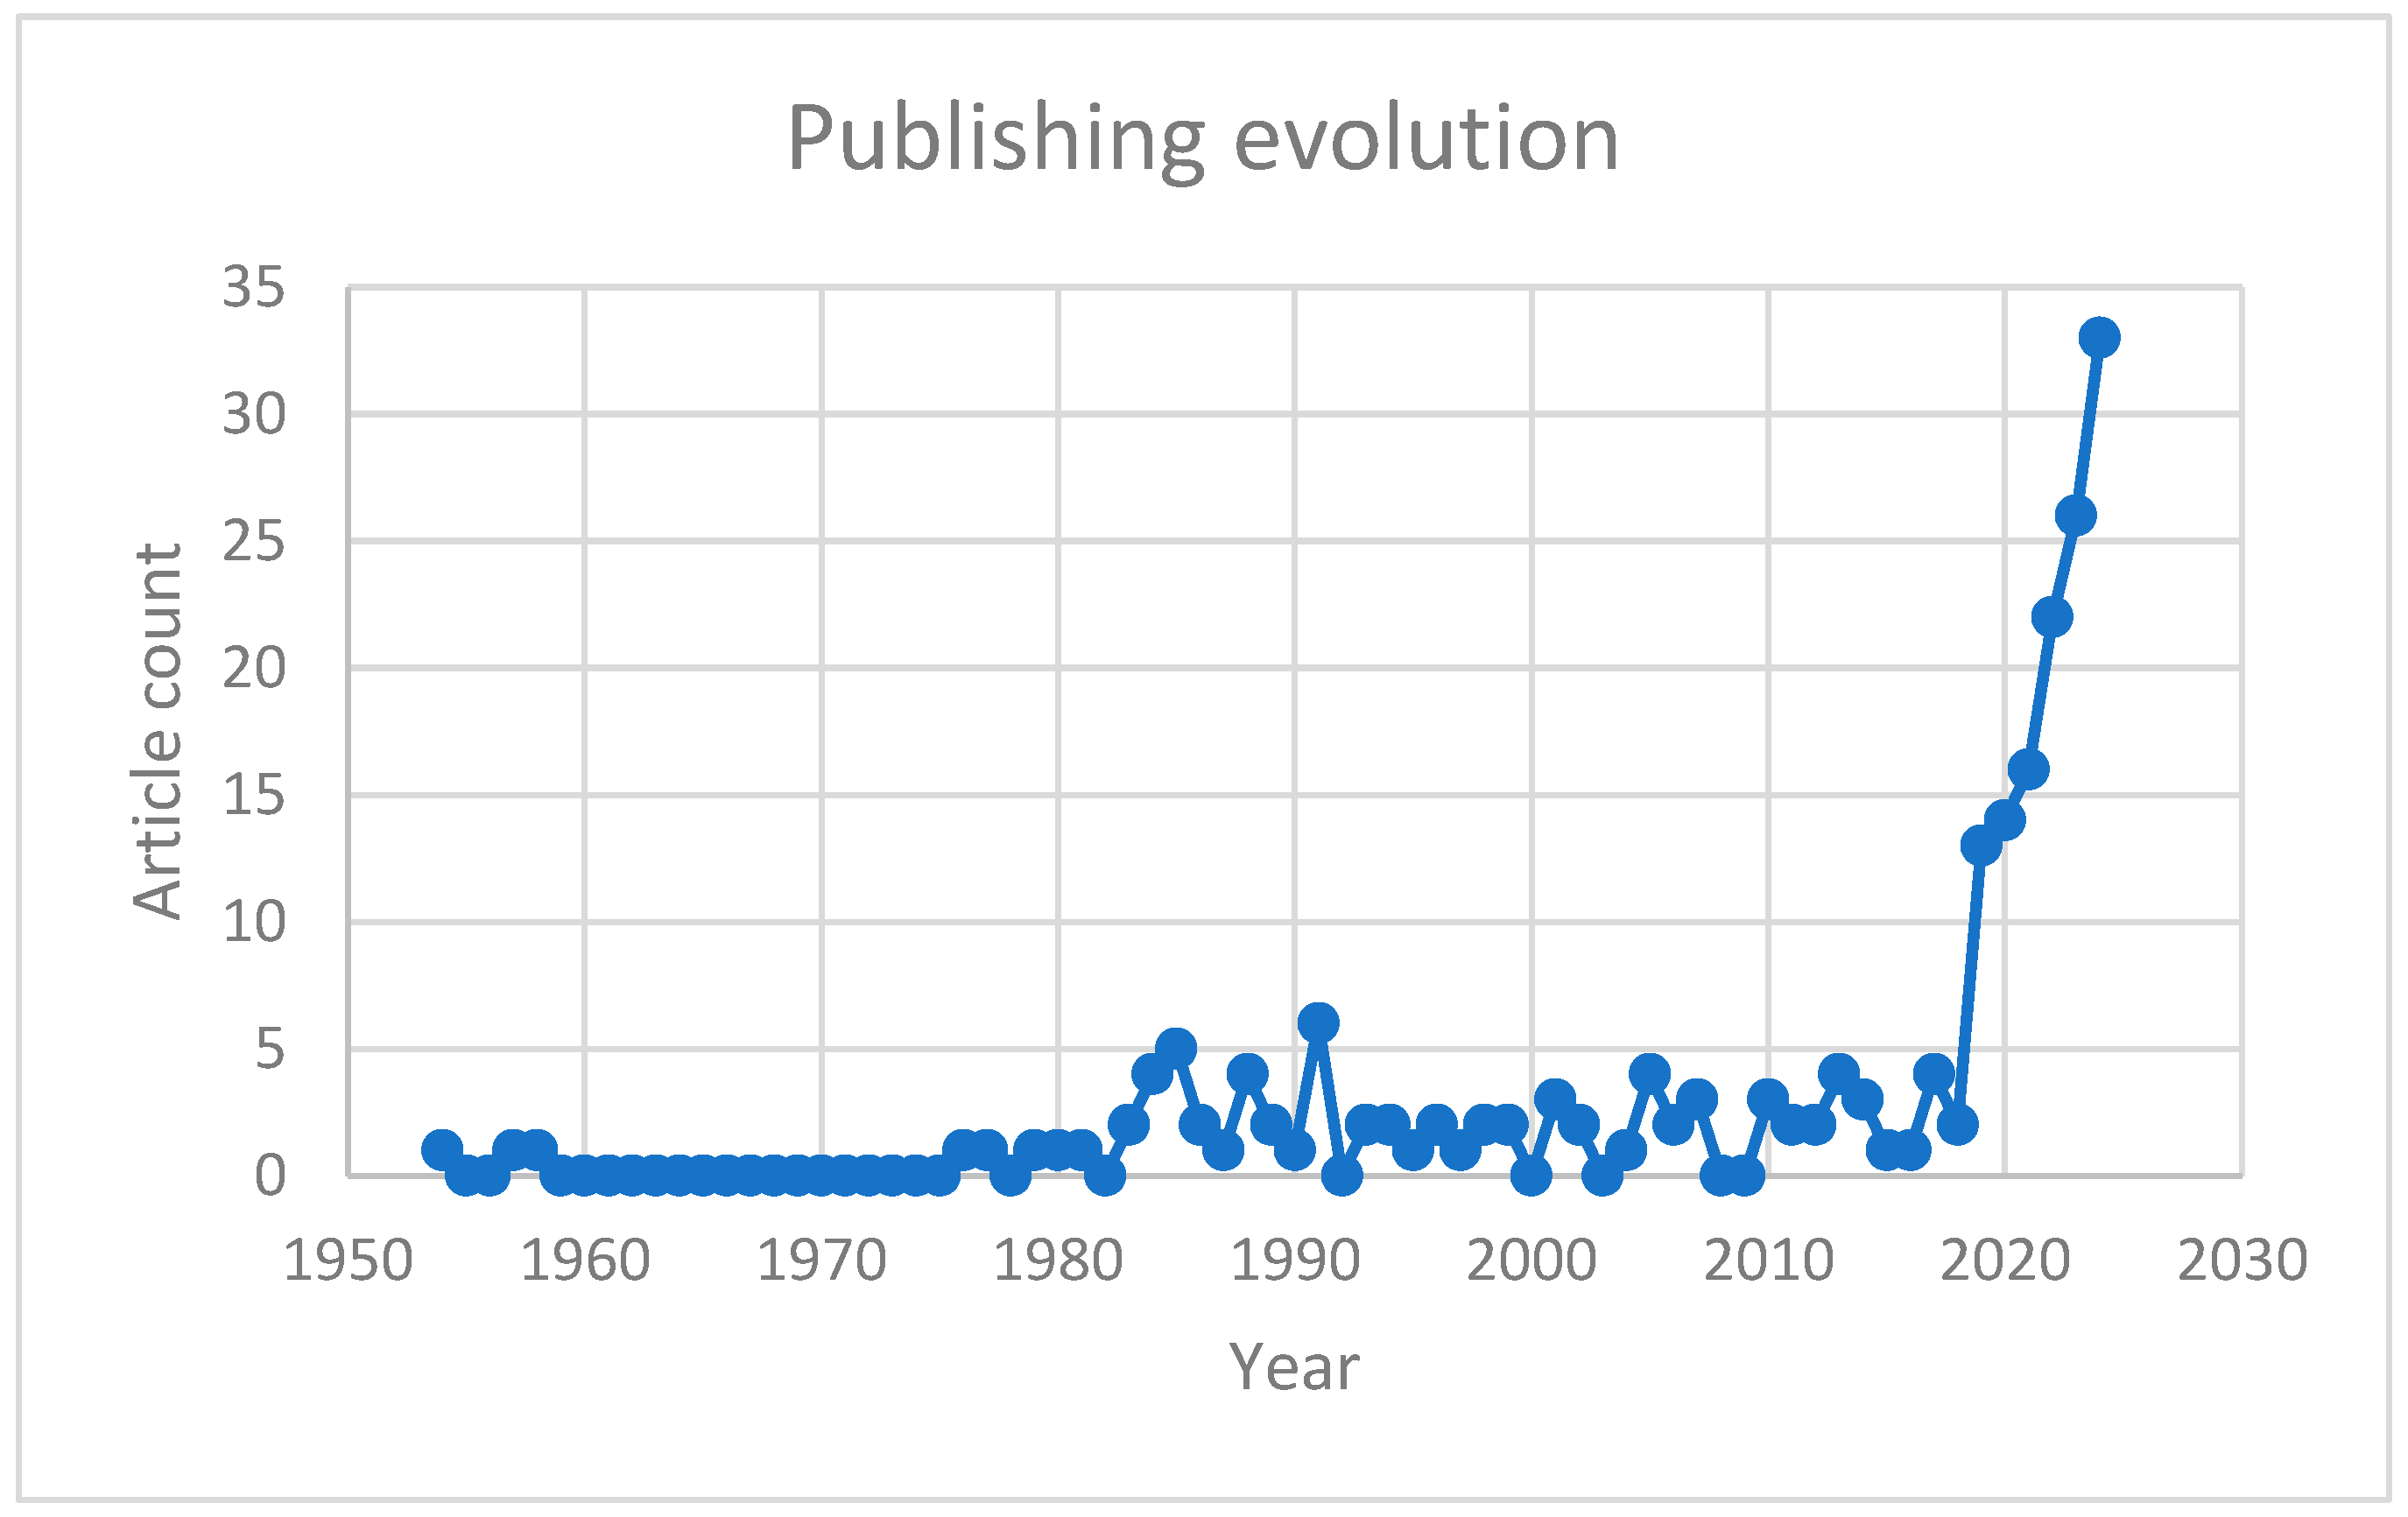
The results show that 208 documents were published, with the earliest dating back to the 1950s. This indicates that the initial developments in digital and automated accounting emerged during that period. Furthermore, Figure 1 illustrates the significant increase in the number of articles published from around 2018.
Figure 1.
Annual scientific production.
Figure 1 shows the annual evolution of publications in this field, demonstrating a clear trend of increasing attention from scholars towards digital, automated, and AI-assisted accounting systems since 2018.
The initial contributions in the 1950s were followed by a period of stagnation that ended in the 1980s. The early decades, particularly between 1950 and 1980, saw sporadic publication activity, suggesting that the field’s foundational concepts and technologies were still in their beginning stages. From the 1980s onwards, the number of articles increased slightly but remained relatively stable, with minor peaks. This growth is tied to the advent of personal computing and the digital transformation of accounting practices. The post-2010 period reflects the rapid development and adoption of advanced technologies such as cloud computing, robotic process automation, and AI in accounting systems. Finally, the period 2019 to 2024 saw a rise in output, increasing from 13 articles in 2019 to 33 articles in 2024. This increase aligns with the heightened interest in AI applications and digital transformation, which was accelerated by the COVID-19 pandemic. The observed trend highlights a movement towards the adoption of automated and AI-driven accounting systems.
Table 4 shows the most relevant sources of articles published on digital, automated, and AI-assisted accounting systems.
Table 4.
Leading sources.
Regarding the most relevant sources (Table 4), the dataset shows the multidisciplinary and applied nature of the research field. The set of the most relevant journals that publish articles on digital, automated, and AI-assisted accounting systems covers areas such as finance, computational sciences, and management.
Table 5 presents the most relevant authors who conducted research on digital, automated, and AI-assisted accounting systems, according to the number of documents published.
Table 5.
Leading authors.
Concerning the leading authors, the results show that Manaf Al-Okaily leads with four documents (2.5 fractionalised), indicating a relevant contribution to the field, both in terms of volume and involvement in multi-authored works. Borkovska V. (four articles, 0.73 fractionalised) and Shevtsiv L. (three articles, 0.50 fractionalised) show a mix of primary and secondary authorship roles and reflect diverse collaboration dynamics. Fractionalised counts reveal varying levels of contribution per article. For example, Alsharari N. (1.00) appears to have contributed more substantially to fewer multi-authored papers, while Borskovska V. and Shevtsiv L. (0.73 and 0.5, respectively) likely participated in larger collaborative efforts.
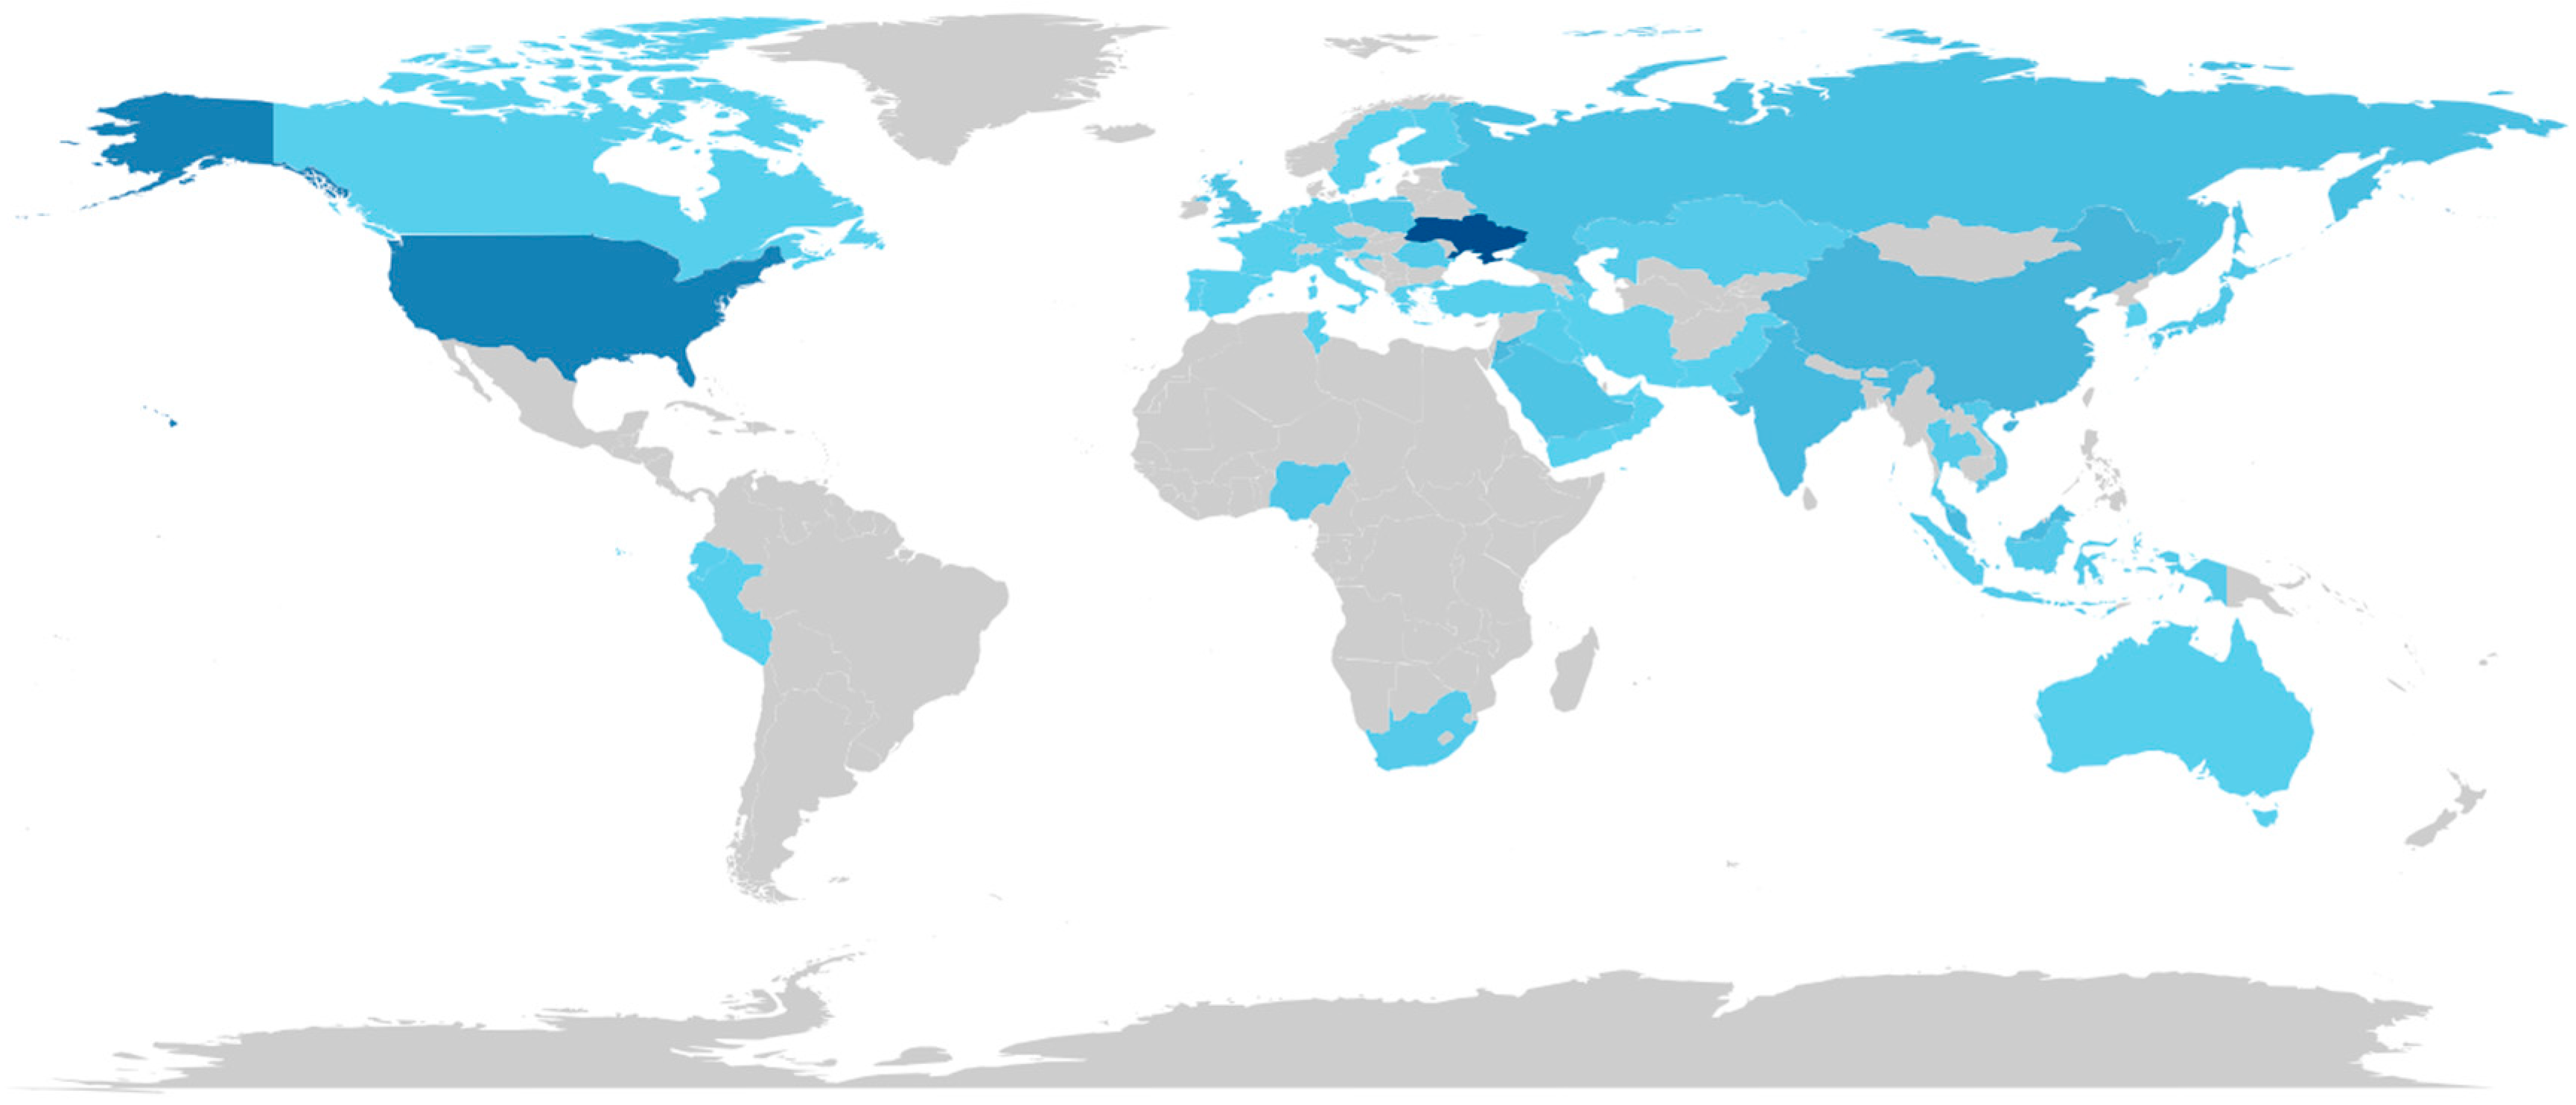
Concerning scientific production by countries/territories, Figure 2 shows the most prolific countries/territories in dark blue and the least prolific in light blue. Countries/territories marked in grey do not have articles in the dataset.
Figure 2.
Scientific production by country/territory.
The geographical distribution of scientific production in the field of digital, automated, and AI-assisted accounting systems identifies Ukraine as the leading contributor. This countries/territories produced 64 documents, followed by the United States (37 documents) and China (13). The regional patterns reveal a concentration of research in certain countries/territories across Asia, Europe, and North America. Conversely, regions such as Africa and parts of South America are mostly absent from the publication output. Table 6 presents the top ten most prolific contributors.
Table 6.
Publishing distribution by countries/territories.
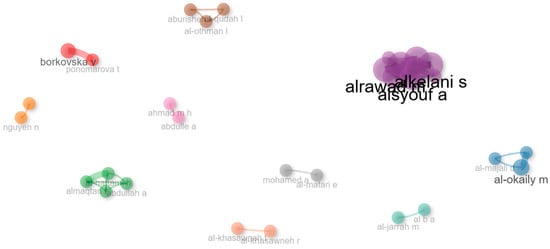
The collaboration network represents the relationships and interactions among authors based on their collaboration efforts. It consists of nodes, or vertices, which represent individual authors, and edges, or links, representing collaborations, partnerships or cooperative interactions among authors. Figure 3 illustrates the collaboration among authors who published articles on digital, automated, and AI-assisted accounting systems.
Figure 3.
Collaboration network.
Figure 3 shows that the research field of digital, automated, and AI-assisted accounting systems is relatively decentralised, with multiple relevant authors leading independent research streams, which usually suggests diverse approaches and findings, but also limits synergies arising from cross-group collaborations. This aspect is also in line with the broader scientific trend in leading academic journals. One relevant cluster was identified in the results: a cluster centred around Alkelani S., Alrawad M., and Alsyouf A. Additionally, nine smaller clusters were identified as more tightly connected collaborative groups.
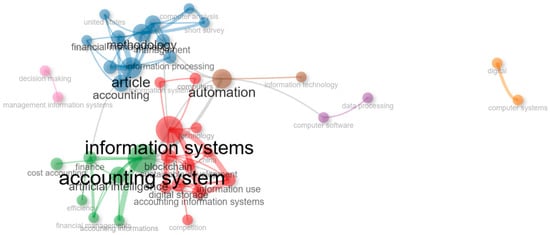
The co-occurrence network is presented in Figure 4, which depicts a graph-based representation of relationships between terms that appear together in a specific context. This type of graph is generally used to visualise patterns of word co-occurrences, highlighting potential relationships, associations, or underlying clusters.
Figure 4.
Co-occurrence network.
The co-occurrence network (Figure 4) shows three main nodes. The green cluster (cluster 1) is centred on accounting system, finance, artificial intelligence, and efficiency. Accounting system is the central node of this cluster, followed by the term artificial intelligence. Overall, these themes seem to be focused on financial processes and efficiency, with artificial intelligence playing a growing role.
Cluster 2 (red) centres on information systems and technology integration, presenting key nodes such as information systems, blockchain, digital storage, sustainable development, and accounting information systems. Information systems play a central role in the cluster, with blockchain and digital storage also showing high centrality. The relatively low centrality of blockchain and technology suggests that they are less directly connected to other terms, despite their relevance to the research stream. The set of terms within the cluster indicates a focus on the integration of technologies such as blockchain and sustainable development practices.
Cluster 3 (blue) includes key nodes such as methodology, article, organisation and management, and management, which serve as the main connectors within the cluster. The overall terms within this cluster reflect the academic discourse around research methodologies.
The four remaining clusters are cluster 4 (purple), including computer software and data processing, cluster 5 (orange), containing digital and computer systems, cluster 6 (brown), which involves automation and represents a highly influential node, reflecting its role in transforming accounting systems and exploring the potential of automation in the accounting domain, and cluster 7 (pink), which encompasses decision-making and management information systems.
Concerning the centrality analysis, automation and information systems are the dominant nodes, appearing to be relevant in modernising accounting systems. On the other hand, emerging technologies like blockchain and digital storage act as enablers of secure and efficient systems.
Concerning the trend topics, Table 7 presents the temporal evolution and frequency of key research terms related to digital, automated, AI-assisted accounting systems.
Table 7.
Trend topics.
The trend term results show established and mature research topics before 2000, with background concepts and emerging areas in the academic literature. These include methodology (year start (YS) = 1984), accounting (YS = 1986), financial management (YS = 1986), organisation and management (YS = 1985), and human (YS = 1985). These terms present a long-standing presence in the literature, with their median years concentrated in the 1990s. However, the moderate frequency after the 2000s suggests that they represent background concepts in accounting research. Information systems (YS = 1989) shows high frequency, and its presence through the years demonstrates sustained relevance, which is most likely linked to technological advancements. Cost accounting (YS = 1991) and decision-making (YS = 1986) gained momentum in the early 2000s, but the results show signs of reduced focus in recent years.
The period 2000–2010 shows transitional topics, including automation (YS = 1997) (frequency (F) = 10), which peaked between 2005 and 2007 and may indicate the technological integration of accounting practices. The recent lower frequency, however, suggests that automation may now be embedded within broader technological frameworks such as artificial intelligence (YS = 2021; F = 12), information systems (F = 10), and accounting systems (YS = 2009; F = 16). Accounting systems (YS = 2009) presents the highest frequency (F = 16), with a median year of 2018 and Q3 in 2023, which may indicate that research highlights the modernisation of accounting systems driven by digitalisation and automation trends.
A set of topics is emerging and rapidly growing, including artificial intelligence (YS = 2021), with high frequency (F = 12) and recent concentration of interest (median and Q3 in 2022), and sustainable development (YS = 2014), which is less frequent (5) but presents a recent focus (Q3: 2022), suggesting growing interest in integrating sustainability into accounting, perhaps trough Environmental, Social, and Governance (ESG) reporting. Moreover, digital storage (YS = 2021), blockchain (YS = 2022), finance (YS = 2021), and accounting information (YS = 2022) are very recent topics, centred around the period 2023–2024. Overall, terms such as blockchain, digital storage, and finance may indicate that the research field is moving towards secure, efficient data handling and financial technologies. On the other hand, topics such as artificial intelligence and accounting systems integration signal the evolution towards fully automated, intelligent accounting solutions. Furthermore, the overlap between automation, decision-making, and artificial intelligence suggests a relationship between operational efficiency and strategic decision-making through technological integration. The emergence of environmental accounting-related topics seems to indicate that accounting systems more frequently address environmental accountability and sustainability reporting.
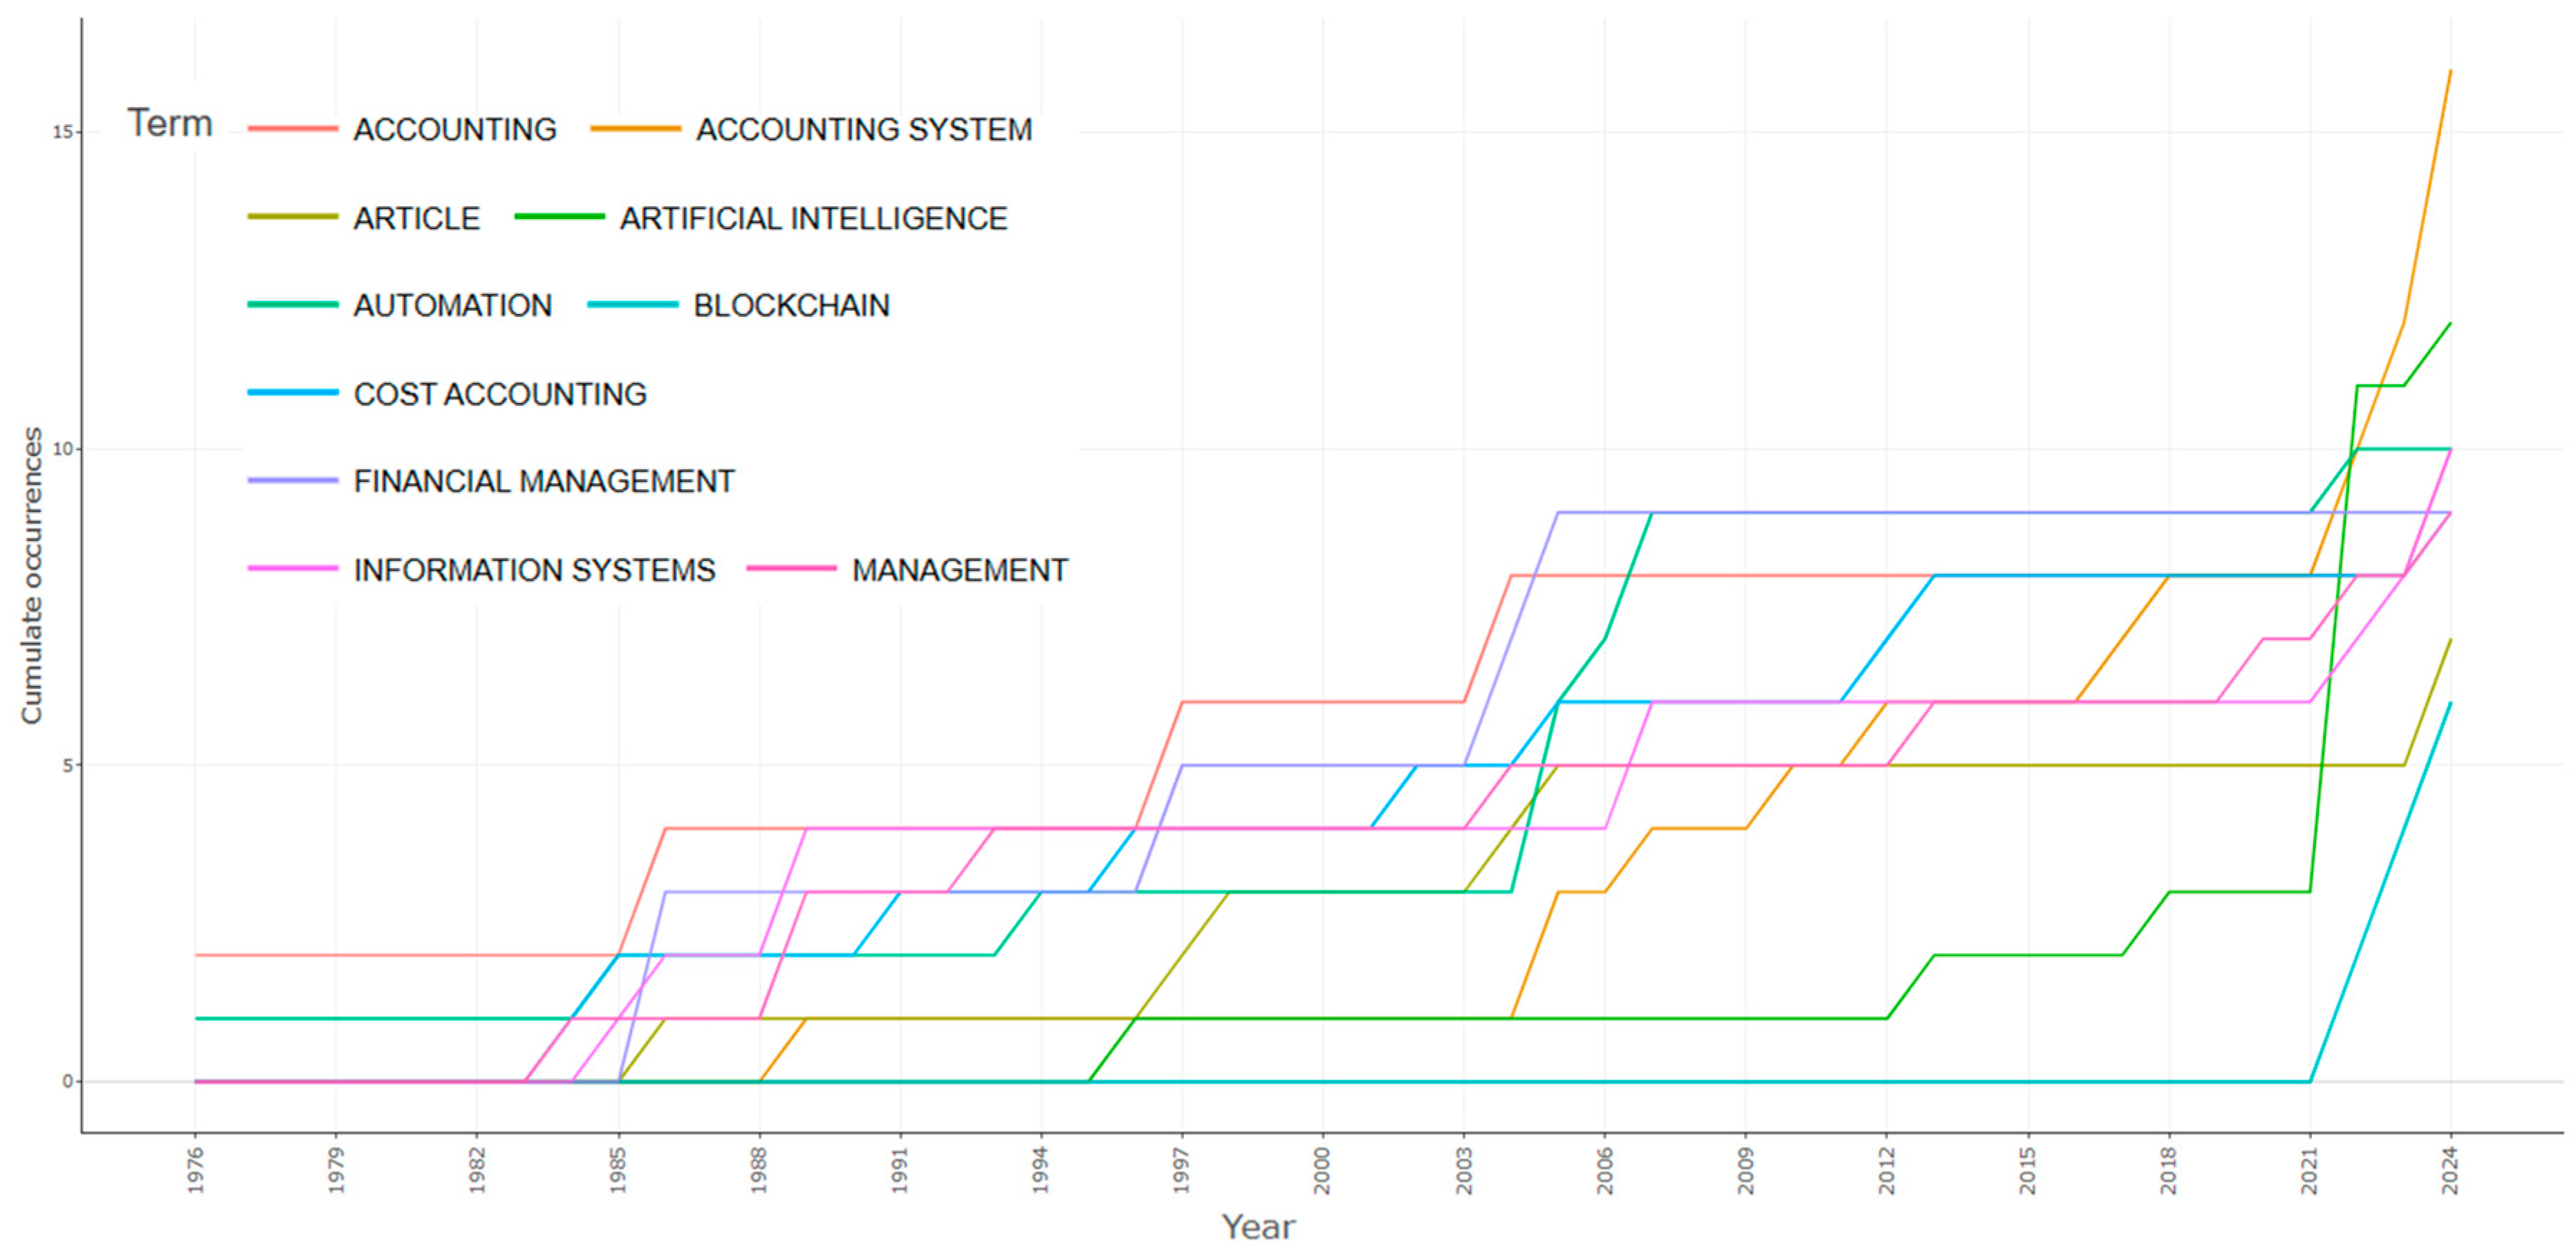
The word frequency analysis (Figure 5) enables an in-depth analysis of the topic evolution over time.
Figure 5.
Word frequency over time.
The word frequency graph (Figure 5) illustrates the evolving focus of scientific production, showing a rise in terms such as artificial intelligence and blockchain in recent years, which reflects a growing interest in these technologies within the digital accounting context. Automation also emerges as a prominent term, highlighting a possible role as a bridge between traditional accounting systems and advanced digital platforms. Terms such as accounting systems and information systems demonstrate relatively stable trends, stressing their key role in the field. Moreover, the recent emergence of blockchain and artificial intelligence suggests a possible shift from procedural automation to more sophisticated, technology-driven approaches. On the other hand, the term financial management shows a stable trend, demonstrating its interrelation with digital systems and emphasising strategic decision-making and operational efficiency enabled by technological advancements in accounting systems.
Concerning the most cited documents, Table 8 presents the 50 most cited documents and shows the total number of citations for each article.
Table 8.
Most cited documents.
The analysis of the most cited documents on digital, automated, and AI-assisted accounting systems shows that recent years have seen a considerable increase in the number of published papers, as confirmed by the production output over time. These papers emphasise the relevance of the research stream, where 37 documents in the top 50 most cited were published since 2019.
To evaluate the main subjects addressed in the literature, Table 9 presents the top 50 most cited documents and identifies the main subject of each.
Table 9.
Most cited documents and subjects.
The analysis of the top 50 most cited documents shows a set of main underlying subjects that form the basis of the research stream. A more concise approach is presented in Table 10, which aggregates the top 50 most cited documents based on their main underlying topics.
Table 10.
Main underlying themes.
5. Discussion and Conclusions
5.1. Discussion
The analysis of the scientific literature on digital accounting, automation, and AI integration in accounting systems provides an overview of the research output and landscape within the research stream. This research draws on 208 documents published between 1954 and 2024 and reveals a growing academic interest, showing an exponential increase in published documents in the last few years, especially since 2018.
The results show that research on digital and automated accounting emerged in the 1950s and remained relatively stagnant until the 1980s. This aspect aligns with the early adoption of computer systems in accounting and suggests that the growth in academic interest began with the arrival of digital transformation. A similar trend can be observed with the increase in publication output from 2018 onwards, which seems to reflect the rapid integration of AI, robotic process automation, and blockchain in accounting practices. Both trends, the early emergence in the 1980s as well as the recent increase, are aligned with the previous literature addressing this issue, emphasising the role of automation in efficiency and effectiveness gains (Cooper et al., 2019) through the integration of software robots and AI into existing systems, linking departments and remote automated monitoring (Gnatiuk et al., 2023) and enabling accounting and management staff to be released from routine work so they can focus on creative processes (Slavinskaitė, 2022), thereby saving time and labour resources while ensuring accurate financial information (Gahramanov, 2022). Furthermore, the process of automation and integration of AI into accounting systems also addresses a major goal of companies to increase efficiency and provide timely and useful information through more accurate reporting, improved control of accounting operations, error avoidance, compliance, and trust in the reliability of financial data, allowing optimisation, improving working processes, and making timely management decisions within companies (Chipriyanova & Krasteva-Hristova, 2023; Łada & Martinek-Jaguszewska, 2023).
Regarding the geographical distribution of publications, the results show that the research activity is concentrated in specific regions of Asia, Europe, and North America. Contributions from Africa and South America remain relatively low. On the other hand, collaboration networks remain somewhat fragmented, with multiple independent research clusters. Despite some authors establishing strong collaboration networks, the lack of cross-group cooperation may limit knowledge integration.
The co-occurrence network highlights several dominant themes in the literature. The most relevant are (1) accounting systems, finance, AI, and efficiency, suggesting a strong focus on the adoption of AI for financial decision-making and operational improvements; (2) information systems, blockchain, and digital storage, indicating an interest in technological integration for secure and efficient data management; and (3) automation, decision-making, and management information systems, which may reflect the increasing role of AI and automation in strategic financial processes. The most cited documents reinforce these thematic areas. Studies on digital accounting systems and information quality (Al-Okaily, 2024; Lutfi et al., 2022a) emphasise the role of AI and automation in improving financial reporting accuracy. On the other hand, research on blockchain in accounting (ALSaqa et al., 2019; Bonyuet, 2020) highlights its potential for enhancing transparency and security. Moreover, artificial intelligence applications in accounting (Ionescu, 2021; Lehner et al., 2022) represent an emerging and important research topic, with studies exploring AI-driven auditing, fraud detection, and decision support systems.
Regarding emerging trends and future directions, the results indicate that trending topics are shifting from fundamental accounting concepts to emerging technologies. Early research addressed mostly financial management, cost accounting, and decision-making, while recent studies increasingly explore AI, blockchain, and digital storage. This process suggests that the research field is evolving from basic automation to AI-driven decision-making systems. Consequently, the results suggest that future research will be driven by (1) AI and machine learning in accounting, investigating how AI-driven models can enhance predictive analytics, fraud detection, and financial forecasting; (2) blockchain and secure accounting systems, addressing how distributed ledger technologies can improve auditability, compliance, and transparency in financial transactions; (3) sustainability and green accounting, assessing how digital accounting systems can integrate environmental, social, and governance (ESG) reporting for sustainable business practices; and (4) interdisciplinary approaches, encouraging collaboration between accounting, computer science, and business management to develop more robust, resilient, and intelligent financial systems.
5.2. Conclusions
The findings of this study suggest that automation in accounting presents both opportunities and challenges. While AI and digitalisation enhance efficiency, accuracy, and compliance, they also raise concerns regarding job displacement, cybersecurity risks, and ethical considerations in financial decision-making. Despite these concerns, previous research has emphasised the role of automation in improving work quality and accuracy, thereby saving accountants’ time (Fernández & Aman, 2018) while also enhancing outcomes and employee productivity through high-performing hybrid teams of humans and robots (Ernst & Young Global Limited, 2019). However, despite the opportunities arising from this transformation process, policymakers and industry leaders must address these challenges by implementing frameworks that support technological adoption while ensuring its responsible use. On the other hand, from a theoretical perspective, the obtained results highlight a relevant research stream, representing a transformative topic within accounting, accounting systems, information management, and decision-making. In conclusion, digital and automated accounting represent significant progress for the financial sector, promoting greater efficiency, transparency, and reliability in accounting information. However, for this transition to be successful, it is essential for organisations to invest in training their professionals and implementing secure and efficient systems. The future of accounting is closely connected to technological evolution, and companies that can adapt to this new context are likely to gain competitive advantages in the global market.
The observed trends in automation and AI adoption in accounting systems align with the Technology Acceptance Model. Nevertheless, this alignment requires a systematic assessment of how perceived usefulness and perceived ease of use influence accounting professionals’ intention to adopt and use new technologies (Lee et al., 2003). Therefore, perceived usefulness and ease of use should continue to drive technology acceptance among accounting professionals.
The results of this study establish several important future research directions for accounting research. Despite the clarity and relevance of the results, there are some limitations to note. First, despite the wide use of bibliometric analysis to track the evolution of academic output in multiple scientific fields, bibliometric analysis uses a quantitative approach that risks overrepresenting some topics while underrepresenting others. The search procedures, especially the search query, can influence these risks. The authors implemented solutions to avoid this issue, namely, by analysing all the documents in the dataset and removing those that did not address the research topics. The detailed analysis of the top 50 most cited papers, identifying relevant themes intersecting with the trend topics, further enhanced confidence in the obtained results. Furthermore, although the number of documents in the dataset could be larger, it was above the minimum threshold suggested in the literature (Rogers et al., 2020). A different approach could also be adopted, such as conducting a systematic literature review. However, the obtained results and insights provide confidence in the timeliness and significance of this study.
Author Contributions
Conceptualisation, C.S. and R.S.; methodology, C.S. and R.S.; software, C.S. and R.S.; validation, C.S. and R.S.; formal analysis, C.S. and R.S.; investigation, C.S. and R.S.; resources, C.S. and R.S.; data curation, C.S. and R.S.; writing—original draft preparation, C.S. and R.S.; writing—review and editing, C.S. and R.S.; visualisation, C.S. and R.S.; supervision, C.S. and R.S.; project administration, C.S. and R.S.; funding acquisition, C.S. All authors have read and agreed to the published version of the manuscript.
Funding
This research was funded by Fundação para a Ciência e Tecnologia: NECE and by FCT (Fundação para a Ciência e Tecnologia), I.P., project reference UIDB/04630/2020 and DOI identifier 10.54499/UIDP/04630/2020.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The original data presented in this study are openly available in Web of Science and Scopus databases, according to the procedure presented in Section 3 Methodology of this document.
Acknowledgments
During the preparation of this manuscript/study, the author(s) used Mendeley Desktop software, version 1.19.8, to organise and insert references. The authors have reviewed and edited the output and take full responsibility for the content of this publication.
Conflicts of Interest
The authors declare no conflicts of interest.
References
- Adler, R. W., & Chaston, K. (2002). Stakeholders’ perceptions of organizational decline. Accounting Forum, 26(1), 31–44. [Google Scholar] [CrossRef] [Scilit]
- Al-Fatlawi, Q. A., Al Farttoosi, D. S., & Almagtome, A. H. (2021). Accounting information security and IT governance under COBIT 5 framework: A case study. Webology, 18(2), 294–310. [Google Scholar] [CrossRef] [Scilit]
- Al-Hattami, H. M., & Almaqtari, F. A. (2023). What determines digital accounting systems’ continuance intention? An empirical investigation in SMEs. Humanities and Social Sciences Communications, 10(1), 814. [Google Scholar] [CrossRef] [Scilit]
- Al-Hattami, H. M., Almaqtari, F. A., Abdullah, A. A. H., & Al-Adwan, A. S. (2024). Digital accounting system and its effect on corporate governance: An empirical investigation. Strategic Change, 33(3), 151–167. [Google Scholar] [CrossRef] [Scilit]
- Alkhatib, E., Ojala, H., & Collis, J. (2019). Determinants of the voluntary adoption of digital reporting by small private companies to Companies House: Evidence from the UK. International Journal of Accounting Information Systems, 34, 100421. [Google Scholar] [CrossRef] [Scilit]
- Al-Okaily, M. (2024). Assessing the effectiveness of accounting information systems in the era of COVID-19 pandemic. VINE Journal of Information and Knowledge Management Systems, 54(1), 157–175. [Google Scholar] [CrossRef] [Scilit]
- Al-Okaily, M., Alghazzawi, R., Alkhwaldi, A. F., & Al-Okaily, A. (2023a). The effect of digital accounting systems on the decision-making quality in the banking industry sector: A mediated-moderated model. Global Knowledge, Memory and Communication, 72(8–9), 882–901. [Google Scholar] [CrossRef] [Scilit]
- Al-Okaily, M., Al-Majali, D., Al-Okaily, A., & Majali, T. (2023b). Blockchain technology and its applications in digital accounting systems: Insights from Jordanian context. Journal of Financial Reporting and Accounting. ahead-of-print. [Google Scholar] [CrossRef] [Scilit]
- ALSaqa, Z. H., Hussein, A. I., & Mahmood, S. M. (2019). The impact of blockchain on accounting information systems. Journal of Information Technology Management, 11(3), 62–80. [Google Scholar] [CrossRef] [Scilit]
- Alsharari, N. M., & El-Aziz Youssef, M. A. (2017). Management accounting change and the implementation of gfmis: A Jordanian case study. Asian Review of Accounting, 25(2), 242–261. [Google Scholar] [CrossRef] [Scilit]
- Araújo, R. M., de Azevedo, A. K., Vieira, L. L., & Nascimento, T. C. (2014). Periódicos em ação: Um estudo exploratório-bibliométrico na área de administração, ciências contábeis e turismo. Perspectivas Em Ciencia Da Informacao, 19(1), 90–114. [Google Scholar] [CrossRef] [Scilit]
- Ardianto, A., & Anridho, N. (2018). Bibliometric analysis of digital accounting research. International Journal of Digital Accounting Research, 18, 141–159. [Google Scholar] [CrossRef] [Scilit]
- Aria, M., & Cuccurullo, C. (2017). Bibliometrix: An R-tool for comprehensive science mapping analysis. Journal of Informetrics, 11(4), 959–975. [Google Scholar] [CrossRef] [Scilit]
- Association of Chartered Certified Accountants. (2013). Digital darwinism: Thriving in the face of technology change. Available online: http://www.accaglobal.com/content/dam/acca/global/PDF-technical/futures/pol-afa-tt2.pdf (accessed on 17 May 2025).
- Azevedo, E. P. R. d. S. (2018). Lobbying in accounting regulation: A bibliometric study in major international journals from 2002 to 2015. Revista Evidenciação Contábil & Finanças, 6(1), 62–82. [Google Scholar] [CrossRef] [Scilit]
- Azman, N. A., Mohamed, A., & Jamil, A. M. (2021). Artificial intelligence in automated bookkeeping: A value-added function for small and medium enterprises. International Journal on Informatics Visualization, 5(3), 224–230. [Google Scholar] [CrossRef] [Scilit]
- Azzari, V., Mainardes, E. W., & da Costa, F. M. (2020). Accounting services quality: A systematic literature review and bibliometric analysis. Asian Journal of Accounting Research, 6(1), 80–94. [Google Scholar] [CrossRef] [Scilit]
- Balstad, M. T., & Berg, T. (2020). A long-term bibliometric analysis of journals influencing management accounting and control research. Journal of Management Control, 30(4), 357–380. [Google Scholar] [CrossRef] [Scilit]
- Berlinski, E., & Morales, J. (2024). Digital technologies and accounting quantification: The emergence of two divergent knowledge templates. Critical Perspectives on Accounting, 98, 102697. [Google Scholar] [CrossRef] [Scilit]
- Beuren, I. M., Machado, D. G., & Dal Vesco, D. G. (2015). Sociometric and bibliometric analysis of research published in management accounting research. Contabilidade Gestao e Governanca, 18(1), 83–105. [Google Scholar]
- Bonyuet, D. (2020). Overview and impact of blockchain on auditing. International Journal of Digital Accounting Research, 20, 31–43. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Carlson, A. E. (1957). Automation in accounting systems. The Accounting Review, 32(2), 224–228. [Google Scholar]
- Chen, H., Ai, S., Xiong, X., & Feng, D. (2024). Big data analytics and corporate financing constraints: Evidence from a developing country. Managerial and Decision Economics, 46, 2224–2236. [Google Scholar] [CrossRef] [Scilit]
- Cheng, T. T., Lock, E. D., & Prywes, N. S. (1984). Use of very high level languages and program generation by management professionals. IEEE Transactions on Software Engineering, SE-10(5), 552–563. [Google Scholar] [CrossRef] [Scilit]
- Chiarini, A. (2012). Lean production: Mistakes and limitations of accounting systems inside the SME sector. Journal of Manufacturing Technology Management, 23(5), 681–700. [Google Scholar] [CrossRef] [Scilit]
- Chipriyanova, G., & Krasteva-Hristova, R. (2023, June 15–18). Technological aspects of accounting automation system as a decision support system. 14th International Scientific and Practical Conference (Vol. 2, pp. 28–33), Rezekne, Latvia. [Google Scholar]
- Chiu, V., Liu, Q., Muehlmann, B., & Baldwin, A. A. (2019). A bibliometric analysis of accounting information systems journals and their emerging technologies contributions. International Journal of Accounting Information Systems, 32, 24–43. [Google Scholar] [CrossRef] [Scilit]
- Chulanov, K. V., Khymchenko, Y. V., Mykhailov, O. O., & Piven, V. S. (2022). Impact of digitalization on accounting in the transition to Industry 4.0. Available online: https://essuir.sumdu.edu.ua/items/4a9151dd-1b43-4269-a93f-027007eaf37e (accessed on 18 May 2025).
- Chung, K. H., Pak, H. S., & Cox, R. A. K. (1992). Patterns of research output in the accounting literature: A study of the bibliometric distributions. Abacus, 28(2), 168–185. [Google Scholar] [CrossRef] [Scilit]
- Chyzhevska, L., Voloschuk, L., Shatskova, L., & Sokolenko, L. (2021). Digitalization as a vector of information systems development and accounting system modernization. Studia Universitatis Vasile Goldis Arad, Economics Series, 31(4), 18–39. [Google Scholar] [CrossRef] [Scilit]
- Cobo, M. J., López-Herrera, A. G., Herrera-Viedma, E., & Herrera, F. (2011). An approach for detecting, quantifying, and visualizing the evolution of a research field: A practical application to the Fuzzy Sets Theory field. Journal of Informetrics, 5(1), 146–166. [Google Scholar] [CrossRef] [Scilit]
- Cooper, L. A., Holderness, D. K., Sorensen, T. L., & Wood, D. A. (2019). Robotic process automation in public accounting. Accounting Horizons, 33(4), 15–35. [Google Scholar] [CrossRef] [Scilit]
- Cortés-Sánchez, J. D. (2020). A bibliometric outlook of the most cited documents in business, management and accounting in Ibero-America. European Research on Management and Business Economics, 26(1), 1–8. [Google Scholar] [CrossRef] [Scilit]
- Curtis, M. B., Jenkins, J. G., Bedard, J. C., & Deis, D. R. (2009). Auditors’ training and proficiency in information systems: A research synthesis. Journal of Information Systems, 23(1), 79–96. [Google Scholar] [CrossRef] [Scilit]
- da Costa, R. S., & Nogueira, D. P. (2016). Perfil e evolução do ENANPAD: Análise bibliométrica e sociométrica da área de ensino e pesquisa em administração e contabilidade de 2001 a 2014. Espacios, 37(21), 20. [Google Scholar]
- da Silva, M. C., & Niyama, J. K. (2019). Bibliometric analysis of the evolution of scientific research in international accounting in the main english language journals. Revista Ambiente Contabil, 11(2), 65–87. [Google Scholar] [CrossRef] [Scilit]
- Deloitte. (2018). Internal controls over financial reporting considerations for developing and implementing bots (Issue September). Available online: https://dart.deloitte.com/USDART/pdf/a754eed6-c33e-11e8-8215-7ddf50acb392 (accessed on 29 October 2025).
- Donthu, N., Kumar, S., Mukherjee, D., Pandey, N., & Lim, W. M. (2021). How to conduct a bibliometric analysis: An overview and guidelines. Journal of Business Research, 133, 285–296. [Google Scholar] [CrossRef] [Scilit]
- Dos Santos Teixeira, L. M., & De Souza Ribeiro, M. (2014). Bibliometric study about environmental accounting caracteristics in nacional and international journals [Estudo bibliométrico sobre as características da contabilidade ambiental em periódicos nacionais e internacionais]. Revista de Gestao Social e Ambiental, 8(1), 20–36. [Google Scholar] [CrossRef] [Scilit]
- Ernst & Young Global Limited. (2019). Why robotics may be the future for family offices (Issue May). Ernst & Young Global Limited. [Google Scholar]
- Faria Duarte, A. L., & Zouain, D. M. (2019). Conceptual rescue of accountability: Proposed categorization from bibliometric study. Revista Gestao Organizacional, 12(2), 102–127. [Google Scholar]
- Fernandez, D., Zaino, Z., & Ahmad, H. (2018). An investigation of challenges in Enterprise Resource Planning (ERP) implementation: The case of public sector in Malaysia. International Journal of Supply Chain Management, 7(3), 113–117. [Google Scholar]
- Fernández, D., & Aman, A. (2018). Impacts of robotic process automation on global accounting services. Asian Journal of Accounting and Governance, 9, 123–131. [Google Scholar] [CrossRef] [Scilit]
- Financial Accounting Standards Board. (2016). FASB concepts statement No. 8, conceptual framework for financial reporting. Available online: https://www.fasb.org/page/ShowPdf?path=Concepts_Statement_No._8_Chapter_8_(As_Issued).pdf&title=CONCEPTS%20STATEMENT%20NO.%208%E2%80%94CONCEPTUAL%20FRAMEWORK%20FOR%20FINANCIAL%20REPORTING%E2%80%94CHAPTER%208,%20NOTES%20TO%20FINANCIAL (accessed on 29 October 2025).
- Gahramanov, R. (2022). Implementation of accounting information systems (Vol. 18, pp. 103–111). Pahtei Proceedings of Azerbaijan High Technical Educational Institutions. ISSN: 1609-1620, E-lSSN: 2674-5224. [Google Scholar]
- Garcia, E. L. M., Fadel, M. O., Sanches, S. L. R., & Moraes, R. D. O. (2016). Influência da regulamentação contábil de instrumentos financeiros na produção científica: Uma análise bibliométrica em periódicos nacionais. REUNIR: Revista de Administração, Contabilidade e Sustentabilidade, 6(1), 74. [Google Scholar] [CrossRef] [Scilit]
- Genete, L.-D., & Tugui, A. (2008, September 23–25). From ERP systems to digital accounting in relations with customers and suppliers. Selected Papers from the WSEAS Conferences in Spain (pp. 57–63), Santander, Spain. [Google Scholar]
- Gnatiuk, T., Shkromyda, V., & Shkromyda, N. (2023). Digitalization of accounting: Implementation features and efficiency assessment. Journal of Vasyl Stefanyk Precarpathian National University, 10(2), 45–58. [Google Scholar] [CrossRef] [Scilit]
- Goldhar, J. D., & Jelinek, M. (1990). Manufacturing as a service business: CIM in the 21st century. Computers in Industry, 14(1–3), 225–245. [Google Scholar] [CrossRef] [Scilit]
- Gomaa, A. A., Gomaa, M. I., Boumediene, S. L., & Farag, M. S. (2023). The creation of one truth: Single-ledger entries for multiple stakeholders using blockchain technology to address the reconciliation problem. Journal of Emerging Technologies in Accounting, 20(1), 59–75. [Google Scholar] [CrossRef] [Scilit]
- Guimarães, P. P. R. S., Ribeiro, L. M. d. P., Brandão, M. L., & Araújo, U. P. (2019). Bibliometric analysis of brazilian surveys on accounting and costs in agribusiness. Custos e Agronegocio, 15(2), 305–327. [Google Scholar]
- Handoko, L. H., & Mardian, S. (2021). Mapping the knowledge of islamic accounting studies on shariah audit: A bibliometric analysis. Library Philosophy and Practice, 102, 1–16. [Google Scholar]
- Handoyo, S. (2024). Evolving paradigms in accounting education: A bibliometric study on the impact of information technology. International Journal of Management Education, 22(3), 100998. [Google Scholar] [CrossRef] [Scilit]
- Henrique, M. R., Da Silva, J. M., Saporito, A., & Silva, S. B. (2021). Tax accounting: Bibliometric study of the accounting area between the period 2010 to 2020. Revista Contabilidade e Controladoria, 12(3), 148–164. [Google Scholar] [CrossRef] [Scilit]
- Hülle, J., Kaspar, R., & Möller, K. (2011). Multiple criteria decision-making in management accounting and control-state of the art and research perspectives based on a bibliometric study. Journal of Multi-Criteria Decision Analysis, 18(5–6), 253–265. [Google Scholar] [CrossRef] [Scilit]
- International Accounting Standards Board. (2018). Conceptual framework for financial reporting. Available online: https://www.ifrs.org/content/dam/ifrs/publications/pdf-standards/english/2021/issued/part-a/conceptual-framework-for-financial-reporting.pdf (accessed on 25 May 2025).
- Ionescu, L. (2021). Big data analytics tools and machine learning algorithms in cloud-based accounting information systems. Analysis and Metaphysics, 20, 102–115. [Google Scholar] [CrossRef] [Scilit]
- Ismayilov, N. (2020). Innovative approaches in the accounting and audit of the book value of assets: Bibliometric analysis. Marketing and Management of Innovations, 3, 319–331. [Google Scholar] [CrossRef] [Scilit]
- Jariwala, B. (2015). Exploring arti cial intelligence & the accountancy profession: Opportunity, threat, both, neither? International Federation of Accountatns. Available online: https://www.ifac.org/knowledge-gateway/developing-accountancy-profession/discussion/exploring-artificial-intelligence-accountancy-profession-opportunity-threat-both-neither (accessed on 23 April 2025).
- Jönsson, S., & Grönlund, A. (1988). Life with a sub-contractor: New technology and management accounting. Accounting, Organizations and Society, 13(5), 513–532. [Google Scholar] [CrossRef] [Scilit]
- Keenoy, C. L. (1958). The impact of automation on the field of accounting. The Accounting Review, 33(2), 230–236. [Google Scholar]
- Kerremans, M., Theunisse, H., & Overloop, G. V. (1991). Impact of automation on cost accounting. Accounting and Business Research, 21(82), 147–155. [Google Scholar] [CrossRef] [Scilit]
- Kuhner, C., & Pelger, C. (2015). On the relationship of stewardship and valuation—An analytical viewpoint. Abacus, 51(3), 379–411. [Google Scholar] [CrossRef] [Scilit]
- Kumar, P., Sharma, A., & Salo, J. (2019). A bibliometric analysis of extended key account management literature. Industrial Marketing Management, 82, 276–292. [Google Scholar] [CrossRef] [Scilit]
- Kumar, S., Marrone, M., Liu, Q., & Pandey, N. (2020). Twenty years of the international journal of accounting information systems: A bibliometric analysis. International Journal of Accounting Information Systems, 39, 100488. [Google Scholar] [CrossRef] [Scilit]
- Lea, B. R., & Fredendall, L. D. (2002). The impact of management accounting, product structure, product mix algorithm, and planning horizon on manufacturing performance. International Journal of Production Economics, 79(3), 279–299. [Google Scholar] [CrossRef] [Scilit]
- Lee, Y., Kozar, K. A., & Larsen, K. R. T. (2003). The technology acceptance model: Past, present, and future. Communications of the Association for Information Systems, 12, 752–780. [Google Scholar] [CrossRef] [Scilit]
- Lehner, O. M., Ittonen, K., Silvola, H., Ström, E., & Wührleitner, A. (2022). Artificial intelligence based decision-making in accounting and auditing: Ethical challenges and normative thinking. Accounting, Auditing and Accountability Journal, 35(9), 109–135. [Google Scholar] [CrossRef] [Scilit]
- Leoni, G., & Parker, L. D. (2019). Governance and control of sharing economy platforms: Hosting on Airbnb. British Accounting Review, 51(6), 100814. [Google Scholar] [CrossRef] [Scilit]
- Linnenluecke, M. K., Marrone, M., & Singh, A. K. (2020). Sixty years of Accounting & Finance: A bibliometric analysis of major research themes and contributions. Accounting and Finance, 60(4), 3217–3251. [Google Scholar] [CrossRef] [Scilit]
- Liu, R., Wang, Y., & Zou, J. (2022). Research on the transformation from financial accounting to management accounting based on drools rule engine. Computational Intelligence and Neuroscience, 2022, 9445776. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Lutfi, A., Alkelani, S. N., Al-Khasawneh, M. A., Alshira’h, A. F., Alshirah, M. H., Almaiah, M. A., Alrawad, M., Alsyouf, A., Saad, M., & Ibrahim, N. (2022a). Influence of digital accounting system usage on SMEs performance: The moderating effect of COVID-19. Sustainability, 14(22), 15048. [Google Scholar] [CrossRef] [Scilit]
- Lutfi, A., Alkelani, S. N., Alqudah, H., Alshira’h, A. F., Alshirah, M. H., Almaiah, M. A., Alsyouf, A., Alrawad, M., Montash, A., & Abdelmaksoud, O. (2022b). The role of E-accounting adoption on business performance: The moderating role of COVID-19. Journal of Risk and Financial Management, 15(12), 617. [Google Scholar] [CrossRef] [Scilit]
- Lytvyn, L., Hryhoruk, A., Verbivska, L., Poprotskyy, O., Medynska, T., & Pelekh, O. (2022). Enterpreneship transformation in the context of the digitization of business processes. Postmodern Openings, 13(2), 396–408. [Google Scholar] [CrossRef] [Scilit]
- Łada, M., & Martinek-Jaguszewska, K. (2023). The autonomization of accounting processes. Zeszyty Teoretyczne Rachunkowosci, 47(3), 95–111. [Google Scholar] [CrossRef] [Scilit]
- Marzi, G., Balzano, M., Caputo, A., & Pellegrini, M. M. (2025). Guidelines for bibliometric-systematic literature reviews: 10 steps to combine analysis, synthesis and theory development. International Journal of Management Reviews, 27(1), 81–103. [Google Scholar] [CrossRef] [Scilit]
- Merigo, J. M., & Yang, J.-B. (2017). Accounting research: A bibliometric analysis. Australian Accounting Review, 27(1), 71–100. [Google Scholar] [CrossRef] [Scilit]
- Merigó, J. M., & Yang, J. B. (2017). A bibliometric analysis of operations research and management science. Omega, 73, 37–48. [Google Scholar] [CrossRef] [Scilit]
- Mohanty, B. K. (2019). Accounting, organizations and society: A bibliometric study based on the science direct database during the year, 2005–2014. Library Philosophy and Practice, 2019, 1–18. [Google Scholar]
- Mongeon, P., & Paul-Hus, A. (2016). The journal coverage of Web of Science and Scopus: A comparative analysis. Scientometrics, 106(1), 213–228. [Google Scholar] [CrossRef] [Scilit]
- Monteiro, A. P., Vale, J., Silva, A., & Pereira, C. (2021). Impact of the internal control and accounting systems on the financial information usefulness: The role of the financial information quality. Academy of Strategic Management Journal, 20(3), 1–13. [Google Scholar]
- Moraes, G. L. d., Behr, A., & Farias, E. d. S. (2016). Cost accounting in agribusiness: A bibliometric study of the articles published in the journal custos e @gronegócio online. Custos e Agronegocio, 12, 71–94. [Google Scholar]
- Mosweu, O., & Ngoepe, M. (2020). Trustworthiness of digital records in government accounting system to support the audit process in Botswana. Records Management Journal, 31(1), 89–108. [Google Scholar] [CrossRef] [Scilit]
- Moya, S., & Prior, D. (2008). Who publish in Spanish accounting jornals? A bibliometric analysis 1996–2005. Revista Espanola de Financiacion y Contabilidad, 37(138), 353–374. [Google Scholar] [CrossRef] [Scilit]
- Nguyen, N. M., Abu Afifa, M., & Van Bui, D. (2023). Blockchain technology and sustainable performance: Moderated-mediating model with management accounting system and digital transformation. Environment, Development and Sustainability, 27, 7255–7277. [Google Scholar] [CrossRef] [Scilit]
- Nolli, J. G., Giordani, M. D. S., Domingues, M. J. C. d. S., & Zonatto, V. C. d. S. (2020). Avaliação da aprendizagem em ciências contábeis: Um estudo bibliométrico e sociométrico. Revista Contabilidade e Controladoria, 11(2), 40–56. [Google Scholar] [CrossRef] [Scilit]
- Noyons, E. C. M., Moed, H. F., & Van Raan, A. F. J. (1999). Integrating research performance analysis and science mapping. Scientometrics, 46(3), 591–604. [Google Scholar] [CrossRef] [Scilit]
- Olusanmi, O. A., Emeni, F. K., Uwuigbe, U., & Oyedayo, O. S. (2021). A bibliometric study on water management accounting research from 2000 to 2018 in Scopus database. Cogent Social Sciences, 7(1), 1886645. [Google Scholar] [CrossRef] [Scilit]
- Omar, S. S., Nayef, J. M., Qasim, N. H., Kawad, R. T., & Kalenychenko, R. (2024). The role of digitalization in improving accountability and efficiency in public services. Investigacion Operacional, 45(2), 203–223. [Google Scholar]
- Panasenko, S. V., Cheglov, V. P., Ramazanov, I. A., Anatolevna Krasil’nikova, E., & Sharonin, P. N. (2021). Mechanisms of e-commerce enterprises development in the context of digitalization. Nexo Revista Científica, 34(1), 469–476. [Google Scholar] [CrossRef] [Scilit]
- Parra-Sánchez, D. T., & Talero-Sarmiento, L. H. (2024). Digital transformation in small and medium enterprises: A scientometric analysis. Digital Transformation and Society, 3(3), 257–276. [Google Scholar] [CrossRef] [Scilit]
- Petchenko, M., Fomina, T., Balaziuk, O., Smirnova, N., & Luhova, O. (2023). Analysis of trends in the implementation of digitalization in accounting (ukrainian case). Financial and Credit Activity: Problems of Theory and Practice, 1(48), 105–113. [Google Scholar] [CrossRef] [Scilit]
- Phornlaphatrachakorn, K., & Kalasindhu, K. N. (2021). Digital accounting, financial reporting quality and digital transformation: Evidence from Thai listed firms. The Journal of Asian Finance, Economics and Business, 8(8), 409–0419. [Google Scholar] [CrossRef]
- Poje, T., & Zaman Groff, M. (2022). Mapping ethics education in accounting research: A bibliometric analysis. Journal of Business Ethics, 179(2), 451–472. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Ponomareva, T., & Matiushko, M. (2021). Analysis of software products used for automation of accounting by entrepreneurship subjects. Social Economics, 62, 148–155. [Google Scholar] [CrossRef] [Scilit]
- Poppe, K., Vrolijk, H., & Bosloper, I. (2023). Integration of farm financial accounting and farm management information systems for better sustainability reporting. Electronics, 12(6), 1485. [Google Scholar] [CrossRef] [Scilit]
- Qi, S., Huang, Z., & Ji, L. (2021). Sustainable development based on green GDP accounting and cloud computing: A case study of Zhejiang province. Scientific Programming, 2021, 7953164. [Google Scholar] [CrossRef] [Scilit]
- R Core Team. (2025). R: A language and environment for statistical computing. R Foundation for Statistical Computing. Available online: https://www.R-project.org/ (accessed on 25 May 2025).
- Resler, M. V. (2013). General approach to the implementation of automated management accounting. Business Inform, 1, 321–323. [Google Scholar]
- Rindasu, S.-M. (2017). Emerging information technologies in accounting and related security risks—What is the impact on the romanian accounting profession. Journal of Accounting and Management Information Systems, 16(4), 581–609. [Google Scholar] [CrossRef] [Scilit]
- Robey, D., & Rodriguez-Diaz, A. (1989). The organizational and cultural context of systems implementation: Case experience from Latin America. Information and Management, 17(4), 229–239. [Google Scholar] [CrossRef] [Scilit]
- Rogers, G., Szomszor, M., & Adams, J. (2020). Sample size in bibliometric analysis. Scientometrics, 125(1), 777–794. [Google Scholar] [CrossRef] [Scilit]
- Saleh, M. M. A., Jawabreh, O. A. A., Al Om, R., & Shniekat, N. (2021). Artificial intelligence (AI) and the impact of enhancing the consistency and interpretation of financial statement in the classified hotels in Aqaba, Jordan. Academy of Strategic Management Journal, 20(3), 1–18. [Google Scholar]
- Sani, A., & Tiamiyu, M. (2005). Evaluation of automated services in Nigerian universities. Electronic Library, 23(3), 274–288. [Google Scholar] [CrossRef] [Scilit]
- Scarbrough, P., Nanni, A. J., & Sakurai, M. (1991). Japanese management accounting practices and the effects of assembly and process automation. Management Accounting Research, 2(1), 27–46. [Google Scholar] [CrossRef] [Scilit]
- Schaltegger, S., Gibassier, D., & Zvezdov, D. (2013). Is environmental management accounting a discipline? A bibliometric literature review. Meditari Accountancy Research, 21(1), 4–31. [Google Scholar] [CrossRef] [Scilit]
- Schatsky, D., Muraskin, C., & Gurumurthy, R. (2015). Cognitive technologies: The real opportunities for business. Deloitte Review, 16, 114–129. [Google Scholar]
- Slavinskaitė, N. (2022). Automation of accounting processes: Case study of the companies in Lithuanian. Global Journal of Business, Economics, and Management: Current Issues, 12(3), 316–325. [Google Scholar] [CrossRef] [Scilit]
- Spilnyk, I., Brukhanskyi, R., Struk, N., Kolesnikova, O., & Sokolenko, L. (2022). Digital accounting: Innovative technologies cause a new paradigm. Independent Journal of Management & Production, 13(3), s215–s224. [Google Scholar] [CrossRef] [Scilit]
- Swanson, E. B. (2020). How information systems came to rule the world: Reflections on the information systems field. Information Society, 36(2), 109–123. [Google Scholar] [CrossRef] [Scilit]
- Tingey-Holyoak, J., Pisaniello, J., Buss, P., & Mayer, W. (2021). The importance of accounting-integrated information systems for realising productivity and sustainability in the agricultural sector. International Journal of Accounting Information Systems, 41, 100512. [Google Scholar] [CrossRef] [Scilit]
- van Raan, A. F. J. (2005). Measuring science. In H. F. Moed, W. Glänzel, & U. Schmoch (Eds.), Handbook of quantitative science and technology research (pp. 19–50). Springer. [Google Scholar] [CrossRef] [Scilit]
- Vedernikova, O., Siguenza-Guzman, L., Pesantez, J., & Arcentales-Carrion, R. (2020). Time-driven activity-based costing in the assembly industry. Australasian Accounting, Business and Finance Journal, 14(4), 3–23. [Google Scholar] [CrossRef] [Scilit]
- Vysochan, O. S., Hyk, V., Mykytyuk, N., & Vysochan, O. O. (2023). Taxonomy of financial reporting in the context of digitalization of the economy: Domestic and international analysis scientific research. Studia Universitatis Vasile Goldis Arad, Economics Series, 33(2), 49–70. [Google Scholar] [CrossRef] [Scilit]
- Wang, S., Tang, X., Zhang, B., & Wang, W. (2021). Accounting and management of natural resource consumption based on input-output method: A global bibliometric analysis. Frontiers in Energy Research, 9, 628321. [Google Scholar] [CrossRef] [Scilit]
- White, H. D., & McCain, K. W. (1998). Visualizing a discipline: An author co-citation analysis of information science, 1972–1995. Journal of the American Society for Information Science, 49(4), 327–355. [Google Scholar] [CrossRef] [Scilit]
- Yamaguchi, C. K., dos Santos, A. P. S., & Watanabe, M. (2015). Environmental accounting: A bibliometric study [Contabilidade ambiental: Um estudo bibliométrico]. Espacios, 36(11), 1–8. [Google Scholar]
- Yao, F., Qin, Z., Wang, X., Chen, M., Noor, A., Sharma, S., Singh, J., Kozak, D., & Hunjet, A. (2023). The evolution of renewable energy environments utilizing artificial intelligence to enhance energy efficiency and finance. Heliyon, 9(5), e16160. [Google Scholar] [CrossRef] [Scilit]
- Zhang, H., Zheng, Q., Dong, B., & Feng, B. (2021). A financial ticket image intelligent recognition system based on deep learning. Knowledge-Based Systems, 222, 106955. [Google Scholar] [CrossRef] [Scilit]
- Zhao, J., Zhang, L., & Zhao, Y. (2022). Informatization of accounting systems in small- and medium-sized enterprises based on artificial intelligence-enabled cloud computing. Computational Intelligence and Neuroscience, 2022, 6089195. [Google Scholar] [CrossRef] [Scilit]
- Zhyvko, Z., Nikolashyn, A., Semenets, I., Karpenko, Y., Zos-Kior, M., Hnatenko, I., Klymenchukova, N., & Krakhmalova, N. (2022). Secure aspects of digitalization in management accounting and finances of the subject of the national economy in the context of globalization. Journal of Hygienic Engineering and Design, 39, 259–269. [Google Scholar]
- Zupic, I., & Čater, T. (2015). Bibliometric methods in management and organization. Organizational Research Methods, 18(3), 429–472. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).