


Abstract
Improved agricultural value chains linking rural and urban areas can provide opportunities to initiate development interventions. This paper was aimed at mapping the value chain of cauliflower and tomato along with the identification of internal and external governance structures throughout the chain. Data were collected from 100 farmers and 60 traders, selected through the application of simple random and purposive sampling, respectively. Value chain mapping techniques and marketing margins were used for evaluating the economic performance of each actor. To uncover the farmers’ perceptions of internal and external governance structures, the Likert scaling technique was utilized, which was checked by applying the Mann–Whitney U test. Eleven marketing channels were ascertained for cauliflower and tomato, whereas wholesalers contributed the largest share of gross (32.28% for cauliflower and 31.96% for tomato) and net (57.41% for cauliflower and 48.09% for tomato) marketing margins. The highest return on investment was obtained by Aratdars. The lowest amount of cauliflower (1.51%) and tomato (1.30%) were responsible for direct marketing. The benefit–cost ratio was found to be 1.30 and 1.25, respectively, for cauliflower and tomato. This paper revealed considerable differences among NATP and non-NATP farmers with regard to internal and external governance practices. Despite both groups reporting good internal governance practices from their own perspectives, the negative attitude of NATP and non-NATP farmers toward the existence of good external governance practices created a matter of deep concern. To ensure the farmers’ benefits, good governance practices must be implemented throughout the value chain.
1. Introduction
Bangladesh is primarily an agricultural country with an estimated population of 165.15 million people [1]. Agriculture, which includes the crop, fishery, livestock, and forest subsectors, is considered the most important economic sector, contributing significantly to food security, value addition, export earnings, employment generation, and poverty alleviation [2,3,4,5,6].
The performance of this sector is directly connected to the country’s overall economic prosperity [4]. Bangladesh is vulnerable to hazardous climatic effects, where agricultural land is rapidly decreasing owing to unplanned industrial expansion and urbanization. With the development and expansion of other sectors (for example, readymade garments), the agriculture’s share of Gross Domestic Product (GDP) has inevitably decreased [2]. Still, the broad agricultural sector is playing a crucial role by contributing 11.50% to the GDP, and also employing around 40.60% of the total labor force [7]. Hence, sustainable and eco-friendly agricultural practices are essential for ensuring the long-term food security of the country’s burgeoning population, which is consistent with the second goal of the SDG (Sustainable Development Goals).
One of the most important components of the crop subsector is the vegetable subsector. As crops are high-value in nature, it is normal to increase the commercial cultivation of vegetables [8]. Vegetables assist in preventing cancer, heart disease, cataracts, hypertension, stroke, and diabetes by providing antioxidants such as vitamin A, C, and E [9,10,11]. Bangladesh is blessed with weather and soils that are conducive to growing a wide range of vegetables. Moreover, in the cultivation of vegetables, Bangladesh has a comparative advantage which has resulted in potential opportunities for the sector [12]. Therefore, a huge number of farmers cultivate various types of vegetables throughout the year in Bangladesh. The year-round expansion of vegetable cultivation is assisting the country in gaining a new level of comfort. Despite outperforming several emerging countries in the context of poverty reduction, approximately 20.5% of people in Bangladesh live below the poverty line [7]. Vegetable cultivation could be a great way to address this challenge by ensuring a new source of income and providing essential nutrients [2,13]. When compared to cereal crops, farmers frequently make more income from vegetable cultivation [14]. Even though 75% of the country’s 8.5 million hectares of arable land are occupied by rice and cereals, vegetable production is growing because of the technical support provided by the government [13,15].
Two of the most popular vegetables grown in Bangladesh are cauliflower and tomato. In Bangladesh, the production of vegetables such as cauliflower and tomato is steadily expanding [16]. Bangladesh produced 387,653 tons of tomato and 284,327 tons of cauliflower in 2018–2019 [17].
Smallholders can contribute to the alleviation of rural poverty by having access to well-functioning local or global marketplaces. A value chain strategy is increasingly being used by many development initiatives to engage smallholders in both domestic and high-value export markets [18]. The value chain encompasses the complete process of bringing a product or service from conception through the various stages of production, distribution to final consumers, and after-use disposal [19]. Barnes [20] defined this development tool as a vertical alliance of enterprises collaborating to achieve a more rewarding market position by effectively and efficiently linking production, processing, and marketing activities. Despite being separated by time and space, it describes how producers, processors, buyers, sellers, and consumers progressively add value to products [21]. This approach not only allows for the evaluation of the efficiency of value-added services, but also provides a number of opportunities to boost the productivity and commerce, as well as the capacity, of farmers and other actors to generate income. The value of a product increases as it moves through the various phases of the supply chain [22]. The notion of added value has been used to construct a business’s long-term competitive advantage in the form of a value chain. Michael Porter [23] considered the value chain as a fundamental tool for assessing the source of competitive advantages by focusing on organization, power relationships, governance structure, and market collaborating strategy. It helps to understand how various activities affect the business unit as a whole, as well as developing the inter-relationships between activities that generate value. Agricultural value chain analysis investigates how markets adjust to variation in commodity demand and supply and alteration in institutional and management structures, as well as technological advancements in both production and marketing techniques [21]. Besides improving interconnectivity among all actors, this approach helps to ascertain weak points and corresponding actions to add more value along the agricultural supply chain [24,25]. A vegetable value chain can be thought of as a set of actors, activities, organizations, and governing rules. The actors throughout the value chain may have limited access to services and other types of assistance which can limit their ability to actively participate in higher-value segments of the chain [26]. Moreover, small-scale vegetable farms are usually based on low-input, low-output production strategies [9]. Therefore, the value chain must be analyzed in order to uncover inefficiencies throughout the chain, improve the coordination mechanisms, aid in understanding power dynamics, and identify the governing actor. As a tool against poverty, this approach improves food security by implementing specific production practices, and increases the quality-based competitiveness of the produce by upgrading agricultural value chains [27]. For improving the value chain performance, governance structure serves as a key tool. It is the mechanism that defines how control is exercised by influencing the activities of all stakeholders, and plays a major role in determining the sustainability of the chain through upgraded production capabilities and the proper distribution of benefits [28,29]. Good governance practices ensure better access to inputs, the improvement of working conditions and skill, the facilitation of information flow and financial services, and the expansion of access to high-value markets.
Even though several studies have been conducted on vegetable value chains in various regions of the country, there is a dearth of research work regarding cauliflower and tomato value chain analysis in Bangladesh. This study has been designed to achieve the following specific objectives: (1) to map the vegetable value chain and estimate the value added by different actors; and (2) to identify the type of governance structure followed by farmers. By analyzing the value chain and governance structure, this study will help all stakeholders to understand the prevailing situation and challenges and make their own judgments accordingly.
2. Literature Review
Value chains and their methods of analysis have been considered in many ways in the literature on the agricultural market [30]. Agricultural value chain analysis employs the six steps outlined as follows: prioritizing a commodity for value chain development; value chain mapping; analyzing performance in terms of costs, prices, and margins; analyzing technology, knowledge, and upgrading opportunities; analyzing the governance structure along the chain; and analyzing linkages among the stakeholders [19].
Onyangore [31] explored the level of collaboration and highly individualistic behaviors among the actors in the African indigenous vegetables (AIV) value chain that aided uncoordinated chain functions in being unable to utilize the benefits of the increasing demand for vegetables. Governance structure was mentioned as a significant tool for making interventions in value chain development. Tomato and cauliflower farmers were found to practice spot market, relational, farmers’’ association, and outgrowing-scheme-based governance structures depending on their transactional traits throughout the chain. Also, the traders showed dissimilation towards various indicators of internal and external governance structures [32]. The benefit–cost ratio of 1.61 worked as an indication of profitable enterprise for both tomato farmers and traders in Lalitpur, Nepal. The marketing margin was NRs. 32/kg, and the producer’s share was 46.6% in the most commonly used marketing channel of tomato [33]. Rahman et al. [34] ascertained the Paiker-1/Bepari as a major governing actor in the vegetable value chain in the north-eastern part of Bangladesh. Even though horizontal linkage was identified, vertical linkage was absent throughout the chain. The farmers had minimal bargaining power and were obliged to accept what traders offered. Inclusive governance was actually buyer-driven along the vegetable value chain, where Aratdars had the highest return on investment. Samoggia et al. [35] identified Interbranch Organizations (IBOs) as a less-explored subject in agro-food governance studies that promotes best practice and market transparency. For solving power imbalances, collective action among the farmers was suggested. Th role of local institutions was explored for introducing innovations along the food supply chain, and the future expansion of IBOs in Italy was also suggested. Wosen and Gobie [36] reported on the processors’ highest profit share of 44.82% among all other actors while conducting the structure, conduct, and performance analysis of the tomato value chain in the Amhara regional state of Ethiopia. With a buyer’s concentration of 45.53%, the market structure was found to be oligopolistic in nature. The traders set 73.21% of the tomato price, whereas the producers were the price takers. Branca et al. [37] discussed the importance of market-based interventions (such as value chain coordination) for improving the value-chain-ready farmers’ market access. Also, non-market-based interventions (such as access to inputs, credits, and extension services) were found to be effective in building the minimum asset thresholds for non-value-chain-ready farmers’ market participation. An economic analysis determined the benefit–cost ratio of 2.44 for cauliflower cultivation, where the cost of labor, seed, and fertilizer had a significant impact on its production [3]. Poudel et al. [38] identified the average production cost as Rs. 7.84/kg for main-season cauliflower and Rs. 11.59/kg for off-season cauliflower. The marketing margin and producer share were Rs. 6.18/kg and 72.95% as well as Rs. 29.2/kg and 52.18%, respectively, for seasonal and off-season cauliflower. Value chain analysis of fresh-cut vegetables (bell pepper, lettuce head, and broccoli) showed a lower environmental impact than productivity level, while sustainability analysis revealed the ‘enough sustainable’ status of the fresh-cut vegetable agro-industry in Indonesia [39]. Shifting the cultivation area nearer to the fresh-cut agro-industry and sustainable contract farming were suggested for fresh-cut business development. Despite the presence of conventional actors in the Rugombo district of Burundi, smallholder producers dominated the tomato value chain, which was characterized by a lack of added value as well as poor vertical and horizontal coordination among the actors [30]. Rural assemblers, wholesalers, retailers, and farmers had the margin share of, respectively, 16.16%, 12.57%, 36.32%, and 34.95%. Sarma and Ali [40] revealed that tomato farmers contributed 49.36% of the value-added cost in the farming stage, while they obtained a revenue of only 21.58%. Conversely, traders received 21.37% of the total revenue during the fresh tomato trading stage against their contribution of 9.50% of the value-added cost. AbdElrazig et al. [41] identified that the primary processor in the farmer stage added 53% of the value, the middleman stage added 21.7%, wholesalers added 10.2%, and retailers added 15.1% of the value. Retailers obtained the highest profit percentage of 52.1%, and the farmers had the lowest (8.8%). Biftu et al. [42] established channel II (Producers ⇒ Retailer ⇒ Consumer) as having the highest producer share of 80% of the total consumer price. Wholesalers took the highest gross marketing margin of 28.57% in channel V (Producers ⇒ Wholesaler ⇒ Consumer). Retailers and collectors accounted for the lowest gross marketing margins of 13.33% in channel III (Producers ⇒ Collector ⇒ Retailer ⇒ Consumer) and IV (Producers ⇒ Wholesaler ⇒ Retailer ⇒ Consumer). In the case of cauliflower, the average per unit net margin and per unit production cost was determined as Tk. 2.93 and Tk. 5.66, respectively. Also, the average margin per piece of cauliflower received by wholesalers, intermediate collectors, Aratdars, street vendors, and stale vegetable collectors was Tk. 4.76, 6.53, 3.95, 4.67, and 8.7, respectively [43]. Neupane et al. [44] noticed about a 5.4% post-harvest loss of tomatoes during handling, while only 4.4% of the total product was distributed directly to customers. Price spread and producer share were 15.25 and 62.88% as well as 7.96 and 76.41%, respectively, for the first channel (Producer ⇒ Wholesaler ⇒ Retailer ⇒ Consumer) and the second channel (Producer ⇒ Retailer ⇒ Consumer). Enoch [45] ascertained that retailers made the most profit with GHS 4.50 per 5 kg of fresh tomatoes sold, whereas farmers were paid only GHS 0.37 for the same. The distributors were the dominant actors wielding power over others in the chain. Good governance practices were absent in the context of credit facilities, market information, and prices of marketed tomatoes. According to the National Horticultural Research and Development Foundation of India [46], marginal tomato farmers were forced to sell approximately 90% of their produce through commission agents mainly due to lack of processing facilities. Weak linkage was observed among the actors of traditional vegetable value chains in Malawi and Mozambique. The chain actors largely focused on spot market transactions, whereas retailers and supermarkets focused on relationship marketing [47]. Hoq et al. [48] discussed the higher marketing cost of cauliflower due to its unique arrangement of transportation. The highest marketing margin was found for urban retailers with Tk. 130.09 per quintal. Sidhu et al. [49] showed that onion had a higher net return than cauliflower while conducting their supply chain analysis in Punjab. The cauliflower wholesale markets had been discovered to be integrated, with faster price transmission compared to onion.
3. Materials and Methods
3.1. Study Area
This study was carried out in the Sylhet and Moulvibazar districts under the Sylhet division of Bangladesh. Sylhet and Moulvibazar are the two districts in the north-east of Bangladesh. The district of Sylhet is located between the latitudes of 24°36′ and 25°11′ north and the longitudes of 91°38′ and 92°30′ east. On the other side, Moulvibazar is situated between the latitudes of 24°08′ and 24°29′ north and the longitudes of 91°36′ and 92°17′ east. As they have a high potential for vegetable production, both of these districts now grow vegetables commercially. The Sylhet district produced 6593 metric tons of cauliflower and 4457 metric tons of tomatoes, while Moulvibazar district produced 1577 metric tons and 3630 metric tons of these two vegetables, respectively [17]. From Sylhet Sadar Upazila of the Sylhet district, the Kandigaon and Hatkhola unions were chosen. Similarly, from Kamalganj Upazila of the Moulvibazar district, the Alinagar and Adampur unions were chosen. These areas were purposely selected based on vegetable production concentration.
3.2. Sampling and Data Collection
The population for this study includes selected vegetable producers as well as various market participants or traders. The Upazila Agriculture Office (UAO) provided a complete list of cauliflower and tomato growers in the study areas. The National Agricultural Technology Project (NATP) was designed to increase productivity, improve smallholder farmers’ access to markets, and eradicate extreme poverty by rejuvenating the whole agricultural technology system [50]. Under it, the farmers made a ‘common interest group’ (CIG) consisting of 20 members. A total of 100 farmers were chosen from two districts using a simple random sampling technique (52 with the “National Agricultural Technology Project (NATP)” and 48 without the NATP project) (Table 1). Furthermore, 60 traders were chosen purposely for the study. Since the current study relied on field-level primary data, creating a survey schedule was essential for gathering information from respondents. Two sets of survey schedules were prepared, which included questions regarding various aspects of the production and marketing of vegetables, various issues related to the governance followed by growers, and their perceptions of internal and external governance along the chain. Preliminary schedules were pre-tested to ensure reliability. Questions on governance issues were thoroughly explained in front of them in order to elicit their response. Data were collected during the period of August to October, 2019.
Table 1.
Distribution of samples.
3.3. Data Analysis
Descriptive analysis, value chain analysis, and the non-parametric test were used for data analysis. For examining and describing the socio-economic and demographic characteristics of sample farmers, descriptive statistical tools such as mean, maximum value, minimum value, percentages, and standard error were used. As a powerful descriptive tool, the value mapping technique was used. The first step was to identify the chain’s actors, followed by mapping the product flow within the chain. Mapping a chain entails visualizing the inter-connections among businesses in the value chains and other market participants [22,51,52]. A value chain map included the series of actions, stages of physical value addition, product circulation, key players, their interactions, and economic activities at each stage with the linked physical and monetary flows [30]. The study calculated the costs and margins of cauliflower and tomato growers. The following equation was employed to calculate the value addition/net profit of vegetables at the producer’s level:
where Profit of the vegetable farmers (Tk./ha); = Price of the produce (Tk./Qt); Quantity of the produce (Qt/ha); = Total variable cost (Tk./ha); = Total fixed cost (Tk./ha).
The fixed cost includes land use costs and interest on operating capital. The cost of land use was calculated using the current rental value (or lease value) of land in hectares per year. Variable costs associated with vegetable production were classified as operating capital. Interest on operating capital refers to when a farmer forgoes the profit of keeping money in the bank by investing cash in growing vegetables:
where i = interest rate per year and t = length of vegetable crop period in months/years.
Interest on operating capital (IOC) = Operating capital × interest rate (i) × time required (t)/2
Following the broad conceptual map of the value chain, the next step is to examine the economic performance. The marketing margin is a significant index in evaluating the performance of the value chain [53]. It is calculated by taking the difference between what the consumer pays (or retail price) and what the farmer receives for their product (or farm price) [42,54]. The following formulations [34,55] were used for assessing value addition at trader’s level:
where GMM = Gross marketing margin (Tk./Qt); NMM = Net marketing margin (Tk./Qt); MC = Marketing cost (Tk./Qt).
GMM = Selling price − purchase price
NMM = GMM − MC
Transportation cost, loading and unloading costs, market toll, commission, wastage, depreciation, and other miscellaneous costs are the most common marketing costs.
There are various forms and types of governance structures that actors in a specific value chain may follow. The Likert scale technique was utilized to determine the farmers’ perceptions of internal and external governance structures. Respondents were given predetermined options in order to rate their opinions. Each option required the farmers to select one of five alternative expressions: ‘highly agree’, ‘agree’, ‘neutral’, ‘disagree’, and ‘highly disagree’. Weights of 5, 4, 3, 2, and 1 were assigned to this five-point continuum. Following that, each respondent’s total score was calculated by adding the value of each item checked. The study used “item analysis” to assess each item’s ability to distinguish between the positive attitudes and the negative attitudes. This is referred to as the item’s discriminative power (DP). The following formula was used to calculate discriminative power [56]:
where, DP = Discriminative power
DP = Q1 − Q3
Weighted total = Score × Number who check that score; Weighted mean = .
The Mann–Whitney U test was applied to confirm the farmers’ diverse sentiment towards the governance structure.
4. Results and Discussion
4.1. Socio-Economic Characteristics of the Selected Farmers and Traders
The dominant age group was 41 to 50 years and the farmers were 44.70 years old on average (Table 2). The maximum and minimum age of the farmers was 67 and 22 years, respectively, whereas only 7% of the farmers were aged above 60 years. The majority of the farmers (52%) were illiterate, while 48% had a formal education of various levels. Apart from 60% of the farmers whose principle and only source of income was agriculture, about 25% and 15% of farmers reported business activities and service providing activities, respectively, as their secondary income source. Cauliflower and tomato farmers had an average of 16.05 years of expertise in growing vegetables. Only 6% of farmers had a farm size of more than 5 acres, whereas the average family size of the farmers was 5.65. About 48% of farmers lived 6 to 10 km from the nearest market. Even though the majority of the farmers (80%) had bargaining power, 56% of them reported regarding their trust commitment with buyers negatively. External governance practices were evident through access to both extension services (87%) and market information (74%), but the frequency of technical extension services and training and the proper dissemination of market information, as well as the availability of quality inputs, questioned sustainable good external governance practices. Further, more than half of the farmers (54%) reported problems in accessing inputs.
Table 2.
Socio-demographic characteristics of cauliflower and tomato farmers.
4.2. Value Chain Mapping of Cauliflower and Tomato
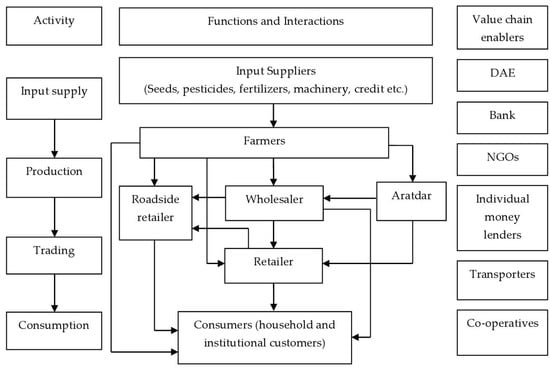
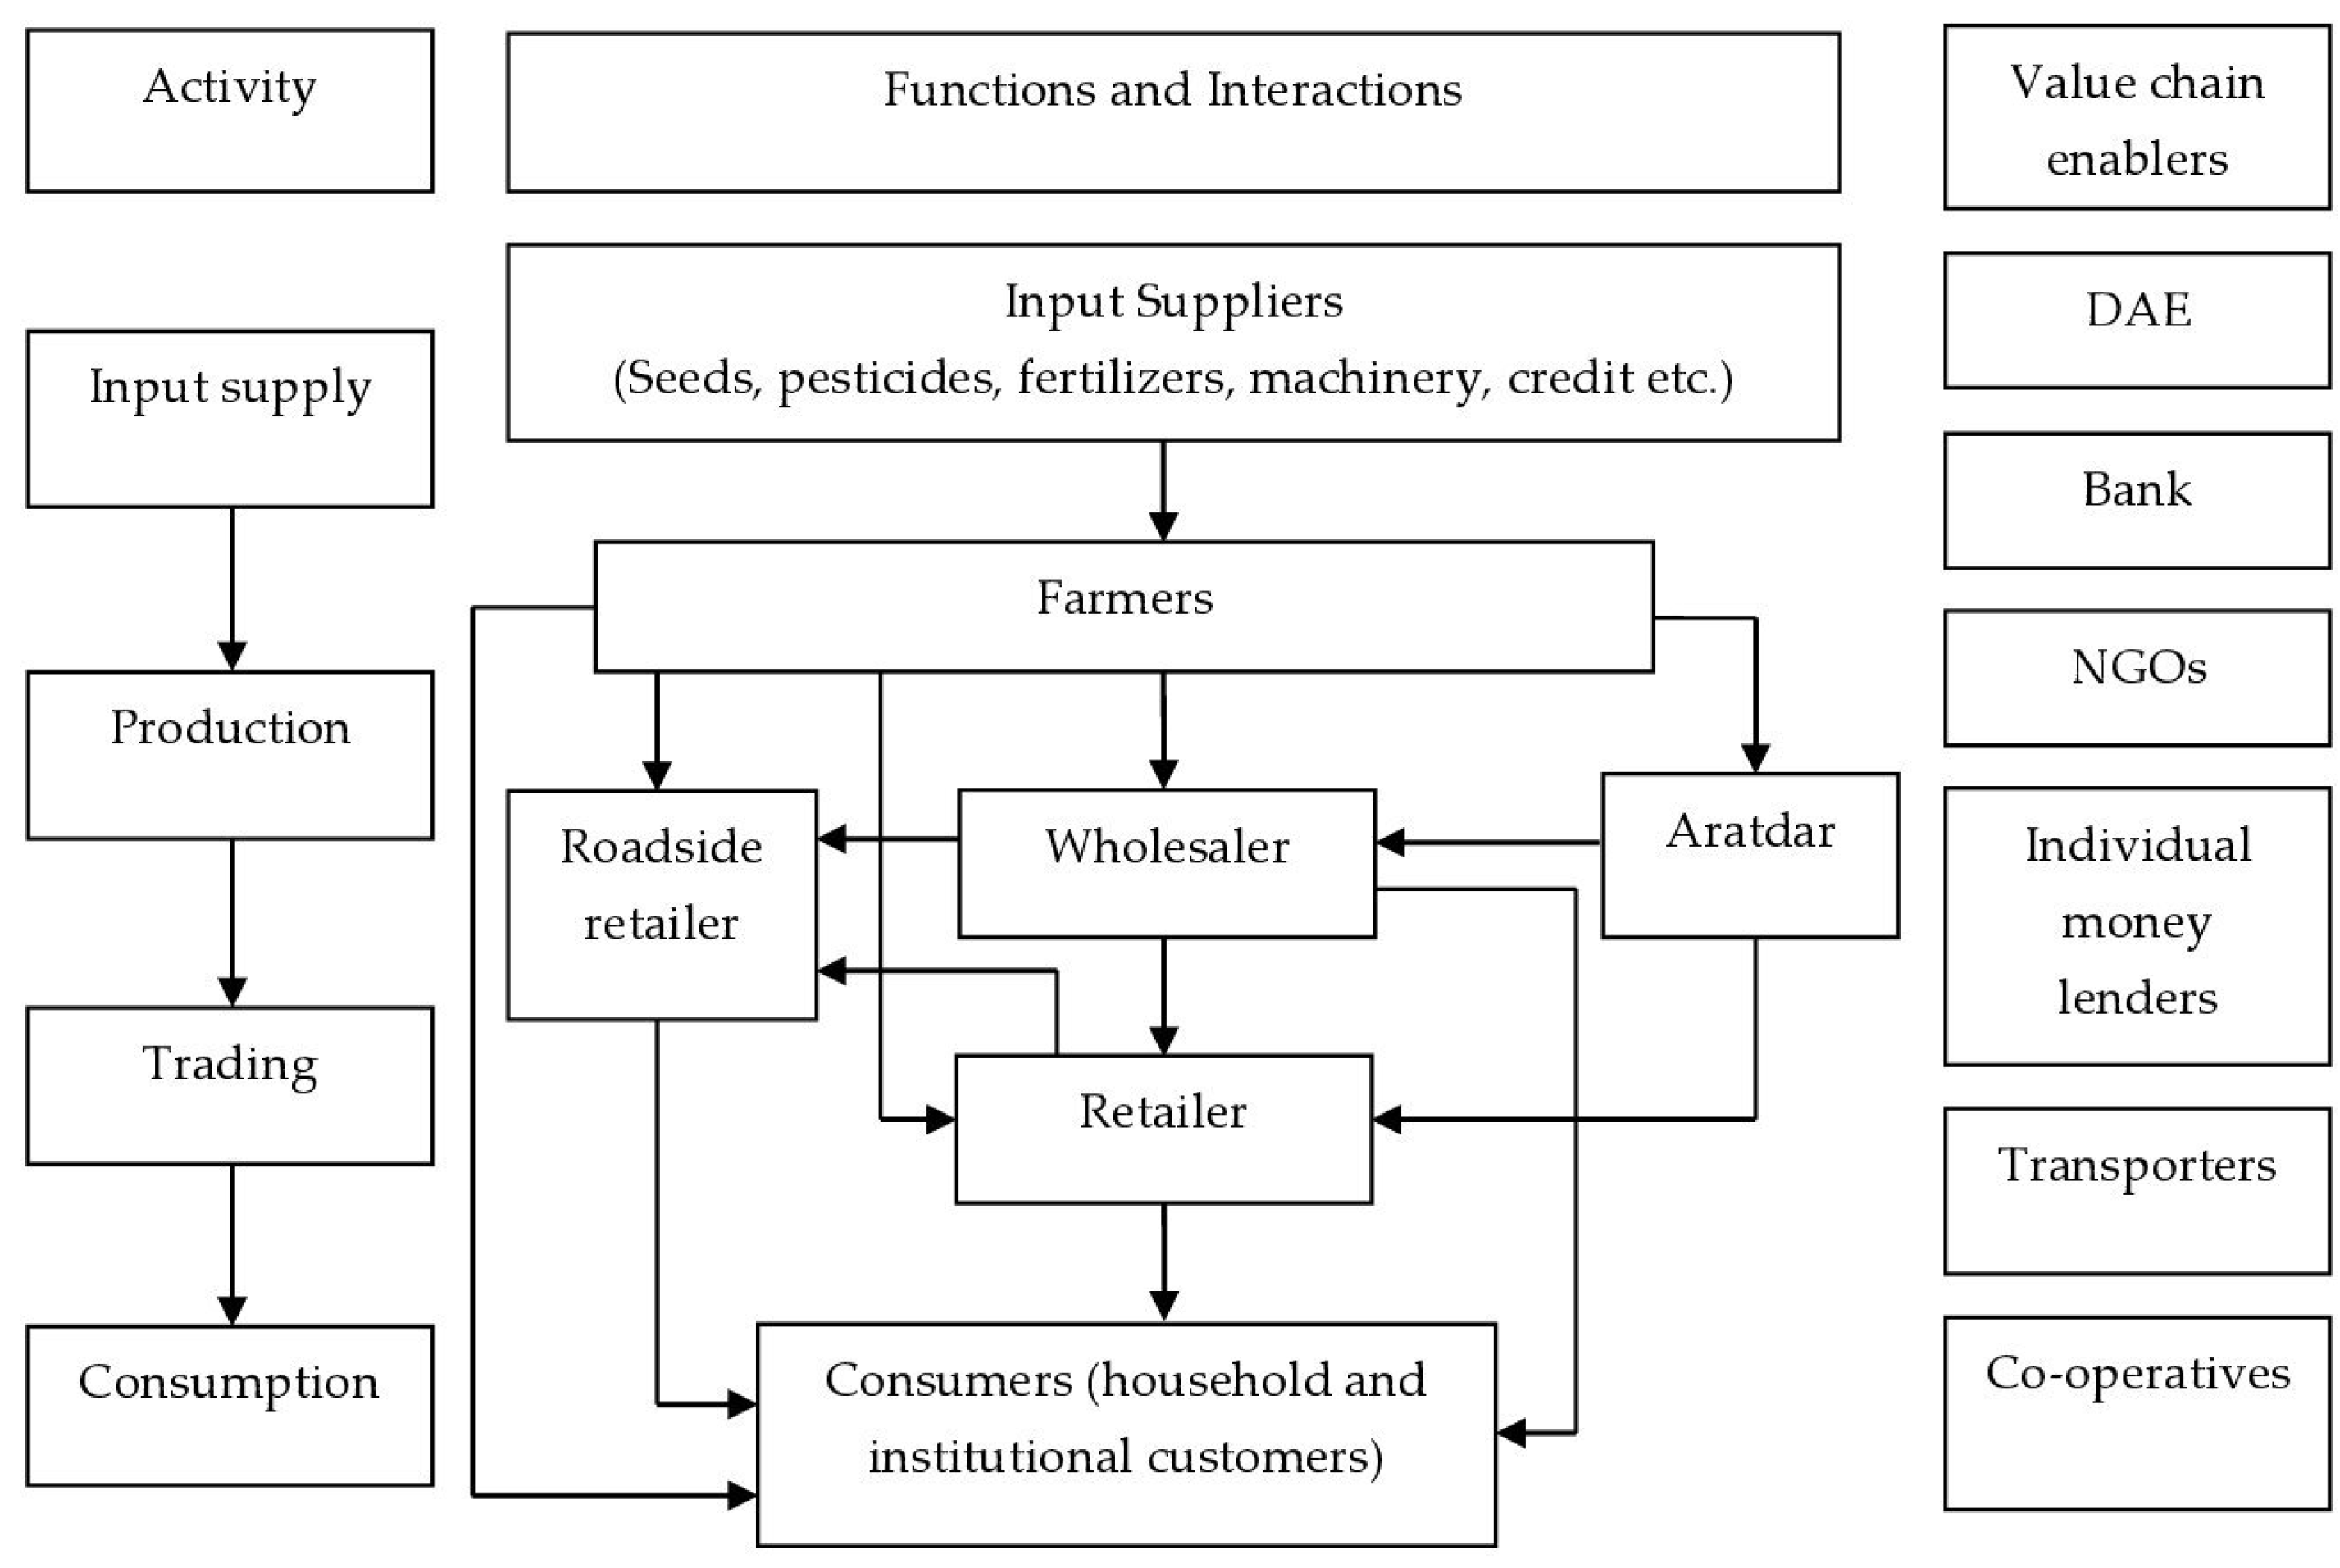
A value chain map depicts all of the components and the flow of products from raw materials to the end market, quantifies the activities that the product undergoes, and explains how the industry operates [57]. Instead of addressing the main issues as a group or location, it does it at the individual level of a supply chain [58]. The current value chain map of cauliflower and tomato is presented in Figure 1. The primary and supporting actors involved in the cauliflower and tomato value chain, its functions, as well as its linkages and relationships, are discussed.
Figure 1.
Value chain map of cauliflower and tomato.
4.2.1. Primary Actors
Input suppliers, farmers, wholesalers, Aratdars, retailers, and roadside retailers were identified as the primary actors along the value chain. Some functions were performed by more than one actor, while some actors performed more than one function.
Analyzing the value chain in agriculture starts with input supply level [42]. The manufacturers of the agricultural inputs such as seed, fertilizer, pesticides, insecticides, mulching sheets, farm implements, etc., are known as input suppliers. Agro-dealers, government distributors, primary cooperatives, small wholesalers, and even tiny retail establishments that sell modest amounts of seed, fertilizer, and pesticide to the farmers in villages are among the main actors participating in input supply networks. In the study area, private input suppliers were the main source of input supply.
Farmers constituted the primary link in the cauliflower and tomato value chain. They are in charge of converting raw supplies into output, which includes production for both domestic consumption and commercial purposes. Farmers choose which inputs to utilize, where to purchase them, when to plant and harvest them, and how much to sell, while taking into account the resources. Land preparation, planting, fertilizer application, irrigation, weeding, managing pests and diseases, harvesting, post-harvest handling, and marketing are some of the main value chain functions performed by cauliflower and tomato farmers. In the study area, vegetable producers normally sold their produce to wholesalers, retailers, roadside retailers, consumers, and most often they brought their produce to the Arat for selling. Thus, they formed a link or relationship in the chain.
Aratdars are authorized traders who, more particularly, act as commission agents for the stocking and selling of various agricultural goods. They look for buyers, negotiate appropriate prices, sell the vegetables, and collect money and hand it over to the farmers. For their services, they usually receive a commission and they have a fixed establishment in the market. In the study areas, it was seen that many beparis from outside the Sylhet and Moulvibazar districts usually send their vegetables to the Arat for sale. The farmers also brought their cauliflower and tomato to the Arat for selling. At this stage, competition was comparatively low, which resulted in the Aratdars receiving a high profit.
Wholesalers are the market participants who buy large quantities of vegetables from farmers or from commission agents and resell them to other traders and consumers. Most of them are independently organized and self-financed. Sometimes they form unofficial contracts with their buyers [42] and significantly influence local price formation. In Sylhet and Moulvibazar, wholesalers purchased cauliflower and tomato at the farm gate in a larger volume than any other actor did. Additionally, they purchased from cauliflower and tomato farmers through commission agents.
Retailers are the professional traders who sell small amounts of vegetables to consumers directly. Most of them are independently organized, with permanent shops in the market and labor for performing retailing activities. However, some of them have no permanent shops and they usually use open market places for selling their vegetables. They are in charge of purchasing vegetables, transporting them to retail establishments, and sorting, displaying, and selling them to consumers [59]. Retailers mostly buy from wholesalers, but in the study areas, they also purchased cauliflower and tomato from farmers as well as Aratdars, and finally sold them to households or institutional consumers.
Roadside retailers are the traders who usually perform the function of selling vegetables beside the road. They purchased cauliflower and tomato from farmers at the farm gate for the purpose of reselling to the consumers. Sometimes they collected vegetables from wholesalers. They have no permanent stores and usually deal with small quantities. However, some roadside retailers sold cauliflower and tomato by using a van instead of sitting in a single place beside the road.
Consumers are the final users and the most important actor in the cauliflower and tomato value chain. In the study area, consumers included domestic households/private consumers, hotels, and restaurants. Private consumers purchased cauliflower and tomato directly from the farmers, roadside retailers, retailers, and wholesalers. On the contrary, institutional consumers (hotels and restaurants) mainly purchased cauliflower and tomato from the wholesalers. However, they had their own standards for quality consideration like shape, color, size, weight, freshness, and smell, etc., while buying vegetables.
4.2.2. Supporting Actors
Supporting players of the value chain provide a variety of services to the chain actors, although they may not be directly involved in the value chain. They assist the chain stakeholders by providing knowledge, access to inputs, extension, training, market information, transportation, financial services, technical support, infrastructure development, standard maintenance, marketing, and advocacy, etc. Many institutions supported the cauliflower and tomato value chain in various ways. The Department of Agricultural Extension (DAE) is one of the principal actors that provides training and extension services to the cauliflower and tomato farmers. On average, the farmers were provided training nearly two times a year on improved production technologies, adopting improved varieties, obtaining inputs, applying fertilizer in the proper way, and increasing yield, etc. Also, the DAE performs field demonstrations of new and improved varieties and assists the farmers in informing market prices. Farmers under the National Agricultural Technology Project (NATP) received extension services, training, and relevant information on buyers and markets from the NATP. Both the government and private banks, as well as NGOs, have been identified as major sources of financial services. Among the farmers who borrowed money, about 69% farmers received their credit from both government and private banks, while the remaining 24% and 7% received credit from NGOs and individual lenders, respectively. However, traders obtained market information regarding the demand and supply of vegetables, prices, and competitors, etc., from the market and from other fellow traders. Both the farmers and traders incurred high costs when transporting their produce, usually by truck, van, and pickup. It is exigent to make these support activities frequent and timely in order to develop the cauliflower and tomato value chain.
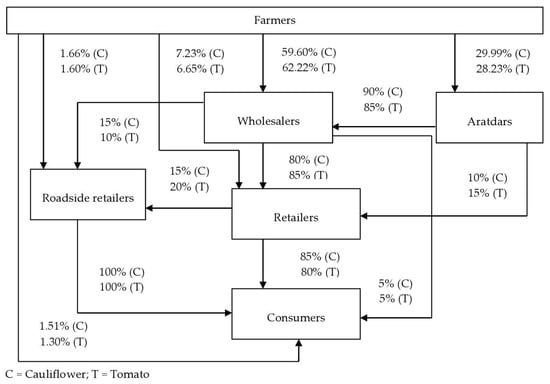
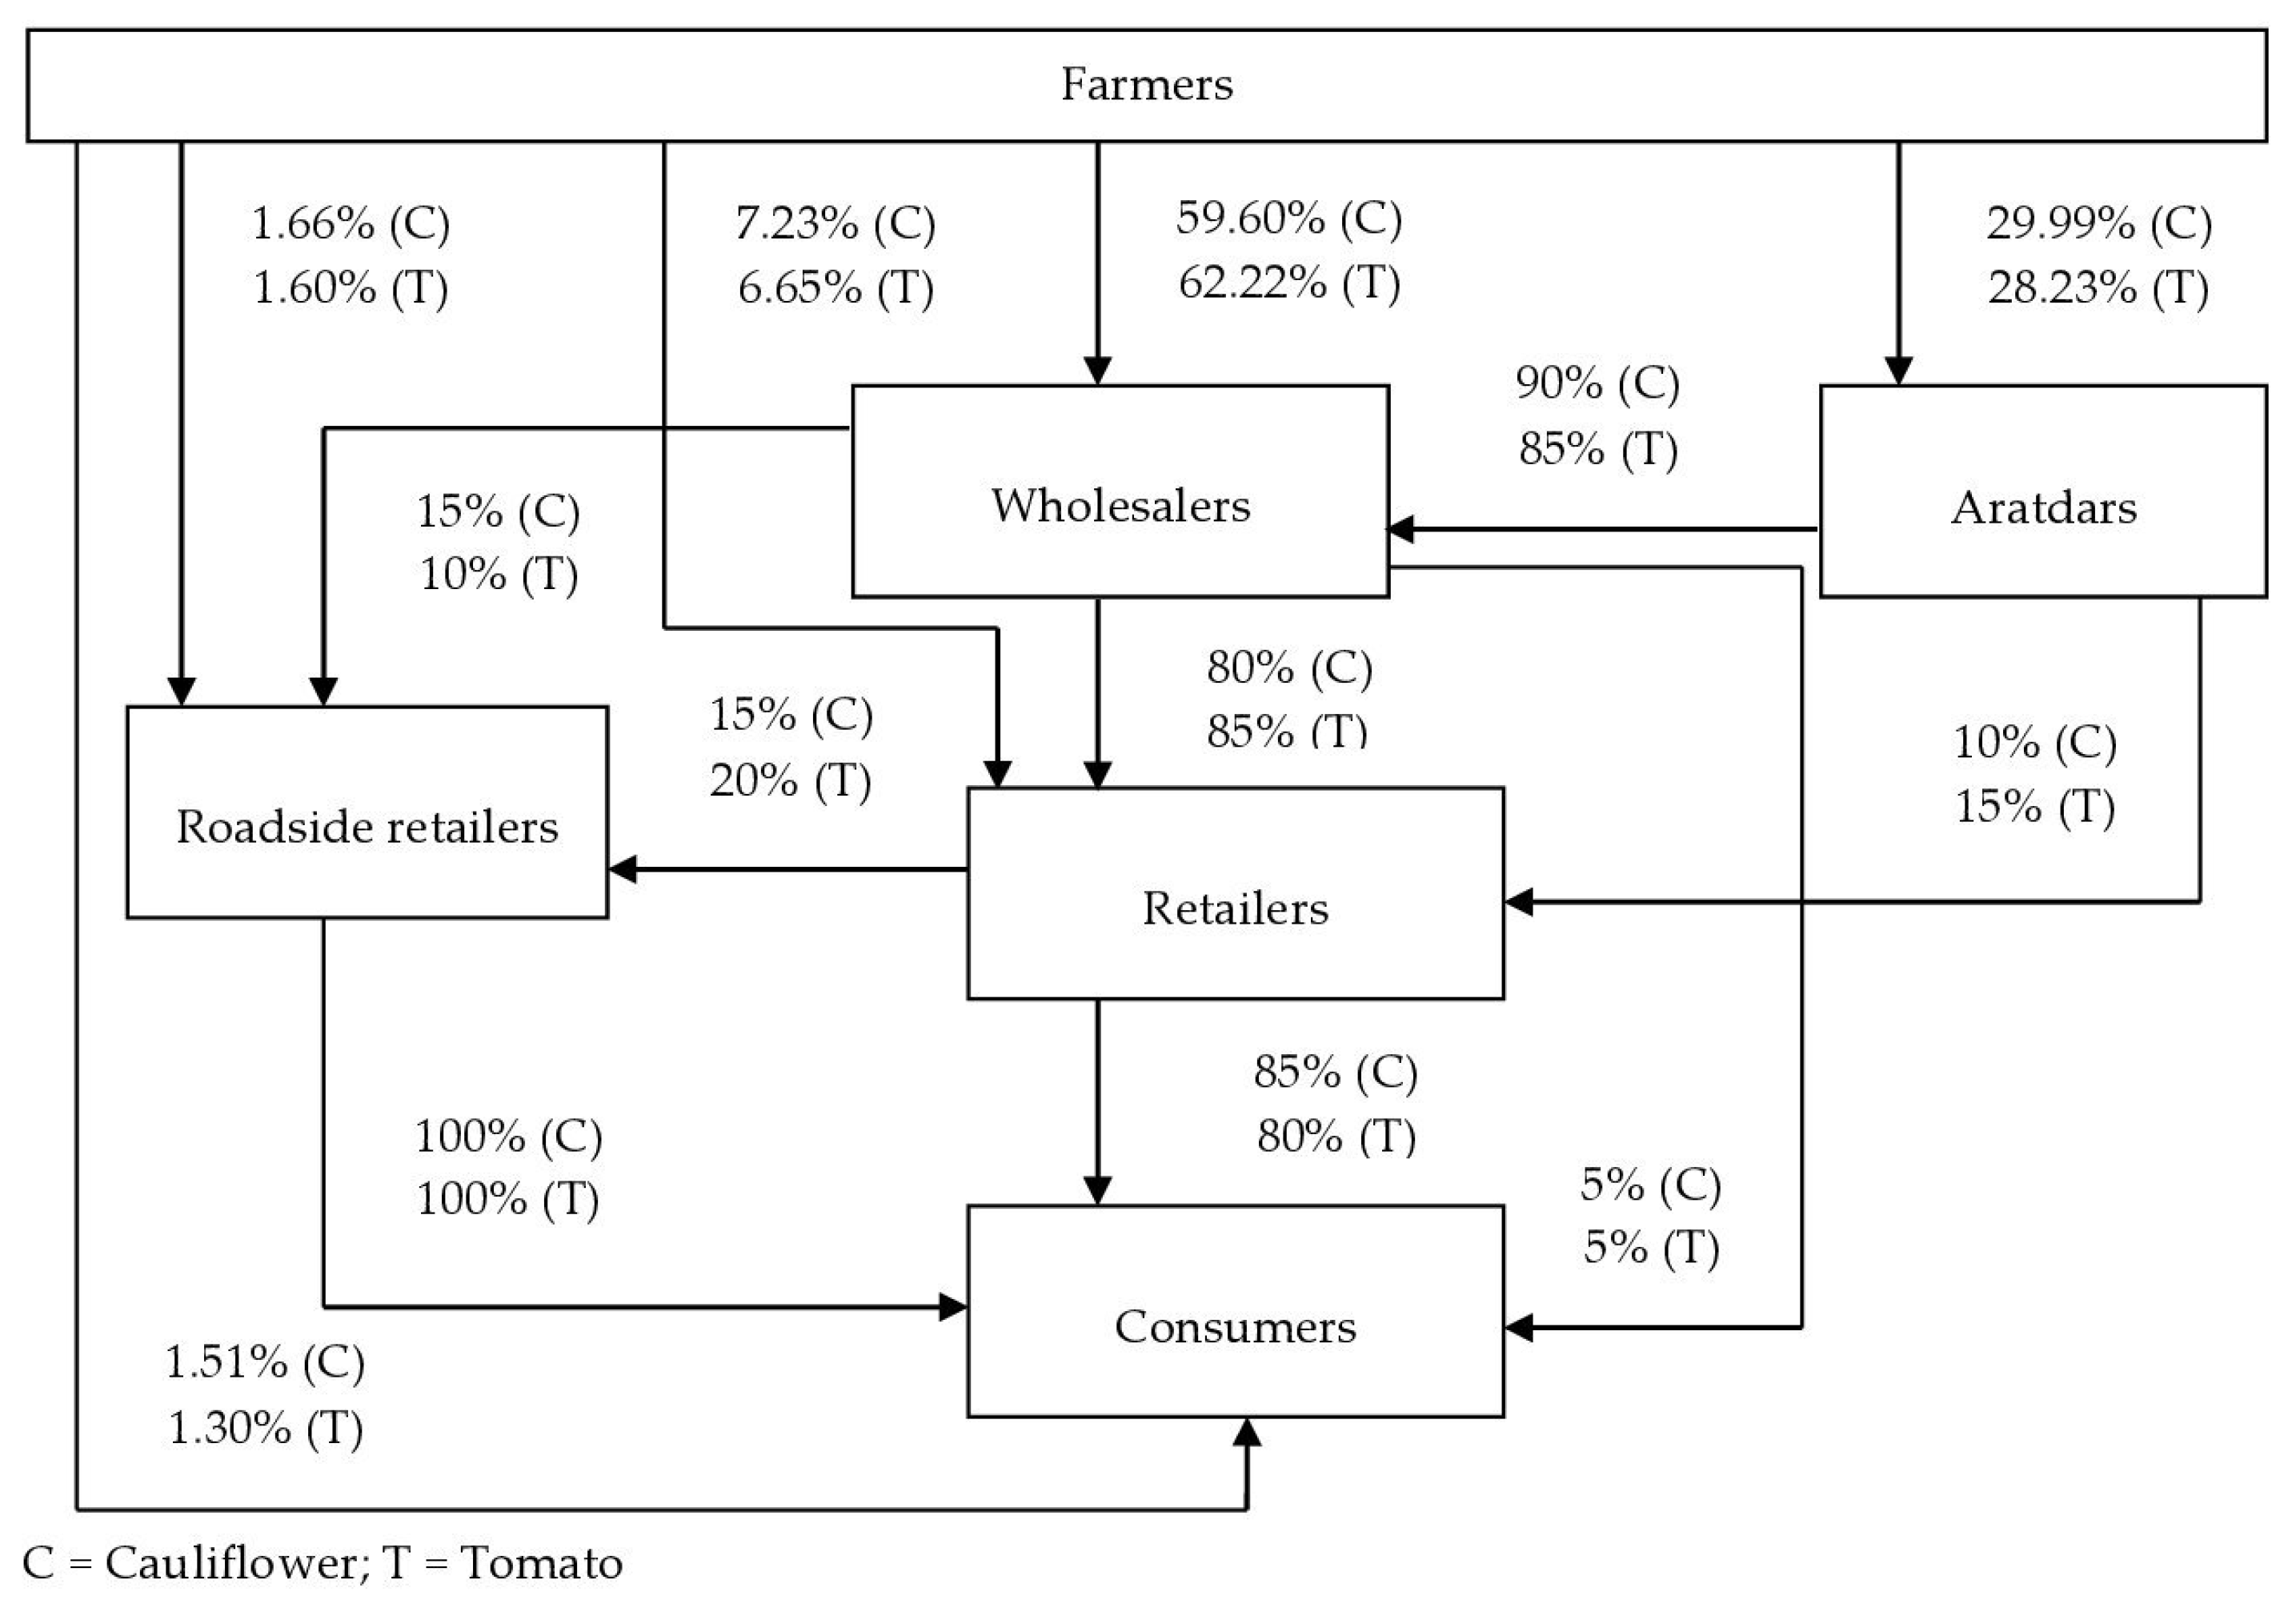
4.2.3. Marketing Channel of Cauliflower and Tomato
A marketing channel is a network of intermediaries that transports food grains from producers to final consumers [55]. Eleven alternative marketing channels were identified in cauliflower and tomato marketing.
- (a)
- Farmer → Consumer
- (b)
- Farmer → Wholesaler → Retailer → Consumer
- (c)
- Farmer → Wholesaler → Consumer
- (d)
- Farmer → Retailer → Consumer
- (e)
- Farmer → Roadside Retailer → Consumer
- (f)
- Farmer → Wholesaler → Roadside Retailer → Consumer
- (g)
- Farmer → Retailer → Roadside Retailer → Consumer
- (h)
- Farmer → Aratdar → Wholesaler → Retailer → Consumer
- (i)
- Farmer → Aratdar → Retailer → Consumer
- (j)
- Farmer → Aratdar → Wholesaler → Roadside Retailer → Consumer
- (k)
- Farmer → Aratdar → Retailer → Roadside Retailer → Consumer
Out of the total quantity, growers sold a maximum amount of cauliflower (59.60%) and tomato (62.22%) through wholesalers. However, the smallest volume of cauliflower (1.51%) and tomato (1.30%) were accounted for through directly marketing to consumers (Figure 2).
Figure 2.
Cauliflower and tomato marketing channel.
4.3. Cost and Margin Analysis of the Farmers
Cost acts as a major consideration in the farmers’ decision-making process. Farmers have to incur both production and marketing cost for cultivating and selling their produce. Production costs include both variable costs and fixed costs. Marketing costs denote the cost of those business activities required for various marketing functions.
On average, the total production costs of cauliflower and tomato were Tk. 257,694.26/ha and Tk. 260,671.93/ha, for which the total fixed costs were Tk. 43,137.43/ha and Tk. 43,525.82/ha, and the total variable costs were Tk. 214,556.83/ha and Tk. 217,146.11/ha, respectively (Table 3). Human labor costs accounted for the largest share of total production costs, which were about 46.25% and 46.05%, respectively, for cauliflower and tomato. Cauliflower and tomato farmers spent 44.56% and 43.58% of total marketing costs on commission charge, while they had to bear approximately 17% and 19% of total marketing costs due to wastage losses.
Table 3.
Production and marketing costs of cauliflower and tomato farmers.
About 17.45% and 17.60% of the total marketing costs of cauliflower and tomato were accounted for through transportation costs. The average yield per hectare of cauliflower and tomato were 15,822.432 kg and 15,688.05 kg, whereas their average sale price was Tk. 27.99/kg and Tk. 27.50/kg, respectively. It was evident that the per hectare net return of cauliflower and tomato farmers was Tk. 103,213.99 and Tk. 85,537.48. The BCR was found to be 1.30 and 1.25, respectively, for cauliflower and tomato (Table 4).
Table 4.
Gross margin and net return of cauliflower and tomato farmers.
4.4. Value Addition of the Different Market Actors of Cauliflower and Tomato
Both the Aratdars and the retailers spent the maximum of their marketing costs on shop rent, which was 45.18% and 31.56% for cauliflower as well as 41.55% and 33.98% for tomato, respectively (Table 5). About 47.08% and 41.25% of the wholesaler’s total marketing costs for cauliflower and tomato were spent on transportation costs. Wastage was the highest cost for cauliflower (43.13%) and tomato (30.76%) marketing for roadside retailers (Table 5). Rahman et al. [34] reported that transportation and wastage were the highest marketing costs for paiker-cum-retailers and retailers. Aratdar had no buying and selling function and therefore the average received commission was considered as their gross marketing margin. They contributed about 10.04% and 10.07% to the total value addition. Among all the traders, retailers incurred the highest marketing costs which were 48.44% and 53.71% of the total marketing costs, respectively, for cauliflower and tomato (Table 6). Wholesalers added the highest value of the total gross marketing margin, accounting for 32.28% for cauliflower and 31.96% for tomato (Table 6). Total net marketing margin was found to cost Tk. 849.18 and Tk. 1183.20, respectively, per hundred kg of cauliflower and tomato, in which wholesalers gained the highest share of 57.41% and 48.09%. Even though the wholesalers captured the largest share of the gross marketing margin and net marketing margin, Aratdars achieved the highest return on investment, which was 18.37% and 110.66% for cauliflower and tomato, respectively (Table 6). The findings are also consistent with Rahman et al. [34].
Table 5.
Marketing cost of traders in the cauliflower and tomato value chain (Tk./quintal).
Table 6.
Value addition, marketing cost, and net marketing margin of traders (Tk./quintal).
4.5. Governance Structure Followed by the Farmers
Gereffi [60] (1995) identified the governance as the authority and power relationships between firms that determine the allocation of material, financial, and human resources within a chain. By exploring the structure of the relationships among the stakeholders, it aims to improve the chain’s efficiency, which can aid in assessing the advantages and disadvantages of the rules for different groups. A particular chain actor can influence the activities of other actors through this governance mechanism [28,61]. Communications, collaboration, information transmission, and market power distribution are the central issues of value chain governance. Apart from transactional traits and institutional context, it is equally important to consider the governance structure as being exercised both internally and externally to the chain. Considering the internal and external issues of the chain, the practice of internal as well as external value chain governance may occur. Internal or formal governance refers to the buyer’s demand from producers and exporters for quality standards and safe food, whereas external or informal governance denotes the rules and regulations that govern social and business norms, buyer–seller relationships, political issues, and so on [62]. Each actor in the cauliflower and tomato value chain has to maintain or perform some standard governance issues as part of their value addition. But, important research questions how farmers perceive various issues related to the existence of good internal and external governance structures. Table 7 shows that the ‘agree’ category received the highest percentage of perception for the ‘quality enhancement of vegetables’ (44.23%), ‘safe production process’ (55.77%), ‘swift delivery of vegetables’ (69.24%), and ‘set reasonable prices and provide discounts’ (38.46%) indicators of internal governance from NATP farmers. The farmers tried to charge rational prices for their produce, but seldom offered price discounts to the customers.
Table 7.
Testing of NATP farmers’ perceptions for internal and external governance.
In total, 55.77% of NATP farmers strongly reported that customers did not reject their vegetables owing to quality assurance, but the majority of them (44.23%) remained neutral in the context of accepting the customer’s feedback for product development. A total of 42.31% of farmers did not receive fair market prices, whereas only 9.62% of NATP farmers participated in contract selling. In case of external governance structure, most of the NATP farmers disagreed with ‘technical support from Department of Agricultural Extension’ (44.23%), ‘get high quality inputs’ (48.08%), ‘frequent inspection and assessment by the government authority’ (36.54%), and ‘adequate storage facilities’ (38.46%). The existence of good external governance practices was identified in terms of ‘access to sufficient market information’, ‘infrastructures for local marketing’, ‘favorable laws and rules’, and ‘rapport between buyers and sellers.
Table 8.
Testing of non-NATP farmers’ perception for internal and external governance.
Table 8 shows that, in the context of internal governance, non-NATP farmers exhibited the highest percentage of perception for the ‘agree’ category for ‘quality enhancement of the vegetables’ (45.83%), ‘safe production process’ (56.25%), and ‘set reasonable prices and provide discounts’ (50%). They were able to quickly market their vegetables. The majority of the non-NATP farmers (60.42%) were in strong agreement against the customer’s rejection of vegetables, but 18.75% of them reported that the customers turned down vegetables due to quality concern. They hardly maintained the market feedback mechanism and most of them did not participate in any contractual selling arrangements. As usual, 54.17% of them affirmed the unfair market prices for their vegetables. For the external governance structure, non-NATP farmers gave the highest percentage for the ‘disagree’ category for ‘technical support from DAE’ (37.5%), ‘access to sufficient market information’ (33.33%), ‘regular inspection and assessment by the government authority’ (54.17%), and ‘adequate storage facilities’ (45.83%). While most of the responses were in favor of local marketing facilities, some non-NATP farmers spoke about the absence of proper selling places. No unfavorable rules and regulations were identified, whereas 25% farmers revealed hostile relationships among the actors.
Comparison between NATP and Non-NATP Farmers in the Context of the Governance Structure
Immediately after arranging the total score of each farmer for all statements in descending order, the top 25% and bottom 25% were selected for the calculation of discriminative power. The statement with the largest DP value indicates the best discrimination among the farmers’ attitudes regarding the practice of good governance structure. Table 9 reveals that NATP farmers showed less variation for all the statements of internal governance except ‘setting reasonable prices and provide discounts’ (1.77) and ‘considering the customer’s feedback for product improvement’ (1.62). The farmers under the NATP form a ‘common interest group’ (CIG) of 20 members and they usually remain under a formal procedure where they are provided training with improved farming practices. Therefore, they did not use excess fertilizer and insecticide on their own assumptions and tried to improve the quality of vegetables by maintaining a safe cultivation process. However, they tried to improve their produce by taking advice from the NATP authority or simply from their own farming experiences, instead of only considering customer feedback. Similarly, the non-NATP farmers rarely thought of product improvement by only applying the market feedback mechanism. Except for the statement of ‘obtaining the fair price of vegetables’ (1.66), non-NATP farmers showed less discrimination towards other statements of internal governance. The majority of both NATP and non-NATP farmers were not attached to contract selling, but it might be beneficial for them due to the perishable nature of the produce and the absence of local storing facilities. The highest variation among the NATP farmers on the existence of good external governance practices was recorded via the DP values for ‘technical support from Department of Agricultural Extension’ (2.31), ‘get high quality inputs’ (1.62), and ‘inspection and assessment by the government authority’ (1.62). Since the NATP farmers have opportunities to receive training on farming methods, field demonstration, input subsidy, technical assistance for mechanization, and knowledge sharing among the members of the CIG, their attitude towards good external governance structure needs to be more positive. However, this may be possible when the DAE, NATP, or concerned authority provides adequate support on a frequent basis. On the contrary, non-NATP farmers should also be provided with regular support from the DAE, as they displayed the highest variation towards DAE functions (2.33). They showed greater discrimination in accessing market information (1.58). Arranging the dissemination of market information to the farmers of both categories can be an excellent way to improve the external governance structure.
Table 9.
Computation of discriminative power.
Both groups of farmers were identified as exposing more or less differed attitudes towards the existence of good internal and external governance structures in the value chain. This is also evident from the Mann–Whitney U test statistics (Table 10). Therefore, the following null hypotheses were proposed. H0: Perceptions of NATP farmers towards the presence of good internal and external governance structures were not identical, and H0: Perceptions of non-NATP farmers towards the presence of good internal and external governance structures were not identical.
Table 10.
Wilcoxon–Mann–Whitney U test statistics for several statements on internal and external governance structures.
The NATP farmers of the Sylhet and Moulvibazar districts disclosed diverse attitudes concerning several statements of both internal and external governance structures, except for ‘quality enhancement of the vegetables’, ‘safe production process’, ‘sufficient infrastructures for local marketing’, ‘adequate storage facilities’, and ‘favorable laws and rules’. However, the corresponding DP values of the above-mentioned five statements also reveal the farmers’ lower variation in attitudes towards these. Similarly, non-NATP farmers of two districts differed from each other owing to expressing different attitudes toward various statements of both internal and external governance structures. They were identical only in attitudes relating to ‘access to sufficient market information’ and ‘sufficient infrastructures for local marketing’, which is somewhat compatible with the DP findings.
5. Conclusions
In the current era of globalization, the potential of agro-industries is being emphasized to develop sustainable agricultural value chains which will help businesses to gain a more advantageous position in the market. It can be seen as a way to assess the value-adding activities and determine which ones should be improved. In addition to various supporting actors, input suppliers, farmers, Aratdars, wholesalers, retailers, roadside retailers, and consumers were identified as major primary actors in the cauliflower and tomato value chain. Eleven alternative marketing channels were observed, where only 1.51% of cauliflower and 1.30% of tomato were sold directly to final consumers. The farmers sold the highest percentage of cauliflower (59.60%) and tomato (62.22%) through wholesalers. The BCR of cauliflower and tomato was found to be 1.30 and 1.25, respectively. This study showed that wholesalers added the highest value to the total gross and net marketing margins. Differences were identified between NATP and non-NATP farmers regarding their attitudes towards internal and external governance structures. Since the NATP farmers belong to a systematic arrangement, it was assumed that they practiced good internal governance structures and at the same time have positive perceptions of good external governance practices. But in reality, this seems not to be happening. Even though both groups spoke of good internal governance practices from their own point of view, they complained about unfair market prices. There was no proper functioning of contractual selling, which could be an effective means for farmers in areas lacking storage facilities for perishable produce. Both categories of farmers rarely considered applying the market feedback mechanism for the improvement of their cultivated vegetables. NATP farmers displayed negative perceptions for the existence of good external governance practices, particularly in the contexts of ‘regular technical support’, ‘access to quality inputs’, ‘frequent inspection and assessment’, and ‘storage facilities’. Non-NATP farmers also reported in similar ways on the existence of good external governance structures. However, they were not faced with any adverse trading rules and modest relationships existed among them. A good governance structure strengthens the position of smallholder farmers in the chain, and therefore it is important to improve governance practices internally and externally. Through the formation of a common interest group, NATP farmers usually received opportunities to share knowledge, skills, and opinions in various meetings and training programs which motivated them to be well-organized for improving their negotiation power. On the other hand, non-NATP farmers did not received such opportunities, which forced them to operate in a fragile system with dependence on other actors. Regardless of whether or not the farmers were involved in the NATP, they did not actually govern the chain. The governance practice of all other actors in the value chain should be uplifted. Farmers should be motivated to grow high-value crops through improved farming methods under adequate support and intensive supervision. Initiatives for information dissemination and local storing facilities should be adopted. Alongside this, the whole institutional and transactional environment should flourish where all stakeholders can add value through the effective accomplishments of their respective tasks.
6. Problems and Limitations of the Study
The researchers faced difficulties in reaching the NATP farmers and in acquiring their responses on good governance structures. In fact, the NATP farmers were afraid to express their views on the CIG and NATP. After explaining the research purposes, they finally agreed to share their opinions with us. Due to time and budget constraints, this study was conducted in limited geographical areas. Conducting this study in larger geographical areas is needed to obtain more representative results, understand the actual field situations, and formulate appropriate policies for improvement. However, to achieve this, the present study can be used as a reference.
Author Contributions
Conceptualization, D.S.; Methodology, D.S., M.J.A., I.A.B., S.D. and A.M.M.; Validation, M.J.A., S.D. and A.M.M.; Formal analysis, D.S.; Data curation, D.S. and A.M.M.; Writing—original draft, D.S.; Writing—review & editing, M.J.A., I.A.B., S.D. and A.M.M.; Supervision, M.J.A. and I.A.B. All authors have read and agreed to the published version of the manuscript.
Funding
The first author received the National Science and Technology (NST) from the Ministry of Science and Technology, GoB for conducting this study. The APC was funded by the University of Arkansas, Fayetteville.
Institutional Review Board Statement
No formal institutional review was required for this study which was derived from first author`s Master thesis. The Department of Agribusiness and Marketing, Bangladesh Agricultural University approved the study design.
Informed Consent Statement
Verbal and written informed consent was taken from the study respondents during field work.
Data Availability Statement
Data is available upon request.
Conflicts of Interest
The authors of this manuscript declare no conflicts of interest.
References
- Bangladesh Bureau of Statistics. Population and Housing Census; Ministry of Planning, Government of the People’s Republic of Bangladesh: Dhaka, Bangladesh, 2022. [Google Scholar]
- Rayhan, S.J.; Islam, M.J.; Kazal, M.M.H.; Kamruzzaman, M. Value Chain Analysis of Brinjal in the Chittagong Hill Tracts of Bangladesh. Asian J. Agric. Ext. Econ. Sociol. 2021, 39, 145–157. [Google Scholar] [CrossRef] [Scilit]
- Islam, M.S.; Nayeem, A.R.; Huda, S.N. An Economic Analysis of Cauliflower Production in Selected Areas of Mymensingh District of Bangladesh. ICRRD High Index Res. J. 2020, 29, 1–10. [Google Scholar]
- Islam, M.W.; Hassan, M.M.; Resmi, S.I.; Rahman, M. Value Addition of Onion Markets of Pabna District in Bangladesh. Res. Bus. Manag. 2019, 6, 1–18. [Google Scholar] [CrossRef] [Scilit]
- Mitra, S.; Yunus, M. Determinants of tomato farmer’s efficiency in Mymensingh district of Bangladesh: Data Envelopment Analysis approach. J. Bangladesh Agric. Univ. 2018, 16, 93–97. [Google Scholar] [CrossRef] [Scilit]
- Doss, C.R.; Raney, T.L. The Role of Women in Agriculture; Working Paper No. 11-02; Agricultural Development Economics Division, Food and Agricultural Organization of the United Nations: Quebec City, QC, USA, 2011. [Google Scholar]
- Bangladesh Bank, Bangladesh Economic Review; Finance Division, Ministry of Finance, Government of the People’s Republic of Bangladesh: Dhaka, Bangladesh, 2022.
- Kamurzzaman, M.; Takeya, H. Importance, Structural Change and Factors Affecting Production of Vegetables in Bangladesh. Int. J. Agric. Res. 2008, 3, 397–406. [Google Scholar] [CrossRef] [Scilit]
- Wondim, D. Value chain analysis of vegetables (onion, tomato, potato) in Ethiopia: A review. Int. J. Agric. Sci. Food Technol. 2021, 7, 108–113. [Google Scholar]
- Emana, B.; Afari-Sefa, V.; Dinssa, F.F.; Ayana, A.; Balemi, T.; Temesgen, M. Characterization and Assessment of Vegetable Production and Marketing Systems in the Humid Tropics of Ethiopia. Q. J. Int. Agric. 2015, 54, 163–187. [Google Scholar]
- Emana, B.; Gebremedhin, H. Constraints and Opportunities of Horticulture Production and Marketing in Eastern Ethiopia; DCG Report No. 46; DCG: Stanford, CT, USA, 2007. [Google Scholar]
- Karim, M.R.; Hossain, S.; Rashid, M.A.; Azad, M.A.K.; Jahan, M.A.H.S. Comparative advantage of vegetables production in Bangladesh. Bangladesh J. Agric. Res. 2011, 36, 87–95. [Google Scholar] [CrossRef] [Scilit]
- Khatun, F.; Jahan, M.; Hossain, S. Evaluating the Production and Marketing Assessment of Selected Vegetables in Bangladesh. Am. J. Agric. Biol. Sci. 2022, 17, 23–33. [Google Scholar] [CrossRef] [Scilit]
- Ibeawuchi, I.I.; Okoli, N.A.; Alagba, R.A.; Ofor, M.D.; Emma-okafor, L.C.; Peter-onoh, C.A.; Obiefuna, J.C. Fruit and Vegetable Crop Production in Nigeria: The Gains, Challenges and the Way Forward. J. Biol. Agric. Healthc. 2015, 5, 194–200. [Google Scholar]
- Ahmad, R. Vegetable output grows fast. In The Daily Star; Dhaka, Bangladesh. 2017; Available online: https://www.thedailystar.net/frontpage/veg-output-grows-fast-1343068 (accessed on 16 July 2023).
- Sharmin, S.; Mitra, S.; Rashid, M.H.A. Production, yield and area growth of major winter vegetables of Bangladesh. J. Bangladesh Agric. Univ. 2018, 16, 492–502. [Google Scholar] [CrossRef] [Scilit]
- Bangladesh Bureau of Statistics. Yearbook of Agricultural Statistics; Ministry of Planning, Government of the People’s Republic of Bangladesh: Dhaka, Bangladesh, 2019. [Google Scholar]
- Heinze, A.S. Value Links Manual: The Methodology of Value Chain Promotion, 1st ed.; German Technical Cooperation Agency (GTZ): Eschborn, Germany, 2007. [Google Scholar]
- Kaplinsky, R.; Morris, M. A Handbook for Value Chain Research; International Development Research Centre: Ottawa, ON, Canada, 2001; pp. 4–74. [Google Scholar]
- Barnes, M. Value Chain Guide Book: A Process for Value Chain Development; Agriculture and Food Council of Alberta, Value Chain Initiative: Nisku, AB, Canada, 2004; pp. 1–82. [Google Scholar]
- Hailu, A. Value Chain Analysis of Vegetables: The Case of Ejere District, West Shoa Zone, Oromia National Regional State of Ethiopia. Master’s Thesis, School of Agricultural Economics and Agribusiness, Haramaya University, Haramaya, Ethiopia, 2016. [Google Scholar]
- Herr, M.L.; Muzira, T.J. Value Chain Development for Decent Work: A Guide for Development Practitioners, Government and Private Sector Initiatives, 1st ed.; International Labour Office: Geneva, Switzerland, 2009; pp. 44–217. [Google Scholar]
- Porter, M.E. Competitive Advantage: Creating and Sustaining Superior Performance, 1st ed.; The Free Press: New York, NY, USA, 1985. [Google Scholar]
- Devaux, A.; Torero, M.; Donovan, J.; Horton, D. Agricultural innovation and inclusive value-chain development: A review. J. Agribus. Dev. Emerg. Econ. 2018, 8, 99–123. [Google Scholar] [CrossRef] [Scilit]
- Nang’ole, E.; Mithofer, D.; Franzel, S. Review of Guidelines and Manuals for Value Chain Analysis for Agricultural and Forest Products; ICRAF Occasional Paper No. 17; World Agroforestry Centre: Nairobi, Kenya, 2011. [Google Scholar]
- Moniruzzaman, S.M. Value Chain Analysis of Jute in Bangladesh. Ph.D. Thesis, Department of Agribusiness and Marketing, Bangladesh Agricultural University, Mymensingh, Bangladesh, 2019. [Google Scholar]
- Demont, M.; Ndour, M. Upgrading rice value chains: Experimental evidence from 11 African markets. Glob. Food Secur. 2015, 5, 70–76. [Google Scholar] [CrossRef] [Scilit]
- Schiffer, E.; Hartwich, F.; Monge, M. Who Has Influence in Multistakeholder Governance Systems? Using the Net-Map Method to Analyze Social Networking in Watershed Management in Northern Ghana; IFPRI Discussion Paper 00964; IFPRI: Washington, DC, USA, 2010. [Google Scholar]
- Marshall, E.; Schreckenberg, K.; Newton, A.C. Commercialization of Non-Timber Forest Products: Factors Influencing Success: Lessons Learned from Mexico and Bolivia and Policy Implications for Decision-Makers (No 23); UNEP, World Conservation and Monitoring Centre: Cambridge, UK, 2006. [Google Scholar]
- Mwadjuma, M. Analysis of Tomato Value Chain in Rugombo District, Burundi. Master’s Thesis, Sokoine University of Agriculture, Morogoro, Tanzania, 2019. [Google Scholar]
- Onyangore, C. Developing Sustainable Fresh Produce Agriculture Value Chains: Case Study of African Indigenous Vegetables (AIVs) Value Chain in Uasin Gishu County, Kenya. COVID-19, Supply Chain, Climate Change, and Sustainable Development in Africa. In International Conference on Current Business Issues in African Countries; Carter, S.D., Ed.; Springer Proceedings in Business and Economics; Springer: Cham, Switzerland; pp. 23–41.
- Sharma, D.; Alam, M.J.; Begum, I.A.; McKenzie, A.M. Factors affecting the choice of governance structure along the vegetable value chain in Bangladesh. Int. Food Agribus. Manag. Rev. 2023, 26, 25–48. [Google Scholar] [CrossRef] [Scilit]
- Koirala, S.; Dhakal, S.C.; Shrestha, K.; Khanal, S.; Thapa, S. Value Chain Analysis of Tomato (Solanumly copersicum L.) in Lalitpur, Nepal. Econ. Aff. 2022, 67, 49–58. [Google Scholar]
- Rahman, M.M.; Barua, S.; Zhou, D.; Li, T.; Farid, M.S. Analyzing the value chain for vegetables in the North-Eastern part of Bangladesh. Cogent Bus. Manag. 2022, 9, 2135222. [Google Scholar] [CrossRef] [Scilit]
- Samoggia, A.; Monticone, F.; Esposito, G. Governance in the Italian Processed Tomato Value Chain: The Case for an Interbranch Organisation. Sustainability 2022, 14, 2749. [Google Scholar] [CrossRef] [Scilit]
- Wosene, G.; Gobie, W. Value chain analysis of tomato: The case of Bure, Jabitehinan and North Mecha districts of Amhara regional state, Ethiopia. J. Agric. Food Res. 2022, 7, 100272. [Google Scholar] [CrossRef] [Scilit]
- Branca, G.; Cacchiarelli, L.; D’Amico, V.; Dakishoni, L.; Lupafya, E.; Magalasi, M.; Perelli, C.; Sorrentino, A. Cereal-Legume Value Chain Analysis: A Case of Smallholder Production in Selected Areas of Malawi. Agriculture 2021, 11, 1217. [Google Scholar] [CrossRef] [Scilit]
- Poudel, K.; Pokharel, S.; Suraj, K.; Adhikari, S. Analysis of supply chain of cauliflower in Tanahun, Nepal. Acad. J. Agric. Res. 2020, 7, 295–306. [Google Scholar]
- Wiryawan, F.S.; Marimin; Djatna, T. Value chain and sustainability analysis of fresh-cut vegetable: A case study at SSS Co. J. Clean. Prod. 2020, 260, 121039. [Google Scholar] [CrossRef] [Scilit]
- Sarma, P.K.; Ali, M.H. Value Chain Analysis of Tomato: A Case Study in Jessore District of Bangladesh. Int. J. Sci. Res. 2019, 8, 924–932. [Google Scholar]
- AbdElrazig, H.E.; Musa, M.I.; Elsheikh, S.E. Value Chain Analysis for Tomato Production and Marketing in Khartoum State, Sudan. Curr. Investig. Agric. Curr. Res. 2018, 5, 715–721. [Google Scholar]
- Biftu, A.B.; Gemechu, A.; Biswas, P. Value Chain Analysis of Vegetables in Yayu and Hurumu District of Iluababor Zone, Ethiopia. J. Bus. Manag. Soc. Sci. Res. 2018, 6, 156–178. [Google Scholar]
- Islam, M.M.; Noor, T.R. Economics of Selected Winter Vegetables ie Bean and Cauliflower: A Study in Rural Bangladesh. Sch. J. Econ. Bus. Manag. 2018, 5, 306–314. [Google Scholar]
- Neupane, H.; Poudel, P.; Parajuli, S. Value Chain Analysis of Tomato in Chitwan District of Nepal. Acta Sci. Agric. 2018, 2, 113–116. [Google Scholar]
- Enoch, K. Value Chain Analysis of Tomato in the Kpone-Katamanso District of Ghana. Master’s Thesis, Department of Agricultural Economics and Agribusiness, College of Basic and Applied Sciences, University of Ghana, Accra, Ghana, 2017. [Google Scholar]
- National Horticultural Research and Development Foundation. Value Chain Study of Tomato of Karnal, Haryana; National Horticultural Research and Development Foundation: Delhi, India, 2017; pp. 1–40. [Google Scholar]
- Chagomoka, T.; Afari-Sefa, V.; Pitoro, R. Value Chain Analysis of Traditional Vegetables from Malawi and Mozambique. Int. Food Agribus. Manag. Rev. 2014, 14, 59–86. [Google Scholar]
- Hoq, M.S.; Matin, M.A.; Hossain, T.M.B.; Hossain, S. Cabbage (Brassica oleracea) and cauliflower (Brassica oleracea) marketing in selected areas of Bangladesh. Bangladesh J. Agric. Res. 2014, 39, 127–141. [Google Scholar] [CrossRef] [Scilit]
- Sidhu, R.S.; Kumar, S.; Vatta, K.; Singh, P. Supply Chain Analysis of Onion and Cauliflower in Punjab. Agric. Econ. Res. Rev. 2010, 23, 445–453. [Google Scholar]
- Bangladesh Agricultural Research Council. National Agricultural Technology Program-Phase II Project (NATP-2); Generated Technology Factsheet under Competitive Research Grant (CRG) Sub-Projects; Bangladesh Agricultural Research Council: Dhaka, Bangladesh, 2020; pp. 1–69. [Google Scholar]
- Stein, C.; Barron, J. Mapping Actors along Value Chains: Integrating Visual Network Research and Participatory Statistics into Value Chain Analysis; Research for Development Learning Series 5; CGIAR Research Program on Water, Land and Ecosystems; International Water Management Institute: Colombo, Sri Lanka, 2017. [Google Scholar]
- McCormick, D.; Schmitz, H. Manual for Value Chain Research on Homeworkers in the Garment Industry; Institute of Development Studies, University of Sussex: Brighton, UK, 2001. [Google Scholar]
- Ghorbani, M. The Efficiency of Saffron’s Marketing Channel in Iran. World Appl. Sci. J. 2008, 4, 523–527. [Google Scholar]
- Cramer, G.L.; Jensen, C.W. Agricultural Economics and Agribusiness, 2nd ed.; McGraw Hill Book Company: New York, NY, USA, 1982. [Google Scholar]
- Acharya, S.S.; Agarwal, N.L. Agricultural Marketing in India, 4th ed.; Oxford and IBH Publishing Co. Pvt. Ltd.: New Delhi, India, 2004. [Google Scholar]
- Nachmias, C.F.; Nachmias, D. Research Methods in the Social Sciences, 7th ed.; Worth Publishers Inc.: New York, NY, USA, 2008. [Google Scholar]
- Taylor, D.H. Value chain analysis: An approach to supply chain improvement in agri-food chains. Int. J. Phys. Distrib. Logist. Manag. 2005, 35, 744–761. [Google Scholar] [CrossRef] [Scilit]
- Dempsey, J.; Campbell, R. A Value Chain Approach to Coffee Production: Linking Ethiopian Coffee Producers to International Market; VOCA Technical Bulletin: Addis Ababa, Ethiopia, 2007. [Google Scholar]
- Woldesenbet, A.T. Value Chain Analysis of Vegetables: The Case of Habro and Kombolcha Woredas in Oromia Region, Ethiopia. Master’s Thesis, Agricultural Economics and Agribusiness, School of Graduate Studies, Haramaya University, Harar, Ethiopia, 2013. [Google Scholar]
- Gereffi, G. Global production systems and third world development. In Global Change, Regional Response: The New International Context of Development; Stallings, B., Ed.; Cambridge University Press: New York, NY, USA, 1995; pp. 100–142. [Google Scholar]
- Hinnou, L.C.; Mongbo, R.L.; Kamanda, J.; Sanyang, S. Innovation platform and governance of local rice value chain in Benin: Between game of power and internal democracy. Cogent Food Agric. 2018, 4, 1433346. [Google Scholar] [CrossRef] [Scilit]
- Uddin, M.T.; Goswami, A.; Rahman, M.S.; Dhar, A.R.; Khan, M.A. Value chain of pangas and tilapia in Bangladesh. J. Bangladesh Agric. Univ. 2018, 16, 503–512. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2023 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).