


Abstract
This study analysed the financial literacy (FL) levels of micro and small entrepreneurs (MSMEs) across 13 countries using data from the 2021 OECD/INFE survey. Focusing on the three core aspects of financial literacy—knowledge, behaviour, and attitudes—our analysis reveals that FL levels tend to vary by enterprise size, with small businesses generally scoring higher than micro-enterprises. Moreover, countries’ performances differ across the three FL aspects, and these differences appear to be component rather than country-specific. This study applied the standardised OECD/INFE methodology, enabling cross-country comparisons of MSME financial literacy. The results identify specific strengths and weaknesses across countries and FL components, providing valuable insights into policy design and educational interventions. For instance, while financial behaviour scores are relatively strong, financial attitude scores are consistently lower, indicating a gap that requires targeted attention.
1. Introduction
Micro, small, and medium enterprises (MSMEs) are the backbone of most economies around the world. They account for over 90% of businesses and make significant contributions to employment and GDP in both developed and developing countries (World Bank, 2021; United Nations, 2024). Despite their importance, MSMEs often face structural challenges—particularly with regard to financial management and access to finance, which can hinder their growth and resilience. In this context, financial literacy (FL) has emerged as a critical factor which influences their ability to survive, adapt, and thrive. While financial literacy has been widely studied in the context of individuals and students, its role and measurement among MSME owners remain underexplored, especially in a cross-country setting. This study addresses this gap by analysing the financial literacy levels of MSME owners across 13 countries using a standardised assessment framework.
Financial literacy (hereafter referred to as FL) is significant in modern society and the economy. Its importance was acknowledged even during the early 20th century, when the establishment of the Smith-Lever Act (USDA) in 1914 led to the development of educational programmes delivering “useful and practical information” about various topics, including personal finance. Since then, and over the years, several international organisations have highlighted the importance of FL in relation to the economic activities of several stakeholders. However, the last two decades in particular have witnessed a growing interest in the concept of FL, as represented by an increasing number of published academic papers. This is because studies have shown that a higher level of financial literacy reduces individuals’ likelihood of being exploited or deceived (Campbell et al., 2011; Deevy et al., 2012; De Bassa Scheresberg, 2013; Lusardi & Mitchell, 2014; Balloch et al., 2015; Andreou & Philip, 2018), increases their propensity to invest in financial markets (Van Rooij et al., 2012), grants them higher returns on their savings accounts (Deuflhard et al., 2019), and helps them to better control their debts (Lusardi & Tufano, 2015) and retirement planning (Lusardi & Mitchell, 2007; Van Rooij et al., 2012).
As mentioned, the academic literature on FL has largely focused on students and adults, while MSMEs remain relatively under-researched. MSMEs are typically classified based on employee count, with micro-enterprises employing fewer than 10 people, small enterprises employing between 10 and 49, and medium enterprises employing up to 250—although the thresholds may vary by country (OECD/INFE, 2021). Such organisations play a pivotal role in economic development, accounting for approximately 90% of businesses and more than half of the employment worldwide. Their contributions are particularly critical in emerging markets, where they drive innovation, reduce poverty, and support inclusive growth. Research on this specific subfield of MSMEs and its links with the respective fields in their economic activity is relatively widespread, particularly with regard to consistent measurements of FL at the global level. This gap in the academic literature appears to be primarily attributed to the difficulties associated with measuring the FL of micro and small entrepreneurs, let alone linking it with economic, financial behaviour and performance.
In this context, the scientific field of financial literacy for micro and small entrepreneurs has attracted the attention of several researchers, such as Anshika and Singla (2022) and Graña-Alvarez et al. (2022), who have both published respective systematic literature reviews. They concluded that there is no systematic way to measure the financial literacy of micro- and small-scale entrepreneurs. Anshika and Singla (2022) note that the existing literature lacks a standardised methodology for measuring entrepreneurs’ financial literacy, while Graña-Alvarez et al. (2022) emphasise the fragmented nature of the current findings. This lack of consistency hinders meaningful cross-country comparisons and prevents researchers from drawing objective conclusions regarding the relative financial literacy levels of MSME owners worldwide.
We hope that the above-mentioned information gap can be eliminated in years to come due to the research efforts of the Organisation for Economic Co-operation and Development (OECD), which has developed a robust methodology for FL measurement specifically for micro and small entrepreneurs, in the context of its OECD/INFE unit1. The OECD/INFE, or the Organisation for Economic Co-operation and Development/International Network on Financial Education, is a global platform dedicated to advancing financial education and literacy. It operates under the umbrella of the OECD, an international organisation comprising 38 member countries committed to promoting policies that foster economic growth, stability, and an improved quality of life. In recognition of the growing importance of financial literacy in today’s complex financial environment, the OECD established the INFE in 2008 to unite public authorities, policymakers and experts from over 100 countries.
In 2020, OECD/INFE published its MSMEs FL study, which describes a specific, questionnaire-based methodological approach to measuring the FL levels of MSMEs. The OECD/INFE (2020) questionnaire is specifically tailored to micro and small entrepreneurs and captures all different angles of FL, since it is divided across three basic aspects of financial literacy: a. financial knowledge, b. financial behaviour, and c. financial attitudes. An overall FL score is calculated based on a set of questions (“components”) pertaining to each aspect of FL. OECD/INFE (2020) has already applied the questionnaire in 14 countries, allowing researchers to identify the relative levels of MSMEs FL across countries. As countries apply the OECD/INFE (2020) methodology in this field, it is only a matter of time before a global database of MSMEs FL is created. This would allow for cross-country comparisons based on a standardised and coherent methodology.
In this context, the main objectives of this paper are as follows: a. to conduct a preliminary cross-country analysis of MSMEs FL levels across 13 countries around the world, namely Brazil, China, France, Georgia, Germany, Italy, Mexico, Netherlands, Portugal, Russia, Saudi Arabia, Spain, and Turkey2; and b. to conduct a detailed investigation of the individual components of FL across its three aforementioned aspects and highlight cross-country differences between these components. The main findings are that FL levels are relative to the size of the enterprise, that countries tend to score differently across FL aspects, and that FL level differences appear to be component-specific and not country-specific. This study is one of the first to apply the OECD/INFE (2020) standardised methodology to assess financial literacy in MSMEs across 13 countries. It offers new comparative evidence not only on overall financial literacy levels, but also on specific knowledge, behaviour, and attitude components. By highlighting both cross-country and component-level variations, our study provides actionable insights for policymakers, educators, and financial institutions seeking to improve financial competence in the MSME sector.
The remainder of this paper is structured as follows: Section 2 reviews the relevant literature on MSME financial literacy. Section 3 outlines the OECD/INFE methodology and describes the dataset. Section 4 presents and analyzes the results. Section 5 discusses the findings, practical implications, and limitations of the study, and provides suggestions for future research.
2. Literature Review
Micro and small enterprises are two distinct subsets of the broader category of small and medium enterprises (SMEs). Although there is no standardised global definition for SMEs, they are most frequently categorised based on the OECD and EU criteria, which set the threshold of an SME at a maximum of 250 employees. However, this threshold varies from country to country and can be as high as 500 employees in some countries, such as the US. In general, however, SMEs account for 90% of businesses, 60 to 70% of employment, and 50% of GDP worldwide (United Nations, 2024), and make considerable contributions to employment generation, industrial production, and GDP formation in developed and emerging economies (Bhuyan, 2016). They generate seven out of 10 formal jobs (World Bank, 2021) and have successfully raised many people out of poverty (Gbandi & Amissah, 2014).
Within this broad definition of SMEs, there are specific sub-segments in which enterprises are further categorised as micro, small, and medium enterprises; the relative thresholds provided by the OECD and EU are 1–9, 10–49, and 50–249 employees, respectively. In this context, micro-enterprises (1–9 employees) cover 93.3% of the enterprises in the EU-27, offering 29.2% of total employment and generating 18.7% in value added; the respective figures for small enterprises (10–49 employees) are 5.7%, 17.0%, and 20.0%, while those of medium enterprises (50–249 employees) are 0.9%, 17.3%, and 15.9%, respectively (EC, 2021). The relative size of enterprises helps determine SMEs’ capital structure and access to finance, as smaller enterprises experience more difficulties in accessing formal financial resources (Ramalho & Silva, 2009; Psillaki & Daskalakis, 2009; Kumar et al., 2020). This financing gap represents an important obstacle to economic growth, technological progress, risk diversification, and even poverty alleviation (Chimucheka & Rungani, 2011; Nkundabanyanga et al., 2014).
Higher levels of FL are associated with better performance, either in general (Ferawati et al., 2024), or specifically in terms of numeracy (Atkinson, 2017), savings (Agarwala et al., 2013), interest rate evaluation, and risk diversification and tolerance (Lusardi & Mitchell, 2014). Furthermore, higher FL levels can help alleviate the issues SMEs face in accessing finance (Nyamboga et al., 2014; Nkundabanyanga et al., 2014; Engström & McKelvie, 2017), while individuals are better prepared for difficult financial circumstances through risk management (Wachira & Kihiu, 2012). Moreover, recent studies continue to reinforce the critical link between financial literacy and MSME success. Urefe et al. (2024) and Dwyanti (2024) emphasise that financial literacy directly enhances financial management practices, particularly in areas such as cash flow, budgeting, and investment decisions, which are vital for MSME sustainability. Culebro-Martínez et al. (2024) found that among the three financial literacy components, financial behaviour had the strongest effect on business performance—an insight that echoes the OECD/INFE framework adopted in this study. Meanwhile, Ahmad (2024) highlights how financial literacy, paired with qualified personnel, leads to better management accounting practices, further improving MSME outcomes.
In developing regions, Fintech has emerged as a valuable tool for promoting both financial literacy and access. Hamid et al. (2024) argue that digital financial education and Fintech tools can bridge literacy gaps and support inclusive growth. Meanwhile, studies conducted in Pakistan (Ullah et al., 2025) and Kuwait (Abdallah et al., 2024) show that regional disparities in financial knowledge and attitudes necessitate tailored, context-sensitive literacy interventions. Collectively, these studies support the need for a standardised, component-level analysis of MSME financial literacy, which is the approach taken in this paper. Furthermore, research by Graha et al. (2024) in Indonesia demonstrates that Fintech significantly mediates the relationship between financial literacy and MSME performance, suggesting that digital financial tools can amplify the benefits of financial literacy. However, Murdiono et al. (2024) found that Fintech alone does not directly impact MSME performance unless accompanied by adequate financial literacy, highlighting the moderating role of financial knowledge in leveraging technological solutions. This underscores the importance of integrating financial literacy programmes with Fintech adoption strategies to enhance MSME outcomes. Lastly, Zaimovic et al. (2025) emphasise the role of digital financial literacy in facilitating Fintech adoption among MSME managers, indicating that business experience influences Fintech usage through the mediating effect of digital financial literacy components such as knowledge, attitudes, and behaviour. This finding aligns with the notion that comprehensive financial literacy, encompassing both traditional and digital aspects, is crucial for MSMEs to effectively navigate and benefit from the evolving financial landscape. Overall, FL affects a broad spectrum of SMEs activities, such as their growth, survival, and financial and non-financial performance (Anshika & Singla, 2022; Graña-Alvarez et al., 2022).
Therefore, it is of utmost importance to assess the level of MSMEs’ FL and identify specific fields that can be improved within the broad area of this topic. Furthermore, it is important for public bodies to be able to compare the FL of MSMEs that operate in their country in a relative context to identify the best practices within countries with high FL levels. Therefore, it is crucial that a standardised approach to measuring SMEs’ FL is followed and applied in a series of countries, facilitating the gradual development of a comprehensive global database of SMEs’ FL. Research on the FL of SMEs is highly fragmented, consisting of individual investigations using different approaches. Anshika and Singla (2022) provide substantial evidence on this fragmented field, referring to more than 20 studies, and describe the broad spectrum of parameters that researchers use, ranging from inflation, the time value of money, record keeping and accounting, budget control, managing cash flow, debt, and depreciation, to name just a few. The academic literature coverage on the specific field of SME FL measures is even broader in Graña-Alvarez et al. (2022), who cite 71 studies in their study, separating the conceptualisation approaches of these studies into five main categories: financial education, financial knowledge, application of financial knowledge, financial attitudes, and financial behaviour. This fragmented picture fails to provide a coherent understanding of the overall financial literacy level and a relative cross-country evaluation.
Given the context outlined earlier, the approach proposed by the OECD/INFE (2020) appears to be one of the most consistent frameworks for assessing financial literacy among MSMEs. Their questionnaire divides financial literacy into three core components: financial knowledge, financial behaviour, and financial attitudes. It collects responses within each of these areas, generating individual scores for each component and an overall financial literacy score. This comprehensive design, specifically tailored to the needs of micro and small business owners, effectively captures various dimensions of financial literacy, offering a thorough understanding of the respondents’ financial literacy levels. Furthermore, as an increasing number of countries have begun to use this methodology, a global database pertaining to this specific field is expected to be created in the near future, allowing for cross-country comparisons. The existing data from the 14 aforementioned countries allow such an evaluation.
3. The OECD/INFE (2020) Methodology
In 2015, the OECD/INFE unit created a survey instrument to measure financial literacy among micro and small business owners. After a refining iterative process, it was piloted in 2018–2019 in seven volunteer countries (Brazil, Chile, Italy, Lebanon, Portugal, the Russian Federation, and South Africa). It underwent further revision in 2020 to account for the financial implications of the COVID-19 crisis. The target population suggested by the OECD/INFE (2020) are for-profit business owners, including self-employed people and one-person businesses, but only those employing fewer than 50 people—namely, micro and small entrepreneurs (MSMEs), which may be formal or informal.
3.1. The Questionnaire
The questionnaire comprises approximately 50 items organised into the following thematic sections:
- Screening (QC1–QC5 questions)
These initial questions served to determine whether the respondents met the basic criteria required to proceed with the interview. For instance, if a respondent indicates that they manage a branch or a non-profit organisation, or if they are not the business owner, the survey is terminated. Similarly, if the business employs more than 50 people, the interview does not continue.
- Characteristics of the business (QC6–QC10 questions)
This section gathers key information about the business itself, such as annual revenue, years of operation, whether it exports goods or services, and the primary sector in which it operates.
- Financial products (QP questions)
These items assess the extent of the respondents’ knowledge and usage of various financial products. The questions explore whether the business holds accounts with traditional or digital banks and whether they are aware of or utilise services such as overdrafts, business loans, invoice discounting, microcredit, and trade credit. It also delves into how respondents choose the financial services they use.
- Managing and planning business finances (QM questions)
This category focuses on how entrepreneurs approach financial decision-making and planning. Respondents are asked whether they seek advice from others—such as partners, accountants, or banks—regarding financial matters, and whether they request support in specific areas such as cash flow management, obtaining external funding, or handling tax issues. This section also examines how financial records are maintained (e.g., via software, on paper, or through professionals), provisions for retirement (or lack thereof), and respondents’ opinions on business-related statements using a 4-point Likert scale.
- Financial knowledge and attitudes (QK questions)
This part evaluates the respondents’ ability to understand basic financial principles and tools, including concepts such as interest rates, balance sheets, dividends, equity, and Return on Assets (ROAs).
- Financial education and protection (QF questions)
Respondents are asked whether they have received training related to business or personal finance management and whether they actively engage in self-education on financial topics relevant to their business.
- Demographics (QD questions)
This section collects standard demographic data pertaining to gender, age, educational background, and the number of years the respondents have been running their businesses.
- Impact of COVID-19 (QX questions)
These questions are intended to measure the impact of the COVID-19 pandemic on the respondents’ businesses. This category is further split into sub-categories measuring COVID-19’s impact on financial performance, the digitalisation process, cash flow issues and financing issues.
3.2. The Overall Financial Literacy Score
The overall FL score is calculated as the weighted average of the individual scores for each of the three “aspects” (financial knowledge, financial behaviour and financial attitudes). To derive the overall financial literacy (FL) score, a selection of questions from the eight questionnaire categories is utilised. In line with the OECD/INFE (2020) approach, the financial knowledge component is assessed using five targeted questions from the QK section. The financial behaviour component is measured through a combination of nine questions from both the QP and QM sections. For the financial attitudes dimension, three particular questions from the QK category are employed.
Details about the exact questions used for each component, as well as their corresponding scores—both by country and question—are presented in the Results Section. Further information, including sample questions, suggested responses, and scoring guidelines, can be found in Appendix A.
The total FL score was calculated using a two-step process. Firstly, individual scores are computed for each of the three components: financial knowledge, financial behaviour, and financial attitudes. The score for each dimension is obtained by summing the number of correct responses, dividing by the total number of relevant questions, and then converting that to a percentage:
Next, the overall financial literacy score is determined by applying a weighted average formula that reflects the relative importance of each component:
3.3. Data Collection Methodology and the Dataset
The above-mentioned methodology was applied by the report of OECD/INFE (2021), upon which this study dataset was based. The report includes average results across all participating countries, which are computed as the arithmetic mean of the available country estimates in each table. Data collection was conducted at the country level. Table 1 presents information related to the dataset3.
Table 1.
OECD/INFE (2021) dataset information.
4. Study Methodology
To enhance methodological transparency, this study adopted a descriptive comparative design, leveraging the OECD/INFE (2021) dataset. A harmonised survey instrument was used to enable cross-country comparisons of MSME financial literacy. Financial literacy scores were calculated for each of the three aspects (knowledge, behaviour, and attitudes) by summing the correct responses, dividing by the number of items, and scaling to a 0–100 range; this methodological approach was also preserved in this study. However, it is important to note that the OECD/INFE framework does not define a benchmark or threshold score that represents an “adequate” level of financial literacy for SMEs. Establishing such a target—or a range of indicative scores—could significantly enhance the interpretability of the results, enable more meaningful comparisons between countries, and allow for a clearer evaluation of performance within each individual financial literacy component.
To deal with this lack of benchmarks of thresholds, areas of low/moderate/high scores are constructed as follows: first, the overall average and standard deviation of all countries and all components per aspect are calculated; second, an area of moderate scores as the overall average ±0.5 standard deviation is set, so that the low scores area are scores < average −0.5 standard deviation, and high scores area are scores > average +0.5 standard deviation can be identified. Scores were categorised as high, moderate, or low using ±0.5 standard deviation from the mean. These scores allowed the exploration of potential differences across FL scores in a multilevel context, namely, cross-country, cross-aspect, and cross-item per aspect. No inferential statistical tests were applied, which was consistent with the descriptive nature of the study.
5. Results
5.1. Overall Financial Literacy Score Results
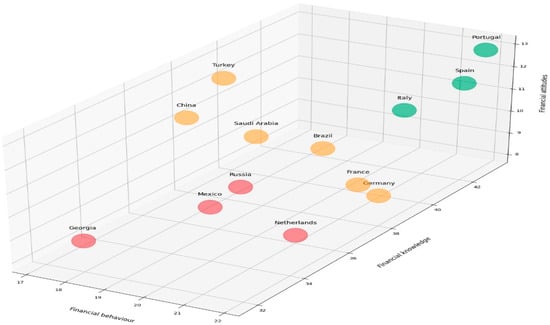
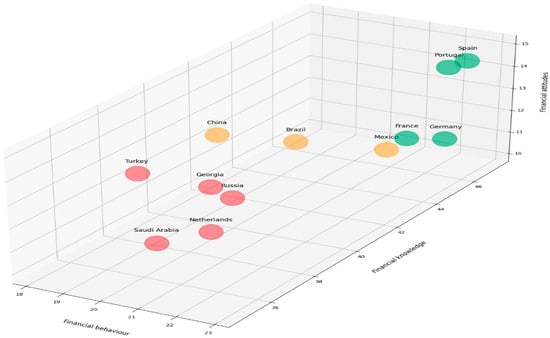
Table 2 and Table 3 show the overall FL scores for all 13 countries that participated in the OECD/INFE (2021) survey for companies that employ up to nine employees and 10 to 49 employees, respectively4. In both tables, an overall average and an overall standard deviation for all countries and all aspects’ components are calculated (see the grey boxes at the bottom right of each table). As discussed above, based on these overall average and overall standard deviation figures, areas of low/moderate/high scores are constructed, and the scores per country and per component are indicated by various colours (low = red, moderate = yellow, high = green). Figure 1 and Figure 2 provide a visual representation of the relative scores per aspect for all countries for micro and small enterprises, respectively; specifically, they show each country in a three-dimensional space where the three dimensions are the three components (aspects) of overall financial literacy.
Table 2.
Scores per aspect and overall FL score per country for companies that employ. Up to nine employees (micro).
Table 3.
Scores per aspect and overall FL score per country for companies that employ. 10 to 49 employees (small-sized).
Figure 1.
Visual representation of the relative scores per aspect, per country (micro). Note: colours are maintained as given in the FL overall score in Table 2.
Figure 2.
Visual representation of the relative scores per aspect per country (small). Note: colours are maintained as given in the FL overall score in Table 3.
There are several results worthy of discussion. An initial observation is that the overall FL score for larger companies is higher than that of smaller companies, on average and in total (68 for micro-enterprises and 75 for small enterprises); thus, we can conclude that owners of larger companies tend to be more financially literate than the owners of micro-companies. The only exception to this rule is Turkey, where micro companies achieved a higher overall FL score (69) than small companies (68). Interestingly, the three highest-scoring countries in terms of micro-enterprises were Italy, Portugal, and Spain, whereas the other European countries’ scores were either moderate (France, Germany) or low (the Netherlands). In the case of micro-entrepreneurs, Spain and Portugal are the only countries with high scores for all three aspects, while Georgia is the only country with low scores for all three aspects. Again, regarding micro-enterprises, France, Germany, and Turkey achieved scores for all three areas (green, yellow, and red) across the three aspects, indicating that there are areas in which they perform well (financial knowledge for France and Germany, financial attitudes for Turkey), in addition to areas in which they perform poorly (financial attitudes for France and Germany; financial knowledge for Turkey), showing clear pathways for future improvement. Slight differences in the case of small enterprises can be observed compared with micro-enterprises. First, France and Germany join Spain and Portugal in achieving high overall FL scores. In contrast, Saudi Arabia and Turkey are among the worst performers. Spain is the only country with consistently high scores across all three aspects, while no country’s scores are consistently low.
5.2. Results per Aspect of Financial Literacy
Next, the components of each aspect per country are explored. Table 4, Table 5 and Table 6 contain questions that comprise the financial knowledge, financial behaviour, and financial attitude scores, respectively, per country, for companies with up to nine employees. Table 7, Table 8 and Table 9 contain questions5 that comprise the financial knowledge, financial behaviour and financial attitude scores, respectively, per country, for companies with 10 to 49 employees. For both cases, an overall average and an overall standard deviation for all countries and all aspects’ components are calculated (see the grey boxes at the bottom right of each table). Based on these overall average and standard deviation figures, areas of low/moderate/high scores are constructed, and the scores per country and per component are presented in various colours (low = red, moderate = yellow, high = green). Below, we discuss some general findings that hold across all three aspects, followed by a discussion of the components for each aspect.
Table 4.
Financial knowledge scores per country per component for companies that employ up to nine employees (micro)/Percentages of respondents who gave correct answers.
Table 5.
Financial behaviour scores per country per component for companies that employ up to nine employees (micro)/Percentages of respondents who gave correct answers.
Table 6.
Financial attitude scores per country per component for companies that employ. Up to nine employees (micro)/Percentages of respondents who gave correct answers.
Table 7.
Financial knowledge scores per country per component for companies that employ 10 to 49 employees (small)/percentages of respondents who gave correct answers.
Table 8.
Financial behaviour scores per country per component for companies with 10 to 49 employees (small)/percentages of respondents who gave correct answers.
Table 9.
Financial attitude scores per country per component for companies that employ. 10 to 49 employees (small)/percentages of respondents who gave correct answers.
5.2.1. Overall Results
One of the main findings, which was to be expected based on the analysis presented above, is that, overall, small companies achieved higher scores for all aspects than the respective scores of micro companies. Secondly, the behaviour scores were the highest, followed by the knowledge scores, while the attitude scores were the lowest. However, the allocation of scores differed across size classes. Specifically, the scores for knowledge and behaviour were relatively close for micro-enterprises (68.3 and 71.2, respectively), while the attitude score was significantly lower (59.5). In the case of small enterprises, the scores for knowledge and attitudes were relatively close (71.0 and 70.3, respectively), while the behaviour score was much higher (78.7). These findings offer clear indications for policymakers regarding which aspects of FL should be prioritised per size class. Comparing scores across size classes also revealed that the distances between scores differed across the three aspects. Specifically, the scores for financial knowledge were relatively close (71 for small and 68.3 for micro-enterprises), while the respective scores for financial behaviour and attitudes differed significantly (78.7 for small vs. 71.2 for micro-enterprises for financial behaviour and 70.3 for small vs. 59.5 for micro-enterprises for financial attitudes). Lastly, it is also worth mentioning that the average standard deviation of all components per aspect also exhibited some differences between the two size classes; specifically, the overall average standard deviations for small companies were 10.6, 10.2, and 11.7 for knowledge, behaviour, and attitudes, while the respective figures for micro companies were 11.9, 6.1, and 6.59. This shows that the score differences across countries were greater in the case of small enterprises and lower in the case of micro-enterprises, with regard to behaviour and attitudes.
5.2.2. Financial Knowledge Results
Focusing on the financial knowledge results and conducting cross-component and cross-country comparisons, we made the following interesting observations. Firstly, there are clear differences across the component scores for all countries. Specifically, both micro and small entrepreneurs have difficulty understanding that “when a company obtains equity from an investor, it gives the investor part of the ownership of the company”, scoring the lowest score for each component. On the other hand, entrepreneurs from both size classes clearly understand that “high inflation means that the cost of living is increasing rapidly” and that “if a financial investment offers the chance to make a lot of money, it is likely that there is also a chance to lose a lot of money”. The remaining two components (dividend concepts and loan features) achieved moderate scores across countries. Interestingly, the high- and low-scoring components were the same for both size classes. In addition, it is worth noting that the component with the highest standard deviation across countries was the concept of dividends for both small and micro-entrepreneurs.
For country-based comparisons, it is worth noting that no single country achieved consistently high or consistently low scores across all five components. In general, no clear conclusion could be drawn regarding high or low-performing countries, since their relative scores per component varied significantly. For example, Saudi Arabia and Mexico were the only countries that scored highly in the equity dilution question in both size classes, while all other countries’ scores were low, and not even moderate scores were achieved. This is a clear indication that each country displays its unique “weaknesses” and “strengths” as regards the components of financial knowledge.
Focusing on the financial knowledge results and conducting cross-component and cross-country comparisons, we made the following interesting observations. Firstly, there are clear differences across the component scores that hold for all countries. Specifically, both micro and small entrepreneurs have difficulty understanding that “when a company obtains equity from an investor, it gives the investor part of the ownership of the company”, scoring the lowest score for each component. On the other hand, entrepreneurs from both size classes clearly understand that “high inflation means that the cost of living is increasing rapidly” and that “if a financial investment offers the chance to make a lot of money, it is likely that there is also a chance to lose a lot of money”. The remaining two components (dividends’ concept and loan features) achieved moderate scores across countries. Interestingly, the high/low-scoring components were the same for both size classes. Also, it is worth noting that the component with the highest standard deviation across countries was the concept of dividends, for both small and micro-entrepreneurs.
For country-based comparisons, it is worth noting that no single country achieved consistently high or consistently low scores across all five components. In general, no clear conclusion could be identified regarding high-performing or low-performing countries, since their relative scores per component varied significantly. For example, Saudi Arabia and Mexico were the only countries that scored highly in the equity dilution question in both size classes, while all other countries’ scores were low, and not even moderate scores were achieved. This is a clear indication that each country displays itt unique “weaknesses” and “strengths” as regards the components of financial knowledge.
5.2.3. Financial Behaviour Results
In terms of financial behaviour, there are clear components for which entrepreneurs achieved both high and low scores across both size classes, with one exception. Specifically, in the case of small enterprises, there are four components for which scores were high (“keeping track of financial records”, “keeping secure data and information about the business”, “forecast the profitability of the business regularly, ” and “adjust planning according to the changes in economic factors”), while moderate “forecast profitability” component scores were achieved for micro-enterprises. On the other hand, the three components with low scores were the same for both size classes (“shopping around”, “thought about retirement” and “Strategies to cope with theft”). As regards the component with the highest standard deviation, this was the “separation account” for both size classes, where the European countries seem to score high, with the exceptions of the Netherlands for both size classes and Germany for micro-entrepreneurs.
Again, the country comparisons reveal no clear, consistently good or bad performers and all countries were represented in all three score classes across the financial behaviour components. This reinforces the finding described in the section above, namely that there are strengths and weaknesses across all countries, with each having a clear area for improvement in its attempt to improve its overall FL score.
5.2.4. Financial Attitudes Results
Turning to the last FL aspect, the distinction between high- and low-scoring components is even clearer. Specifically, there were only three attitude components, and there were clear scoring differences among them: the “long-term goal setting” component scored relatively highly (84.1 for small entrepreneurs and 75.8 for micro-entrepreneurs), the “confidence to approach banks and external investors to obtain finance” component achieved moderate scores (72.5 for small entrepreneurs and 57.2 for micro-entrepreneurs) and the “instinct preference rather than to make detailed financial plans” component scored low (54.4 for small entrepreneurs and 45.5 for micro-entrepreneurs). Notably, there were large differences between the scores of the small and micro-entrepreneurs in the last two components (“external financing confidence” and “instinct vs. planning”). As regards standard deviations, there appear to be differences between the two size classes; specifically, the larger standard deviation for micro-entrepreneurs is that of the “external financing confidence” component, while the larger standard deviation for the small entrepreneurs is that of the “instinct vs. planning” component. Lastly, in terms of countries, it is the first time that a country (Spain) has scored highly on all components, though only for small entrepreneurs. Spain is the exception, as all the remaining countries show highs and lows across the components. For example, Turkey and Saudi Arabia scored highly on the first two components but low on the last component for small entrepreneurs. Similarly, Brazil, Mexico, and the Netherlands scored highly in the first component and low in the last two for micro-entrepreneurs. Overall, the conclusion that countries do not seem to score consistently high or low across all components still holds (with the exception of Spain).
5.2.5. Relating Findings to Existing Literature
The results outlined in the previous sections align with and expand on the findings of the current literature on MSME financial literacy. Consistent with the conclusions of Graña-Alvarez et al. (2022), this study confirms the fragmented nature of financial literacy among small business owners: while some components—such as understanding inflation or maintaining financial records—are well grasped across countries, others, such as equity dilution or retirement planning, remain poorly understood. These patterns support Grana-Alvarez et al.’s categorisation of financial literacy dimensions and the uneven development across those dimensions.
This study also corroborates Anshika and Singla’s (2022) assertion that there is a lack of standardised methodology for measuring the entrepreneurial financial literacy. By applying the OECD/INFE (2020) methodology across 13 countries, this paper contributes to filling that gap by offering one of the first comparative applications of a unified framework. Furthermore, the observation that financial behaviour tends to outperform attitudes in both micro and small enterprises supports the prior work by Lusardi and Mitchell (2014), who found that behavioural traits are more easily influenced by experience or targeted interventions than deeper attitudinal dispositions. The finding that FL differences are more component-specific than country-specific provides novel insight, suggesting that tailored policy responses can transcend national contexts and focus on addressing specific weaknesses shared across countries. Thus, this study contributes confirmatory evidence, reinforces calls for a harmonised FL assessment approach, and introduces new comparative insights into the structure and variability of the FL dimensions of MSMEs.
6. Conclusions
The main objective of this paper is twofold: to explore the relative levels of financial literacy across 13 countries, and across the three main aspects of FL, namely financial knowledge, financial behaviour and financial attitudes, and to investigate the relative scores of individual components per each FL aspect—knowledge, behaviour, and attitudes—across countries. This exercise is applied across two different size classes, namely micro and small entrepreneurs (MSMEs). An interesting conclusion is that the FL levels are generally lower for micro-entrepreneurs than for small entrepreneurs (with the exception of Turkey). Additionally, few countries achieved consistently high or consistently low scores across all aspects of FL. In other words, countries tended to score differently (i.e., high, moderate, or low) across FL aspects, providing clear pathways for policymakers that will allow them to focus on specific areas to improve general FL levels.
Focusing on the components of each FL aspect, we first note that there are components of each aspect for which countries tend to score high and others for which countries tend to score low. This finding, combined with the fact that countries do not achieve consistently high or low scores across all components of any FL aspect, leads us to conclude that FL level differences are component-specific and not country-specific. This is an important conclusion since it reinforces the argument that policymakers across all countries face relatively similar challenges in their efforts to improve overall FL scores, which in turn could lead either individual countries or international organisations to develop educational initiatives for MSMEs to focus on improving specific components.
The findings of this study provide key insights relevant to the research objectives. MSME financial literacy levels vary significantly by component and enterprise size, suggesting that targeted interventions rather than uniform national policies are necessary. These insights have practical implications for policymakers, who can prioritise educational efforts on specific FL aspects, and for MSME support organisations and financial institutions, which can tailor services to fill identified gaps. Banks and other financial institutions that finance MSMEs would also find this study beneficial, as the financial knowledge, behaviour, and attitudes (i.e., the three FL aspects) of MSMEs also affect them as providers of capital. Lastly, theoretically, this study supports the view that financial literacy is a multidimensional construct that requires an aspect-level rather than an aggregate analysis. The cross-country findings offer a foundation for future comparative research and reinforce the need for a globally standardised MSME FL database.
The main limitation of this study is that it only focuses on 13 countries; a larger set of countries would allow for several other levels of analyses, such as clustering of countries and identification of common features across clusters. Additionally, the data collection process varied by country, using different modes (e.g., online, phone, and face-to-face), which may have introduced response biases or mode effects. While the OECD/INFE framework standardises questions and scoring, cultural and contextual interpretations may still influence responses. Furthermore, due to the descriptive nature of the analysis, no causal relationships could be inferred. Despite these limitations, cross-country standardisation enables valuable comparative insights.
In terms of future research, while this study offers a cross-country comparison of MSME financial literacy, it is limited to 13 countries. Future research could focus on analysing an expanded dataset featuring additional countries and regions, enabling more granular analyses, such as clustering or typology-building based on financial literacy patterns. Moreover, beyond exploring the knowledge of MSMEs, it would be valuable to investigate why knowledge gaps persist, potentially using mixed-methods approaches that incorporate qualitative insights. Building on recent research, future studies could also examine the role of Fintech adoption, digital financial literacy, and contextual factors (e.g., culture and regulatory environment) in shaping MSME financial behaviour. Longitudinal studies could further capture how financial literacy evolves over time, especially as digital tools and financial ecosystems continue to develop.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The dataset is available here: https://web-archive.oecd.org/2021-11-12/616062-G20-OECD-INFE-report-navigating-the-storm-tables-figures.xlsx (accessed on 21 April 2024).
Conflicts of Interest
The authors declare no conflict of interest.
Notes
| 1 | For more information on OECD/INFE, please see: https://www.oecd.org/en/networks/infe.html (accessed on 4 April 2024). |
| 2 | The 14th country that is not included in our study is Peru, as the scores that appear in the database seem problematic. In addition, the OECD/INFE reports for Italy only provide scores for micro-enterprises (1–9 employees). |
| 3 | The dataset is available here: https://web-archive.oecd.org/2021-11-12/616062-G20-OECD-INFE-report-navigating-the-storm-tables-figures.xlsx (accessed on 20 April 2024). |
| 4 | Only questions and results are shown with no indicative answers to avoid excess table sizes. For the full questions, including indicative answers, please refer to Appendix A. |
| 5 | Same as in note 4. |
References
- Abdallah, A., Harraf, A., Ghura, H., & Abrar, M. (2024). Financial literacy and small and medium enterprises performance: The moderating role of financial access. Journal of Financial Reporting and Accounting. ahead-of-print. [CrossRef] [Scilit]
- Agarwala, S. K., Barua, S. K., Jacob, J., & Varma, J. R. (2013). Financial literacy among working young in urban India. Indian Institute of Management. [Google Scholar]
- Ahmad, K. (2024). The influence of financial literacy, risk orientation and qualified accountants on performance in micro, small and medium enterprises: The mediating role of management accounting. International Review of Management and Marketing, 14(6), 314–324. [Google Scholar] [CrossRef] [Scilit]
- Andreou, P., & Philip, D. (2018). Financial knowledge among university students and implications for personal debt and fraudulent investments. Cyprus Economic Policy Review, 12(2), 3–23. [Google Scholar] [CrossRef] [Scilit]
- Anshika, A., & Singla, A. (2022). Financial literacy of entrepreneurs: A systematic review. Managerial Finance, 48(9/10), 1352–1371. [Google Scholar] [CrossRef] [Scilit]
- Atkinson, A. (2017). Financial education for MSMEs and potential entrepreneurs (Working Papers Finance No. 43). Insurance and Private Pensions. OECD Publishing. [Google Scholar]
- Balloch, A., Nicolae, A., & Philip, D. (2015). Stock market literacy, trust and participation. Review of Finance, 19(5), 1925–1963. [Google Scholar] [CrossRef] [Scilit]
- Bhuyan, U. (2016). A study on the performance of micro, small and medium enterprises (MSMEs) in India. Global Journal of Management and Business Research, 16(9), 33–36. [Google Scholar]
- Campbell, J. Y., Jackson, H. E., Madrian, B. C., & Tufano, P. (2011). Consumer financial protection. Journal of Economic Perspectives, 25(1), 91–114. [Google Scholar] [CrossRef] [Scilit]
- Chimucheka, T., & Rungani, E. (2011). The impact of inaccessibility to bank finance and lack of financial management knowledge to small, medium and micro enterprises in Buffalo City municipality, South Africa. African Journal of Business Management, 5(14), 5509–5517. [Google Scholar]
- Culebro-Martínez, R., Moreno-García, E., & Hernández-Mejía, S. (2024). Financial literacy of entrepreneurs and companies’ performance. Journal of Risk and Financial Management, 17(2), 63. [Google Scholar] [CrossRef] [Scilit]
- De Bassa Scheresberg, C. (2013). Financial literacy and financial behavior among young adults: Evi dence and implications. Numeracy, 6(2), 5. [Google Scholar] [CrossRef] [Scilit]
- Deevy, M., Lucich, S., & Beals, M. (2012). Scams, schemes and swindles: A review of consumer financial fraud research. Stanford University Center on Longevity Financial Fraud Research Center. [Google Scholar]
- Deuflhard, F., Georgarakos, D., & Inderst, R. (2019). Financial literacy and savings account returns. Journal of the European Economic Association, 17(2), 131–164. [Google Scholar] [CrossRef] [Scilit]
- Dwyanti, A. (2024). The importance of financial literacy in financial management in Micro, Small and Medium Enterprises (MSMEs). Journal of Applied Management and Business, 5(1), 1–6. [Google Scholar] [CrossRef] [Scilit]
- EC. (2021). Annual report on European SMEs. Available online: https://op.europa.eu/en/publication-detail/-/publication/849659ce-dadf-11eb-895a-01aa75ed71a1 (accessed on 14 April 2024).
- Engström, P., & McKelvie, A. (2017). Financial literacy, role models, and micro-enterprise performance in the informal economy. International Small Business Journal: Researching Entrepreneurship, 35(7), 855–875. [Google Scholar] [CrossRef] [Scilit]
- Ferawati, D., Fadah, I., & Paramu, H. (2024). Literature review: Financial literacy in the context of micro enterprise development and the methods used. Jurnal Pendidikan Akuntansi dan Keuangan, 12(2), 189–202. [Google Scholar]
- Gbandi, E. C., & Amissah, G. (2014). Financing options for small and medium enterprises (SMEs) in Nigeria. European Scientific Journal, 10(1), 327–340. [Google Scholar]
- Graha, A., Asna, A., & Suharso, A. (2024). Crafting the msmes’ performance into financial literacy, financial inclusion, and fintech in emerging countries. Migration Letters, 21(8), 50–63. [Google Scholar]
- Graña-Alvarez, R., Lopez-Valeiras, E., Loureiro, M. G., & Coronado, F. (2022). Financial literacy in SMEs: A systematic literature review and a framework for further inquiry. Journal of Small Business Management, 62(1), 331–380. [Google Scholar] [CrossRef] [Scilit]
- Hamid, A., Widjaja, W., Sutrisno, S., Napu, F., & Sipajung, B. (2024). The role of fintech on enhancing financial literacy and inclusive financial Management in MSMEs. TECHNOVATE: Journal of Information Technology and Strategic Innovation Management, 1(2), 81–88. [Google Scholar] [CrossRef] [Scilit]
- Kumar, S., Sureka, R., & Colombage, S. (2020). Capital structure of SMEs: A systematic literature review and bibliometric analysis. Management Review Quarterly, 70, 535–565. [Google Scholar] [CrossRef] [Scilit]
- Lusardi, A., & Mitchell, O. (2007). Financial literacy and retirement preparedness: Evidence and implications for financial education. Business Economics, 42(1), 35–44. [Google Scholar] [CrossRef] [Scilit]
- Lusardi, A., & Mitchell, O. (2014). The economic importance of financial literacy: Theory and evidence. Journal of Economic Literature, 52(1), 5–44. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Lusardi, A., & Tufano, P. (2015). Debt literacy, financial experiences, and overindebtedness. Journal of Pension Economics & Finance, 14(4), 332–368. [Google Scholar] [CrossRef] [Scilit]
- Murdiono, A., Zen, F., & Istanti, L. (2024). The influence of financial technology on the performance of MSMEs in the regency blitar: Effect financial literacy mediation. Journal of International Accounting Taxation and Information Systems, 1(3), 150–158. [Google Scholar] [CrossRef] [Scilit]
- Nkundabanyanga, S. K., Kasozi, D., Nalukenge, I., & Tauringana, V. (2014). Lending terms, financial literacy and formal credit accessibility. International Journal of Social Economics, 41(5), 342–361. [Google Scholar] [CrossRef] [Scilit]
- Nyamboga, T. O., Nyamweya, B. O., & Njeru, F. (2014). An assessment of the effect of financial literacy on loan repayment by small and medium entrepreneurs in Ngara, Nairobi county. Research Journal of Finance and Accounting, 5(12), 181–192. [Google Scholar] [CrossRef] [Scilit]
- OECD/INFE. (2020). OECD/INFE survey instrument to measure the financial literacy of MSMEs. Available online: https://www.bancaditalia.it/statistiche/tematiche/indagini-famiglie-imprese/alfabetizzazione-imprese/Data-Description.pdf (accessed on 10 May 2024).
- OECD/INFE. (2021). G20/OECD-INFE report on navigating the storm: MSMEs’ financial and digital competencies in COVID-19 times. OECD Publishing. [Google Scholar] [CrossRef] [Scilit]
- Psillaki, M., & Daskalakis, N. (2009). Are the determinants of capital structure country or firm specific? Small Business Economics, 33, 319–333. [Google Scholar] [CrossRef] [Scilit]
- Ramalho, J., & Silva, V. (2009). A two-part fractional regression model for the capital structure decisions of micro, small, medium and large firms. Quantitative Finance, 9(5), 621–636. [Google Scholar] [CrossRef] [Scilit]
- Ullah, A., Sami Latif, A., & Hassan, S. (2025). The role of financial literacy in entrepreneurial success: A study of small businesses in Pakistan. Qualitative Research Review Letter, 3(1), 192–216. [Google Scholar]
- United Nations. (2024). 2024 Theme: MSMEs and the SDGs. Available online: https://www.un.org/en/observances/micro-small-medium-businesses-day (accessed on 16 April 2025).
- Urefe, O., Odonkor, T. N., Chiekezie, N. R., & Agu, E. E. (2024). Enhancing small business success through financial literacy and education. Magna Scientia Advanced Research and Reviews, 11(2), 297–315. [Google Scholar] [CrossRef] [Scilit]
- Van Rooij, M., Lusardi, A., & Alessie, R. (2012). Financial literacy, retirement planning and household wealth. Economic Journal, 122(560), 449–478. [Google Scholar] [CrossRef] [Scilit]
- Wachira, M. I., & Kihiu, E. N. (2012). Impact of financial literacy on access to financial services in Kenya. International Journal of Business and Social Science, 3(19), 40–50. [Google Scholar]
- World Bank. (2021). Small and medium enterprises (SMEs) finance (IBRD-IDA). Available online: https://www.worldbank.org/en/topic/smefinance (accessed on 14 April 2024).
- Zaimovic, A., Omanovic, A., Dedovic, L., & Zaimovic, T. (2025). The effect of business experience on fintech behavioural adoption among MSME managers: The mediating role of digital financial literacy and its components. Future Business Journal, 11. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).