


Abstract
This study is an attempt to review relevant literature on the theme of corporate real investment decisions. We have conducted a comprehensive survey of literature on the studies published in well-reputed journals of finance, i.e., The Journal of Finance, The Review of Financial Studies, and The Journal of Financial Economics, during the years 2010 to 2022. The theoretical analysis reveals that information asymmetry, cash holdings, policy uncertainty, idiosyncratic risk, governance quality, financing diversification, financial development, managerial network, investor protection, tax policy, etc., are prominent factors influencing investment decisions. The current review analysis is useful and has certain policy implications for investment managers regarding investment decisions. It guides on the factors that can impede or boost investment volume. Our study has a novel contribution to the literature by summarizing the voluminous empirical literature arranged on physical investment decisions.
JEL Classification:
G30; G31
1. Introduction
Corporate firms make multiple decisions, including funding, the expansion of existing operations, and the acquisition of new assets to achieve the underlying objective of growth (Rahayu 2019). In this context, long-term investment, specifically investment in the acquisition of fixed assets, is fundamental to ensure the long-term view of growth. Such investment decisions stem from other attached factors, i.e., rate of return, payback period, profitability index, etc. (Farooq and Subhani 2021). Industrial enterprises are mostly concerned with accomplishing such tasks through some policy tools that can help to achieve such objectives efficiently. Such policy tools are commonly known as determinants of corporate investment decisions, affecting the managerial thinking of investment structuring. Given that, there exists a stream of studies that deems to explore such determinants of investment by arranging the empirical analyses on different countries of the world (Adelino et al. 2017; Ajide 2017; Farooq et al. 2021a, 2021b). However, there is a scarcity in the literature on summarizing such determinants and giving a clear theoretical understanding of such determinants. Thus, our review study accomplishes this task by reviewing the previous empirical studies arranged on the topic of industrial investment and published in top-tier journals of finance1 during the last decade. The current study attempts to respond to the following research question.
- What are the major determinants of corporate physical investment decisions?
In addition to other business decisions, corporate managers should also focus on long-term sustainability in their structured decisions processes. They should establish efficient investment strategies to make the corporate firms confident about their future growth. From a corporate perspective, such strategies include, but are not limited to, achieving consistent sales growth, high profitability, more availability of funds, and higher returns on long-term investment (Ding et al. 2013). Such factors are more conducive in investment-intensive corporations that require substantial ramifications on the activities. Considering this, an array of empirical studies has attempted to find out the determinants that can escalate the investment decisions of corporate firms (Federic and Parisi 2015; Frésard and Valta 2016; Gao et al. 2019). Despite the enormous empirical studies, the literature is lacking in summarizing such determinants. Thus, this study addressed this gap by offering clear theoretical thoughts on corporate physical investment decisions.
The objective of the current study is to review the empirical findings of previous literature arranged on the theme of investment, specifically physical investment, and gives a clear theoretical understanding. For this purpose, we review the empirical studies published in three top-ranked journals of finance, including The Journal of Finance (JOF), The Review of Financial Studies (RFS), and The Journal of Financial Economics (JFE), during the period 2010 to 2022. Following the review analysis for studies published in the Journal of Finance, we noted that external financing, idiosyncratic risk, information asymmetry, firm age, the social connectivity of managers, behavioral biases, etc., are major determinants of investment decisions. Similarly, the review of studies published in RFS advocate that stock mispricing, country-level governance, cash holdings, loan availability, tax laws, employment protection laws, financing diversifications, etc., are the key factors that can influence investment decisions. Lastly, the review analysis for the studies published in JFE indicates that the Sarbanes-Oxley Act of 2002, herding behavior, political uncertainty, debt market access, managerial network, financial crisis, etc., are the main determinants of corporate investment decisions.
Our review study has several implications and literature contributions: first, this study reviews the large number of studies published in well-reputed journals and clearly guides on major determinants of investment decisions. Secondly, this review study tends to enhance the theoretical insights on relevant factors that can potentially determine industrial investment decisions. It further shows the significance of such factors in different eras and was considered by the research community. Third, this study can be a handful as an outline document of investment determinants for corporate managers because it provides a summarized review of a large body of literature. As for the concern of literature contribution, this study brings forward the empirical findings of past studies and adds new thoughts regarding determinants of corporate investment decisions. In literature, there exist numerous studies that empirically suggest the various determinants of industrial investment decisions, but no study has been found which offers such theoretical understanding. Thus, our study fulfills this instant gap in the literature by offering a review of studies and bringing them together into a single study. It was an immense need to summarize the voluminous literature published on investment during the recent decade.
Other parts of the paper consist of the following sections: Section 2 discusses the major theories on investment, Section 3 provides information on adopted methodology to obtain the objective. Section 4 attempts to conclude the whole discussion of the paper. The bibliographical detail of studies cited in the body of the paper is placed at the end of the paper.
2. Theoretical Review
According to Fisher (1930) and Keynes ([1936] 2007), corporate firms do not make an investment until the future cash flow is adjusted against the net present value (NPV) of future cash flow from such investment becomes zero. Thus, net present value is an important criterion for making any physical investment. Later, Markowitz (1952) clearly indicated the other factors, including discounted cash flow, payback period, internal rate of return, etc., for portfolio selection of investment. Since this, certain theories have emerged that tend to explain investment behavior. Such theories define the underlying assumptions on which investment decisions are based. These theories are as follows.
2.1. Neoclassical Theory of Investment
Jorgenson (1963) provided the concept of neoclassical investment theory for the first time. This theory is called neoclassical theory because it utilizes the basic neoclassical production function. The standard assumptions for this theory are as follows:
- No uncertainty exists in the market;
- The enterprises are operating in full perfect competition;
- There exists a maximum employment rate in an economy;
- There is an efficient financial market that can offer loans to the industrial sector at given interest rates;
- Corporate firms are able to maximize the net present value of present and future cash flows.
These assumptions somehow explain the basic requirements to achieve maximum corporate investment. However, the achievement of such assumptions in the real economy is hard. Thus, such fictitious assumptions led to the development of other investment theories.
2.2. Accelerator Theory of Investment
This theory was originally argued by Clark (1917). However, the development of theoretical notions of this theory was greatly influenced by Keynesian thoughts in the 20th Century. After this overlapping, the accelerator theory of investment becomes public knowledge. The accelerator theory of investment stipulates that capital expenses relating to investment are a function of macroeconomic outputs, i.e., demand and income. During a high GDP growth rate and income, the demand for industrial goods increases. In such a situation, the corporate sector responds to such increments in demand either by raising the price of products or by widening the production capacity through capital investment. According to accelerator theory, corporate firms typically choose to enhance production through capital investment and thereby boosting profitability. Given that, it can be comprehended that macroeconomic factors, e.g., GDP growth rate and income, can induce more capital investment across the industrial sector. Supporting this, the study of Farooq et al. (2021a) has explicitly illustrated the pivotal role of macroeconomic factors in determining capital investment decisions. Kong et al. (2022) asserted that economic uncertainty inhibits corporate investment, which further has a material impact on corporate performance. Islam et al. (2022) vowed that corporate investment is a key determinant of corporate financial performance. Salehi et al. (2022) supported the positive link between investment efficiency and firm value. Their study further reveals the moderating role of board independence and institutional ownership.
2.3. Q Theory of Investment
There were some fundamental flaws in both neoclassical theory and accelerator theory. First, both theories vowed that the adjustment of capital is instantaneously relevant to each period. However, there also exists a role of adjustment costs function. Secondly, there is no importance of future expectations in making the investment. Resolving such ambiguities, Brainard and Tobin (1968) and Tobin (1969) offered a new investment theory that advocates that corporations do not make the investment until the replacement cost of existing assets become equal to the market value of assets. Thus, this theory provides a more relevant understanding by adding the adjustment cost function of investment into the profit function. According to the Q theory of investment, corporate firms make the physical capital investment when the replacement cost of such investment is less than the market value of installed capital. This theory is also known as Tobin’s Q theory, where q can be calculated as:
2.4. The Internal Funds Theory of Investment
Tinbergen (1938) argued this theory for the first time. Following the conjectures of the internal funds theory of investment, the decision related to desired capital stock or investment is mainly dependent upon profit volume. Investment decisions are presumably attached to profitability capacity as it ensures the availability of funds for new investments. Alternatively, the corporate managers often make the investment following the availability of both internal and external funds, i.e., capital reserve, depreciation expenses that are set aside to adjust the depreciation expenses in the net value of assets, sale of stock, and other miscellaneous internal borrowings, e.g., the sale of bonds. Internally, the capital reserve or retained earnings and funds set aside for depreciation urge the corporate managers to acquire the new physical assets categorized as capital investment. Externally, corporate firms acquire the funds by issuing equity stock and bonds to make the investment. However, firms are often reluctant to acquire the borrowings through external sources due to fear of control loss and a high probability of bankruptcy. Due to such reasons, the proponents of the internal funds theory contend that corporate firms should arrange more funds for investment internally by focusing on profitability. In line with such theoretical notions, it can be advocated that internal funds and profitability ratio are two potential factors that can determine investment decisions.
3. Material and Methods
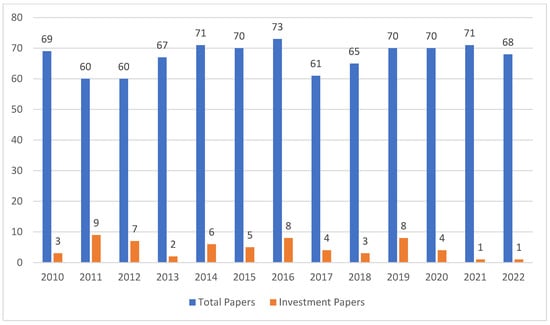
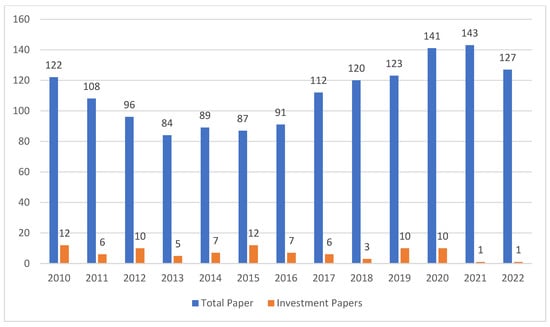
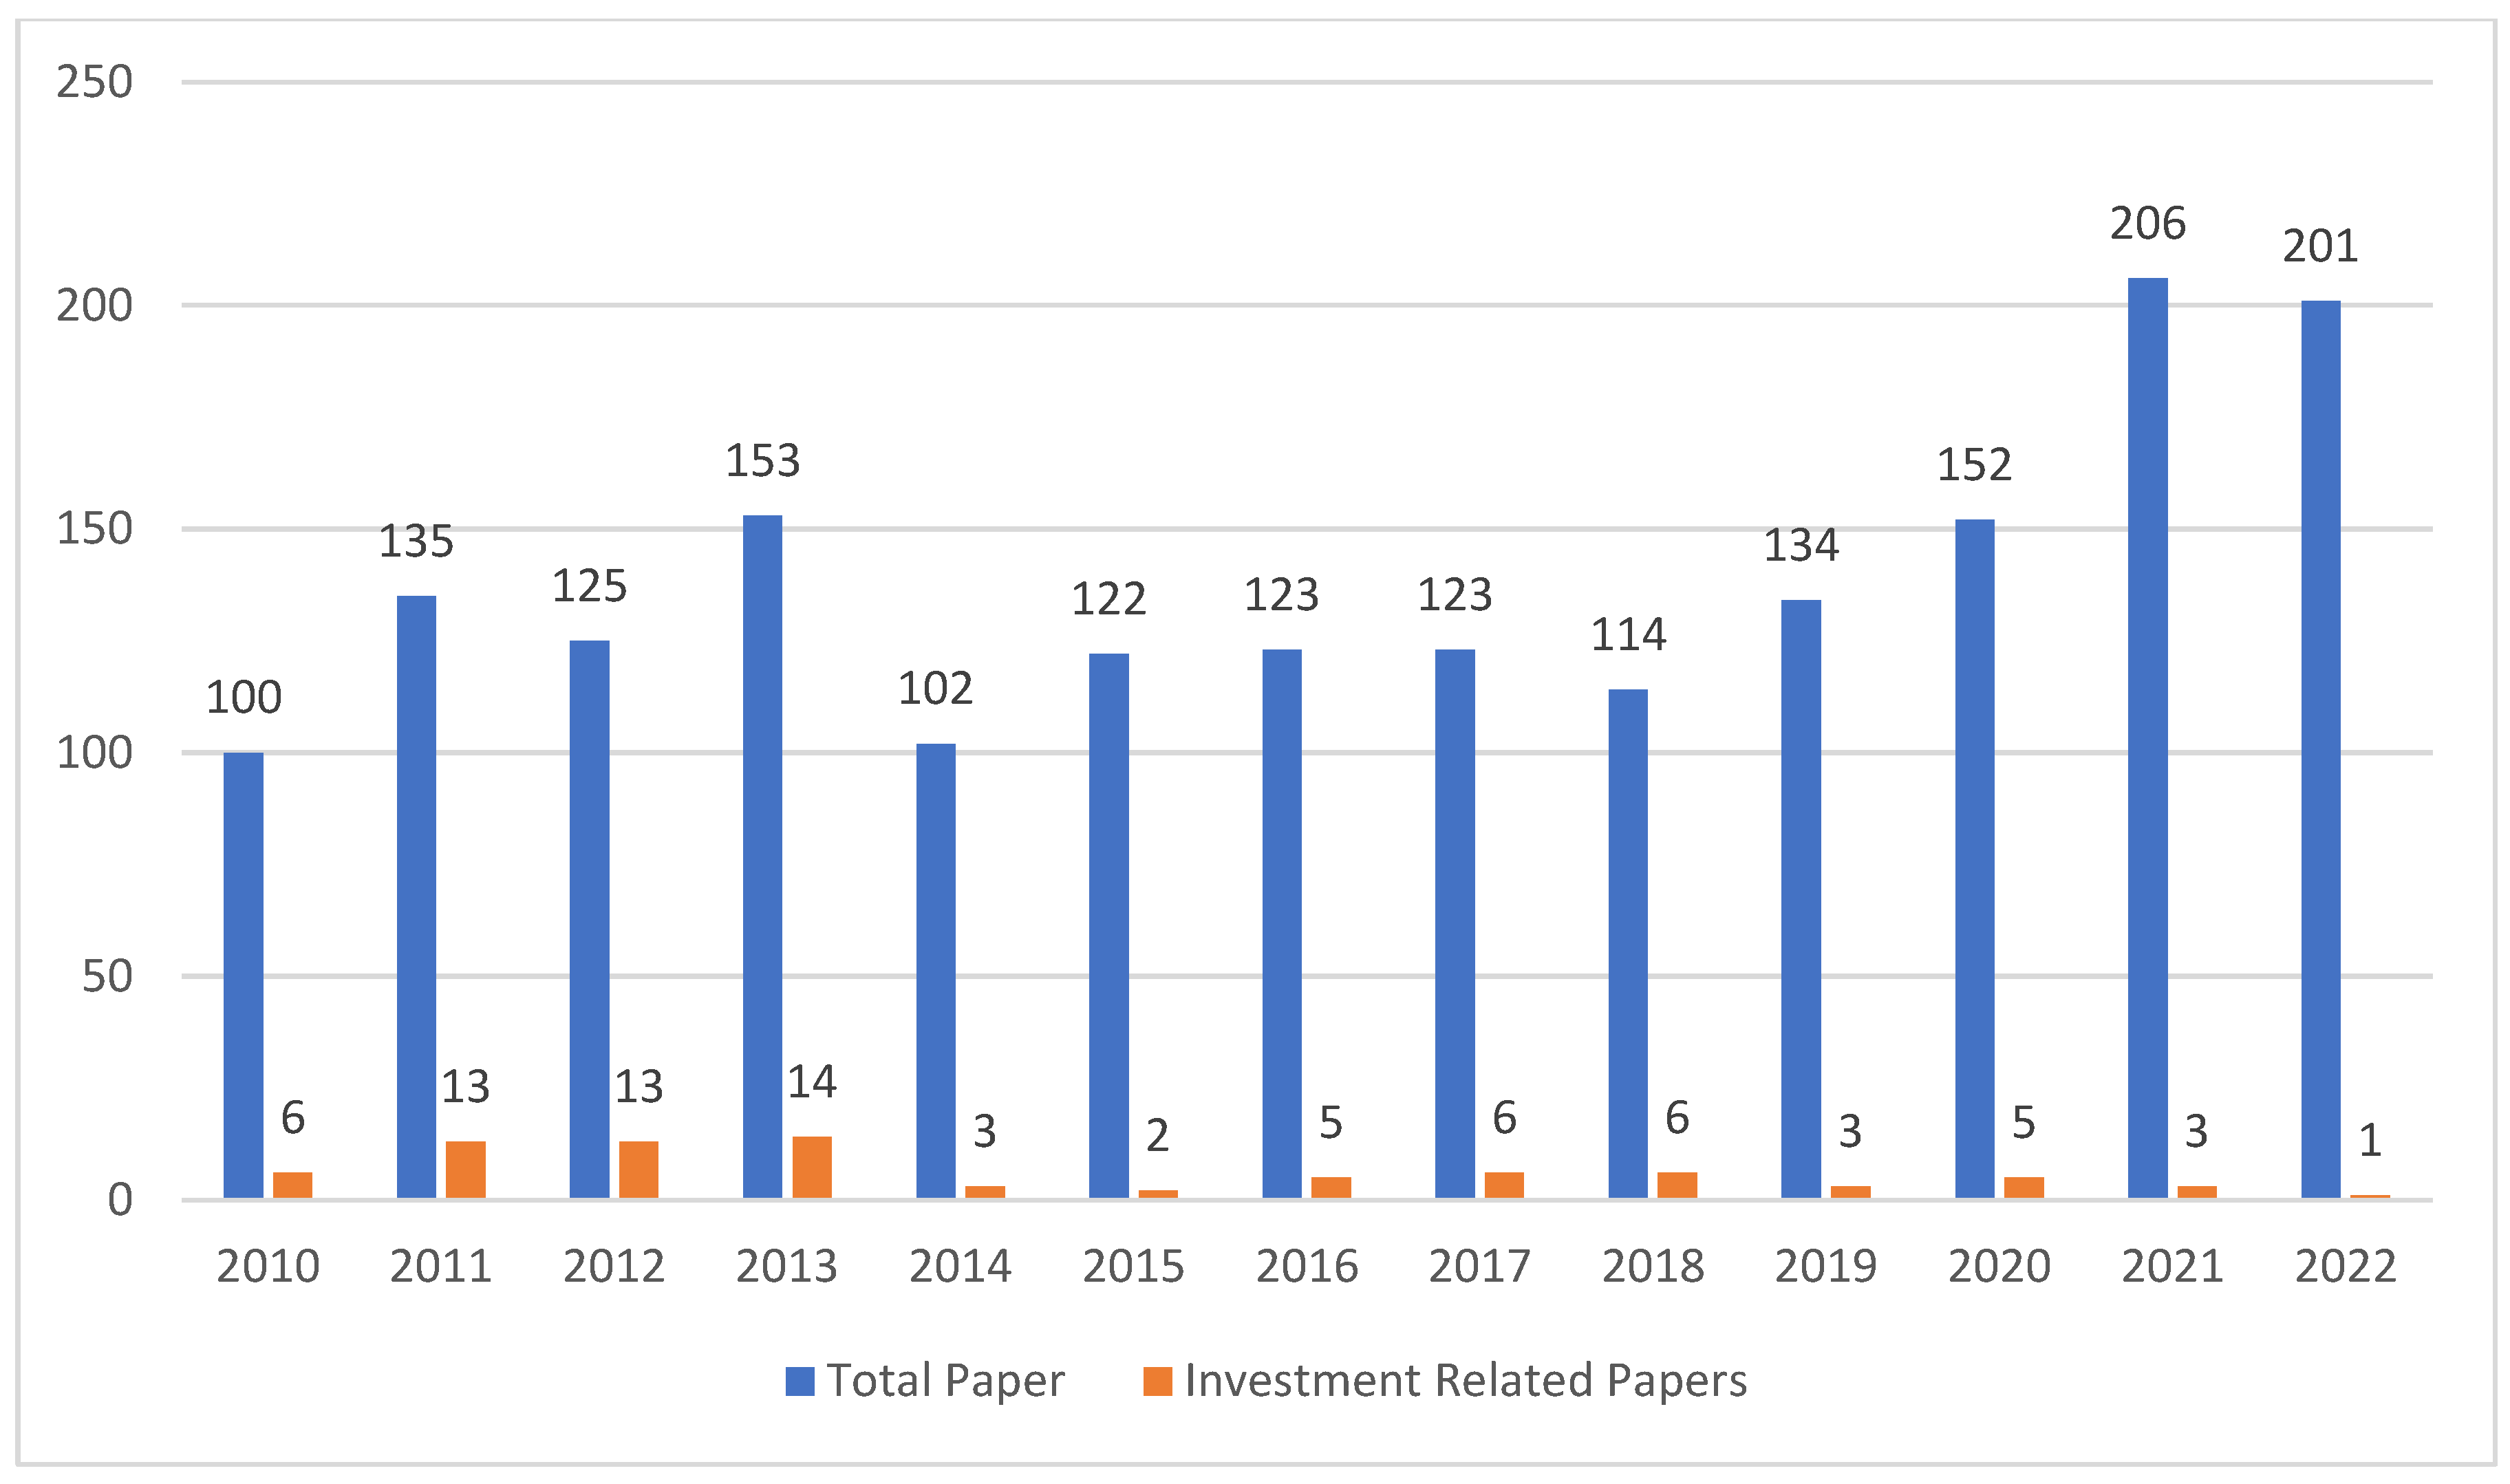
This review analysis is based upon the review of 13 years of investment literature ranging from 2010 to 2022 and published in different issues of the top three journals named The Journal of Finance (JOF), The Review of Financial Studies (RFS), and The Journal of Financial Economics (JFE). The initial population size for JOF consists of 875 articles published in 13 volumes (vol. 65 to vol. 77) and 77 issues. However, we have scrutinized the articles on the criterion of the word “investment” in the title and selected 61 articles for final review. Figure 1 provides the relevant information on the intensity of the total and selected articles for review. The publication intensity of investment articles in JOF is 6.971%. Similarly, the total strength of articles published in RFS during the selected span is 1443. For RFS, we have reviewed the 13 volumes (vol. 23 to vol. 35) and 156 issues and found the 90 articles that contained the word “investment” in the title. The intensity of investment-related articles in RFS is 6.237%. As likely to JOF and RFS, we have followed a similar criterion for JFE and reviewed the 51 volumes (vol. 95 to vol. 146) and 155 issues. The total strength of published articles in JFE is 1790, while on investment, it is 80 (4.469% of total strength). In our final review analysis, we mainly focused on the articles that discussed physical investment and its related determinants. Such a winnowing tool helps to focus on more specific articles and summarize the discussion. Figure 2 and Figure 3 exemplify the comparison between total and selected articles for the journals of RFS and JFE.
Figure 1.
Intensity of Papers Published in JOF. Source: The information on the intensity of papers has been extracted from papers published in different volumes and respective issues. Note: Figure 1 shows the relevant comparison between the total number of papers and papers on investment published in The Journal of Finance.
Figure 2.
Comparison of Papers Published in RFS. Source: The Review of Financial Studies (RFS). Note: Figure 2 compares the studies published in RFS during the period 2010 to 2022.
Figure 3.
Comparative Analysis for JFE. Source: Journal of Financial Economics (JFE). Note: Figure 3 illustrates the total number of papers and papers on investment published in JFE from 2010 to 2022.
4. Conclusions and Implications
In the literature on finance, the discussion on corporate investment decisions, specifically physical investment, has attracted the attention of researchers. The topic of investment has gained more popularity since the seminal works of Markowitz (1952) and Sharpe (1964). A stream of recent studies was found in the literature that tends to explain the different factors influencing investment decisions. However, the literature is scarce on summarizing the voluminous empirical literature and giving better theoretical insights. Given that, this study attempted to review the empirical studies about corporate investment that were published in the top three journals of finance, including The Journal of Finance, The Review of Financial Studies, and The Journal of Financial Economics. We have reviewed the studies published in the journals during the period 2010 to 2022. The theoretical review of previous studies, as appeared in Table 1, Table 2 and Table 3, offers knowledge on various factors that can determine investment and be comprehended by the research community. Based on the review analysis, some prominent factors that can influence investment decisions are peer effect, the network connection of managers, internal funds, information asymmetric, governance, financial crisis, policy uncertainty, financing diversification, idiosyncratic risk, cash holdings, etc. Additionally, the emergence of such factors from the review of studies demonstrates the association of such factors with investment decisions.
Table 1.
Analysis of Studies Published in The Journal of Finance.
Table 2.
Key Empirical Findings of Studies Published in Review of Financial Studies.
Table 3.
A Pilot-view of Studies Published in Journal of Financial Economics.
Our review analysis has several implications for corporate managers and researchers. This study provides comprehensive guidance to investment managers on different factors that can affect investment decisions. This study can be a handful for investment managers to comprehend the dynamic role (both negative and positive) of different factors in determining investment decisions. The current study brings voluminous literature together and offers a brief understanding of various determinants of investment decisions. For the research community, this study urges them to think about investment determinants and augment the existing literature by exploring the other factors that can affect investment decisions. However, our study is limited to not including the other well-known journals in the review analysis due to time limitations. Future studies can be arranged by setting the other criterion, i.e., country and methodology distinctions, and adding more journals to the analysis.
Author Contributions
U.F.: Conceptualization, Data curation, Writing—Original draft preparation; M.I.T.: Writing—Original draft, methodology, Supervision; A.A.A.-N.: Data curation, Reviewing and Editing, Methodology; K.D.: formal analysis, Conceptualization, Software. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Data Availability Statement
Not applicable.
Conflicts of Interest
The authors declare no conflict of interest.
Declaration
We declare that the paper can be dispatched for exclusive consideration by the Journal and has not been sent elsewhere for publication.
Note
| 1 | According to JCR (journal citation report) journal lists, the top three journals of finance are The Journal of Finance (JF), The Review of Financial Studies (RFS), and The Journal of Financial Economics (JFE). |
References
- Abel, Andrew B., and Stavros Panageas. 2022. An Analytic Framework for Interpreting Investment Regressions in the Presence of Financial Constraints. The Review of Financial Studies 35: 4055–104. [Google Scholar] [CrossRef] [Scilit]
- Adelino, Manuel, Katharina Lewellen, and Anant Sundaram. 2015. Investment Decisions of Nonprofit Firms: Evidence from Hospitals. The Journal of Finance 70: 1583–628. [Google Scholar] [CrossRef] [Scilit]
- Adelino, Manuel, Song Ma, and David Robinson. 2017. Firm Age, Investment Opportunities, and Job Creation. The Journal of Finance 72: 999–1038. [Google Scholar] [CrossRef] [Scilit]
- Ai, Hengjie, and Rui Li. 2015. Investment and CEO compensation under limited commitment. Journal of Financial Economics 116: 452–72. [Google Scholar]
- Ajide, Folorunsho M. 2017. Firm-specific, and Institutional Determinants of Corporate Investments in Nigeria. Future Business Journal 3: 107–18. [Google Scholar] [CrossRef] [Scilit]
- Alti, Aydoğan, and Paul C. Tetlock. 2014. Biased Beliefs, Asset Prices, and Investment: A Structural Approach. The Journal of Finance 69: 325–61. [Google Scholar] [CrossRef] [Scilit]
- Arif, Salman, and Charles M. C. Lee. 2014. Aggregate Investment and Investor Sentiment. The Review of Financial Studies 27: 3241–79. [Google Scholar] [CrossRef] [Scilit]
- Asker, John, Joan Farre-Mensa, and Alexander Ljungqvist. 2015. Corporate Investment and Stock Market Listing: A Puzzle? The Review of Financial Studies 28: 342–90. [Google Scholar] [CrossRef] [Scilit]
- Babenko, Ilona, Michael Lemmon, and Yuri Tserlukevich. 2011. Employee Stock Options and Investment. The Journal of Finance 66: 981–1009. [Google Scholar]
- Bai, John, Douglas Fairhurst, and Matthew Serfling. 2020. Employment Protection, Investment, and Firm Growth. The Review of Financial Studies 33: 644–88. [Google Scholar] [CrossRef] [Scilit]
- Bakke, Tor-Erik, and Toni M. Whited. 2010. Which Firms Follow the Market? An Analysis of Corporate Investment Decisions. The Review of Financial Studies 23: 1941–80. [Google Scholar] [CrossRef] [Scilit]
- Barattieri, Alessandro, Laura Moretti, and Vincenzo Quadrini. 2021. Banks funding, leverage, and investment. Journal of Financial Economics 141: 148–71. [Google Scholar] [CrossRef] [Scilit]
- Bargeron, Leonce, David Denis, and Kenneth Lehn. 2018. Financing Investment Spikes in the Years Surrounding World War I. Journal of Financial Economics 130: 215–36. [Google Scholar] [CrossRef] [Scilit]
- Bernard, Darren, Terrence Blackburne, and Jacob Thornock. 2020. Information Flows among Rivals and Corporate Investment. Journal of Financial Economics 136: 760–79. [Google Scholar] [CrossRef] [Scilit]
- Bharath, Sreedhar, Amy Dittmar, and Jagadeesh Sivadasan. 2014. Do Going-Private Transactions Affect Plant Efficiency and Investment? The Review of Financial Studies 27: 1929–76. [Google Scholar] [CrossRef] [Scilit]
- Billett, Matthew T., Jon A. Garfinkel, and Yi Jiang. 2011. The influence of governance on investment: Evidence from a hazard model. Journal of Financial Economics 102: 643–70. [Google Scholar] [CrossRef] [Scilit]
- Bolton, Patrick, Hui Chen, and Neng Wang. 2011. A Unified Theory of Tobin’s q, Corporate Investment, Financing, and Risk Management. The Journal of Finance 66: 1545–78. [Google Scholar] [CrossRef] [Scilit]
- Bottazzi, Laura, Marco Da Rin, and Thomas Hellmann. 2016. The Importance of Trust for Investment: Evidence from Venture Capital. The Review of Financial Studies 29: 2283–318. [Google Scholar] [CrossRef] [Scilit]
- Brainard, William C., and James Tobin. 1968. Pitfalls in Financial Model Building. The American Economic Review 58: 99–122. [Google Scholar]
- Bustamante, M. Cecilia. 2015. Strategic Investment and Industry Risk Dynamics. The Review of Financial Studies 28: 297–341. [Google Scholar] [CrossRef] [Scilit]
- Butler, Alexander W., Jess Cornaggia, Gustavo Grullon, and James P. Weston. 2011. Corporate financing decisions, managerial market timing, and real investment. Journal of Financial Economics 101: 666–83. [Google Scholar] [CrossRef] [Scilit]
- Caggese, Andrea. 2012. Entrepreneurial risk, investment, and innovation. Journal of Financial Economics 106: 287–307. [Google Scholar] [CrossRef] [Scilit]
- Campello, Murillo, Erasmo Giambona, John R. Graham, and Campbell R. Harvey. 2011. Liquidity Management and Corporate Investment During a Financial Crisis. The Review of Financial Studies 24: 1944–79. [Google Scholar] [CrossRef] [Scilit]
- Cavagnaro, Daniel R., Berk A. Sensoy, Yingdi Wang, and Michael S. Weisbach. 2019. Measuring Institutional Investors’ Skill at Making Private Equity Investments. The Journal of Finance 74: 3089–134. [Google Scholar] [CrossRef] [Scilit]
- Cingano, Federico, Francesco Manaresi, and Enrico Sette. 2016. Does Credit Crunch Investment Down? New Evidence on the Real Effects of theBank-Lending Channel. The Review of Financial Studies 29: 2737–73. [Google Scholar] [CrossRef] [Scilit]
- Clark, J. Maurice. 1917. Business Acceleration and the Law of Demand: A Technical Factor in Economic Cycles. Journal of Political Economy 25: 217–35. [Google Scholar] [CrossRef] [Scilit]
- DeMarzo, Peter M., Michael J. Fishman, Zhiguo He, and Neng Wang. 2012. Dynamic Agency and the q Theory of Investment. The Journal of Finance 67: 2295–340. [Google Scholar] [CrossRef] [Scilit]
- Denis, David J., and Valeriy Sibilkov. 2010. Financial Constraints, Investment, and the Value of Cash Holdings. The Review of Financial Studies 23: 247–69. [Google Scholar] [CrossRef] [Scilit]
- Dessaint, Olivier, Thierry Foucault, Laurent Frésard, and Adrien Matray. 2019. Noisy Stock Prices and Corporate Investment. The Review of Financial Studies 32: 2626–72. [Google Scholar] [CrossRef] [Scilit]
- Dicks, David, and Paolo Fulghieri. 2021. Uncertainty, Investor Sentiment, and Innovation. The Review of Financial Studies 34: 1236–79. [Google Scholar] [CrossRef] [Scilit]
- Ding, Sai, Alessandra Guariglia, and John Knight. 2013. Investment and financing constraints in China: Does working capital management make a difference? Journal of Banking & Finance 37: 1490–507. [Google Scholar]
- Duchin, Ran, Oguzhan Ozbas, and Berk A. Sensoy. 2010. Costly external finance, corporate investment, and the subprime mortgage credit crisis. Journal of Financial Economics 97: 418–35. [Google Scholar] [CrossRef] [Scilit]
- Edmans, Alex, Vivian W. Fang, and Katharina A. Lewellen. 2017. Equity Vesting and Investment. The Review of Financial Studies 30: 2229–71. [Google Scholar] [CrossRef] [Scilit]
- Fakos, Alexandros, Plutarchos Sakellaris, and Tiago Tavares. 2022. Investment slumps during financial crises: The real effects of credit supply. Journal of Financial Economics 145: 29–44. [Google Scholar] [CrossRef] [Scilit]
- Farooq, Umar, and Bilal Haider Subhani. 2021. Three Corporate Finance Practices in Pakistan: A Review of Previous Studies and Way Forward. Journal of Finance and Accounting Research 3: 61–84. [Google Scholar] [CrossRef] [Scilit]
- Farooq, Umar, Jaleel Ahmed, and Shamshair Khan. 2021a. Do the Macroeconomic Factors Influence the Firm’s Investment Decisions? A Generalized Method of Moments (GMM) Approach. International Journal of Finance and Economics 26: 790–801. [Google Scholar] [CrossRef] [Scilit]
- Farooq, Umar, Jaleel Ahmed, Mosab I. Tabash, Suhaib Anagreh, and Bilal Haider Subhani. 2021b. Nexus between Government Green Environmental Concerns and Corporate real Investment: Empirical evidence from selected Asian Economies. Journal of Cleaner Production 314: 128089. [Google Scholar] [CrossRef] [Scilit]
- Faulkender, Michael, and Mitchell Petersen. 2012. Investment and Capital Constraints: Repatriations Under the American Jobs Creation Act. The Review of Financial Studies 25: 3351–88. [Google Scholar] [CrossRef] [Scilit]
- Favara, Giovanni. 2012. Agency Problems and Endogenous Investment Fluctuations. The Review of Financial Studies 25: 2301–42. [Google Scholar] [CrossRef] [Scilit]
- Favara, Giovanni, Erwan Morellec, Enrique Schroth, and Philip Valta. 2017. Debt enforcement, investment, and risk taking across countries. Journal of Financial Economics 123: 22–41. [Google Scholar] [CrossRef] [Scilit]
- Federici, Daniela, and Valentino Parisi. 2015. Do corporate taxes reduce investments? Evidence from Italian firm-level panel data. Cogent Economics & Finance 3: 1–14. [Google Scholar]
- Fisher, Irving. 1930. The Theory of Interest. New York: Macmillan Co. [Google Scholar]
- Foucault, Thierry, and Laurent Fresard. 2014. Learning from peers’ stock prices and corporate investment. Journal of Financial Economics 111: 554–77. [Google Scholar] [CrossRef] [Scilit]
- Frank, Murray Z., and Tao Shen. 2016. Investment and the weighted average cost of capital. Journal of Financial Economics 119: 300–15. [Google Scholar] [CrossRef] [Scilit]
- Frésard, Laurent, and Philip Valta. 2016. How Does Corporate Investment Respond to Increased Entry Threat? The Review of Corporate Finance Studies 5: 1–35. [Google Scholar] [CrossRef] [Scilit]
- Gale, Douglas, and Piero Gottardi. 2015. Capital Structure, Investment, and Fire Sales. The Review of Financial Studies 28: 2502–33. [Google Scholar] [CrossRef] [Scilit]
- Gao, Shenghao, Liming Wang, Ningyue Liu, and Min Zhang. 2019. Fiscal Decentralization and Corporate Investment: Empirical Evidence from China. Journal of Economic Policy Reform 22: 51–68. [Google Scholar] [CrossRef] [Scilit]
- Gilje, Erik P., and Jerome P. Taillard. 2016. Do Private Firms Invest Differently than Public Firms? Taking Cues from the Natural Gas Industry. The Journal of Finance 71: 1733–78. [Google Scholar] [CrossRef] [Scilit]
- Goldstein, Itay, and Chong Huang. 2020. Credit Rating Inflation and Firms’ Investments. The Journal of Finance 75: 2929–72. [Google Scholar] [CrossRef] [Scilit]
- Grieser, William, and Zack Liu. 2019. Corporate Investment and Innovation in the Presence of Competitor Constraints. The Review of Financial Studies 32: 4271–303. [Google Scholar] [CrossRef] [Scilit]
- Guceri, Irem, and Maciej Albinowski. 2021. Investment responses to tax policy under uncertainty. Journal of Financial Economics 141: 1147–70. [Google Scholar] [CrossRef] [Scilit]
- Gulen, Huseyin, and Mihai Ion. 2016. Policy Uncertainty and Corporate Investment. The Review of Financial Studies 29: 523–64. [Google Scholar] [CrossRef] [Scilit]
- Hackbarth, Dirk, and David C. Mauer. 2012. Optimal Priority Structure, Capital Structure, and Investment. The Review of Financial Studies 25: 747–96. [Google Scholar] [CrossRef] [Scilit]
- Harford, Jarrad, and Vahap B. Uysal. 2014. Bond market access and investment. Journal of Financial Economics 112: 147–63. [Google Scholar] [CrossRef] [Scilit]
- Hugonnier, Julien, Semyon Malamud, and Erwan Morellec. 2015. Capital Supply Uncertainty, Cash Holdings, and Investment. The Review of Financial Studies 28: 391–445. [Google Scholar] [CrossRef] [Scilit]
- Islam, Muhammad Saif Ul, Muhammad Saeed Meo, and Muhammad Usman. 2022. The relationship between corporate investment decision and firm performance: Moderating role of cash flows. Journal of Public Affairs 22: e2445. [Google Scholar]
- Jacob, Martin, Roni Michaely, and Maximilian A. Müller. 2019. Consumption Taxes and Corporate Investment. The Review of Financial Studies 32: 3144–82. [Google Scholar] [CrossRef] [Scilit]
- Jens, Candace E. 2017. Political Uncertainty and Investment: Causal Evidence from U.S. Gubernatorial Elections. Journal of Financial Economics 124: 563–79. [Google Scholar] [CrossRef] [Scilit]
- Jorgenson, Dale Weldeau. 1963. Capital Theory and Investment Behavior. The American Economic Review 53: 247–59. [Google Scholar]
- Julio, Brandon, and Youngsuk Yook. 2012. Political Uncertainty and Corporate Investment Cycles. The Journal of Finance 67: 45–83. [Google Scholar] [CrossRef] [Scilit]
- Kahle, Kathleen M., and René M. Stulz. 2013. Access to capital, investment, and the financial crisis. Journal of Financial Economics 110: 280–99. [Google Scholar] [CrossRef] [Scilit]
- Kang, Qiang, Qiao Liu, and Rong Qi. 2010. The Sarbanes-Oxley act and corporate investment: A structural assessment. Journal of Financial Economics 96: 291–305. [Google Scholar] [CrossRef] [Scilit]
- Keynes, John Maynard. 2007. The General Theory of Employment, Interest and Money. London: Palgrave Macmillan. First published 1936. [Google Scholar]
- Kim, Hyunseob, and Howard Kung. 2017. The Asset Redeployability Channel: How Uncertainty Affects Corporate Investment. The Review of Financial Studies 30: 245–80. [Google Scholar] [CrossRef] [Scilit]
- Kong, Qunxi, Rongrong Li, Ziqi Wang, and Dan Peng. 2022. Economic policy uncertainty and firm investment decisions: Dilemma or opportunity? International Review of Financial Analysis 83: 102301. [Google Scholar] [CrossRef] [Scilit]
- Kumar, Praveen, and Dongmei Li. 2016. Capital Investment, Innovative Capacity, and Stock Returns. The Journal of Finance 71: 2059–94. [Google Scholar] [CrossRef] [Scilit]
- Lambrecht, Bart M., and Stewart C. Myers. 2017. The Dynamics of Investment, Payout and Debt. The Review of Financial Studies 30: 3759–800. [Google Scholar] [CrossRef] [Scilit]
- Lerner, Josh, Morten Sorensen, and Per Strömberg. 2011. Private Equity and Long-Run Investment: The Case of Innovation. The Journal of Finance 66: 445–77. [Google Scholar] [CrossRef] [Scilit]
- Leuz, Christian, Karl V. Lins, and Francis E. Warnock. 2010. Do Foreigners Invest Less in Poorly Governed Firms? The Review of Financial Studies 22: 3245–85. [Google Scholar] [CrossRef] [Scilit]
- Li, Qingyuan, Chen Lin, and Li Xu. 2020. Political Investment Cycles of State-Owned Enterprises. The Review of Financial Studies 33: 3088–129. [Google Scholar] [CrossRef] [Scilit]
- Lin, Xiaoji, Chong Wang, Neng Wang, and Jinqiang Yang. 2018. Investment, Tobin’s q, and interest rates. Journal of Financial Economics 130: 620–40. [Google Scholar] [CrossRef] [Scilit]
- Livdan, Dmitry, and Alexander Nezlobin. 2021. Investment, capital stock, and replacement cost of assets when economic depreciation is non-geometric. Journal of Financial Economics 142: 1444–69. [Google Scholar] [CrossRef] [Scilit]
- Lyandres, Evgeny, Maria-Teresa Marchica, Roni Michaely, and Roberto Mura. 2019. Owners’ Portfolio Diversification and Firm Investment. The Review of Financial Studies 32: 4855–904. [Google Scholar] [CrossRef] [Scilit]
- Markowitz, Harry. 1952. Portfolio Selection. The Journal of Finance 7: 77–91. [Google Scholar]
- McLean, R. David, and Mengxin Zhao. 2014. The Business Cycle, Investor Sentiment, and Costly External Finance. The Journal of Finance 69: 1377–409. [Google Scholar] [CrossRef] [Scilit]
- McLean, R. David, Tianyu Zhang, and Mengxin Zhao. 2012. Why Does the Law Matter? Investor Protection and its Effects on Investment Finance. The Journal of Finance 67: 313–50. [Google Scholar] [CrossRef] [Scilit]
- Meeuwis, Maarten, Jonathan A. Parker, Antoinette Schoar, and Duncan Simester. 2022. Belief Disagreement and Portfolio Choice. The Journal of Finance 77: 3191–247. [Google Scholar] [CrossRef] [Scilit]
- Morellec, Erwan, and Norman Schürhoff. 2010. Dynamic Investment and Financing under Personal Taxation. The Review of Financial Studies 23: 101–46. [Google Scholar] [CrossRef] [Scilit]
- Morellec, Erwan, and Norman Schürhoff. 2011. Corporate investment and financing under asymmetric information. Journal of Financial Economics 99: 262–88. [Google Scholar] [CrossRef] [Scilit]
- Ouimet, Paige, and Geoffrey Tate. 2020. Learning from Coworkers: Peer Effects on Investment Decisions. The Journal of Finance 75: 133–72. [Google Scholar] [CrossRef] [Scilit]
- Ozdagli, Ali K. 2012. Financial Leverage, Corporate Investment, and Stock Returns. The Review of Financial Studies 25: 1033–69. [Google Scholar] [CrossRef] [Scilit]
- Panousi, Vasia, and Dimitris Papanikolaou. 2012. Investment, Idiosyncratic Risk, and Ownership. The Journal of Finance 67: 1113–48. [Google Scholar] [CrossRef] [Scilit]
- Peters, Ryan H., and Lucian A. Taylor. 2017. Intangible capital and the investment-q relation. Journal of Financial Economics 123: 251–72. [Google Scholar] [CrossRef] [Scilit]
- Rahayu, Sri Mangesti. 2019. Mediation Effects Financial Performance toward Influences of Corporate Growth and Assets Utilization. International Journal of Productivity and Performance Management 68: 981–96. [Google Scholar] [CrossRef] [Scilit]
- Rantala, Ville. 2019. How Do Investment Ideas Spread through Social Interaction? Evidence from a Ponzi Scheme. The Journal of Finance 74: 2349–89. [Google Scholar] [CrossRef] [Scilit]
- Rossi, Alberto G., David Blake, Allan Timmermann, Ian Tonks, and Russ Wermers. 2018. Network centrality and delegated investment performance. Journal of Financial Economics 128: 183–206. [Google Scholar] [CrossRef] [Scilit]
- Salehi, Mahdi, Grzegorz Zimon, Arash Arianpoor, and Fatemeh Eidi Gholezoo. 2022. The Impact of Investment Efficiency on Firm Value and Moderating Role of Institutional Ownership and Board Independence. Journal of Risk and Financial Management 15: 170. [Google Scholar] [CrossRef] [Scilit]
- Schneider, Christoph, and Oliver Spalt. 2016. Conglomerate Investment, Skewness, and the CEO Long-Shot Bias. The Journal of Finance 71: 635–72. [Google Scholar] [CrossRef] [Scilit]
- Sharpe, William F. 1964. Capital asset Prices: A Theory of Market Equilibrium under Conditions of Risk. Journal of Finance 19: 425–42. [Google Scholar]
- Tinbergen, Jan. 1938. Statistical Evidence on the Acceleration Principle. Economica 5: 164–76. [Google Scholar] [CrossRef] [Scilit]
- Tobin, James. 1969. A General Equilibrium Approach To Monetary Theory. Journal of Money, Credit and Banking 1: 15–29. [Google Scholar] [CrossRef] [Scilit]
- Tsoutsoura, Margarita. 2015. The Effect of Succession Taxes on Family Firm Investment: Evidence from a Natural Experiment. The Journal of Finance 70: 649–88. [Google Scholar] [CrossRef] [Scilit]
- Ungeheuer, Michael, and Martin Weber. 2021. The Perception of Dependence, Investment Decisions, and Stock Prices. Journal of Finance 76: 797–844. [Google Scholar] [CrossRef] [Scilit]
- Warusawitharana, Missaka, and Toni M. Whited. 2016. Equity Market Misvaluation, Financing, and Investment. The Review of Financial Studies 29: 603–54. [Google Scholar]

Publisher’s Note: MDPI stays neutral with regard to jurisdictional claims in published maps and institutional affiliations. |
© 2022 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).