


Abstract
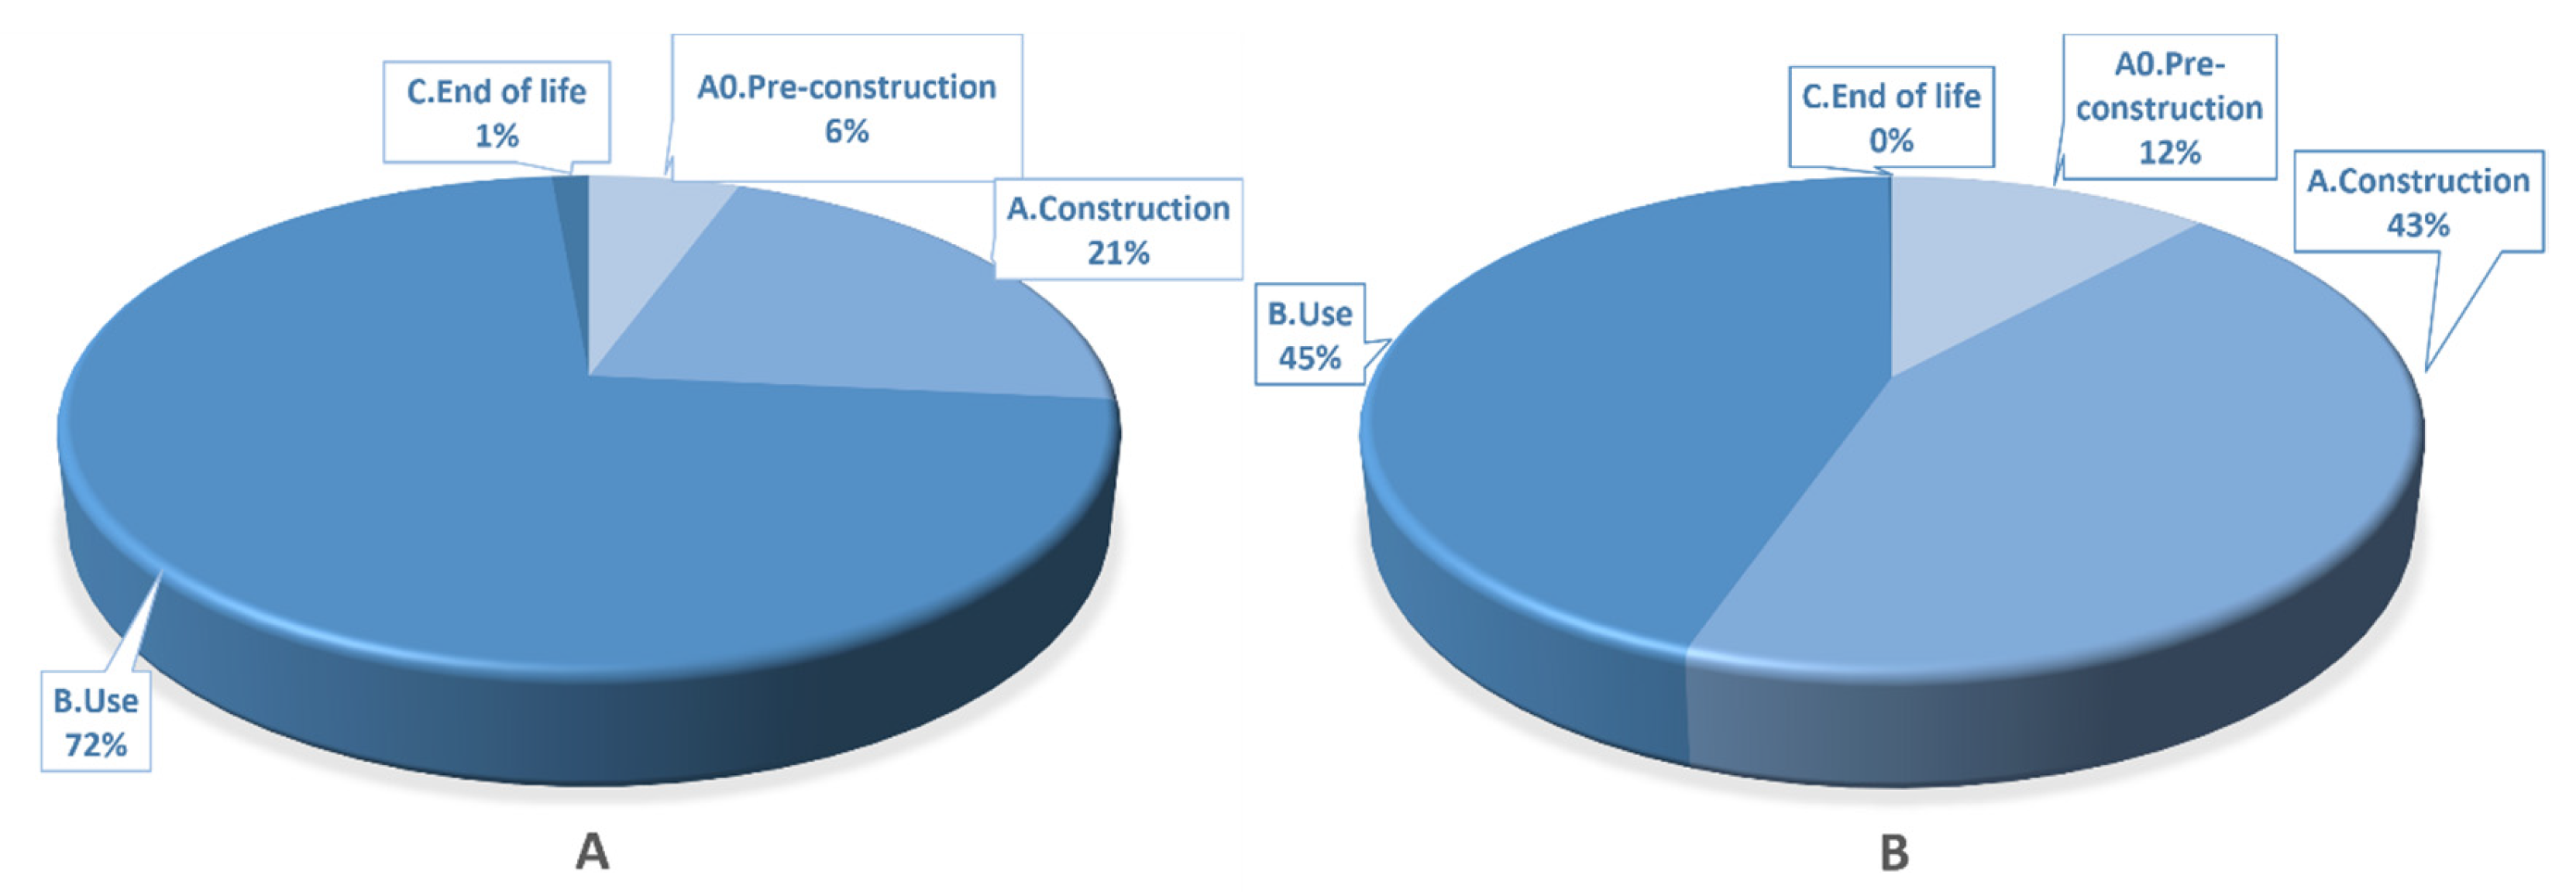
The tools used for budgeting in the building design phase are still insufficient to address the life cycle of the building in terms of environmental and cost impacts. The main objective of this research is to define a model for extending existing cost databases to accommodate life cycle sustainability assessment. For this, current classification systems are reviewed and a case study has been analysed using the new approach. To this end, a new system of classification of construction information is proposed for the evaluation of early design costs, when data are scarce and the only information available refers to the gross interior area and the plot. The classification organizes the costs in a similar way to the sustainability assessment in EN-15643. A subcategory has been added for revenue, developer costs, and taxes at all stages of the lifecycle. The resulting classification is applied to the functional elements of a secondary school project. In the case study, construction costs represent 21% while the use stage accounts for 72% in a 100-year lifespan. The results show that, starting from generic cost bases, more complex costs and functional costs can be defined at different stages of the life cycle and adjusted to sustainability assessment standards.
1. Introduction
It has become essential for the construction sector to act in order to achieve a sustainable economic model, since it represents 13% of the world’s GDP [1], 5.4% in the European Union, and 5.7% in Spain [2]. Furthermore, buildings have a long life cycle, and hence they have an impact, not only when they are first built, but throughout their useful life. For example, the operating costs of buildings can account for more than 40% of their total expenses [3]. This takes on special significance in the construction of public works, since their costs represent a long-term commitment of public funds [4]. Life cycle cost (LCC) must be addressed in order to analyse the economic sustainability of construction.
In 2014, the European Union introduced the LCC concept in the evaluation of public tenders through Directive 2014/24/EU [5]. The directive contains criteria for awarding public contracts that include economic, environmental, and social aspects, and places emphasis on the LCC indicator, which makes it possible to control the cost of the construction of the building, and of all the subsequent stages of the life cycle: use, maintenance, and end of life. This indicator is used, among others, in the sustainability assessment of Level(s) [6] and BREEAM [7].
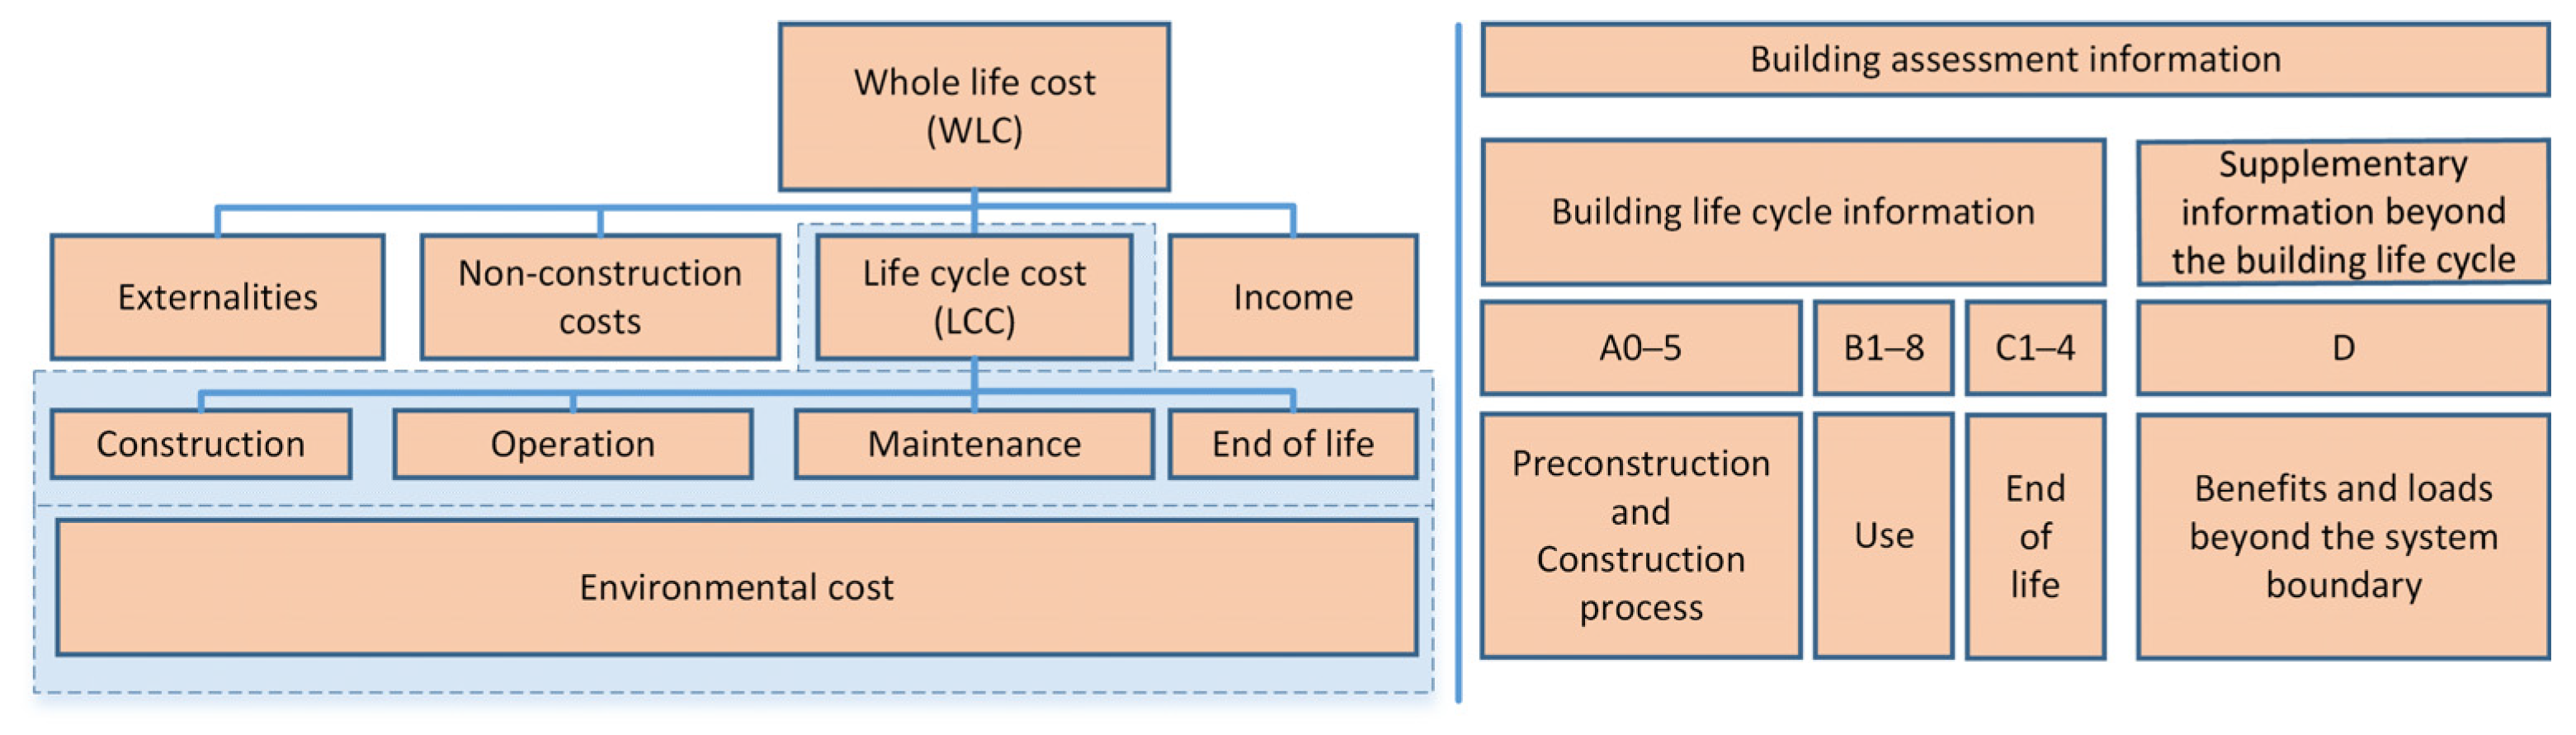
The LCC indicator is not a new concept; it was first applied in the mid-20th century in the military industry [8]. In the case of building construction, this requires the adaptation of traditional construction cost databases, and hence it is necessary to clearly define exactly to what the LCC refers. Currently, the most prominent standards are the ISO 15686-5 standard [9] and the EN-15643 standard [10] (Figure 1). The most notable difference between the two is that for the former, the LCC concept only includes the costs related to buildings from their construction to the end of their life (blue box) and introduces another concept, whole life cycle cost (WLC) where pre-construction costs, revenues and externalities are added. This double definition can understandably lead to major confusion [11], and it is therefore always necessary to declare under which regulations the calculation of the indicator is to be carried out. In the European standard, as shown in Figure 1 on the right-hand side, the LCC concept already includes pre-construction costs and revenues.
Figure 1.
Categories of overall life cycle cost: on the left-hand side according to ISO 15686-5, and, on the right-hand side, EN-15643. In the blue box, the life cycle cost.
Research on LCC has received increased interest in recent decades, as shown by Goh et al. [11]. They reviewed 45 works related to the LCC calculation of conventional and green buildings. And Islam et al. [12] reviewed over 50 works which advance in simultaneously evaluating LCC and LCA in the construction of residential buildings. Among more recent proposals can be found a systematic classification through a work breakdown structure (WBS) that considers all the operating costs of a building throughout its life cycle, including its water and energy consumption, through a unified framework that allows the flow of design and construction information in the correct management of the building. For this, the Omniclass and Masterformat classifications are combined. This WBS-based framework aims to cover the entire life cycle of an asset to provide a unified classification system for asset inventory [13].
In the particular case of the study of building structure solutions, Abou et al. propose LCC assessment for design selection. They studied reinforced concrete, structural steel, and cold-formed steel frames and compared the results. The framework is developed in accordance with the relevant guidelines for LCA and sustainability and is intended to support decision-making at the design stage. They combine LCC and LCA simultaneously in the analysis of the structure’s life cycle [14]. In a more general way, LCC is employed in the creation of a selection tool with design variants in building construction [15]. They developed an LCC calculation tool in Excel.v2403 that includes individual variants of building designs with different input parameters. It analyses the components or equipment that have the greatest impact on total LCC. It also assesses the long-term economic efficiency of proposed residential buildings. The calculation of the costs of servicing, maintenance and renovation of the building elements is determined for each element. This is achieved with data on their service life, maintenance intensity, service intensity, and operating costs. Finally, the calculation of the costs consists of a percentage rate based on the acquisition costs.
But there are still limitations in the development and validation of LCC estimation. Barriers have been identified such as “varying definitions of LCC calculation methodologies; the availability and standards of data sources, in particular, the misalignment of coding systems for identification and classification of components at various levels of development, proprietary ownership of data, lack of knowledge and skills in team members to produce and/or utilize data sources, and limitations of software” [16].
In the particular case of Spain, The Directive 2014/24/EU has been consolidated into national legislation by means of the Law on Public Procurement [17]. Prior to the publication of this European directive, the legislation on the contracting of public works only contemplated the evaluation of the construction costs of new buildings. To this end, public administrations regularly publish their construction cost databases, which facilitates the preparation of budgets for new buildings. Costs are calculated per work unit, which is defined as “a construction element formed of basic or auxiliary elements which is carried out by a group of specialists” [18], as required by the public procurement legislation [17]. Defining a construction project’s scope and establishing its WBS are the first steps to estimating its costs. Their aims are to classify and code work, however, significant overlapping still takes place, as per surveys performed in the sector [19]. Construction costs and, to a lesser extent, end-of-life costs are usually the most commonly estimated, although, in general, information regarding the costs of the pre-construction use, maintenance, and end-of-life stages remains scarce and/or unreliable [20]. As a result, existing cost databases are insufficiently prepared to deal with the assessment of LCC.
This research addresses the creation of a Construction Information Classification System (CICS) for the calculation of building LCC in the early design stage that is adapted to international models of sustainability analysis in buildings. To this end, national and international systems are reviewed and compared. From their combination, the new classification organises the information and construction types. This enables the calculation of the LCC required by the legislation on contracts in the public sector [17].
2. State of the Art
2.1. Analysis of Existing CICS
Faced with the challenge of creating a new database of construction information adapted to the calculation of LCC, it is necessary to select the most suitable CICSs. These systems constitute fundamental tools for cost analysis which can be used in both the professional and scientific fields. The international standard ISO-12006-2 [21] organises and classifies the basic concepts. In addition to cost assessment, if the classification is associated with the standards for the calculation of environmental sustainability it would be possible to carry out economic and environmental calculations with the same system structure [3,22,23].
Afsari and Eastman [24] compared different CICSs according to their purposes and properties, frameworks, grouping principles, and organisation of classification models. Based on their criteria and adding new elements of evaluation such as scope of use, coding, life cycle, and scope boundaries, a comparison is carried out of the main international systems, focusing, in particular, on the Andalusia region (see Table 1). The criteria are defined below:
- (1)
- Scope of use: Sets the geographic scale of use for which the classification model is created.
- (2)
- Purpose of the classification model: Initial step in the classification of objects. Identifies the interest for which the classification model has been made [25].
- (3)
- Conceptual framework: The framework on which the classification model is built. Related to higher-level information classification models.
- (4)
- Grouping principle: This defines whether the grouping is single or multiple, related to the vision of grouping and classifying objects [24], by adding whether the classification model is itself a conceptual framework. ISO 12006-2 [21] classification is employed: resources, processes, results, and properties.
- (5)
- Organisation: This defines the item classification organisation in order to distinguish items within a collection [25]. Specifically, these are the information levels of development.
- (6)
- Coding: This establishes the coding type, numeric or alphanumeric, of the classification model.
- (7)
- Life cycle: This defines the temporal boundaries of the information incorporated into the classification model according to the stages of the building’s life cycle.
- (8)
- Scope boundaries: This establishes the physical boundaries of the information incorporated into the classification model. It determines whether the information is about the endogenous and/or exogenous costs of building elements. Endogenous costs refer to the costs related directly to the construction site, while exogenous costs are those necessary for the completion of the project but take place away from the construction site.
Table 1.
Comparison of Level 0 and Level 1 classification models. The columns stand for (1) scope of use, (2) purpose of the classification model, (3) conceptual framework, (4) grouping principle, (5) organisation, (6) coding, (7) life cycle, and (8) scope boundaries.
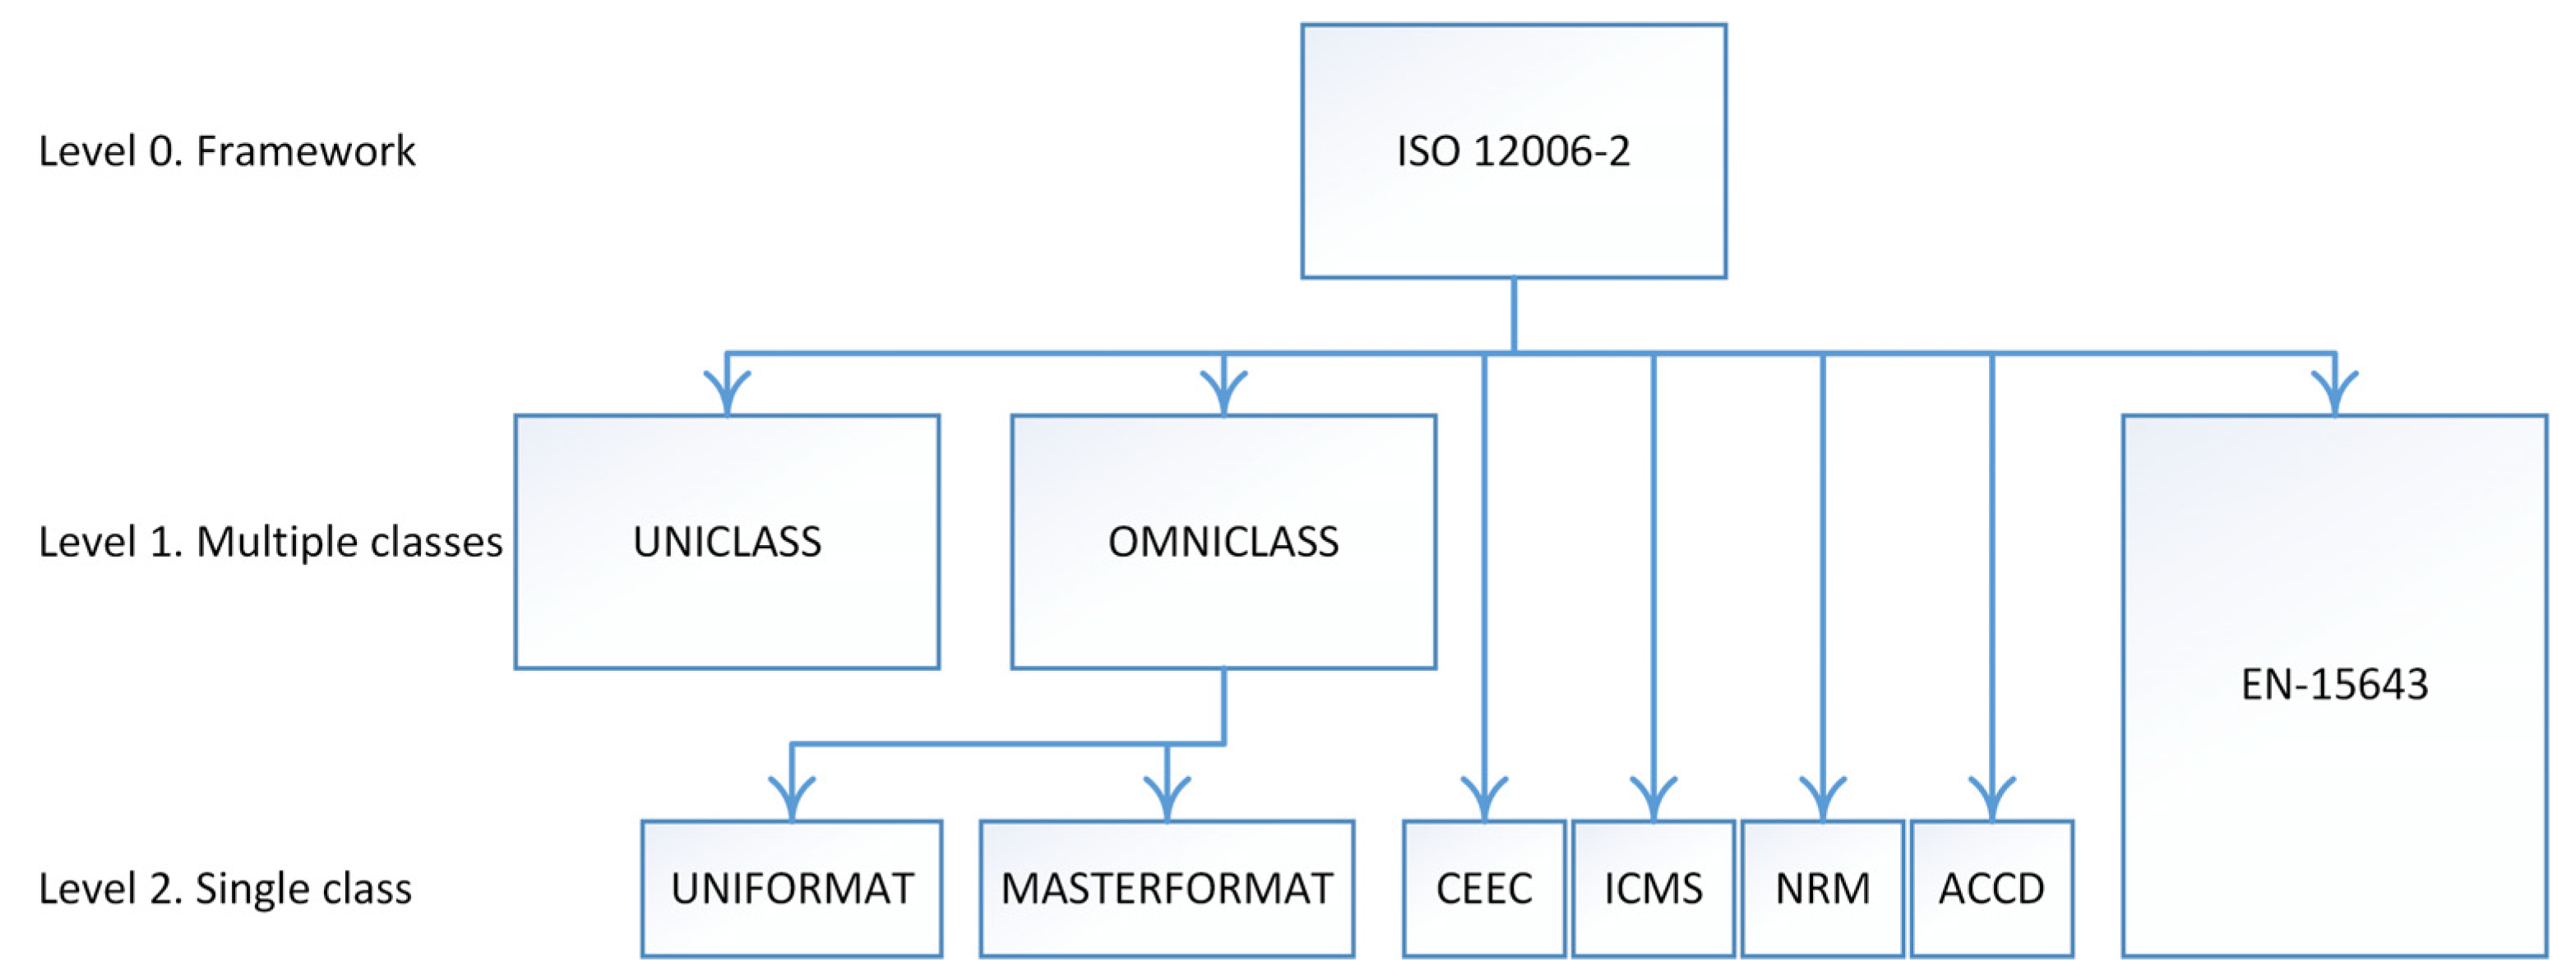
Table 1 analyses the most representative international and national CICSs and classifies them according to the levels indicated in the ISO 12006-2 standard, which aims to establish a framework for the classification of building information from the point of view of object-oriented programming. At Level 0, there are systems that contemplate a conceptual framework of classification. Level 1 includes those that contemplate multiple types of classifications, such as resources, processes, results, and properties. Lastly, Level 2 includes CICSs that have only one classification type (see Figure 2). A particular case is the EN-15643 standard, since it is a conceptual framework that contains the assessment of the environmental, social, and economic sustainability of construction with a single information structure throughout the life cycle. The standard development at the building level is currently pending [10].
Figure 2.
Hierarchical Structure of Classification Models. Abbreviations: Uniclass (UNC), Omniclass (OMC), Conseil Européen des Economistes de la Construction (CEEC), International Cost Management Standard (ICMS), New Rules of Measurement (NRM), and Andalusian Construction Cost Database (ACCD).
In North America, two main classifications have been developed, Masterformat and Uniformat. Both are conducted by the Construction Specifications Institute (CSI) and the Construction Specification Canada Institute [28]. Masterformat is the most widely used standard for construction information classification, mainly in the form of the product and technical information classification of building work units. Uniformat is largely used for the estimation of the functional element costs of buildings. In an attempt to unify concepts, CSI and CSC have supported, since 2006, the Omniclass classification, which structures information in a common format across several tables. Thus, the Uniformat and Masterformat classifications are represented by the Omniclass information in Tables 21 and 22, respectively. The Uniformat, Masterformat, and Omniclass classifications hold particular importance since they are supported by the BIM-IFC building models [29].
In Great Britain, the Committee of Construction Project Information (CPIc) created Uniclass in 1997, whose most recent version is from 2015, with the aim of creating a classification system for all aspects of design and the construction process by integrating the Construction Index/Samarbetskommitten for Byggnadsfragor tables (CI/SfB), the Common Arrangement of Work Sections for Buildings Works (CAWS), the Electronic Product Information Cooperation (EPIC), and the Civil Engineering Standard Method of Measurement (CESMM) [24]. Uniclass is currently updated by the Royal Institute of British Architects (RIBA) on the NBS professional platform [30].
At the European level, the Conseil Européen des Economistes de la Construction (CEEC) created the Code of Measurement for Cost Planning [31]. The council implements a classification of building costs that can be integrated with other national classifications and can be employed to make international cost comparisons at the management level [32]. This classification is used in European research projects, such as Life Cycle Costing and Cravezero [33].
Since 2017, the International Construction Measurement Standards Coalition (ICMSC) has published the International Construction Measurement Standard (ICMS). This standard is based on the New Rules of Measurement (NRM), developed by the Royal Institution of Chartered Surveyors (RICS), and aims to standardise the classification of construction costs at all levels from local to international in order to compare costs in a consistent and transparent way [34]. The standard supports life cycle cost from the 2019 release.
In Spain, there have been several CICSs developed over the last 40 years with a unifying exchange format called .bc3 [35]. This format is reviewed and updated periodically, and the Spanish software uses public and private tools for the creation of project budgets. These include ITEC in Catalonia, CYPE in Alicante, Construction Cost Database of the Community of Madrid, BDC-IVE in Valencia, BDEU in the Basque Country, PRECIOCENTRO in Guadalajara, and the Construction Cost Database of Andalusia [23].
In the particular case of this work, its geographical focus is Andalusia, Spain. The CICS of the Andalusian Construction Cost Database (ACCD) is used as a reference [36]. The database is employed for the cost estimation of architectural projects and it is based on the definition of work unit costs. Its hierarchical costs division is harmonised with the cost structure proposed by Spanish public procurement legislation. This meets the most commonly used decomposition criteria internationally, where the main divisions of WBS for building projects are elements, work sections, physical location, and auxiliary means of construction [37].
2.2. Coding of the CICSs
The coding of a cost database is a key issue in the identification and organisation of the information in an unambiguous way and brings simplicity to the information processing. The use of letters, digits, or combinations thereof has both advantages and disadvantages. Alphabetic characters enable the same number of sub-divisions as the number of letters in the alphabet of each language; for example, in Spanish it would admit 27 sub-divisions. On the other hand, numeric characters only support 10 sub-divisions at each level. Another advantage of letters with respect to digits is that they allow the first letter of each title to be associated with a certain concept but are only identifiable in the language of the titles, and therefore would not provide an intuitive universal coding system.
Table 2 summarises the coding employed by the CICSs reviewed: Uniclass [30], ACCD [36], CEEC [31], EN-15643 [10], and the ICMS [34]. All have alphanumeric classifications, except for the ICMS, which contains numeric characters exclusively.
Table 2.
Comparison of cost classifications.
3. Methodology
The main objective of this study is to create a CICS which organises costs throughout the life cycle of buildings, and a model to evaluate costs at a pre-design stage when design data are scarce and only approximate information is available on the needs of the building and its characteristics.
First, the new CICS should contain a classification of the stages or categories of the life cycle. To this end, it is proposed that the classification considers the ISO 12006-2 normative framework [21], the EN-15643 standard [10], since it is a life cycle structure, and the ISO classification [9]. The separation of LCC and CGCV concepts in the ISO standard is unnecessary, however, since pre-construction externalities, revenues, and costs can all be included as sub-categories within each stage of the life cycle.
Secondly, it is essential to establish a structured definition of a building divided into elements that can be quantified. The division element of buildings that is considered most appropriate for the pre-design phase is the functional unit cost, understood as the cost of the construction element which has a complete function within the project, which is formed by a set of basic, auxiliary, and unitary elements that constitute a construction whole [18]. Each functional element is the consequence of the characteristics, needs, and uses that the building is going to have. Therefore, the cost database will be composed of functional elements of the building, with their corresponding costs of construction, consumption, maintenance, repairs, replacements, and end of life.
Regarding the sources of information, it should be borne in mind that the cost information retains its reliability and quality because the costs of functional elements are an aggregation of the costs of basic elements, auxiliaries, and work units, all of which are sufficiently contrasted since they are already part of the existing construction cost databases in use in Spain. In this work, the costs of the basic elements, auxiliaries, and work units are those included in the ACCD, since the final objective is their application in Andalusia (Spain) [36]. Two types of functional elements are used: functional cells and functional areas. Functional cells are defined as a combination of constructive elements that give shape to a homogeneous functional space, defined by boundaries that guarantee that there are no gaps or overlaps, such as a teaching classroom. Functional areas are an aggregate of cells and are defined as the combination of constructive elements that give shape to a set of homogeneous functional spaces, defined by boundaries that guarantee that there are no gaps or overlaps, such as a classroom building [18].
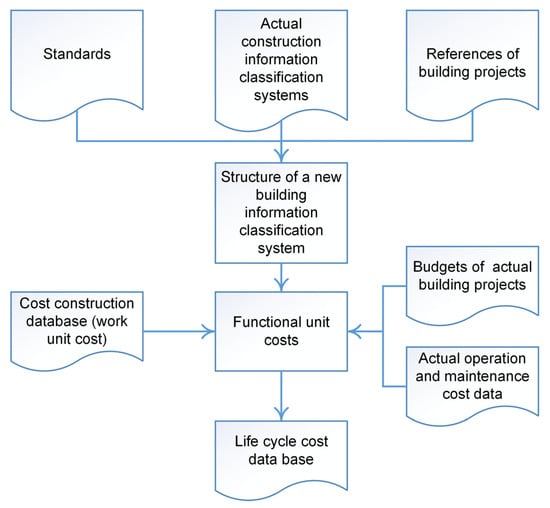
Thirdly, it is necessary for each functional element to be defined in the context of a building typology, since the technical characteristics can vary considerably. In this respect, the classification of building typologies proposed by the cadastral regulations of Spain has been selected as a reference [38]. Figure 3 provides an outline of the procedure for the creation of the cost database.
Figure 3.
Methodological schema for the creation of a CICS for public works projects in Spain.
For the creation of functional costs, the case study of a state secondary school building located in Andalusia has been chosen. Based on the tendered projects with this typology, the design regulations of these buildings, and on the actual costs of supplies, the functional costs that comprise the buildings are defined. The projects and design regulations in the region provide the ground floor area that is usually required in the design of these buildings, as well as the quantity surveying of similar previous projects. For data on supplies and other expenditures, information is provided by the regional government.
3.1. The Structure of the New Classification System
Firstly, the new structure takes into consideration the Uniclass classification, with levels and tables in accordance with ISO 12006-2 [21], which facilitates computer processing. Its list of entities contains buildings and civil infrastructures. It also contains a list of spaces and functional elements. Its main disadvantage is that the costs are organised into three different tables. Secondly, the levels established in the ICMS [34], which focus on the costs of the life cycle of any construction (building or infrastructure) are taken as a reference. It has a limitation in the division into categories of the life cycle however, which is not fully aligned with EN-15643 [10]. Finally, the ICMS classification is the closest to the objective proposed in this research. From the combination of the above, the levels are proposed in Table 3. The level dedicated to life cycle stages is aligned with EN-15643, another level is for the classification regarding building typologies as suggested by Uniclass [30] and the ICMS, and a functional group level enables cost elements to be organised, which is common to all reference classifications.
Table 3.
Comparative structure of the reference and current proposed CICS. Levels of decomposition.
Level N1 divides the classification into categories within the stages of the building’s life cycle. This level is divided into two sub-levels that are compatible with the levels represented in EN-15643 [10], which will also allow this classification to be used for environmental or social analysis. Level N2 enables the building to be divided into functional groups and sub-groups and relates them to each stage of the life cycle. Level 3, n3, comprises the building typologies, based on the classification of the Spanish Real Estate Cadastre [38]. Its sub-divisions of building typologies are hierarchical, from top to bottom, as follows: families, sub-families, and sections.
The coding of each element is formed by 10 digits (see Table 4). Numeric characters are used due to the universality of the code. The first two digits correspond to the life cycle categories. The next two digits are the functional groups. The third three-digit block identifies the construction type. And the last three digits establish the order of the functional elements belonging to the same level. Each primary or secondary level defined in the classification structure is assigned a numeric character (see Table 4).
Table 4.
Numeric coding of the model. N represents a numeric character.
3.1.1. Level 1—Life Cycle Categories
In Level 1, the CICS is structured according to the life cycle of the building, taking the EN-15643 standard as a reference. The first level, Categories, is made up of the following stages of the life cycle: pre-construction, construction, use, and end of life [10]. The following boundaries are established for each category:
- -
- Pre-construction: costs from the completion of the preliminary studies, the acquisition of the land, and its transformation, until the moment at which the construction of the building begins. If the cycle begins with the acquisition of an existing building, only the work prior to its rehabilitation or transformation is included.
- -
- Construction: all costs incurred from the beginning of the construction of the building until it is made available for use.
- -
- Use: all costs dedicated to the use and maintenance of the building until the construction reaches its end of life.
- -
- End of life: all costs necessary for the demolition or deconstruction of the building and the treatment of the waste generated.
The second sub-level is Sub-categories, which are those in the EN-15643 standard [10] with the addition of a further sub-category of fees and taxes, revenues, and other developer related overheads. These costs can be presented at any stage of the life cycle, as shown in Table 5. Another difference with respect to the standard is that the transport sub-categories (A2, C2) are not considered separately, but instead form part of each sub-category. This is due to the fact that, in Spanish traditional cost definitions, transport costs form part of each element of the building. The costs of basic elements always include their transport and unloading costs on site [35].
Table 5.
Level 1 categories and sub-categories. Life cycle. NN.NN. NNN. NNN, bolded the location of the code.
The boundaries of each sub-category of Level 1 are as follows:
- -
- 01. Preliminary actions: The costs related to the purchase of the land where a new building is to be constructed or where an existing building is located. These costs also include all the necessary actions, fees, and management expenses of the developer before the start of the construction work.
- -
- 09, 19, 29, and 39. Property developer’s income, taxation, professional fees, and other expenses: All professional fees, taxes, management expenses, and general expenses of the developer.
- -
- 11. Building and outdoor spaces: All expenses related to the construction of the building related to the developer–construction contract.
- -
- 21. Building use expenses: All contracted expenses and services not included in other sub-categories of building use (e.g., security, alarm, voice, and data installations).
- -
- 22. Maintenance: All expenses for inspection, preventive and scheduled maintenance of the building so that it retains its characteristics of use (e.g., cleaning and painting).
- -
- 23. Repair: Repair costs for unscheduled breakage or defects of building elements.
- -
- 24. Replacement: The costs arising from the replacement of building elements that end their useful life before the end of the useful life of the building.
- -
- 25. Refurbishment: Costs of major building modifications. These are only applicable in anticipation of legal or technological changes. In this research, transformations are not contemplated since they are considered to significantly alter the useful life of the building and to define a new life cycle of the building.
- -
- 26. Operational energy use: Costs due to the building’s energy consumption. Income from surplus energy production is considered in sub-category 29.
- -
- 27. Operational water use: Costs for water consumption.
- -
- 28. Occupant activities. Costs related to users or occupants of the building.
- -
- 31. Demolition–deconstruction: Incorporates the costs of demolishing the building.
- -
- 34. Waste management or landfill: Considers the costs of waste transport and management of any treatment, such as reuse, recycling, and landfill deposit. Income received from selling waste is considered a negative cost, as in ACCD [36].
3.1.2. Level 2—Functional Groups
At Level 2, the sub-division of the buildings’ functional groups is contemplated. A building can be defined as a “stable construction, made with resistant materials, to be inhabited or for other uses” [39], or by the following definitions provided by ASTM E631: “a shelter that comprises a partially or totally enclosed space, erected through a planned process of forming and combining materials” [40] and the ISO 6707-1:2020 definition of “a construction site whose main functions include housing its occupants or its contents; normally closed and designed to remain permanently fixed in place” [41]. Interpreting the above definitions and in order to establish the functions that the building must fulfil, it is understood that the building remains fixed in place and provides closed or partially closed spaces that enable them to be occupied.
Following the previous concepts, the organisation of functional groups is proposed in Table 6. For the configuration and use of this sub-level, the ICMS classification has been used as a reference. Specifically, it is proposed that the same classification of functional sub-group levels is repeated within each sub-category: construction, use, and end of life. Only the sub-categories referring to external costs of the building, such as land, and income, fees and taxes, professional fees and other expenses of the developer, will have a different structure. A sub-group is also included within each group that organises the functional areas.
Table 6.
Building functional groups and sub-groups belonging to the life cycle sub-categories, 11, 21, 22, 23, 24, 26, 27, 28, 31, and 34. NN.NN. NNN.NNN, bolded the location of the code.
The inclusion of the groups that contain functional sub-groups related to waste management, quality control, and health and safety are of particular note. In addition to the costs directly associated with the buildings, it is necessary to consider the following other, indirectly related, costs in the sub-categories: preliminary actions, income, taxation, professional fees, and other expenses of the developer.
Table 7 shows the functional groups and sub-groups that form part of sub-category 01 of the life cycle, the preliminary work. These include the acquisition of land or existing buildings and related actions, such as the transformations carried out on the land before it became urban in relation exclusively to servicing the new building. In the case of an urban development that serves more than one building, it must be studied as an independent project by means of typology 9: Urbanisation (see Appendix A).
Table 7.
Classification of functional elements of sub-category 01 of the life cycle: Preliminary actions of existing land or buildings (01.NN. NNN.NNN.), bolded the location of the code.
Table 8 describes the classification of sub-categories 09, 19, 29, and 39 for income, professional fees, and other expenses of the developer, including all expenses and income generated by the development activity, except costs due to land and building work and taxes. Income is generated by the use of the site or building, usually in the form of rent or assignments. Studies, projects, and construction management are the expenses for external professional services provided to the developer. Other expenses of the developer include those that can be imputed to the building and do not fit in other categories.
Table 8.
Classification of functional elements for life cycle sub-categories 09, 19, 29, and 39 for revenue, taxation, professional fees, and other developer expenses. NN.NN. NNN. NNN, bolded the location of the code.
3.1.3. Level 3—Building Typologies
The third and final level refers to the definition of the building typologies classification based on the Spanish Real Estate Cadastre [38]. Each element of the typology classification is defined in Appendix A. The classification of construction typologies is organised in three levels. First, the general building uses are grouped into the following nine main categories: 1. Commercial, 2. Sport, 3. Hospitality, 4. Warehouses, 5. Leisure, 6. Teaching, 7. Residential, 8. Healthcare, and 9. Urbanisation. The last category, although it is not directly related to buildings, is included as an exception since it is considered necessary when the development costs are not due to a single building. In sub-levels, the typologies are grouped according to the building’s specific uses. For example, within the hospitality classification, there are the sub-families of lodging and catering. In its sub-level 3.2, within the catering sub-family, would be the bar, cafe, and restaurant sections.
3.2. Costs of Functional Spaces
In Appendix A, Appendix B, Appendix C, Appendix D and Appendix E, examples are given of the methodology applied to the creation of functional costs of construction, maintenance, repair, and replacement. The functional cell space corresponds to the corridor of a secondary school building in Andalusia. The corridor’s functional cell cost, which is measured per usable area, is described in Appendix B. This consists of the ceiling, floor, lighting, electrical installation, fire protection system, and speakers. The walls of the corridor are included in other cells, such as interior partitions and façades. The cost calculation is performed by aggregating the work unit costs that are presented in the functional cell. The quantities of each unit cost depend on the proportion that corresponds to that area.
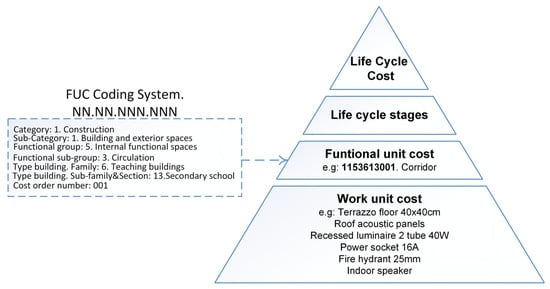
The corridor’s functional cell has the coding 1153613001, which corresponds to category 1 construction, sub-category 1: building and exterior spaces, 5 for indoor functional spaces, 3 for circulations, 6 for teaching building, 13 for secondary school, and 001 is the cost order number. The unitary costs that form the functional cell are obtained from the regional construction cost database ACCD. In order to establish the quantities of each unitary cost, such as the corridor surface, in the project this is 263.89 m2 and has three loudspeakers. The quantity to be considered in the cell is six units/263.89 m2 = 0.02272 u/m2. The functional cell is formed by unit costs at the base of the cost pyramid, Figure 4.
Figure 4.
Cost structure, the work unit cost is obtained from the ACCD which is part of the functional cost.
The maintenance costs of the functional cell refer to the preventative tasks that must be carried out in order to maintain it in good condition (see Appendix C). The cost of repairs is an annual proportion of each element and is calculated as a percentage of each construction cost that makes up the functional cell (see Appendix D). The percentages are based on “The Whitestone Installation Maintenance and Repair Cost Reference” [42] or on the EN-15459-1 standard [43].
Replacement costs correspond to the substitution of elements that form part of the functional cell, since their useful life ends before that of the building. They include the costs of the small demolitions required to carry out the replacement. An example is given in Appendix E.
The costs of functional cells are combined into a functional area. In Appendix F, there is an example of the area “circulation zone in a secondary school”. The functional area is the result of adding functional cells and their corresponding quantities.
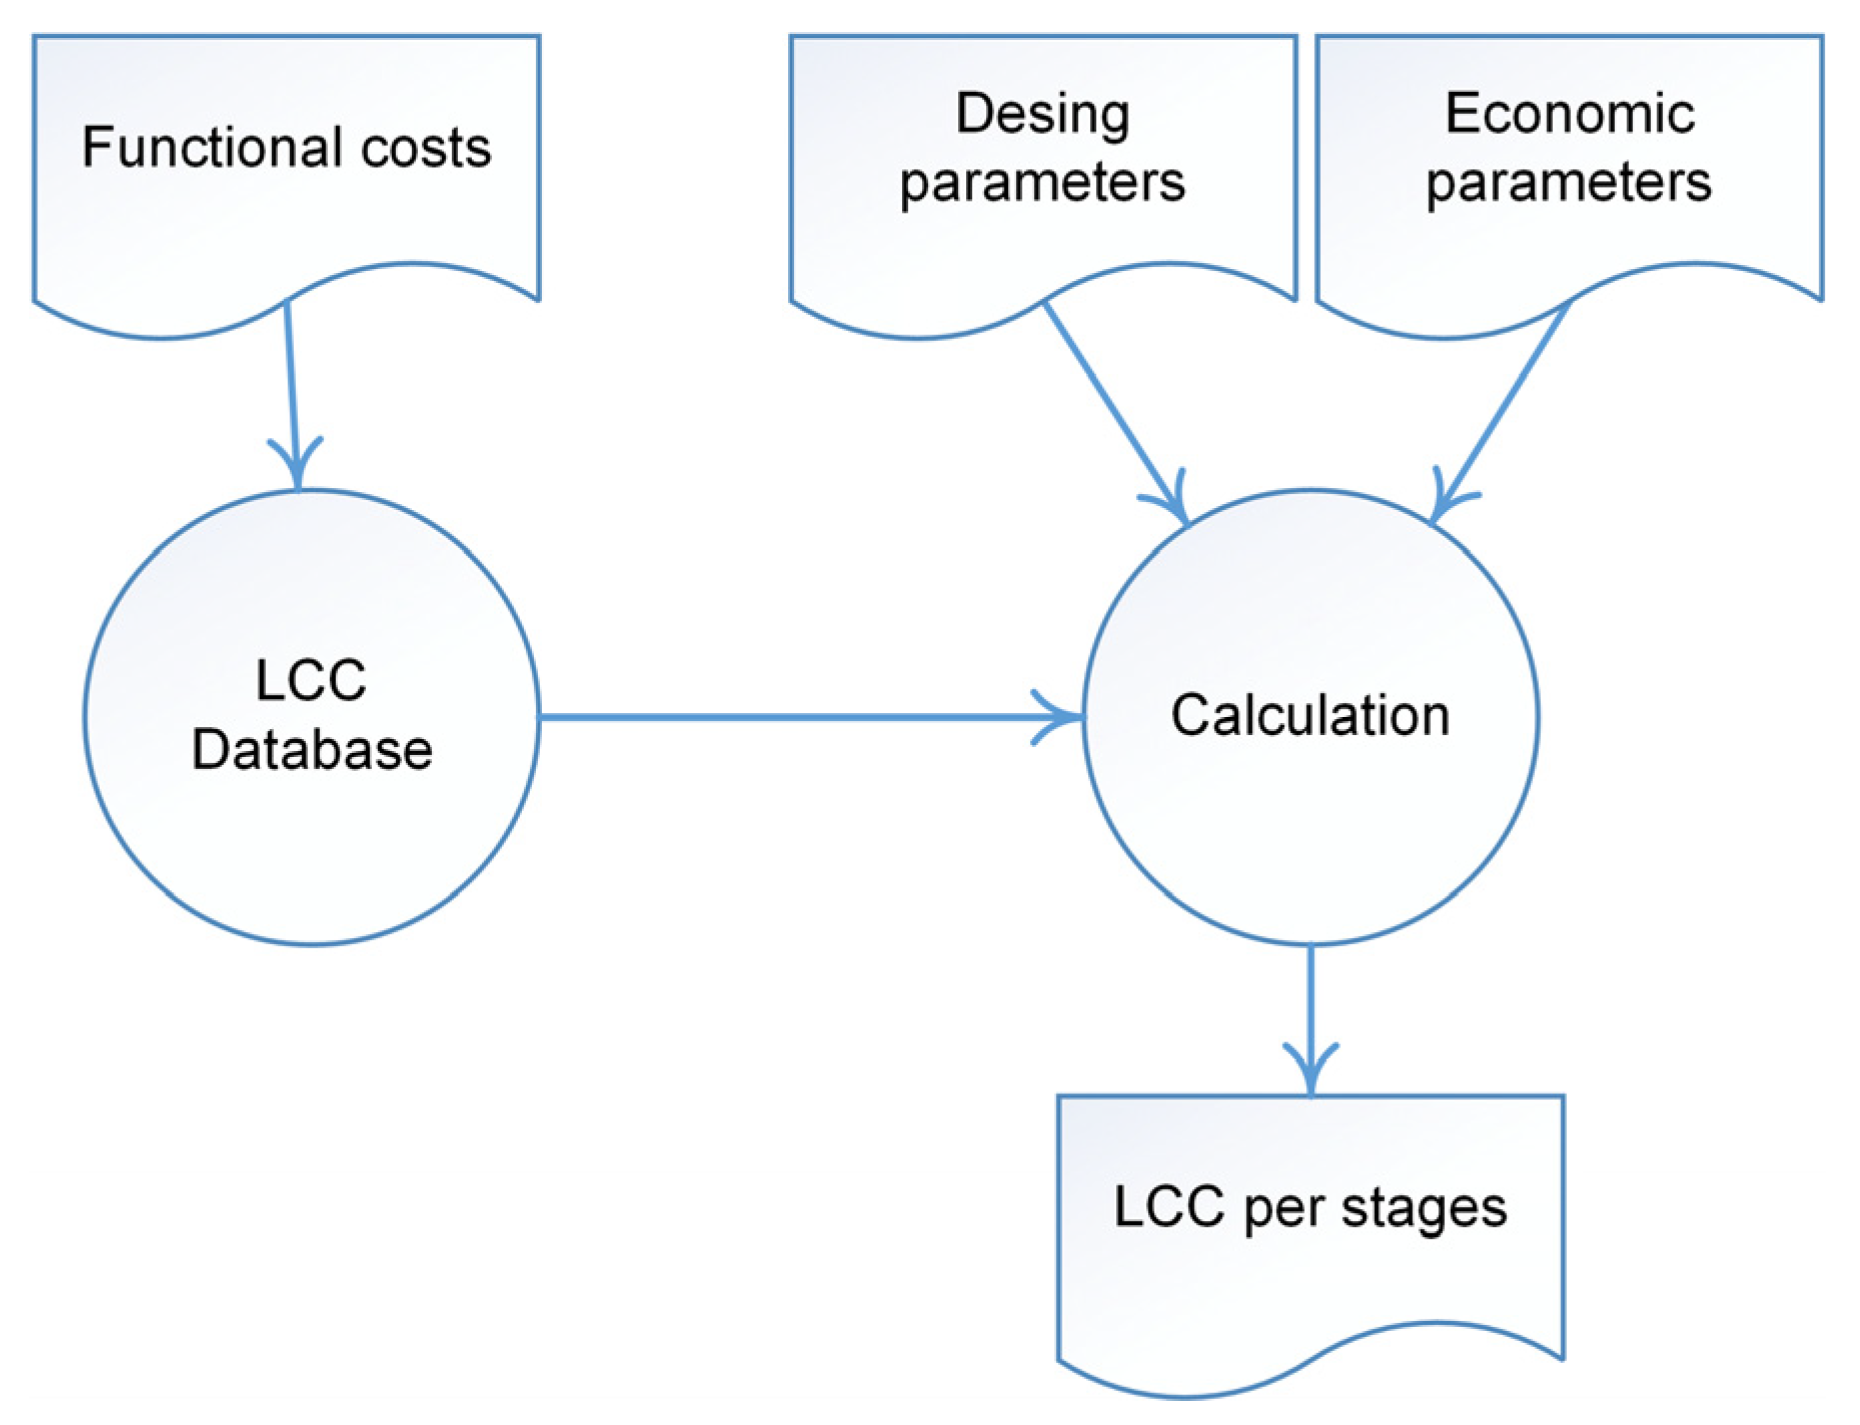
Finally, the functional costs form an LCC database of construction maintenance, repair, and replacement costs. For the calculation of the LCC it is necessary to define the building’s general characteristics or design parameters that describe the geometrical aspects of the functional spaces. Other aspects needed are the economic parameters; in this case, the discount rate to be applied to the cost estimation. This calculation is performed per stage of the life cycle (see Figure 5).
Figure 5.
Steps for the calculation of the life cycle cost (LCC) of the project per stage.
3.3. Case Study
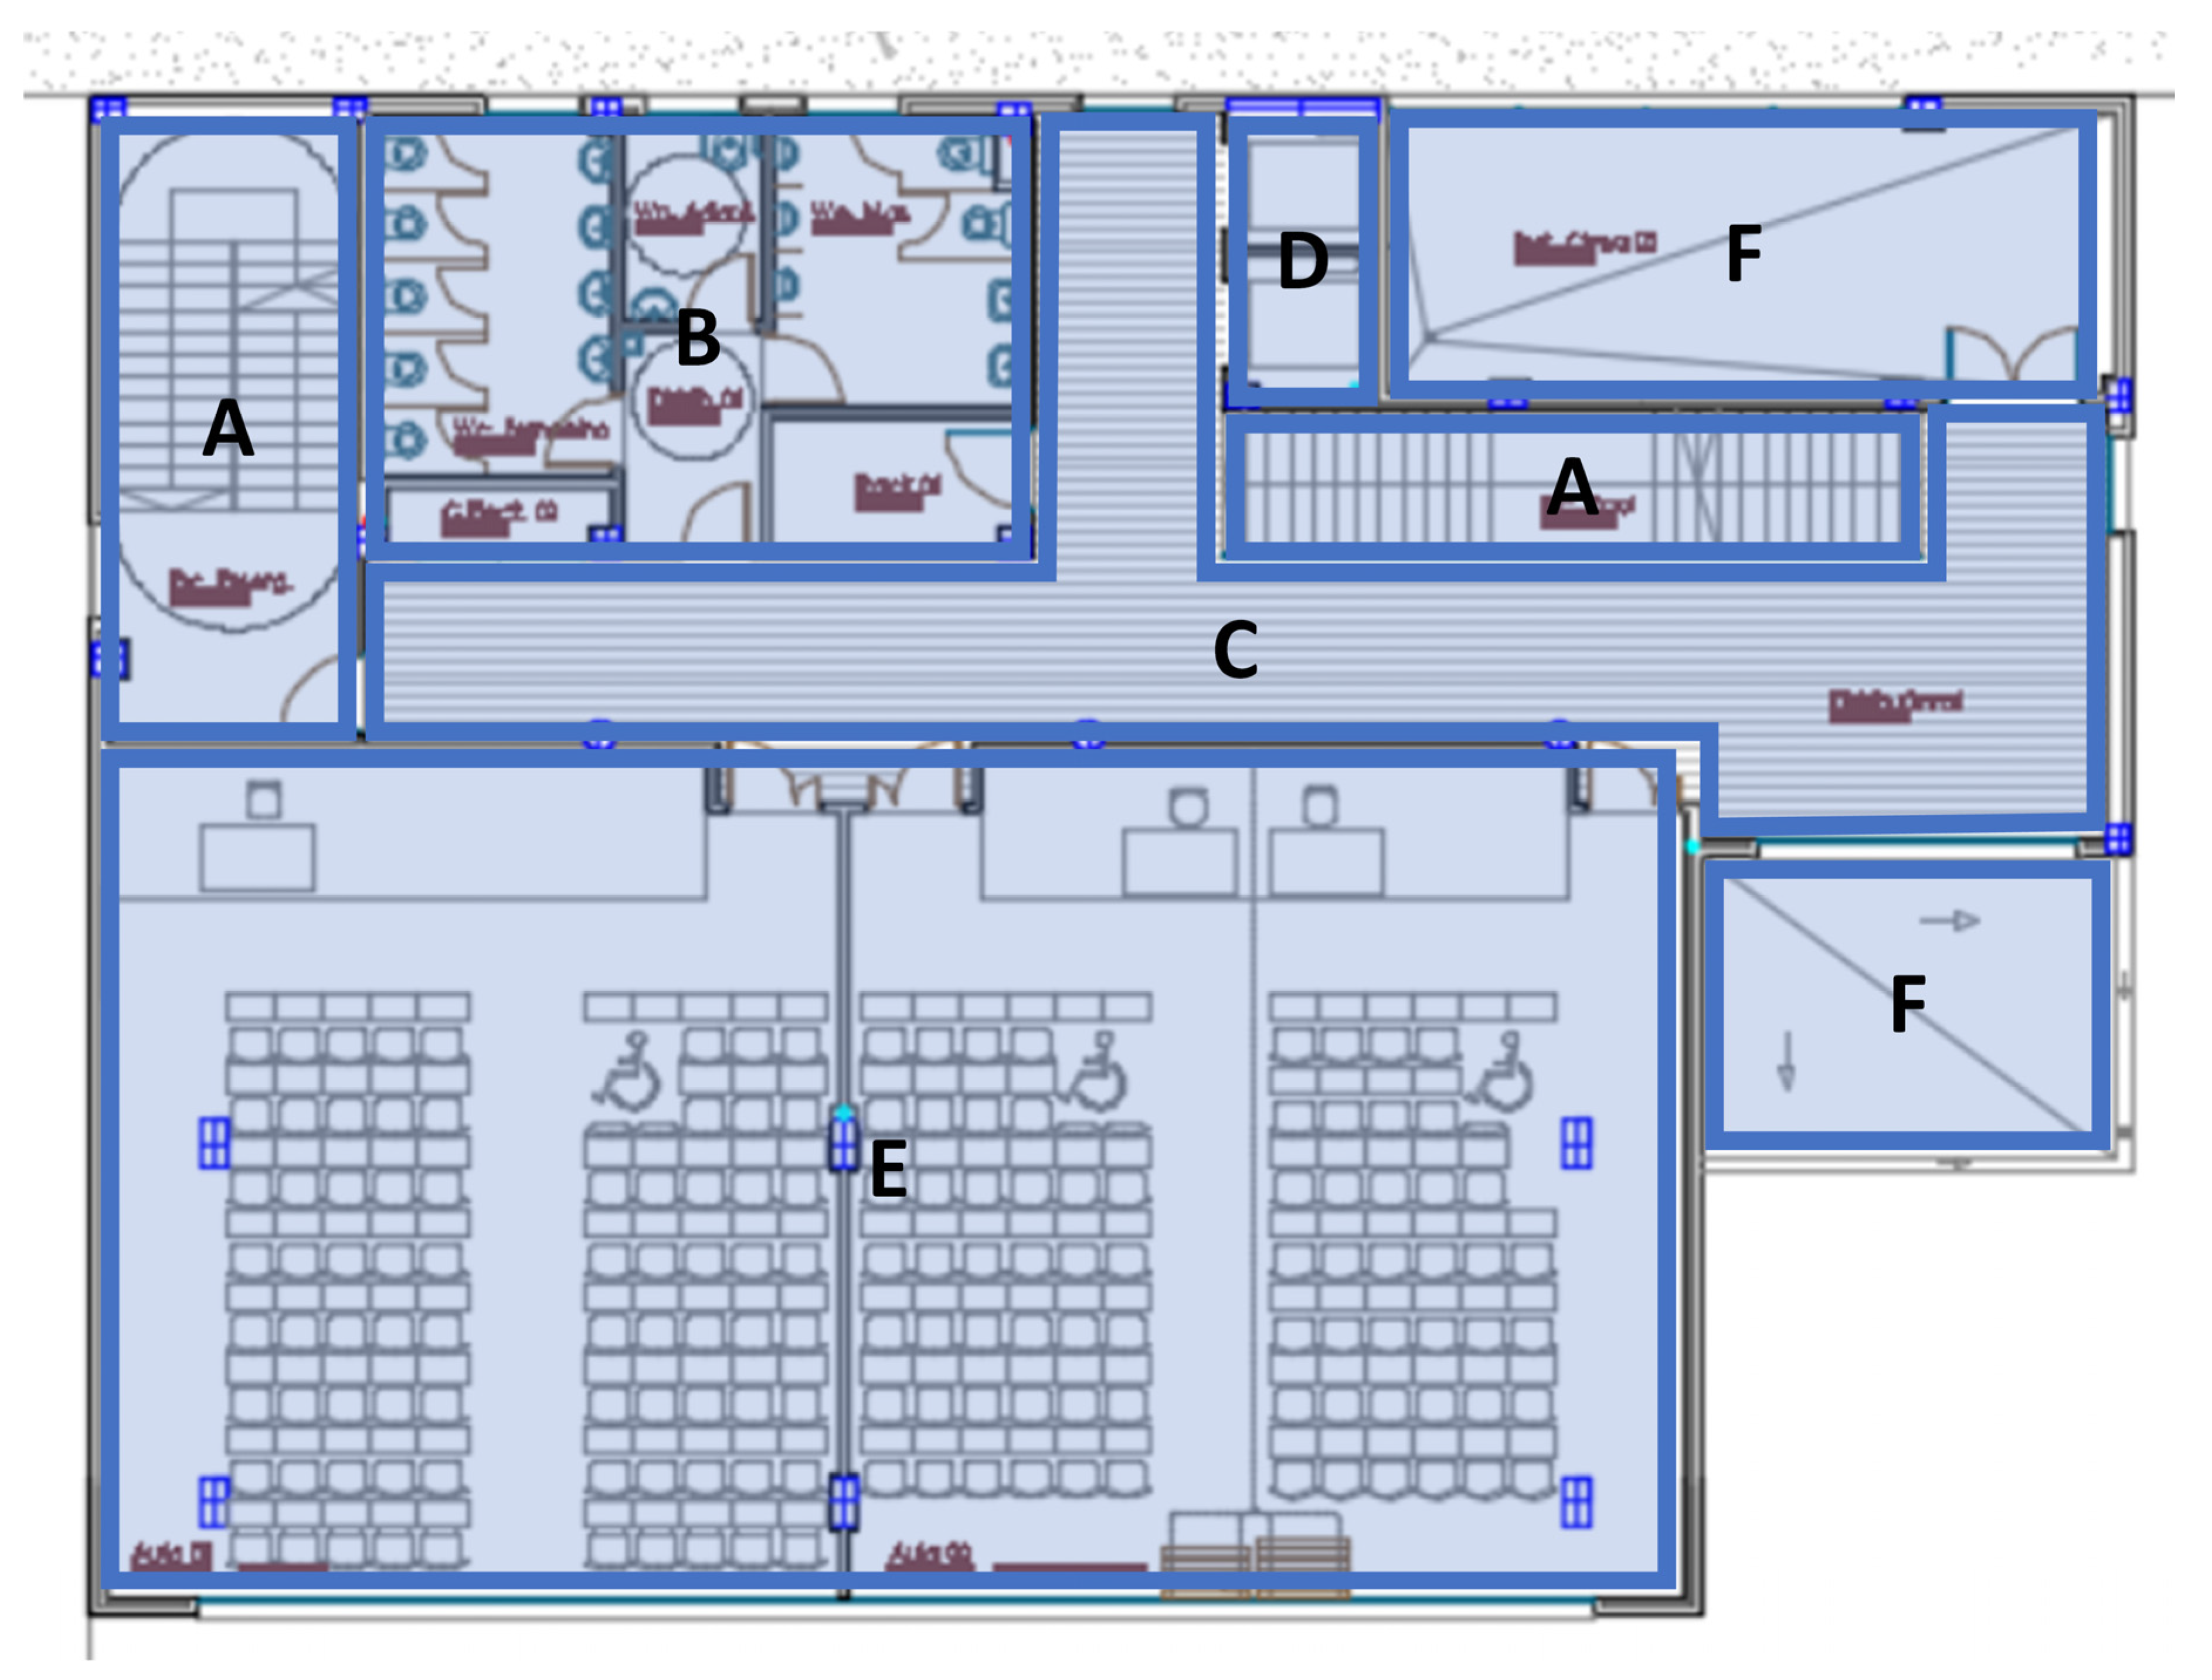
A public school building built by the regional government is studied, whose standardization and representativeness of secondary schools in Andalusia, Spain allows the application and validation of the model. The D3 typology of the regional government has been chosen [44]. It is a fourth-year teaching building, divided in three classrooms per year, with a capacity of 30 students each. Three projects studied are built in the municipalities of Palomares, Almensilla, and Marbella. From those, a generic secondary school is defined. In Figure 6, a representative floor is shown, and in Table 9, the space distribution per square metre.
Figure 6.
Example functional spaces ((A). Staircase, (B). Lavatory, (C). Corridor, (D). Lift, (E). Classroom, (F). Terrace).
Table 9.
Description of the project floor area.
The duration of the pre-construction, construction, and end-of-life stages is 1 year each. The use stage lasts 100 years in order to meet Spanish requirements for concrete structures [45]. Maintenance tasks take place annually except for painting which occurs every five years. Repairs are annual and the following substitutions are at 20 years: HVAC, electronics, bathrooms and kitchens; the following at 40 years: HVAC, electronics, other installations, bathrooms and kitchens, elevators, envelope repair, ceilings; and the following at 70 years: the same activities as at 40 years but, additionally, the floor is replaced.
The following four hundred and sixty functional costs were defined: five for the pre-construction stage, 108 for the construction, 338 for the use stage and nine for the end-of-life stage. The utilities consumption was obtained from the public school system’s actual data. The water consumption is 640 m3/year, the power consumption is 40,000 kWh/year, gas consumption is 20,000 kWh/year, and data and telephonic communications are EUR 790/year. The cost of urban land in the province of Seville was obtained from official statistics (EUR 154.20/m2) [46]. The taxes were taken from local (Seville), regional (Andalusia), and national (Spain) regulations [47].
4. Results
The results are obtained by stages of the life cycle, analogous to environmental product declarations, and by functional spaces, allowing for the identification of the most expensive elements. Finally, future investment costs in the life of the building can be determined from the early design stages. The results have been obtained for a discount rate of 0% and 3%, in the calculation of the 100-year LCC (Figure 7).
Figure 7.
Comparison of LCC category percentages with different discount rates of 0% (A) and 3% (B).
The most expensive stage is B. Use, followed by A. Construction. The effect of the discount rate in the calculations appreciates, since it clearly reduces the influence of the use stage when the 3% discount is applied. The A0. Pre-construction costs are also significant, but not included in other studies [23].
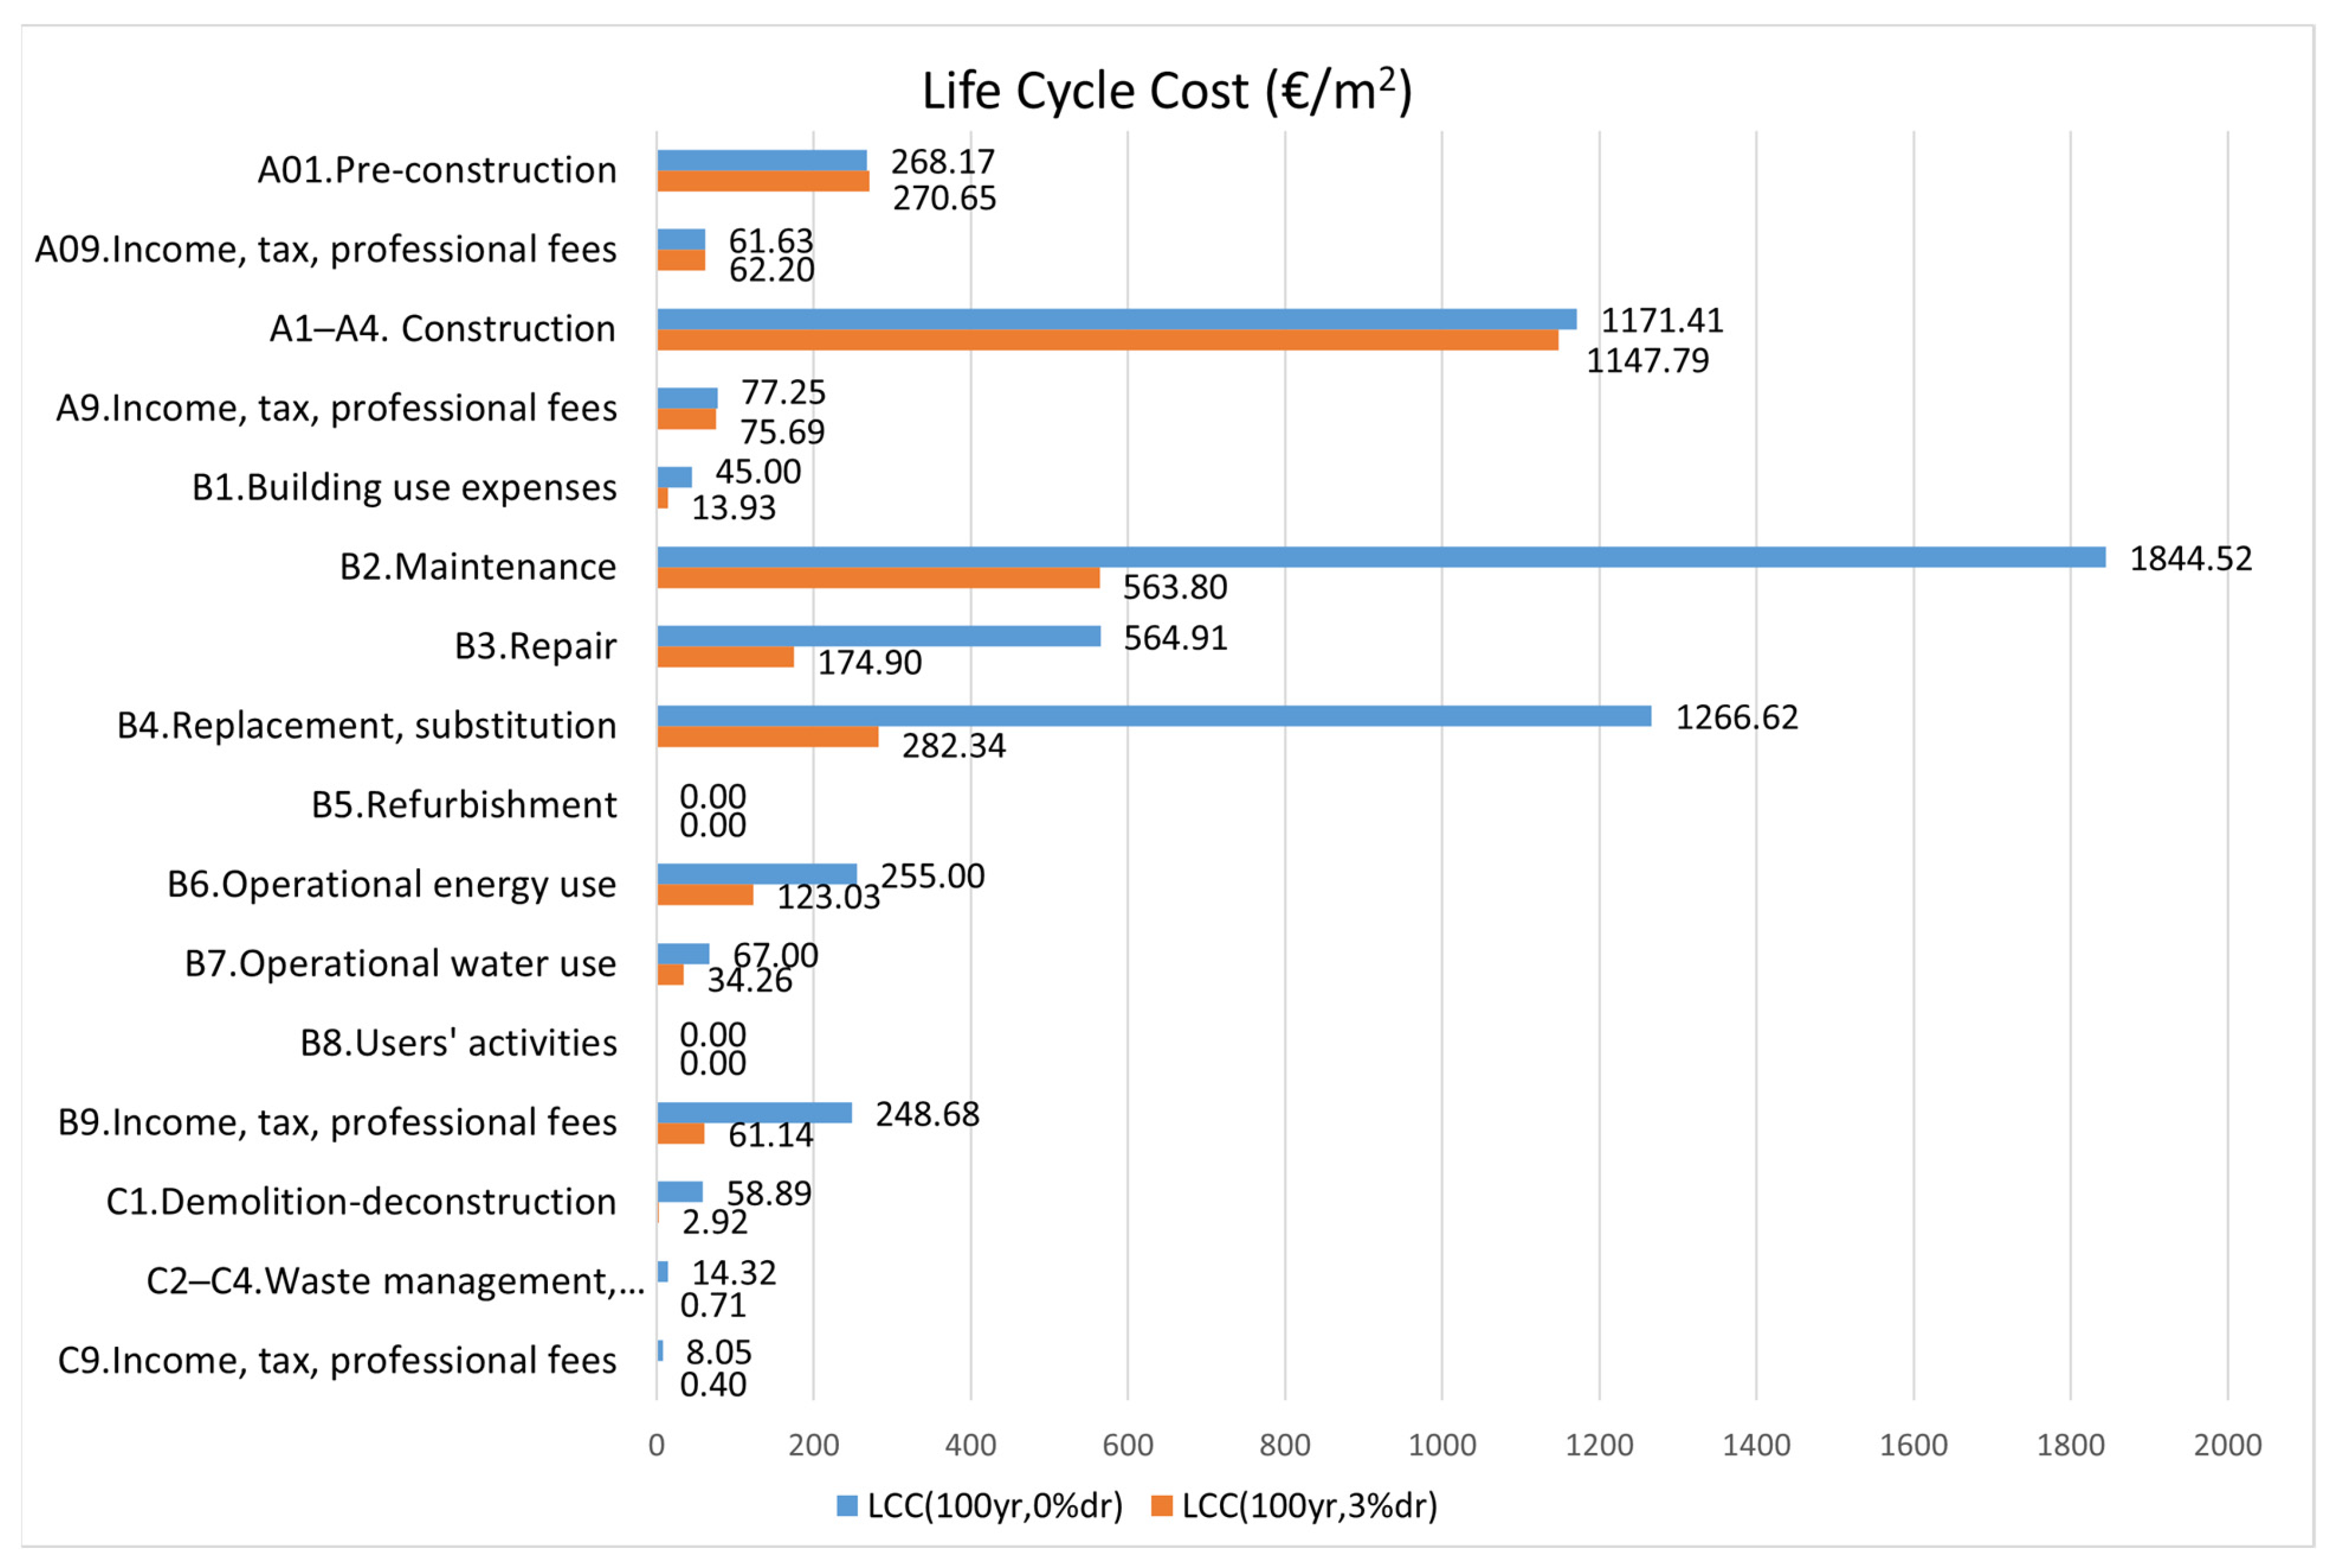
Analysing the decomposition of data from the different stages, see Figure 8, the most impacting stage of the building life cycle is B2. Maintenance, followed by B4. Substitutions, both with economic impact higher than stages A1–A4 Construction. B3. Repairments is the fourth must impacting stage. The utilities consumption rates are not very significant and are similar to those of developer expenses and taxation. It can be seen that the discount rate reduces the importance of subcategories B2 and B4 in the 3% discount rate.
Figure 8.
The costs per life cycle subcategories with 0% (blue) and 3% (orange) discount rates.
The results can be compared to C. Rivero-Camacho et al. [3]. They studied social housing in the same region and employed the ACCD for the unit cost data. Their discount rate was 0%. In Table 10 their results are compared to the present work. Although the buildings have different purposes, residential vs. secondary school, the results are similar in terms of percentage. It should only be noted that the B stage or use in the school building is more influential than in the case of the residential building. Even though Rivero-Camacho et al. employed the actual project data and in the present work a simplification functional costs were applied (those being feed by unit costs of the same data base). The results show that the functional costs can be a good approximation to the project’s LCC.
Table 10.
Comparative results between the secondary school and a social housing project. The percentage of each stage and in parenthesis the cost per square metre.
5. Discussion
The new classification considers the ISO 12006-2 normative framework [21], the EN-15643 standard [10], since it is a life-cycle structure, and the ISO classification [9]. But the separation of the LCC and CGCV concepts in the ISO standard is shown to be unnecessary because pre-construction externalities, revenues, and costs can all be included as sub-categories within each stage of the life cycle. ISO 12006-2’s main disadvantage is that the costs are organised into three different tables. For this, ICMS is taken as a reference because it is the closest to the objective proposed in the present research, which focuses on the costs of the life cycle, even though it is not fully aligned with EN-15643.
The sub-categories proposed are those in the EN-15643 standard [10], with the addition of a further sub-category of fees and taxes, revenues, and other developer related overheads. These costs can be presented at any stage of the life cycle. Another difference with respect to the standard is that the transport sub-categories (A2, C2) are not considered separately, but instead form part of each sub-category. This is due to the fact that in traditional Spanish cost definitions the costs of basic elements always include their transport and unloading costs on site [35].
From the combination of the above, the levels are (1) life cycle categories, (2) functional groups and (3) building typologies. The level dedicated to life cycle stages is aligned with EN-15643 [10], another level is for the classification regarding building typologies as suggested by Uniclass [30] and the ICMS [34], and a functional group level enables cost elements to be organised; this is common to all reference classifications.
The results show that this new CICS allows the generation of a robust structure that first contains the different stages of the life cycle of the functional element under analysis. Second, it analyses the functional element and establishes clear boundaries, and, lastly, it specifies this element in the building typology, which in this case is a teaching centre. The aggregation of the costs of elements and functional areas generates the structure of the estimate that in turn leads to the determination of the LCC of the building to be analysed. All this suggests that the definition of the functional costs needs to be performed by experts with knowledge of construction and previous experience of the building typology.
In summary, in a novel way, the proposed systematic classification covers the entire life cycle, being aligned with the standards for environmental sustainability assessment EN-15643 [10]. It enables early estimates of life cycle cost, using functional costs in a novel way to estimate construction and maintenance costs. The classification also clearly includes taxes, fees, and financial expenses at different stages of the life cycle. It is the first Spanish work breakdown system that includes all these aspects.
6. Conclusions
In order to understand how a CICS is developed, the main international and regional CICSs have been analysed. Their comparison has been carried out using eight criteria: purpose and properties, framework, the principles of grouping, the organisation of the classification models, scope of use, coding, life cycle, and scope boundaries. The comparison reveals a fairly complete picture of the organisation and classification.
A new classification is proposed with the following three levels: life cycle categories, functional groups, and building types. The level dedicated to life cycle stages is aligned with EN-15643. The functional group level enables cost elements to be organised, and the third level is for the classification of building typologies as suggested by Uniclass and the ICMS.
A cost structure has been possible that defines and meets the objectives for environmental sustainability assessment. The new classification employs the stages of the life cycle of the EN-15643, A0-pre-construction, A-construction, B-Use and C-end-of-life in a way equivalent to that which appears in the environmental product declarations, but at the building level. New sub-categories are included, such as income, professional fees, other expenses of the property developer, and tax costs. This makes it possible to attribute them individually to each stage of the building’s life and to study them in detail.
For the evaluation of costs during the early stages of the design, these are defined as functional costs. For their definition, it is necessary to gather information from similar previously tendered projects, from the design regulations, and from the actual costs of supplies from construction cost databases.
The case study of a secondary school project in Andalusia shows that the use stage is important as compared to other costs. This makes crucial the correct definition of all future repair work and maintenance tasks, as well as the utility consumption of the building. The new CICS can be aligned with the sustainability assessment stages.
In future work, the methodology will be applied to entire building projects, and will define their cells and functional spaces in order to carry out the complete life cycle cost assessment procedure. This can be performed for a variety of building typologies, such as residential buildings, offices, and educational centres, in order to determine whether this classification effectively covers the LCC in the early stages of design. Furthermore, the influences of inflation, discount rates, and life cycle duration could also be taken into consideration.
The integration of this classification system into the determination of the LCC indicator is also proposed in evaluation tools such as Level(s) and BREEAM, as is its integration into BIM environments regarding the functional costs created. Likewise, future research is proposed regarding the in-depth determination of LCC in terms of the new CICS.
Author Contributions
Conceptualization, E.V.-L.; methodology, J.S.-G.; validation, J.S.-G.; formal analysis, M.M. and E.V.-L.; investigation, E.V.-L.; writing—original draft preparation, E.V.-L. and M.M.; writing—review and editing, M.M. and J.S.-G.; funding acquisition, M.M. All authors have read and agreed to the published version of the manuscript.
Funding
Ayudas a la Internacionalización de la Investigación IUACC 2023 del VII Plan Propio de Investigación y Transferencia de la Universidad de Sevilla.
Data Availability Statement
The original contributions presented in the study are included in the article, further inquiries can be directed to the corresponding authors.
Acknowledgments
The authors would like to thank the I.E.S Palomares staff for their help in data collection and A. Ramírez de Arellano for his support and advice.
Conflicts of Interest
The authors declare no conflicts of interest.
Appendix A
Table A1.
Sections of the division of building typologies (NN.NN.NNN. NNN), bolded the location of the code.
Appendix B
Table A2.
Example of construction cost of functional cell.
Appendix C
Table A3.
Example of the cost of maintaining functional space.
Appendix D
Table A4.
Example costs of functional space repairs.
Appendix E
Table A5.
Example of costs of replacements in functional space.
Appendix F
Table A6.
Example of costs of construction in functional area space.
References
- Oxford Economics. Future of Construction—A Global Forecast for Construction to 2030; Oxford Economics: London, UK, 2021. [Google Scholar]
- Eurostats Construction Sector. Available online: https://ec.europa.eu/eurostat/cache/digpub/housing/bloc-3a.html?lang=en (accessed on 29 October 2023).
- Rivero-Camacho, C.; Martín-del-Río, J.J.; Marrero-Meléndez, M. Evolution of the Life Cycle of Residential Buildings in Andalusia: Economic and Environmental Evaluation of Their Direct and Indirect Impacts. Sustain. Cities Soc. 2023, 93, 104507. [Google Scholar] [CrossRef] [Scilit]
- MITMA. Licitación Oficial En Construcción. Año 2021; MITMA: Madrid, Spain, 2021. [Google Scholar]
- European parlament Directive 2014/24/EU of The European Parliament and of the Council of 26 February 2014 on Public Procurement and Repealing Directive 2004/18/EC (Text with EEA Relevance). Off. J. Eur. Union 2014, 94, 65–242.
- Dodd, N.; Donatello, S.; Cordella, M. Level(s)-A Common EU Framework of Core Sustainability Indicators for Office and Residential Buildings User Manual 1: Introduction to the Level(s) Common Framework (Publication Version 1.1); European Commission: Brussels, Belgium, 2021. [Google Scholar]
- BREEAM-SE. BREEAM-SE New Construction v6.0 Technical Manual 1.1; Sweden Green Building Council: Stockholm, Sweden, 2023. [Google Scholar]
- Sherif, Y.S.; Kolarik, W.J. Life Cycle Costing: Concept and Practice. Omega 1981, 9, 287–296. [Google Scholar] [CrossRef] [Scilit]
- ISO-15686-5; ISO Buildings and Constructed Assets—Service Life Planning—Part 5: Life-Cycle Costing. ISO: Geneva, Switzerland, 2017; p. 52.
- EN 15643:2021; Sustainability of Construction Works—Framework for Assessment of Buildings and Civil Engineering Works. CEN: Brussels, Belgium, 2021; p. 48.
- Goh, B.H.; Sun, Y. The Development of Life-Cycle Costing for Buildings. Build. Res. Inf. 2016, 44, 319–333. [Google Scholar] [CrossRef] [Scilit]
- Islam, H.; Jollands, M.; Setunge, S. Life Cycle Assessment and Life Cycle Cost Implication of Residential Buildings—A Review. Renew. Sustain. Energy Rev. 2015, 42, 129–140. [Google Scholar] [CrossRef] [Scilit]
- Al-Kasasbeh, M.; Abudayyeh, O.; Liu, H. A Unified Work Breakdown Structure-Based Framework for Building Asset Management. J. Facil. Manag. 2020, 18, 437–450. [Google Scholar] [CrossRef] [Scilit]
- AbouHamad, M.; Abu-Hamd, M. Framework for Construction System Selection Based on Life Cycle Cost and Sustainability Assessment. J. Clean. Prod. 2019, 241, 118397. [Google Scholar] [CrossRef] [Scilit]
- Hromada, E.; Vitasek, S.; Holcman, J.; Heralova, R.S.; Krulicky, T. Residential Construction with a Focus on Evaluation of the Life Cycle of Buildings. Buildings 2021, 11, 524. [Google Scholar] [CrossRef] [Scilit]
- Zanni, M.; Sharpe, T.; Lammers, P.; Arnold, L.; Pickard, J. Developing a Methodology for Integration of Whole Life Costs into BIM Processes to Assist Design Decision Making. Buildings 2019, 9, 114. [Google Scholar] [CrossRef] [Scilit]
- Gobierno de España. Ley 9/2017, de 8 de Noviembre, de Contratos Del Sector Público; Gobierno de España: Madrid, Spain, 2017; Volume 2014, pp. 1–233. [Google Scholar]
- Ramírez de Arellano Agudo, A. Presupuestación de Obras; Universidad de Sevilla, Secretariado de Publicaciones: Sevilla, Spain, 2014; ISBN 9788447212057. [Google Scholar]
- Cerezo-Narváez, A.; Pastor-Fernández, A.; Otero-Mateo, M.; Ballesteros-Pérez, P. Integration of Cost and Work Breakdown Structures in the Management of Construction Projects. Appl. Sci. 2020, 10, 1386. [Google Scholar] [CrossRef] [Scilit]
- Vázquez-López, E.; Garzia, F.; Pernetti, R.; Solís-Guzmán, J.; Marrero, M. Assessment Model of End-of-Life Costs and Waste Quantification in Selective Demolitions: Case Studies of Nearly Zero-Energy Buildings. Sustainability 2020, 12, 6255. [Google Scholar] [CrossRef] [Scilit]
- ISO 12006-2; Building Construction—Organization of Information about Construction Works. ISO: Geneva, Switzerland, 2015.
- Soust-Verdaguer, B.; Bernardino Galeana, I.; Llatas, C.; Montes, M.V.; Hoxha, E.; Passer, A. How to Conduct Consistent Environmental, Economic, and Social Assessment during the Building Design Process. A BIM-Based Life Cycle Sustainability Assessment Method. J. Build. Eng. 2022, 45, 103516. [Google Scholar] [CrossRef] [Scilit]
- Marrero, M.; Rivero-Camacho, C.; Alba-Rodríguez, M.D. What Are We Discarding during the Life Cycle of a Building? Case Studies of Social Housing in Andalusia, Spain. Waste Manag. 2020, 102, 391–403. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Afsari, K.; Eastman, C.M. A Comparison of Construction Classification Systems Used for Classifying Building Product Models; In Proceedings of the 52nd ASC Annual International Conference Proceedings, Provo, UT, USA, 13–16 April 2016.
- Ekholm, A. A Conceptual Framework for Classification of Construction Works. Electron. J. Inf. Technol. Constr. 1996, 1, 25–50. [Google Scholar]
- ISO 12006-3:2022; Building Construction—Organization of Information about Construction Works—Part 3: Framework for Object-Oriented Information. ISO: Geneva, Switzerland, 2022.
- RICS. NRM 1: Order of Cost Estimating and Cost Planning for Capital Building Works; RICS: London, UK, 2012; ISBN 978-1-84219-716-5. [Google Scholar]
- CSI&CSC. Masterformat; CSI: Alexandria, VA, USA, 2016. [Google Scholar]
- Gelder, J. The Principles of a Classification System for BIM: Uniclass 2015. In Proceedings of the 49th International Conference of the Architectural Science Association, Melbourne, VIC, Australia, 2–4 December 2015; Volume 1, pp. 287–297. [Google Scholar]
- NBS Uniclass 2015 | NBS. Available online: https://www.thenbs.com/our-tools/uniclass-2015 (accessed on 26 November 2019).
- European Committee of Construction Economists. Code of Measurement for Cost Planning CEEC; European Committee of Construction Economists: Brussels, Belgium, 2014; pp. 1–20. [Google Scholar]
- Davis Langdon Management Consulting. Life Cycle Costing (LCC) as a Contribution to Sustainable Construction: A Common Methodology; Davis Langdon Management Consulting: London, UK, 2007. [Google Scholar]
- Pernetti, R.; Kystallidi, K. D2.3: Structured Repository of Existing LCC Calculation Tools; European Commission: Brussels, Belgium, 2018. [Google Scholar]
- ICMS SSC. International Construction Measurement Standards: Global Consistency in Presenting Construction Costs; ICMS: London, UK, 2019. [Google Scholar]
- FIEBDC. Formato de Intercambio de Datos Estandar de Base de Datos de Construcción; FIEBDC: Madrid, Spain, 2020. [Google Scholar]
- Junta de Andalucía Base de Costes de La Construcción de Andalucía (BCCA)—Junta de Andalucía. Available online: https://www.juntadeandalucia.es/organismos/fomentoarticulaciondelterritorioyvivienda/areas/vivienda-rehabilitacion/planes-instrumentos/paginas/vivienda-bcca.html (accessed on 3 October 2023).
- Makarfi Ibrahim, Y.; Kaka, A.; Aouad, G.; Kagioglou, M. Framework for a Generic Work Breakdown Structure for Building Projects. Constr. Innov. 2009, 9, 388–405. [Google Scholar] [CrossRef] [Scilit]
- Gobierno de España. Real Decreto 1020/1993 de 25 de Junio, Por El Que Se Aprueban Las Normas Técnicas de Valoración y El Cuadro Marco de Valores Del Suelo y de Las Construcciones Para Determinar El Valor Catastral de Los Bienes Inmuebles de Naturaleza Urbana; Gobierno de España: Madrid, Spain, 1993. [Google Scholar]
- RAE Edificio | Definición | Diccionario de La Lengua Española | RAE—ASALE. Available online: https://dle.rae.es/edificio (accessed on 15 January 2020).
- ASTM E631; Standard Terminology of Building Constructions. ASTM International: West Conshohocken, PA, USA, 2015.
- ISO 6707-1; Buildings and Civil Engineering Works Vocabulary Part 1: General Terms. ISO: Geneva, Switzerland, 2020.
- Lufkin, P.S.; Miller, J.; Romani, L.; Towers, M. The Whitestone Facility Maintenance and Repair Cost Reference, 2010th ed.; Whitestone Research: Santa Barbara, CA, USA, 2009; ISBN 978-0-9670629-9-0. [Google Scholar]
- EN-15459-1; Energy Performance of Buildings. Economic Evaluation Procedure for Energy Systems in Buildings. Part-1. Calculation Procedures, Module M1-14. CEN: Brussels, Belgium, 2017.
- Junta de Andalucía Anexo, I. Programas de Necesidades Para Los Diferentes Tipos de Centros Docentes; Junta de Andalucía Anexo, I: Sevilla, Spain, 2003; p. 12. [Google Scholar]
- Gobierno de España. Real Decreto 1247/2008. Instrucción de Hormigón Estructural (EHE-08); Gobierno de España: Madrid, Spain, 2008. [Google Scholar]
- Ministerio de Fomento Boletín Estadístico Online—Información Estadística—Ministerio de Fomento. Available online: https://apps.fomento.gob.es/BoletinOnline2/?nivel=2&orden=36000000 (accessed on 12 May 2021).
- Ayuntamiento de Sevilla. Ordenanza Fiscal Por Prestación de Servicios Urbanísticos; Ayuntamiento de Sevilla: Sevilla, Spain, 2018; p. 30. [Google Scholar]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2024 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).