


Abstract
This paper studies insurance companies’ optimal reinsurance–investment strategy under the stochastic interest rate and stochastic volatility model, taking the HARA utility function as the optimal criterion. It uses arithmetic Brownian motion as a diffusion approximation of the insurer’s surplus process and the variance premium principle to calculate premiums. In this paper, we assume that insurance companies can invest in risk-free assets, risky assets, and zero-coupon bonds, where the Cox–Ingersoll–Ross model describes the dynamic change in stochastic interest rates and the Heston model describes the price process of risky assets. The analytic solution of the optimal reinsurance–investment strategy is deduced by employing related methods from the stochastic optimal control theory, the stochastic analysis theory, and the dynamic programming principle. Finally, the influence of model parameters on the optimal reinsurance–investment strategy is illustrated using numerical examples.
1. Introduction
Insurance companies face significant risks in the financial market due to the high volume of insurance claims. Consequently, risk avoidance and management become paramount for these companies. Recently, reinsurance has emerged as an effective tool for risk management, garnering considerable attention in the insurance industry. When confronted with overwhelming claims, insurance companies transfer a portion of the risk to a reinsurer, relieving their burden. Simultaneously, they invest the premiums received to enhance their ability to make repayments, ensuring the smooth operation of their insurance business. This strategic approach significantly boosts their net profit while maintaining a delicate balance between profitability and risk. Therefore, the selection of an optimal reinsurance–investment strategy holds immense importance for insurance companies.
Several examples of the results of stochastic differential equations are applied to optimal control problems. Święch [1] proved the optimality inequalities of dynamic programming for viscosity sub- and super-solutions of the associated Bellman–Isaacs equations, where the value functions are the unique viscosity solutions of the Bellman–Isaacs equations and satisfy the principle of dynamic programming. Soner and Touzi [2] introduced a new dynamic programming principle for optimal stochastic control problems. They proved that the value function of the stochastic target problem is a discontinuous viscosity solution of the associated dynamic programming equation, proposing that financial mathematics should be the main application. Rami et al. [3] introduced the generalized (differential) Riccati equation, a new type of differential Riccati equation to both solve the algebraic equality/inequality constraints and matrix pseudoinverse, and to also prove that the solution to such an equation can identify all optimal controls. In recent years, some achievements have been made in applying the stochastic models: Zhu and Li [4] studied relevant questions by modeling interest rates in the market using the Vasicek model. They derived equilibrium reinsurance–investment strategies and value functions using a comprehensive dynamic programming approach. Ali and Khan [5] used an automatic procedure to solve the resultant algebraic equation after the discretization of the stochastic Lotka–Volterra operator and the proposed scheme was applied to the equivalent integral form of stochastic fractional differential equations under consideration. Their numerical simulations further demonstrate the effectiveness that the fractional Atangana–Baleanu operator approach produces.
Notably, the issue of investment and reinsurance of insurance companies has received much attention in recent decades. For example, Browne [6] considered a diffusion risk model and studied the optimal investment strategy to maximize the exponential utility function of terminal wealth and minimize the probability of bankruptcy. Yang and Zhang [7] studied the optimal investment strategy of an insurance company with a jump –diffusion risk process to minimize the ruin probability. Hipp and Plum [8] developed a compound Poisson risk model to determine the optimal investment strategy by minimizing the bankruptcy probability and the capital market index. For the reinsurance problem, Promisslow and Young [9] extended Browne’s work by considering investing in risky assets and purchasing proportional reinsurance. They obtained the minimum bankruptcy probability and the optimal reinsurance–investment strategy. Bai and Zhang [10] studied the optimal ratio reinsurance and investment strategies in the classical and diffusion risk models because short-selling is prohibited. Ramadan et al. [11] came up with a new distribution method considering the appropriate transformation for half-logistic geometric (HLG) distribution and introduced an application in the insurance field to show its flexibility.
In addition, the logarithmic utility function, exponential utility function (CARA), and power utility function (CRRA) [12] commonly used in the field of actuarial insurance are exceptional cases of the hyperbolic absolute risk utility function (HARA). Therefore, the HARA utility function is more representative and has a more general mathematical structure and a more comprehensive range of applications. However, because the structure of the HARA utility function is more complex than the logarithmic utility, exponential utility, and power utility functions, there are few studies on the optimal reinsurance–investment strategy of insurance companies under the HARA utility function. Representative studies include the following: Jung and Kim [13] used the Legendre dual transformation method under the CEV model to solve the optimal investment problem under the HARA utility criterion and obtained a definitive solution. Chang and Chang [14] studied the consumption and investment problem under the HARA utility function when the interest rate was the same as the Vasicek stochastic interest rate model and obtained the explicit solution of the optimal strategy. Zhang and Zhao [15] studied the optimal reinsurance–investment problem related to sparse risk based on the HARA utility function, in which the CEV model drove the price of risky assets, and they obtained the closed-form expression of the optimal strategy. Zhang [16] studied the optimal asset–liability management problem under the framework of maximizing the expected utility, taking a variety of stochastic volatility models as a particular case and using the backward stochastic differential equation (BSDE) method to derive closed-form expressions for optimal investment strategy and optimal value function. Through the research literature, it was found that the HARA utility function was more widely used than the logarithmic utility function, exponential utility function, and power utility function. Regarding consumption investment and optimal asset–liability management, few studies in the literature have been applied towards studying the optimal portfolio strategies of insurance companies.
Although optimal reinsurance–investment strategies under the HARA utility criterion have been studied extensively, two aspects still require further exploration. First, most of the literature mentioned was studied with the precondition of constant or deterministic volatility, which differs from the facts observed in financial markets, such as volatility smiles and clustering. Therefore, in recent years, many studies have proposed various local volatility models and stochastic volatility models to serve as extensions of the deterministic volatility models, such as the CEV model [17], the Stein–Stein model [18], and the Heston model [19]. For example, Gu et al. [20] assumed that the insurance company’s earnings process approximates the Brownian motion with drift and studied the optimal excess-of-loss reinsurance and investment strategy under the CEV model. Wang et al. [21] derived time-consistent reinsurance strategies before and after default using a game-theoretic framework that considers the strategy feedback time lag and the stock price following the CEV model. Huang et al. [22] studied the robust optimal investment and proportional reinsurance problems of general insurance companies, including insurers and reinsurers, under the Heston model. Zhu et al. [23] considered the relative performance problem. They derived the equilibrium investment reinsurance strategy’s closed-form expression and corresponding value function based on the Heston model by applying the stochastic control theory. Zhang et al. [24] applied the Legendre transformation and stochastic control theory to obtain the optimal excess-of-loss reinsurance and investment strategy with dependent claims under the Heston model. Yan and Wong [25] first applied the open-loop LQ control framework to the reinsurance investment problem in general SV incomplete markets, deriving explicit solutions for the Hull–White SV model, the unleveraged Heston model, and the unleveraged 3/2 SV models, and gave uniqueness conditions for all of the above equilibrium controls that allow straightforward solutions.
Most of the above literature assumes that the interest rate was constant or deterministic, which ignores the application of some specific interest rate models in actual situations, such as the Vasicek model and the CIR model. Many scholars have studied the optimal reinsurance–investment problem with stochastic interest rates: Sheng [26] considered the reserve process with dynamic returns to study the reinsurance-–investment problem of insurance companies under the Vasicek stochastic interest rate model; Zhang and Zheng [27] studied the optimal reinsurance-–investment strategy of insurance companies under the Ho–Lee and Vasicek models, respectively, and explained the impact of two different stochastic interest rate models on the optimal decision-making of insurance companies. Yuan et al. [28] used the linear quadratic optimal control theory and the corresponding Hamilton–Jacobi–Bellman (HJB) equation to study the optimality of the interest rate subject to the Vasicek stochastic interest rate model in case the bond and stock processes are fully correlated. On investment and reinsurance issues, Guo and Zhuo [29] assumed that the extended CIR model described domestic and foreign nominal interest rates. They used dynamic programming principles to study the optimal reinsurance–investment strategy of insurance companies investing in domestic and foreign markets. Sun and Guo [30] studied insurance companies’ optimal investment and reinsurance problems under the mean–variance criterion by applying reverse stochastic differential equations where the stock prices obey the Cox–Ingersoll–Ross (CIR) process.
In most of the literature reviewed on optimal reinsurance investments, only a random factor was considered. However, in real-world financial markets, it is better to consider the optimal reinsurance–investment strategy with random volatility and random interest rates. For example, Wang et al. [31] studied the time-consistent open-loop equilibrium reinsurance–investment strategy of insurance companies under Vasicek’s stochastic interest rate model and Heston’s stochastic volatility model. Guan et al. [32] introduced an inflation index and studied the robust optimal reinsurance and investment problem of fuzzy risk-averse insurance companies, where the stock prices are described using Heston’s stochastic volatility model and the interest rates are described via Vasicek’s model. Zhang et al. [33] introduced stochastic interest rates and stochastic volatility into optimal proportional reinsurance and investment strategies based on insurers’ CRRA utility criterion and reinsurers’ CARA utility criterion.
There are scattered results on the optimal reinsurance–investment strategy based on the HARA utility function in the stochastic financial market. To our knowledge, no research has yet been conducted on the optimal reinsurance–investment strategy under the HARA utility criterion, considering both the risk assets subject to the Heston model and the interest rates subject to the CIR model. The multiple stochastic factors and the variance premium principle are considered more practical and valuable for research. Here, we explore the optimal proportional reinsurance problem under a diffusion approximation claims model based on the stochastic factors, maximizing the HARA utility of the terminal wealth value.
We studied the optimal reinsurance–investment problem for insurers considering stochastic volatility and stochastic interest rates under the HARA utility function criterion. We use the arithmetic Brownian motion as a diffusion approximation to the insurer’s surplus process. We assume that the financial market comprises risk-free assets, risky assets, and zero-coupon bonds. The insurance company can purchase proportional reinsurance and invest its surplus in a financial market of risk-free assets, risky assets, and zero-coupon bonds to maximize the expected ultimate return. The Heston model describes the price of this risky asset while the CIR model describes the risk-free rate. In addition, we assume that the proportion of reinsurance purchases must be non-negative and that there are no borrowing and short-selling constraints in the trading of financial assets. The HJB equation for the wealth process is established using dynamic programming principles. The nonlinear partial differential equation is solved using the Legendre transformations and pairwise theory. This ultimately leads to an optimal reinsurance–investment strategy for the insurance company and an analytical expression for the value function.
The rest of the paper is organized as follows: Section 2 establishes the model and gives the optimal reinsurance–investment problem of the insurance company in the stochastic financial market. Section 3 obtains the optimal reinsurance–investment strategy of the insurance company. In Section 4, several numerical examples are provided to illustrate our results. Finally, in Section 5, we present our conclusions.
2. The Model
In this section, we investigate the problem of optimal reinsurance–investment strategies with CIR rates under the Heston model from the perspective of insurance companies, using the HARA utility function as the criterion. The model in this section consists of equities , zero-coupon bonds , and risk-free assets . Assuming that the price of risky assets follows the Heston stochastic volatility model and the stochastic interest rate meets the CIR interest rate model, and to maximize the HARA utility function of terminal wealth, the corresponding HJB equation was solved by applying the dynamic programming principle and employing both the Lejeune transformation and pairwise theory to solve the corresponding HJB equation, to obtain the analytical expressions for the optimal reinsurance–investment strategy and value function of the insurance company.
2.1. Surplus Process
Let be a complete probability space, with the total amount of information flow held by the insurance company up to time . We assume that all stochastic processes are adapted processes in this probability space. The expression is the natural information flow generated using the dimensional Brownian motion , with and independent of each other, . In the classical risk model, the earnings process of insurance companies can be described using the following classical Cramér–Lundberg model:
where . is the initial capital of the company, is the premium rate, and the claim number process is a time-homogeneous Poisson counting process with a density parameter of , a positive random variable sequence with mutual independent and identically distributed random variables, and where represents the amount of each claim and is also independent of the Poisson point process . For simplicity, let be a general random variable with the same distribution function as . The first and second moments of are and , respectively, and the generating function of the moment is recorded as . Suppose there is a constant , and for , we have and . According to Grandell [34], the claim process can be approximated using the diffusion of the Brownian motion with drift. That is, the diffusion claim model can be calculated using the following equation:
where is a standard Brownian motion, is the claim rate; is the volatility of the insurance company’s claim process; , ; and and are the first and second moments of , respectively. Assuming that the premium is paid at the interest rate , is the premium return rate, is the safe load of the insurance company, and is the safe load of the reinsurance company. When there is no reinsurance or investment, the surplus process of the insurance company is
and the earning process becomes
2.2. Financial Market
To enrich the financial markets, we assume that they consist of risk-free assets, equities, and zero-coupon bonds.
For a risk-free asset, we set as the price at the moment of , to satisfy the following differential equation
The CIR model describes short-term interest rates:
where initial values are , is the average regression velocity, is the mean of the previous period, is the interest rate volatility and .
For a risky asset, we denote the price at the moment of as , satisfying the Heston stochastic volatility model:
where , , parameters , , , , , and are all positive numbers, and .
For a zero-coupon bond, we assume that the expiration date is and the price at is noted as , which satisfies the following differential equation
where
2.3. Wealth Process
The insurance company purchases proportional reinsurance and invests in a financial market of equities, risk-free assets, and zero-coupon bonds. The reinsurance–investment strategy iis ; then, we set as the wealth process of the insurer at the time of . Assuming that the amount invested in risky assets is and the amount invested in zero-coupon bonds is denoted as , then the amount invested in risk-free assets is . The wealth process of the insurer under the strategy satisfies the following differential equation:
Substituting the differential equations of (6), (7) and (8) into the wealth process (11) above gives the following equation:
where the initial wealth .
Definition 1.
(Allowable strategy) The reinsurance–investment strategy is defined as an allowable strategy if meets the following conditions:
- (i)
- , and are -measurable, , ;
- (ii)
- (iii)
- , the stochastic Equation (12) has a unique solution.
Let be the space of all acceptable reinsurance–investment strategies. Assuming the optimal strategy , the insurer expects to find the optimal reinsurance–investment strategy that maximizes the expected utility of its terminal wealth, i.e.,
where is the utility function of the insurance company.
3. Optimization Problem and the Optimal Strategy
The optimization problem is considered in this section and the corresponding optimal strategy is derived. We examine the optimal reinsurance strategy of an insurer under the HARA utility function
where .
At time , we define the value functions for instantaneous volatility , instantaneous interest rate , and wealth as
and then, the optimal value function can be expressed as
where the boundary conditions meet
The arbitrary value function defines the variational operator as
where represent the first- and second-order partial derivatives with respect to the corresponding variables. The value function is a convex function, given as the dyadic variable of the vvariable , and its Legendre transformation is defined as follows:
Denote as the optimal value of the variable and , assuming that satisfies the following equation
with the boundary condition
where we then obtain the relation between and :
Therefore and are both pairwise functions of the value function . In solving the optimal reinsurance strategy, the function is easier to calculate numerically, so the function is chosen for this study.
Theorem 1.
When an insurance company adopts the HARA utility function as the optimal criterion, the reinsurance–investment problem (13) under the Heston model considering stochastic interest rates has the following optimal reinsurance–investment strategy:
Proof.
See Appendix A.
To verify that the result mentioned in Theorem 1 is the optimal reinsurance–investment strategy for the insurance company, we introduce the following verification theorem (Yong and Zhou [35]).
Theorem 2.
(Verification theorem) Suppose that given in Equation (A57) is a solution of the HJB Equation (A1); then, for any allowable strategy , there is , and
When , we have
4. Sensitivity Analyses and Numerical Experiments
In this section, we conduct a sensitivity analysis of the parameters related to the optimal reinsurance–investment strategy and match it with the reality in the financial market. The optimal reinsurance–investment strategy obtained in the previous section will be analyzed through numerical calculation experiments to obtain the parameter changes related to the reinsurance ratio, stochastic volatility, stochastic interest rate, and their dynamic impact on the optimal strategy.
The model parameter settings in this section refer to the work of Deelstra et al. (2003) [36], Guan and Liang (2014) [37], and Chang and Chang (2017), and the parameter values are shown in Table 1. Without loss of generality, we take and only discuss the impact of model parameters on the optimal strategy at the initial moment, as shown in the figures below.
Table 1.
Parameter values.
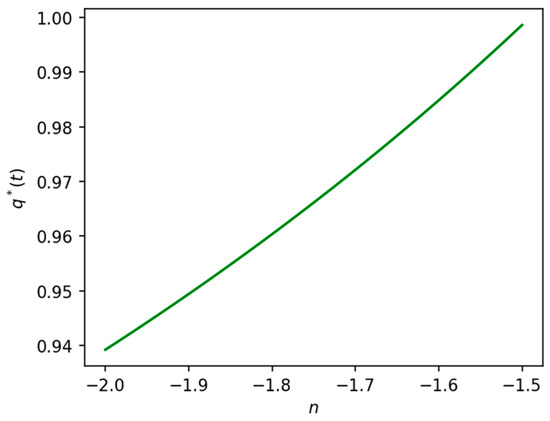
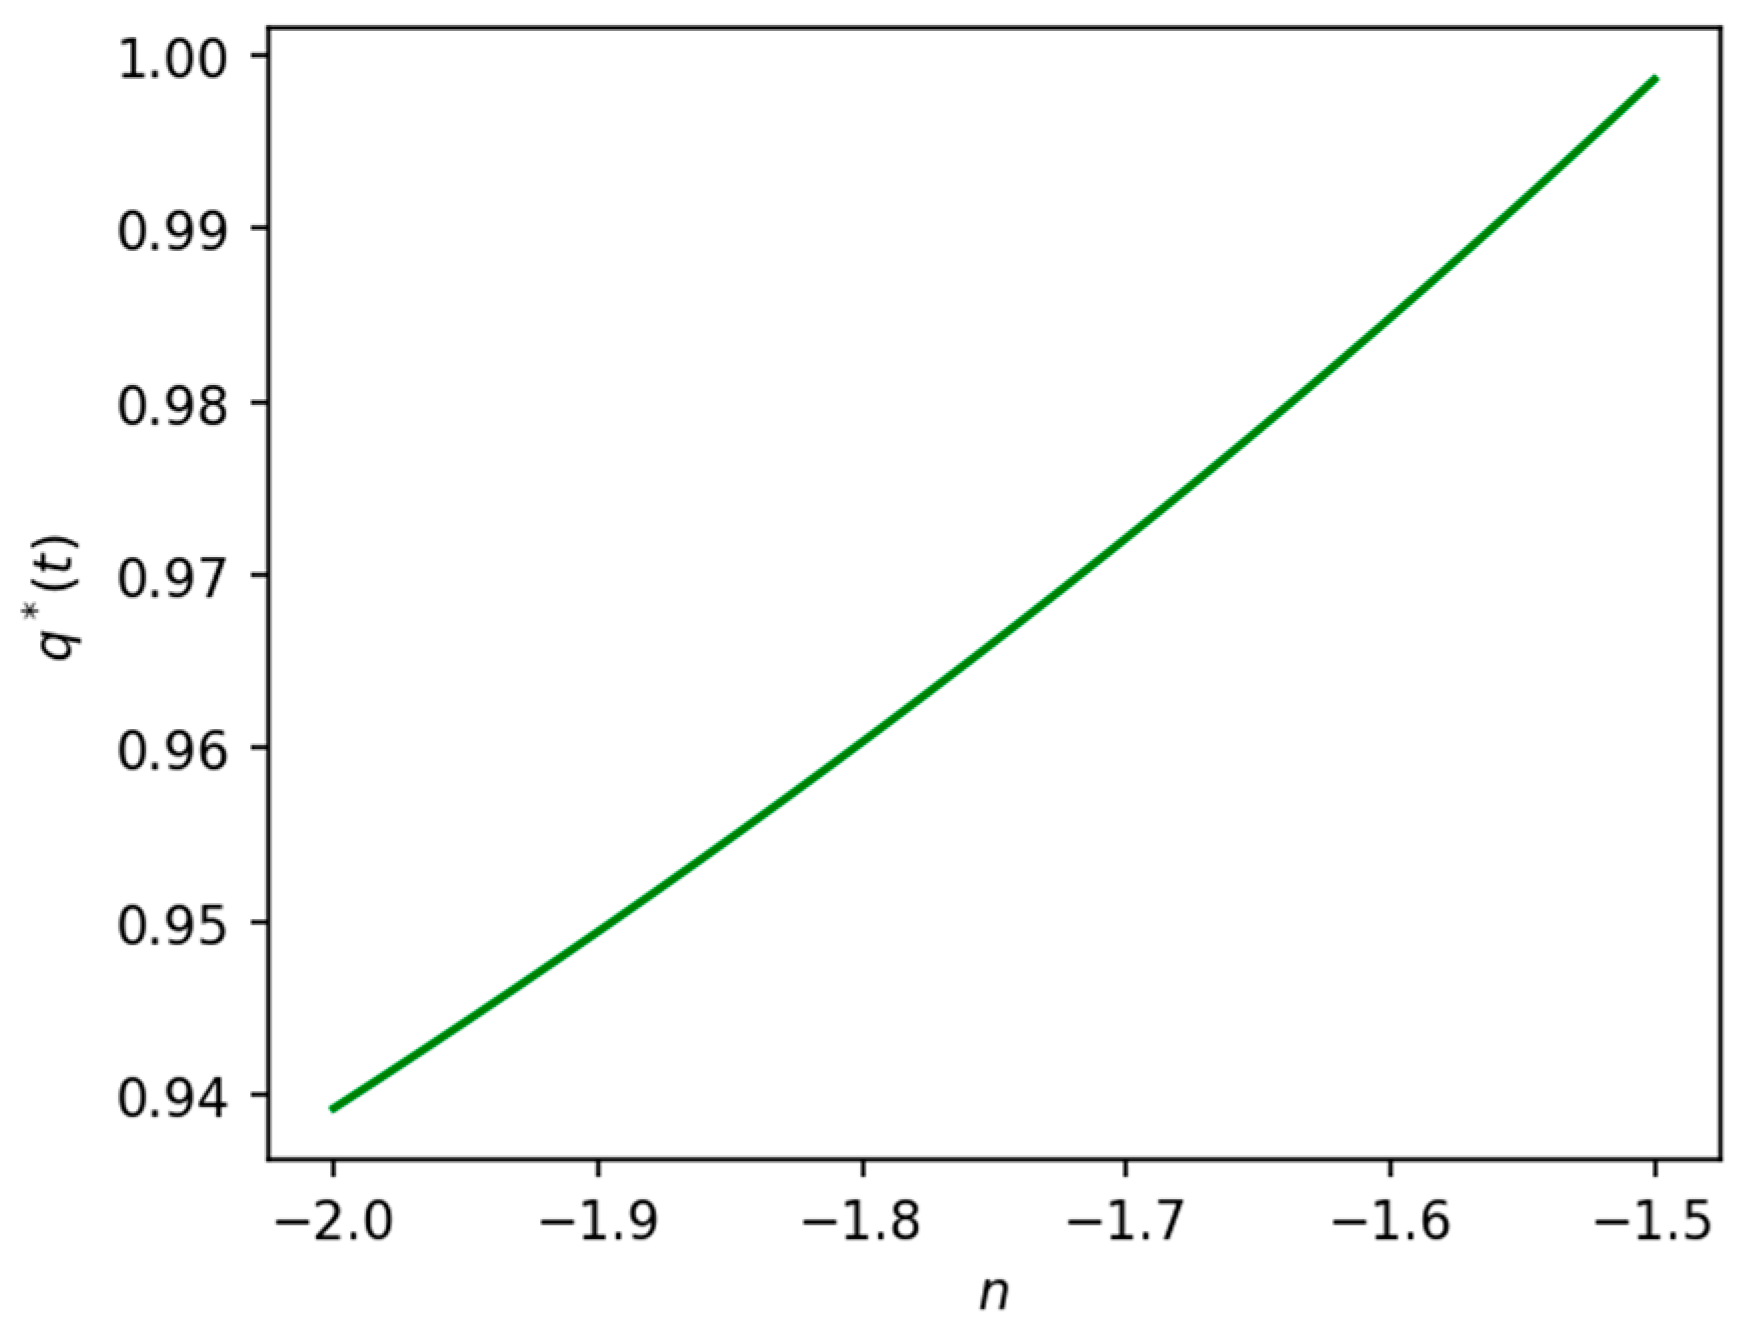
In Figure 1, the parameter is used to measure the degree of risk aversion of an insurance company, that is, the trade-off between the rate of return and the risk it requires when facing the same risk. Specifically, the larger is, the smaller the absolute risk aversion of the insurance company. Figure 1 shows that the insurance company’s reinsurance retention share usually increases when the risk aversion factor rises because the insurance company’s aversion to risk decreases and its tolerance to risk increases, so it can reduce reinsurance protection and improve its retained share.
Figure 1.
The influence of parameter on the optimal reinsurance strategy.
Conversely, when decreases, its reinsurance retention generally decreases. When an insurance company’s risk aversion increases, it requires a higher rate of return for the same risk. Therefore, it requires more reinsurance protection to reduce the risk it faces, thereby reducing its retained share.
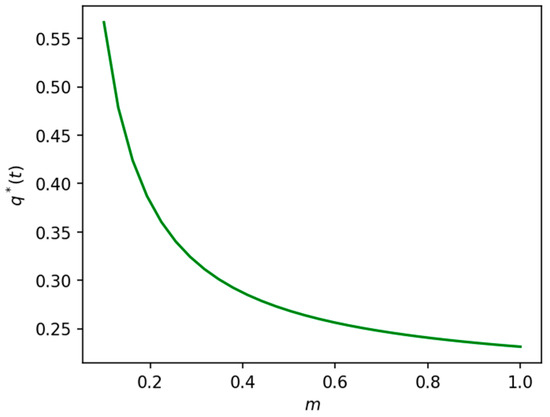
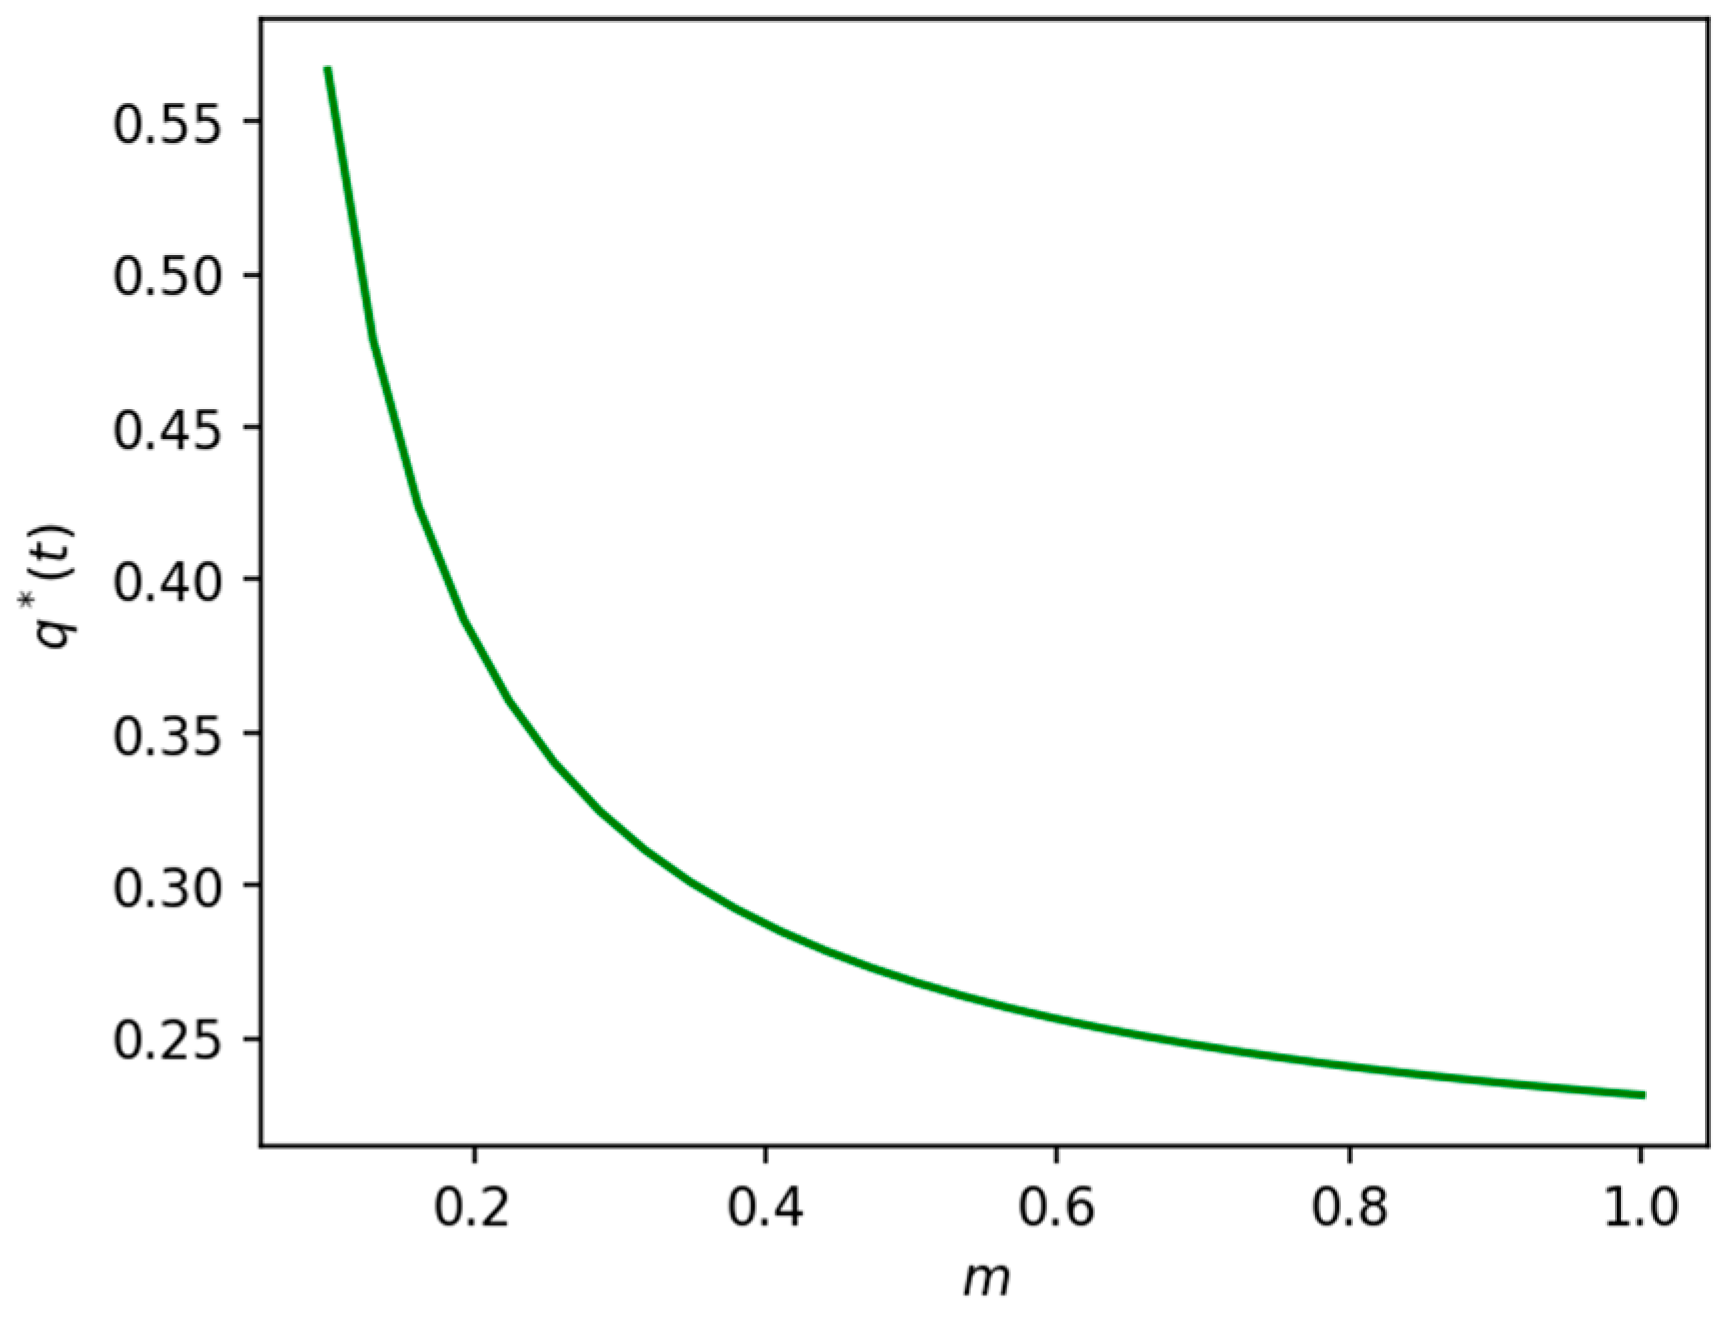
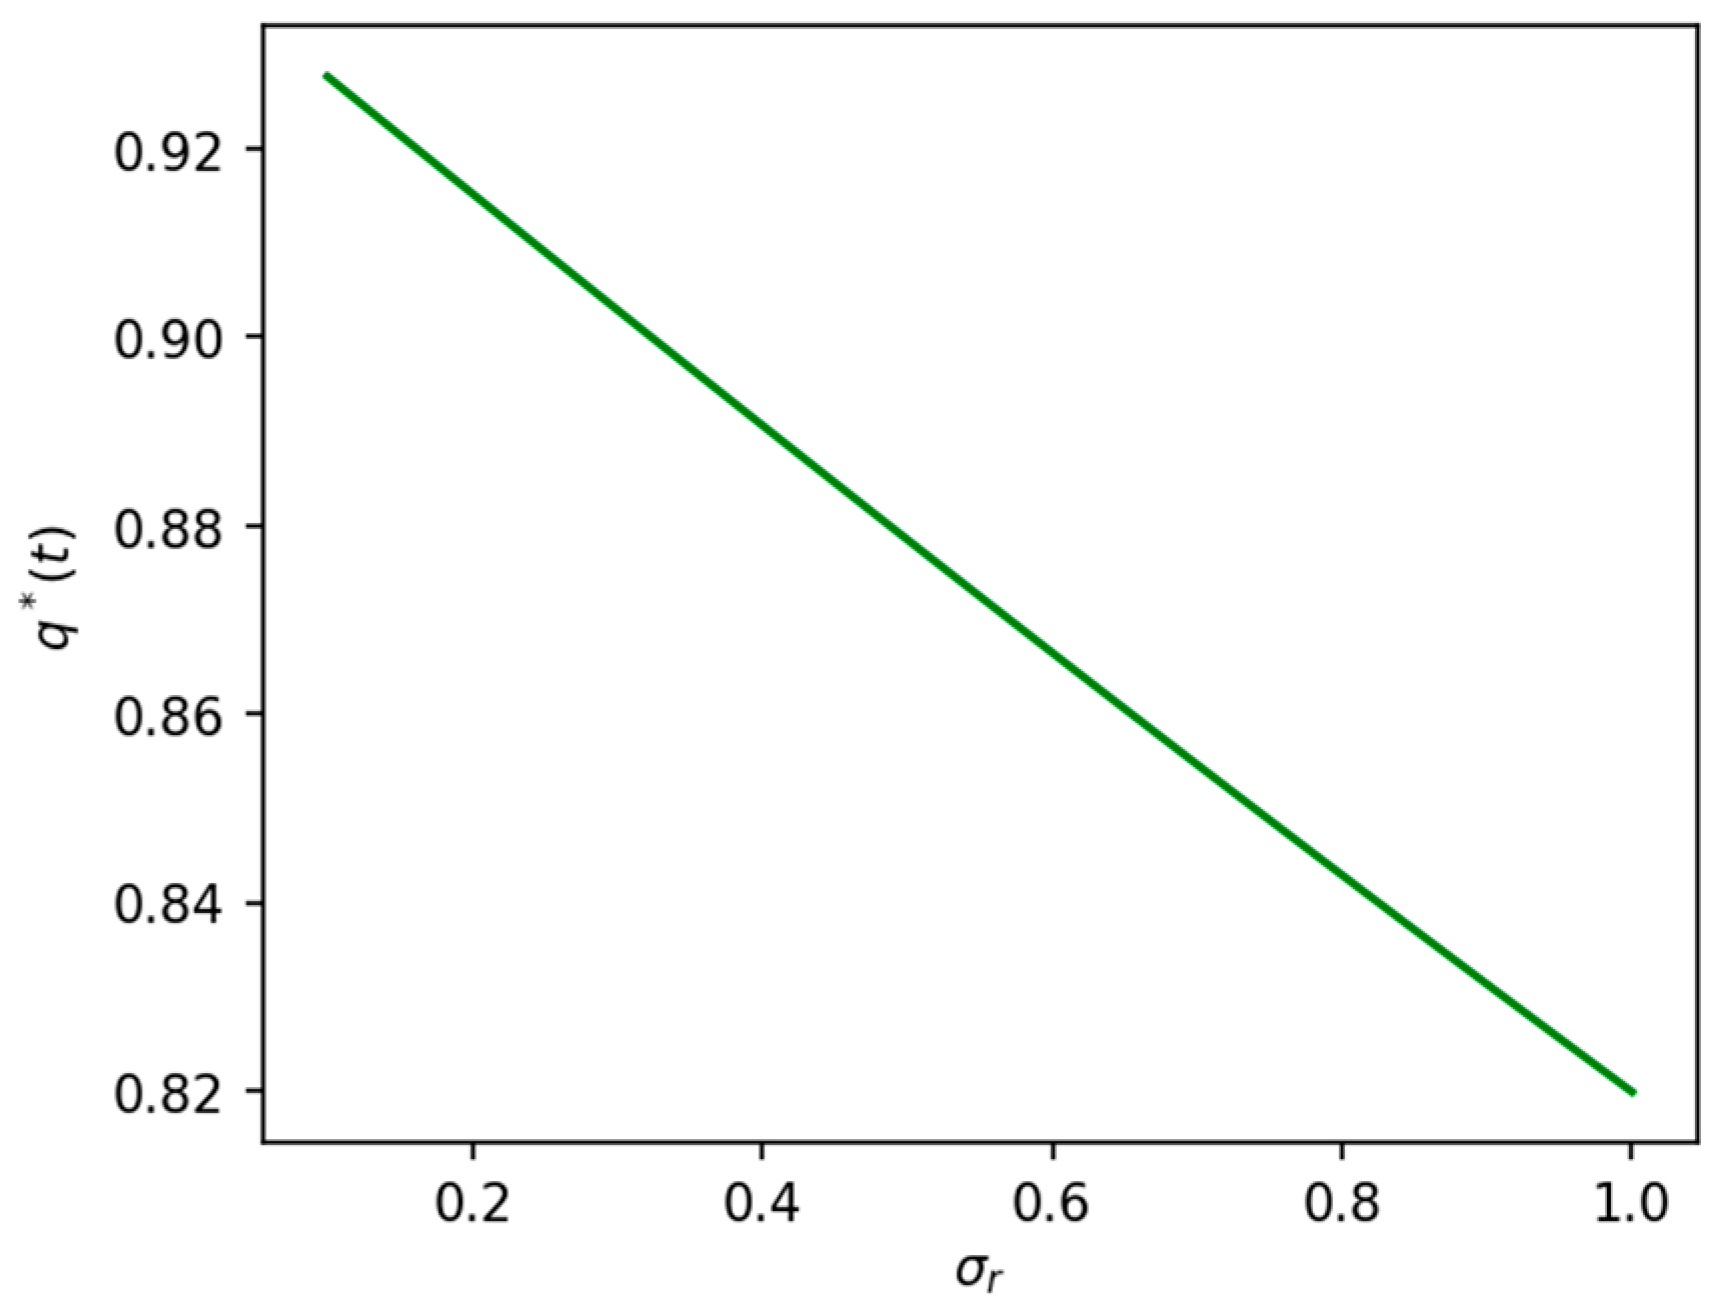
Figure 2 indicates that the insurance company’s optimal retention ratio decreases with the parameter’s increase . The larger is, the greater the risk aversion of the insurance company. Therefore, if the insurance company chooses to bear less compensation risk, the reinsurance ratio grows and the insurance payment risk the reinsurer bears increases.
Figure 2.
The influence of parameter on the optimal reinsurance strategy.
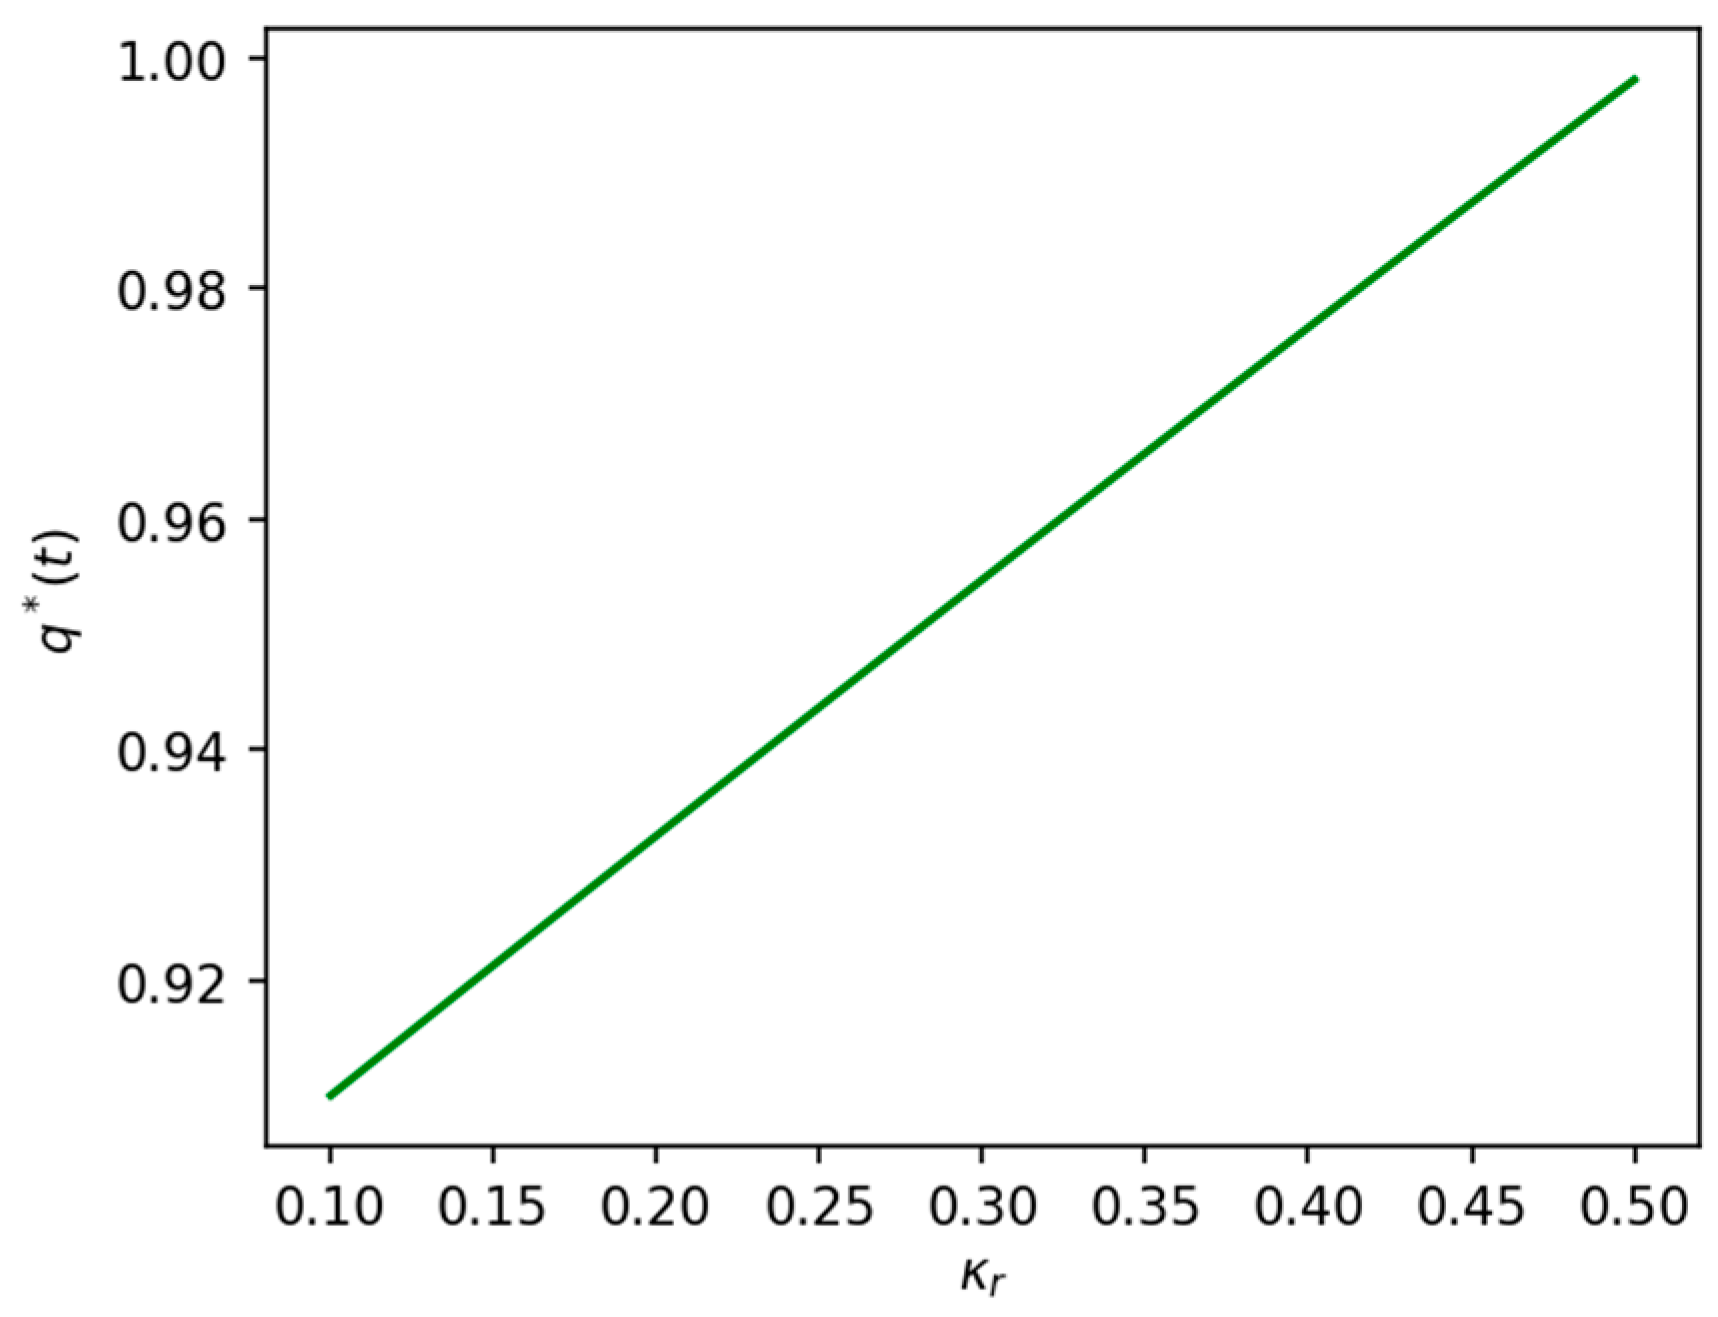
In Figure 3, the parameter represents the average reversion speed of interest rates, which refers to the speed at which market interest rates return from past highs or lows to their long-run average. Typically, the faster interest rates revert to the mean, the more volatile the market. The figure above shows that the optimal retention ratio rises as the parameter increases. Under the safety load factor condition , insurance companies may worry that changes in market interest rates will harm their reinsurance asset management and may choose to improve the reinsurance retained share to reduce the risk of their reinsurance asset management. In this case, with faster returns in the interest rate to the average, the insurance company may choose to increase the reinsurance retained share to reduce the risk of its reinsurance asset management.
Figure 3.
The influence of parameter on the optimal reinsurance strategy.
In practice, insurance companies usually take some measures to reduce the impact of changes in market interest rates on their reinsurance asset and liability management. For example, insurers can balance interest rate risks between their reinsurance assets and liabilities by holding the assets for longer durations until maturity or by matching liabilities with assets. In addition, insurance companies can also use instruments such as interest rate derivatives to hedge the interest rate risk between their reinsurance assets and liabilities.
In Figure 4, the parameter represents the interest rate fluctuation. When the parameter increases, the risk caused by the interest rate fluctuation also grows. The reinsurance strategy of the insurance company is usually more conservative, that is, retaining less self-retained shares and sharing more reinsurance to reduce the impact of interest rate fluctuations on its financial position.
Figure 4.
The influence of parameter on the optimal reinsurance strategy.
Since high-interest rate volatility means that the cash flow risk of insurance companies is more remarkable (unacceptable for insurance companies with a high degree of risk aversion), the insurance company will increase the proportion of reinsurance to reduce its retention and cash flow risk, thereby protecting its financial position. On the other hand, when interest rate volatility is low, insurers typically opt for less reinsurance to obtain a higher rate of return. Low-interest rate volatility means that insurance companies have less of a cash flow risk. Currently, insurance companies can take higher risks in pursuit of higher returns.
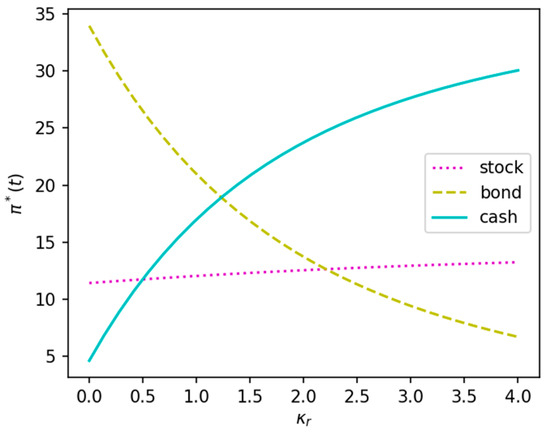
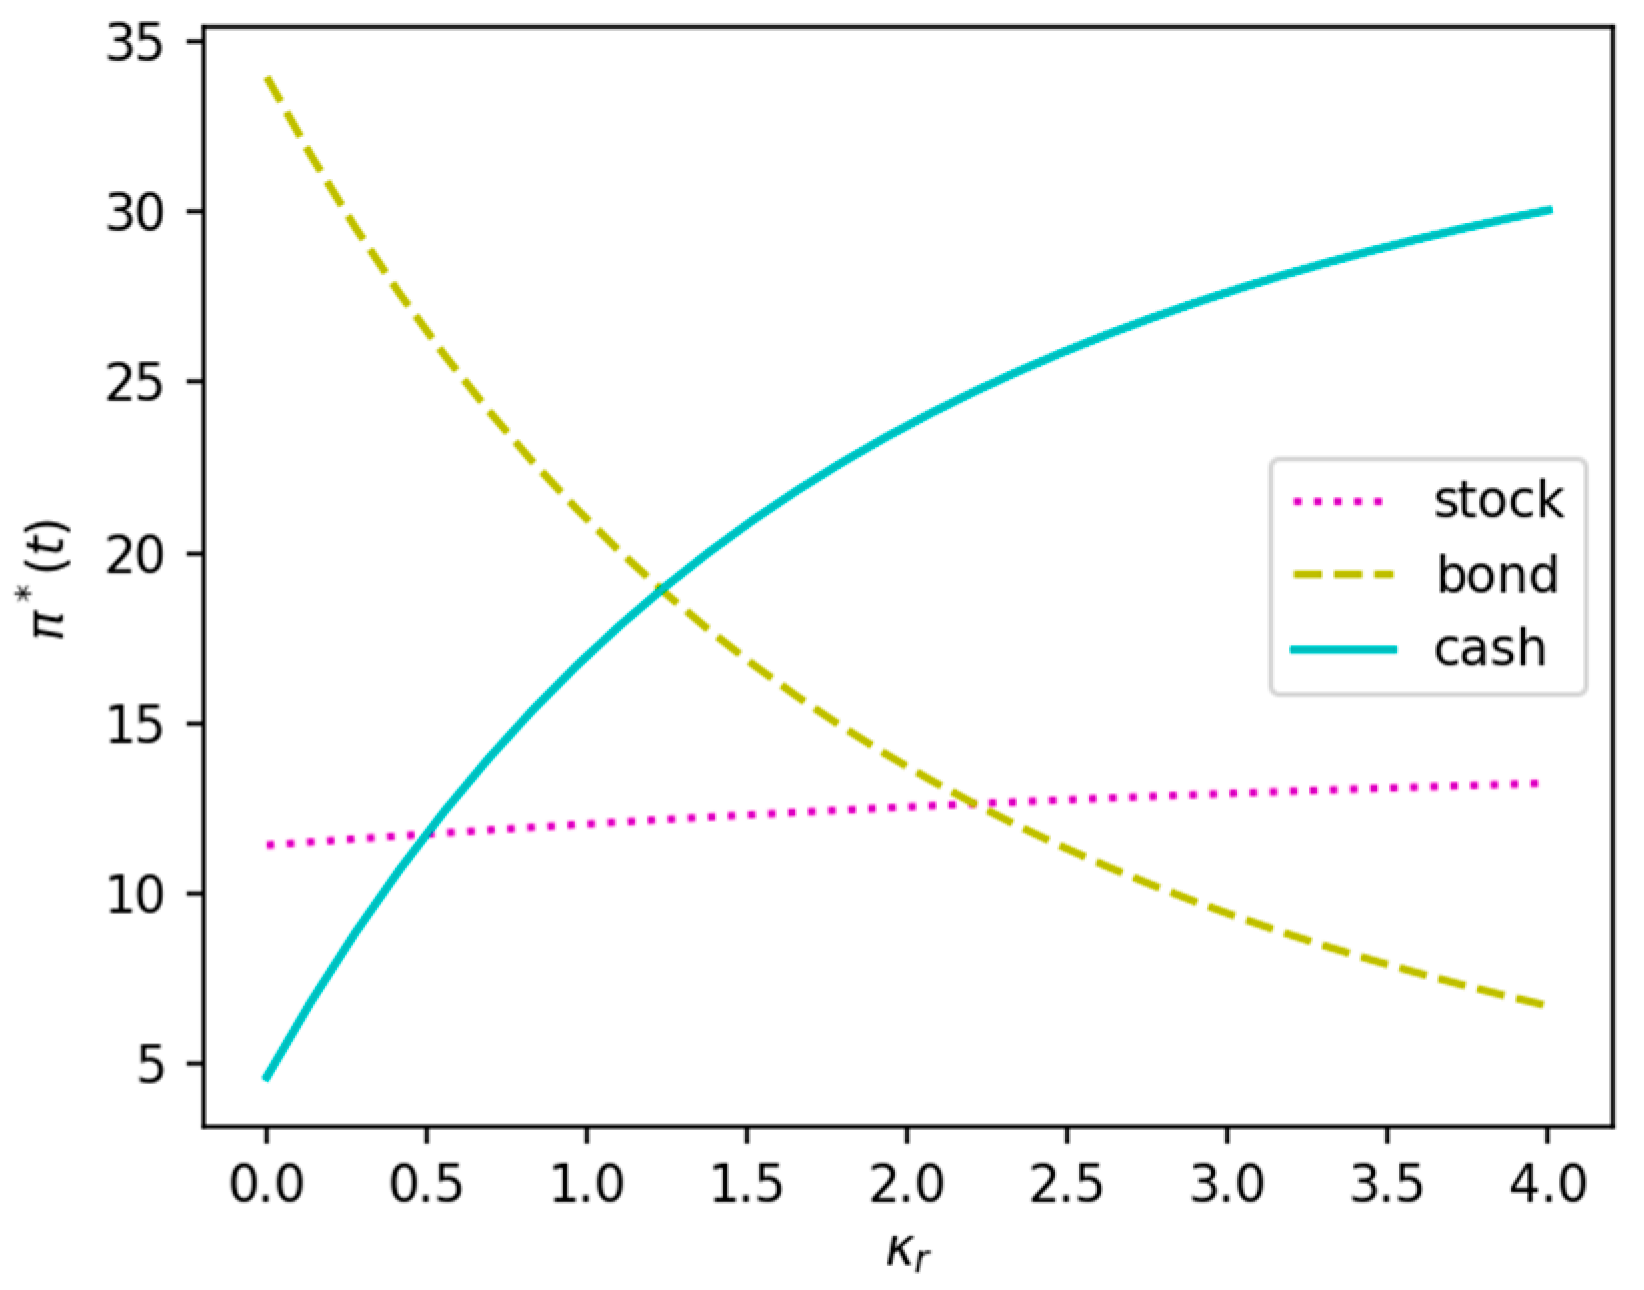
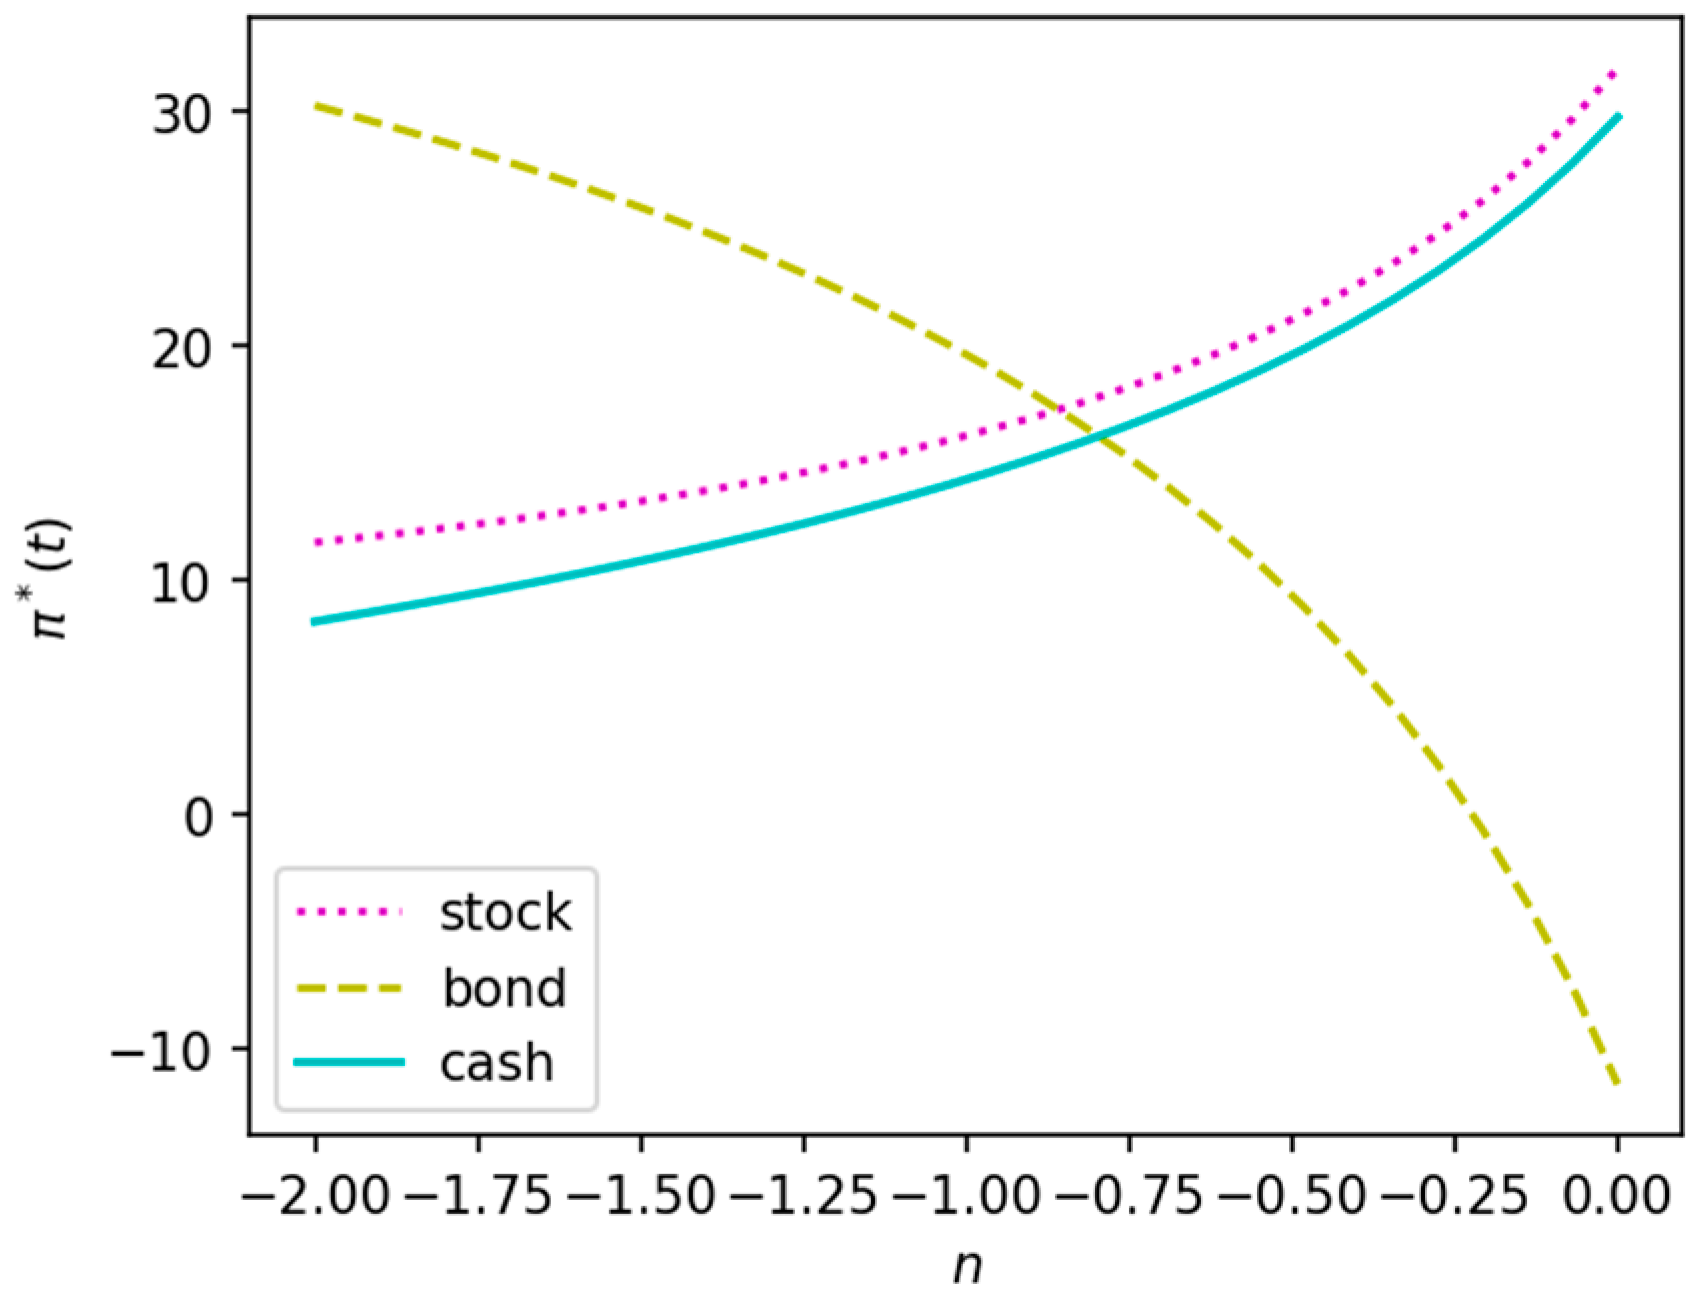
Figure 5 gives that as increases, strategies investing in risky assets and strategies in risk-free assets grow, while strategies in zero-coupon bonds decrease. The high regression speed of the stochastic interest rate in the CIR model means that interest rates change faster, so insurance companies need to adjust their asset allocation more frequently to adapt to changes in the market.
Figure 5.
The influence of parameter on the optimal investment strategy.
In this case, the insurance company will increase its investment in risky assets since they usually have higher yields, which can help improve its return on the investment. At the same time, insurance companies also add their investments in risk-free assets to protect their portfolios from price fluctuations in risky assets.
Instead, insurers reduce their exposure to zero-coupon bonds because these bonds typically have lower yields and their prices are affected by the fluctuations in interest rates. As a result, insurers typically reduce their exposure to zero-coupon bonds to reduce their exposure and raise their returns when the rate of reversion increases.
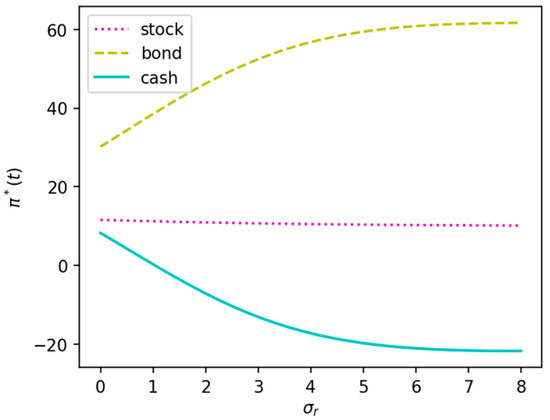
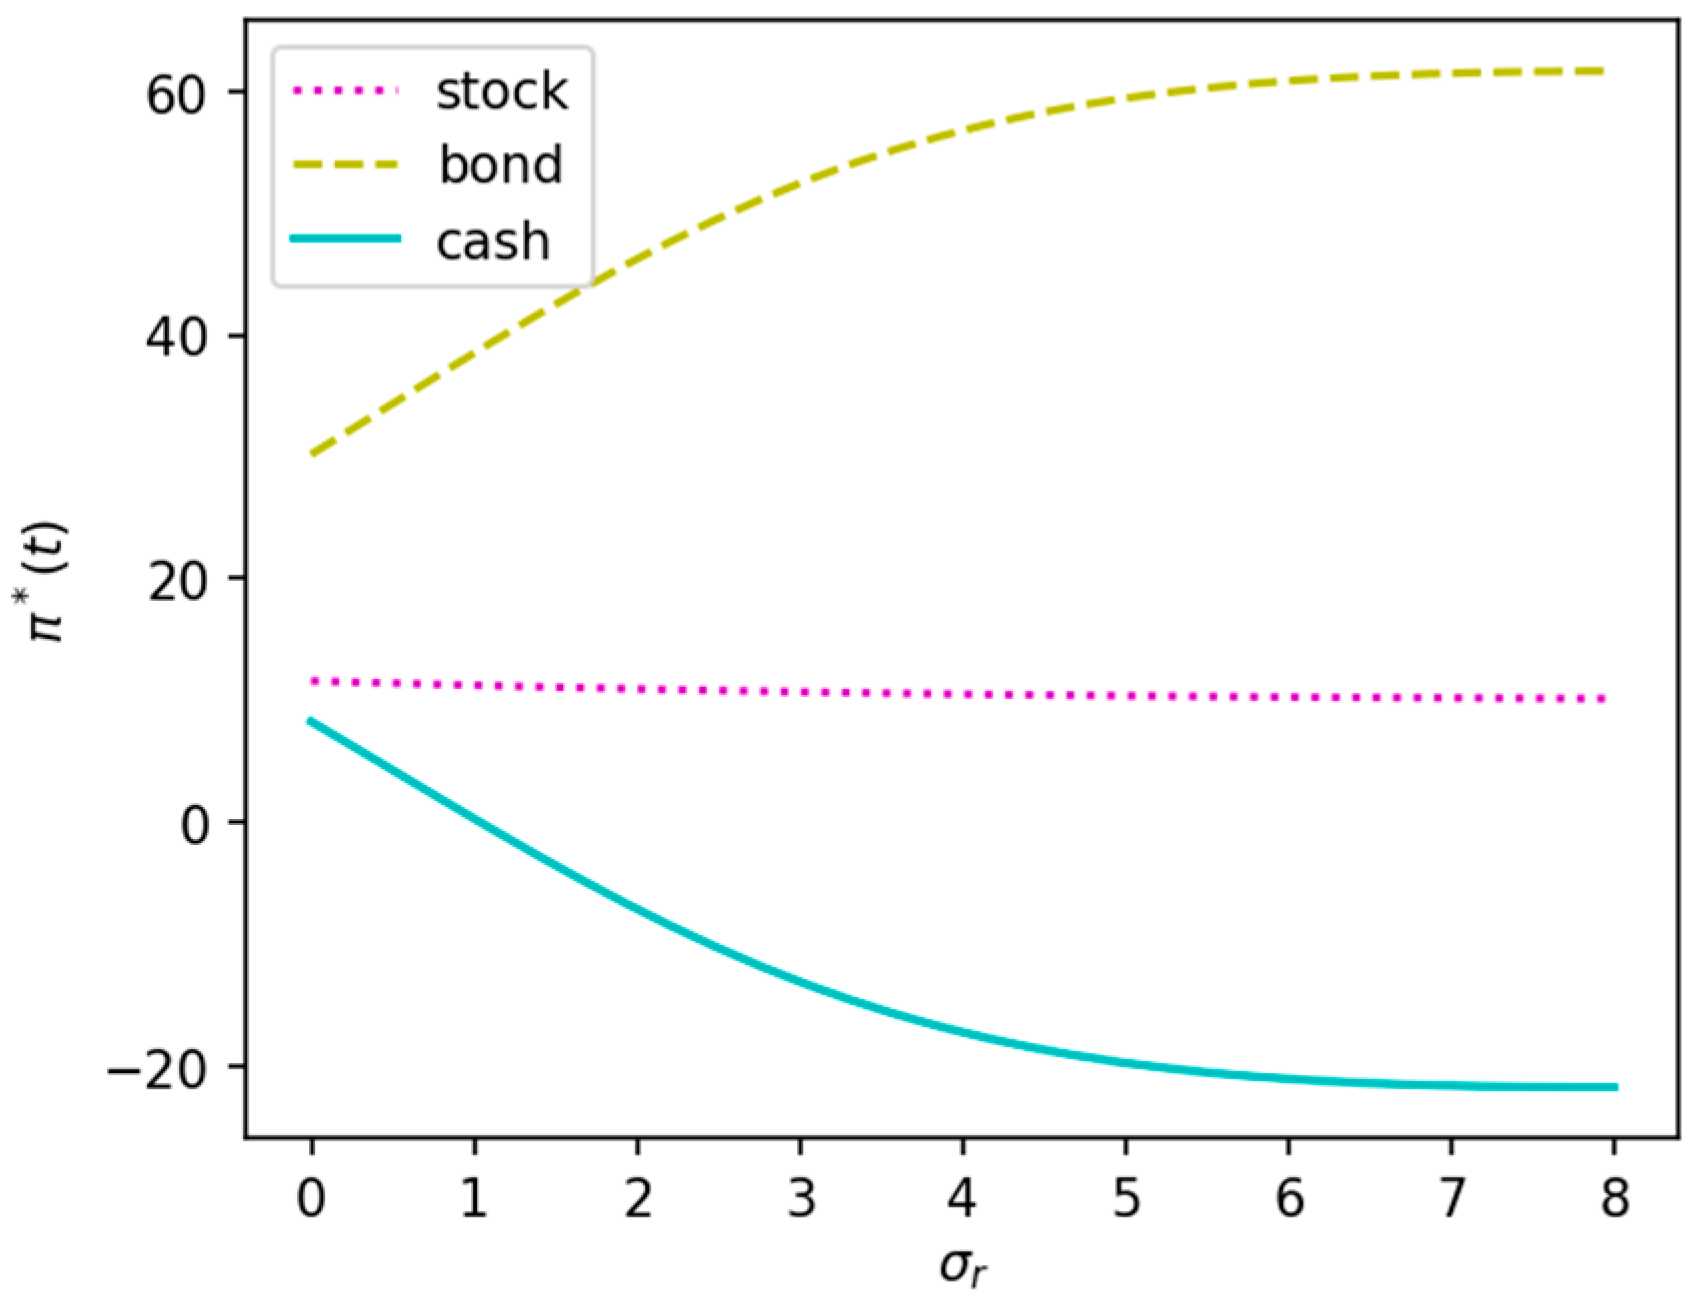
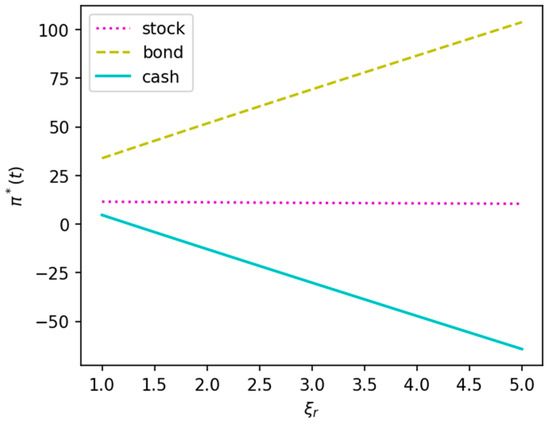
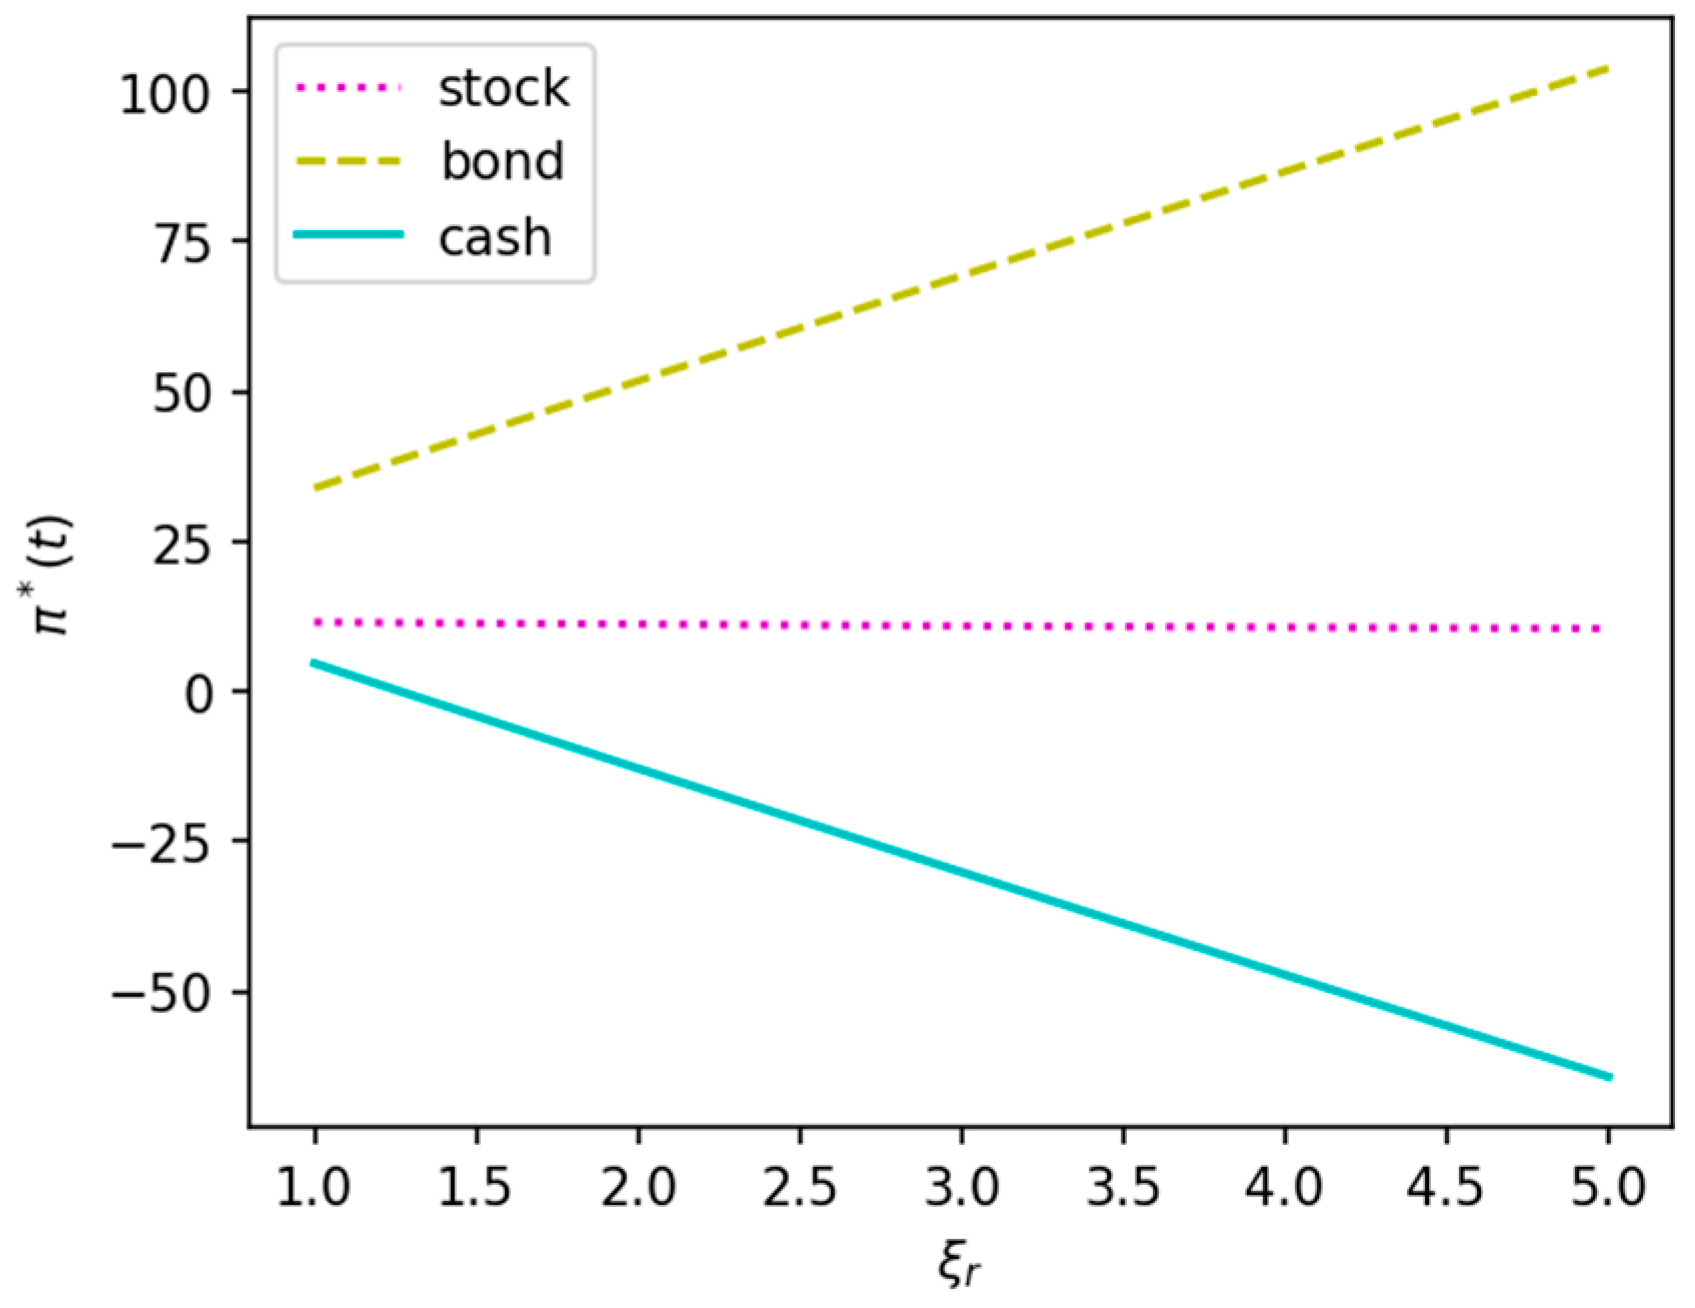
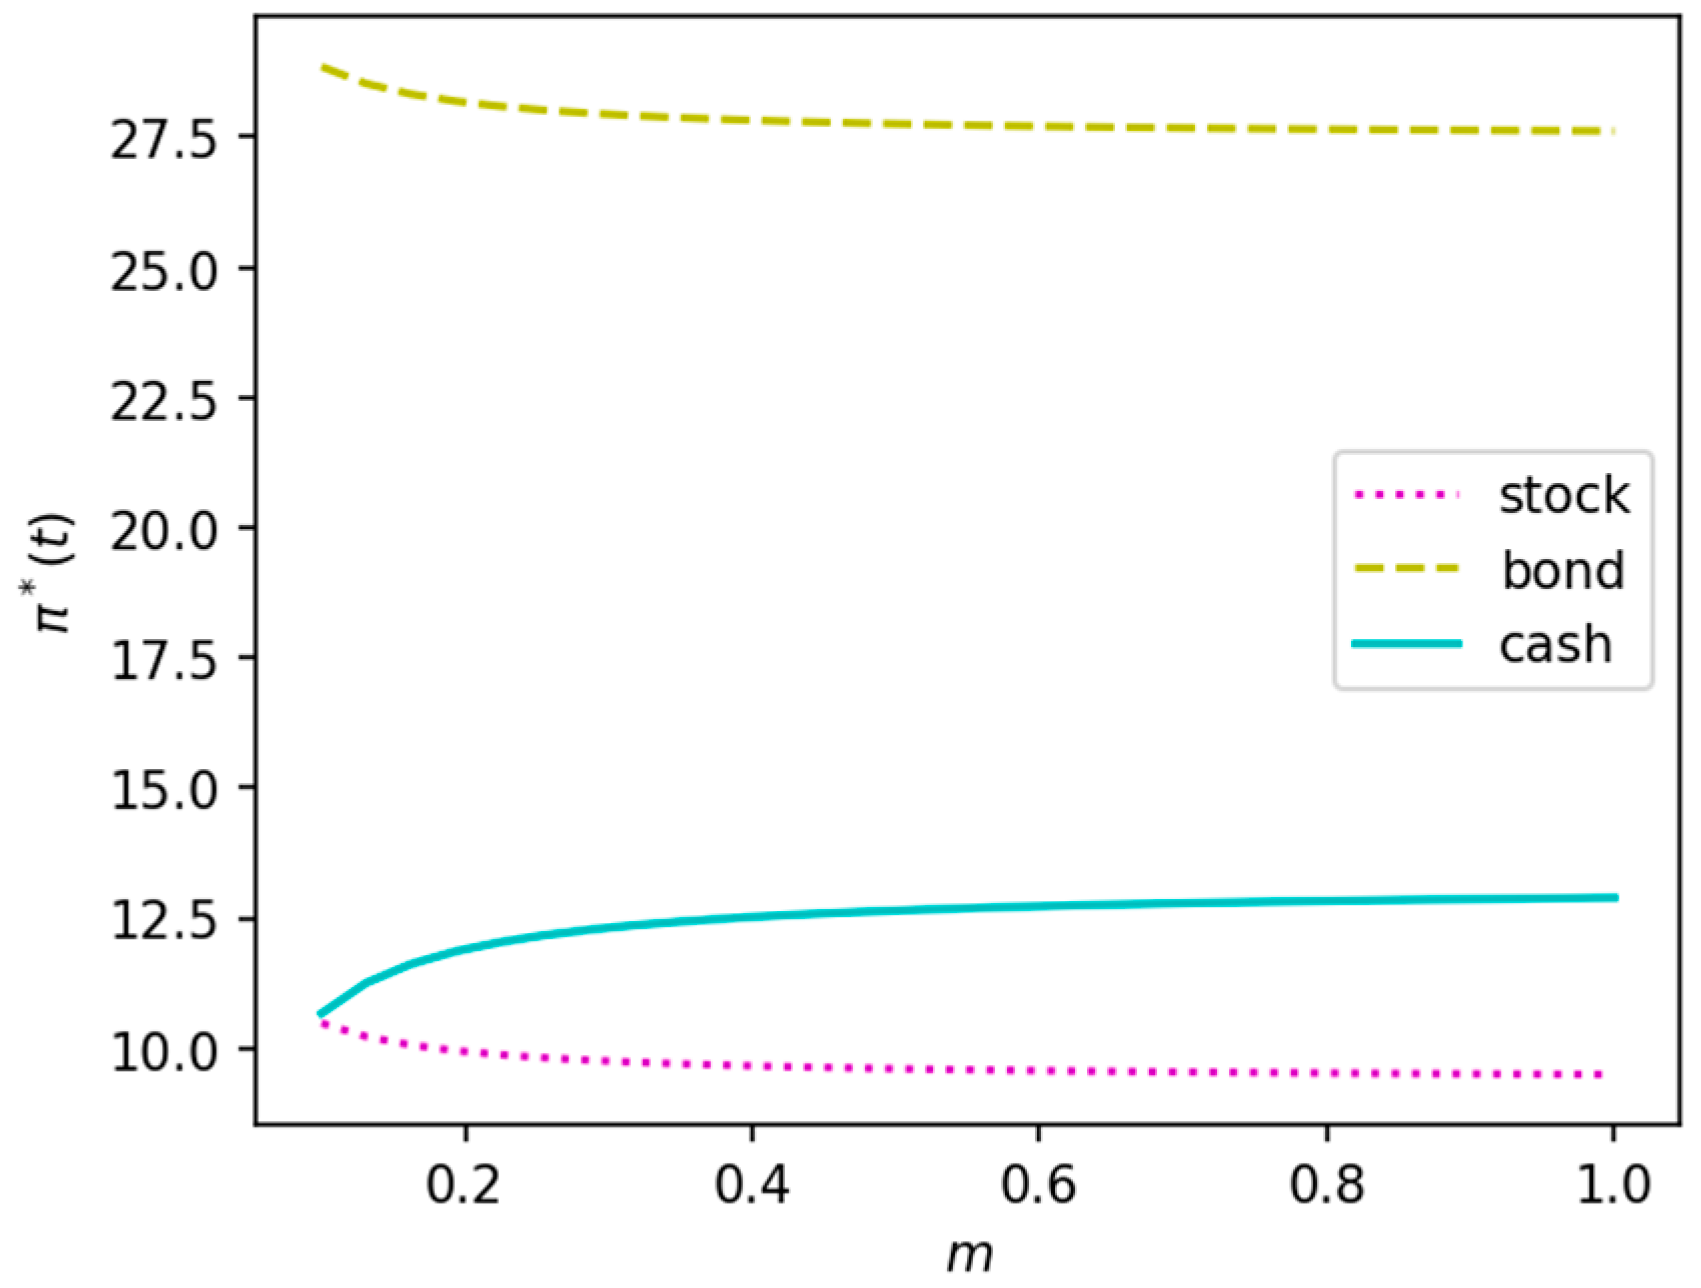
Figure 6 shows that the optimal investment strategies and are monotonically decreasing functions of the parameter, while is a monotonically increasing function concerning the parameter . The parameter M determines the volatility of random interest rates. When the volatility of interest rates increases, the uncertainty of risk assets will also improve, making insurance companies invest in risk assets more cautiously. Therefore, in such a situation, insurers may reduce their exposure to risky assets while increasing their exposure to zero-coupon bonds for a more stable return. In addition, since risk-free assets are usually related to interest rates, in the event of increased interest rate volatility, insurance companies may reduce their investment in risk-free assets to avoid the disproportionate impact of interest rate fluctuations on their investments.
Figure 6.
The influence of parameter on the optimal investment strategy.
Figure 7 shows that as the parameter increases, investment in risk-free assets decreases, investment in zero-coupon bonds goes up, and investment in risky assets changes by a small amount. As the parameter increases, the market price of random interest rates grows, increasing the uncertainty in future interest rate changes and, in turn, may result in insurance companies reducing their investments in risk-free assets due to the fixed return on such assets yielding lower returns compared to other options when market interest rates rise. Conversely, investments in zero-coupon bonds may increase as they can offer higher returns and serve as a hedge against rising interest rates. Investments in risky assets may change less as insurers strive to achieve higher returns by investing in risky assets to compensate for the reduced returns on risk-free assets and zero-coupon bonds. However, with the increase in stochastic interest rates, the price volatility of risky assets may also increase, leading insurance companies to moderate their investments in risky assets.
Figure 7.
The influence of parameter on the optimal investment strategy.
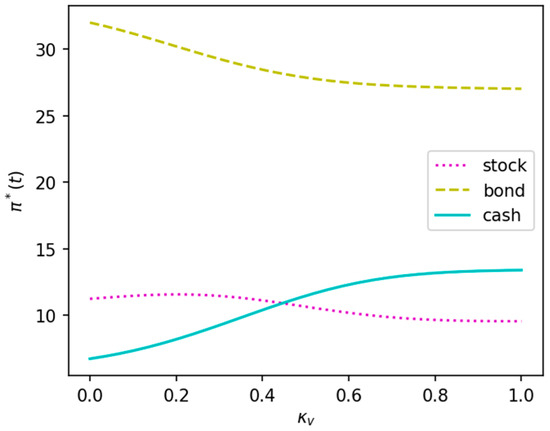
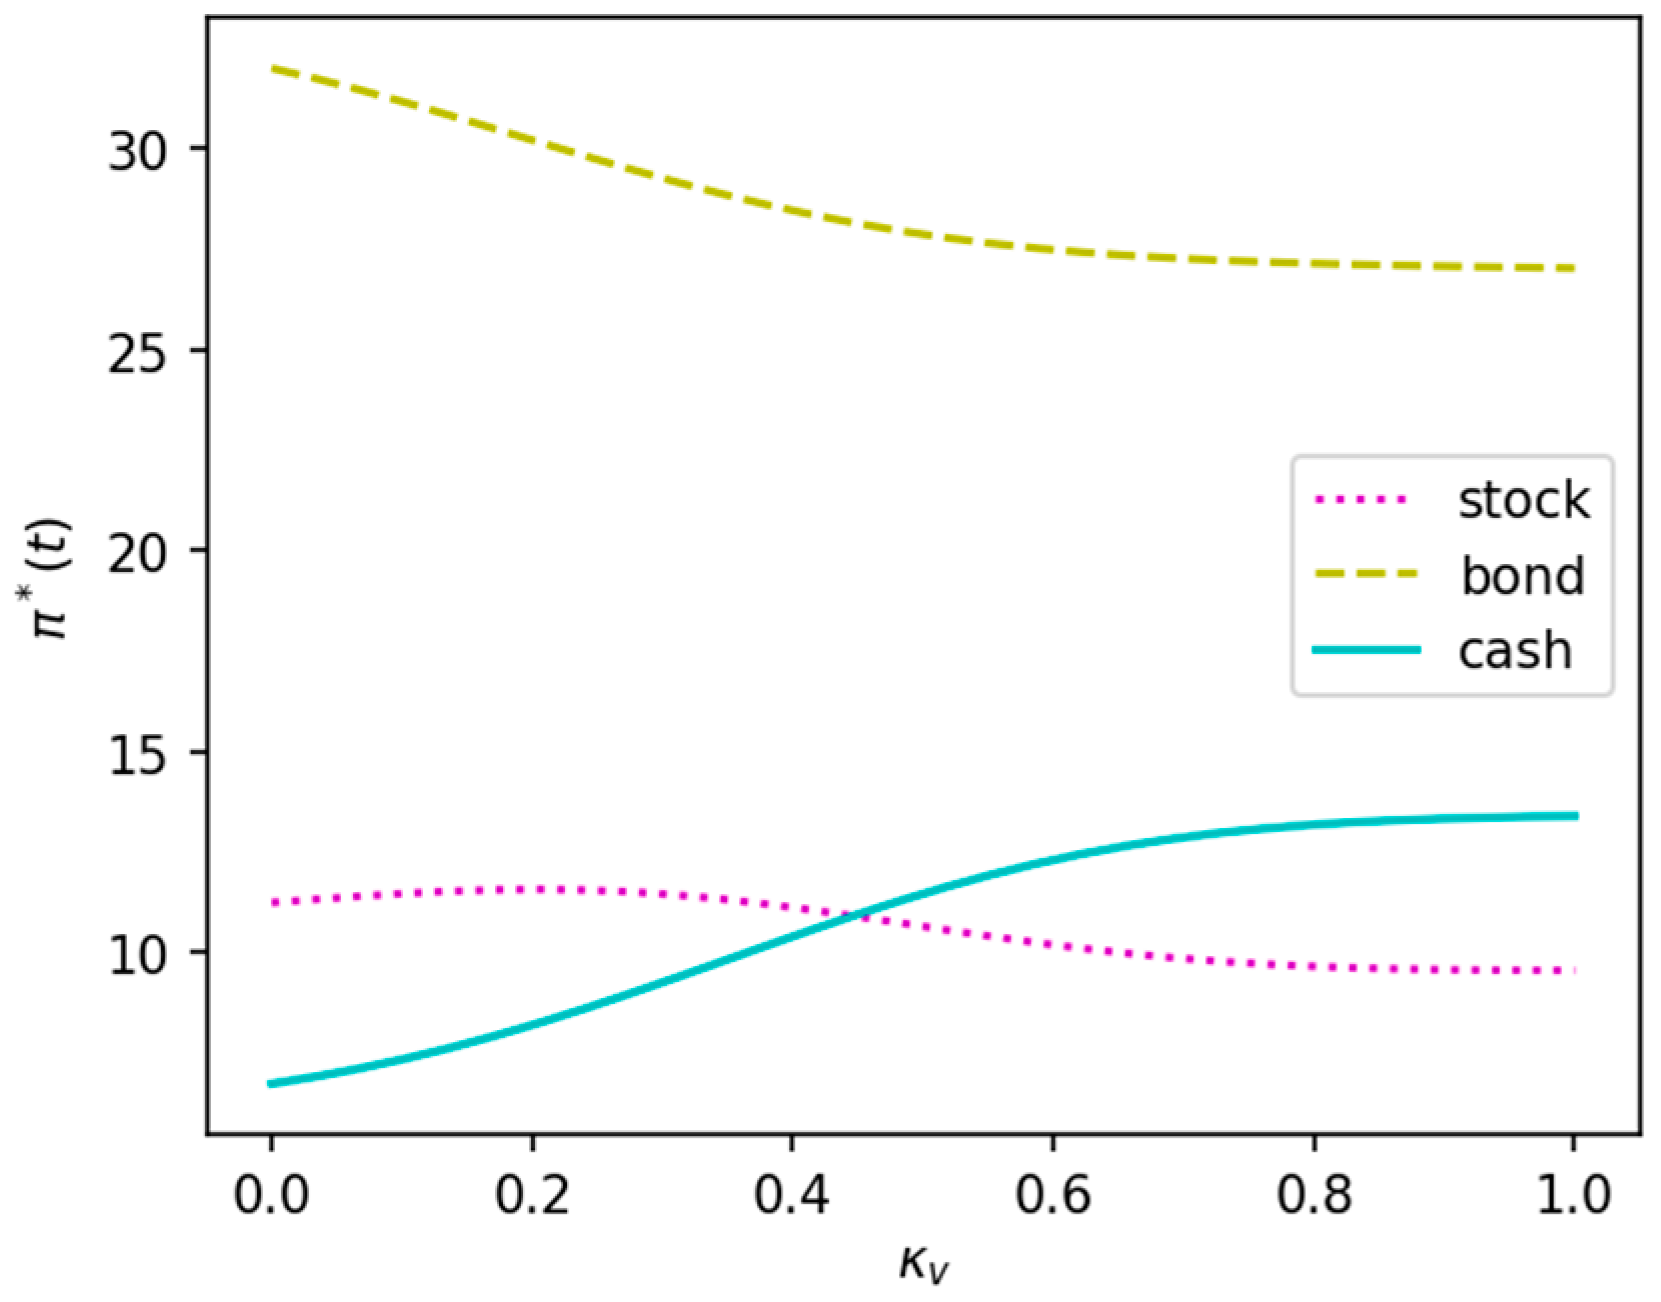
In Figure 8, the optimal strategy and zero-coupon bond decrease as the parameter increases, while increases. When the average regression speed of risky asset price volatility rises, risky asset price volatility will become more unstable, increasing the risk aversion of insurance companies and leading insurance companies to reduce their investment in risky assets. At the same time, since the price of zero-coupon bonds has an inverse relationship with interest rates, in the event of increased interest rate volatility, insurance companies may reduce their investment in zero-coupon bonds to avoid price falls and losses. On the contrary, risk-free assets like treasury bonds have a lower volatility and more stable returns. Therefore, when the average regression speed of risky asset price volatility goes up, insurance companies may increase investment in these assets.
Figure 8.
The influence of parameter on the optimal investment strategy.
Figure 9 indicates that the insurance company’s investment in risky assets and investment in risk-free assets increases as the parameter goes up. In contrast, its investment in zero-coupon bonds decreases as the parameter increases. The parameter characterizes the risk aversion factor in the HARA utility function, representing the absolute risk aversion coefficient (ASAC). That is, the larger the value of the parameter, the smaller the absolute risk aversion coefficient.
Figure 9.
The influence of parameter on the optimal investment strategy.
Figure 10 shows that investments in a risky asset and a zero-coupon bond decrease as the parameter increases. In contrast, investment in a risk-free asset grows as the parameter increases because as the parameter goes up, the ASAC also grows. Insurance companies become more risk-averse and invest more in risk-free assets and zero-coupon bonds, reducing investment in risky assets.
Figure 10.
The influence of parameter on the optimal investment strategy.
We can infer that when risk aversion increases, insurance companies are more inclined to take negligible risks, reducing their investment in risky assets to reduce the risk of their portfolios. In addition, insurers’ investments in zero-coupon bonds are usually a good match to their liabilities, thus ensuring sufficient cash flow to cover claims and interest expenses, even at lower yields. With less exposure to risky assets and zero-coupon bonds, insurers may increase exposure to risk-free assets to ensure portfolio liquidity and soundness.
5. Conclusions
In this work, we studied the optimal reinsurance–investment strategy of insurance companies under a stochastic interest rate and stochastic volatility model with the HARA utility function as the criterion. Reinsurance–investment strategies under stochastic volatility models have recently become a hot topic. Assuming that the surplus process of insurance companies obeys the Brownian motion with drift, insurance companies can invest in bank accounts and risky assets by purchasing proportional reinsurance or new business. This paper applied the CIR model to describe the stochastic interest rate, and the Heston model to describe the price process of risky assets. The Legendre transformation and pairwise theory solve the corresponding HJB equations to obtain the analytical expressions for the insurance company’s optimal reinsurance–investment strategy and value function. Later, we investigated some sensitivities of the optimal investment strategy. Our results from the numerical example are as follows: the parameters of the financial market in the stochastic interest rate model have an essential impact on the optimal reinsurance strategy; investing in non-performing risky assets with high volatility and low appreciation rates increases the overall risk.
The main contributions of our model are as follows: (1) The risk model considers both insurance and investment risks, and reinsurance is an effective risk management method. (2) We added the random fluctuations of risky and risk-free assets. The premium calculation adopts the variance premium principle, so the random investment of insurance companies is closer to the real financial market than the general geometric model. (3) This work assumes the HARA utility function as the optimal criterion, which has a more general mathematical structure and a broader application.
The modeling framework in this paper is worth extending to other optimal control problems in insurance, such as asset–liability management, optimal pension funds, and optimal life insurance purchases. Further discussions on the reinsurance–investment problem of insurance companies could be made, such as studying the optimal reinsurance–investment problem of investing in multiple risk assets and solving the optimal control problem under different constraints.
Author Contributions
Conceptualization, H.B. and Q.W.; methodology, Y.W.; software, W.W.; validation, H.B. and Y.W.; formal analysis, Q.W. and Y.W.; investigation, W.W.; writing—original draft preparation, Y.W. and Q.W.; writing—review and editing, W.W. and R.M.; visualization, Q.W.; supervision, R.M.; project administration, H.B.; funding acquisition, H.B. All authors have read and agreed to the published version of the manuscript.
Funding
This study has been partly supported by the Scientific Research Funding Project of the Liaoning Province Department of Education (LJKZ0066), the Natural Science Foundation of Liaoning Province (2021-BS-076), the List of Key Science and Technology Projects in Transportation Industry of Ministry of Transport (2022-MS3-102), the Dalian Maritime University Think Tank Special Project (3132023721), the Humanities and Social Science Research General Program of Chinese Ministry of Education (22YJC910011), and the China Postdoctoral Science Foundation Funded Project (2023M733444).
Data Availability Statement
Not applicable.
Conflicts of Interest
The authors declare no conflict of interest.
Appendix A
Proof of Theorem 2.1.
According to the standard stochastic optimal control theory, the HJB equation is satisfied by the value function :
Assume that is a solution to the HJB Equation (A1); according to the first-order condition for extremes, look for the derivatives of the HJB equation in Equation (A1) , and ; and let the derivatives be zero. Then, the optimal solution can be found as follows:
Combining (A2), (A3), and (A4) into the HJB equation, gives
Equation (A5) is a second-order nonlinear partial differential equation and the form of the solution to Equation (A5) cannot be directly guessed due to the complexity of the HARA utility function and its boundary conditions.
We apply the methods and techniques of the Legendre transformation and pairwise theory to transform Equation (A5) into a second-order linear partial differential equation and ultimately find its shown solution.
Definition A1.
Let be a convex function for . Define the Legendre transformation of as follows:
which is called the Legendre dual function of function .
If is a strictly convex function, then there is a unique maximum point in (A6) and its maximum value is marked as , according to the first-order condition
where the unique solution can be obtained as follows:
According to Gao [38], with the definitions of (A6) and the convexity of the value function , the Legendre transformation is defined as follows:
Upon denoting as the optimal value of the variable and , we assume that satisfies the following equation:
where we then obtain the relation between and
Therefore and are both pairwise functions of the value function . In solving the optimal reinsurance strategy, the function is more straightforward to calculate numerically, so the function is chosen for the study. Further calculation gives
For Equation (A11), calculating the partial derivatives of each other with respect to gives
Then, at the terminal moment , define
where we then have
where is the inverse of marginal utility.
Substituting (A12) into (A5) with respect to the value function gives the dyadic function :
and further simplification gives
Differentiating on both sides of Equation (A13) simultaneously yields
Combining Equation (21) yields a linear differential equation for the dyadic function :
The quadratic nonlinear partial differential Equation (21) is transformed into a second-order linear partial differential Equation (A14) utilizing the Legendre transform and the pairwise theory.
By solving Equation (A14), we can obtain the optimal reinsurance–investment strategy for the insurance company. Using the HARA utility as a criterion and using the boundary conditions yields
Based on the idea of equality, it can be conjectured that the solution of Equation (A14) has the following structure:
where the boundary conditions are , , .
Calculating the partial derivative for Equation (A16) gives
Substituting Equations (A16) and (A17) into Equation (A14) and simplifying gives
By eliminating the dependence on and in (A18), Equation (A18) can be divided into three parts concerning , , and , where we let each be equal to zero and obtain the following three equations:
Equations (A19)–(A21) will be separately solved below.
Firstly, for the differential Equation (A19), assume that the solution has the following structure
where the boundary condition is .
Taking the higher-order partial derivatives of each end of Equation (A22) for , , and yields
Substituting the above partial derivative result (A23) into Equation (A19) gives
Eliminating the dependence on and in the above equation gives the following three differential equations:
Equations (A25) and (A26) are equations and , respectively, that can be solved directly, while Equation (A24) is the equation on , and . So, we can solve , and as follows:
Since Equation (A25) is a Riccati equation, first find the quadratic equation in Equation (A25) for as follows:
To simplify our calculation later, we can state that
and the discriminant can be obtained as follows:
Suppose that ; then, Equation (A29) has two distinct roots at this point, denoted as and and
Then, Equation (A25) can be written in the following form:
Separating the variables in the above equation and integrating both sides at the same time gives
Integrating the two ends of Equation (A25) gives
The procedure for solving Equation (A25) is similar to that described above. Finding Equation (A25) about of the quadratic equation is as follows:
Again, for simplifying purposes, we can have
then, the discriminant becomes
Suppose that ; then, the equation has two distinct roots at this point, denoted as and respectively, and
Then, Equation (A26) can be noted in the following form:
Separating the variables in this equation and integrating both sides at the same time gives
Solving this integral equation yields
To solve , note Equation (A24) in the following form:
Integrating both ends of the above equation from to , solves the differential equation and gives :
At this point, we have obtained the expression in Equation (A37) as
where the solutions of , and are given using (A31), (A36), and (A37), respectively.
Then, we solve Equation (A20), assuming that the solutions have the following structure, where
and taking the high-order partial derivatives of each end of Equation (A38) with respect to , , gives the following:
Substituting the partial derivative results into Equation (A20) and simplifying gives
Eliminating the dependence on and in the above equation, we obtained the following three differential equations:
where the boundary condition is .
First, we solve . Equation (A42) is a simple first-order linear differential equation, the solution of which can be obtained as follows:
Second, we solve Equation (A43), which is a Riccati equation. We first solve the quadratic equation in (A43) with respect to :
For simplification of subsequent calculations, we note
and the discriminant is obtained as
where its two dissimilar roots are as follows:
Then, Equation (A43) can be written in the following form:
Separating the variables in the above equation and integrating both sides at the same time gives the following:
Solving this integral equation yields , as follows:
Finally, to calculate , integrate both ends of Equation (A41):
At this point, we obtain the formulation in Equation (A38) as
where the solutions of , and are given using Equations (A44), (A47) and (A48), respectively.
Then, we solve Equation (A21), introducing the following variational operator for the arbitrary function :
Then, the differential Equation (A21) can be rewritten as follows:
On the other hand, the calculation leads to the following:
Substituting the above equation into Equation (A50) and simplifying it gives
and meets the following partial differential equation:
In summary, we solve for :
On the other hand, considering and Equation (A16) leads to the following:
Since , the optimal solution of the HJB Equation (A1) is obtained via integration, as follows:
In summary, we can obtain the optimal reinsurance–investment strategy under the HARA utility function. The proof is completed.
References
- Święch, A. Another Approach to the Existence of Value Functions of Stochastic Differential Games. J. Math. Anal. Appl. 1996, 204, 884–897. [Google Scholar] [CrossRef]
- Soner, H.M.; Touzi, N. Stochastic Target Problems, Dynamic Programming, and Viscosity Solutions. SIAM J. Control Optim. 2002, 41, 404–424. [Google Scholar] [CrossRef]
- Rami, M.A.; Moore, J.B.; Zhou, X.Y. Indefinite Stochastic Linear Quadratic Control and Generalized Differential Riccati Equation. SIAM J. Control Optim. Soc. Ind. Appl. Math. 2002, 40, 1296–1311. [Google Scholar] [CrossRef]
- Zhu, J.; Li, S. Time-Consistent Investment and Reinsurance Strategies for Mean-Variance Insurers under Stochastic Interest Rate and Stochastic Volatility. Mathematics 2020, 8, 2183. [Google Scholar] [CrossRef]
- Ali, I.; Khan, S.U. A Dynamic Competition Analysis of Stochastic Fractional Differential Equation Arising in Finance via Pseudospectral Method. Mathematics 2023, 11, 1328. [Google Scholar] [CrossRef]
- Browne, S. Optimal Investment Policies for a Firm With a Random Risk Process: Exponential Utility and Minimizing the Probability of Ruin. Math. Oper. Res. 1995, 20, 937–958. [Google Scholar] [CrossRef]
- Yang, H.; Zhang, L. Optimal investment for insurer with jump-diffusion risk process. Insur. Math. Econ. 2005, 37, 615–634. [Google Scholar] [CrossRef]
- Hipp, C.; Plum, M. Optimal investment for insurers. Insur. Math. Econ. 2000, 27, 215–228. [Google Scholar] [CrossRef]
- David, P.S.; Young, V.R. Minimizing the Probability of Ruin When Claims Follow Brownian Motion with Drift. N. Am. Actuar. J. 2005, 9, 110–128. [Google Scholar] [CrossRef]
- Bai, L.; Zhang, H. Dynamic mean-variance problem with constrained risk control for the insurers. Math. Methods Oper. Res. 2008, 68, 181–205. [Google Scholar] [CrossRef]
- Ramadan, A.T.; Tolba, A.H.; El-Desouky, B.S. A Unit Half-Logistic Geometric Distribution and Its Application in Insurance. Axioms 2022, 11, 676. [Google Scholar] [CrossRef]
- Georgescu, I.; Kinnunen, J. Optimal Saving by Expected Utility Operators. Axioms 2020, 9, 17. [Google Scholar] [CrossRef]
- Jung, E.J.; Kim, J.H. Optimal investment strategies for the HARA utility under the constant elasticity of variance model. Insur. Math. Econ. 2012, 51, 667–673. [Google Scholar] [CrossRef]
- Chang, H.; Chang, K. Optimal consumption–investment strategy under the Vasicek model: HARA utility and Legendre transform. Insur. Math. Econ. 2017, 72, 215–227. [Google Scholar] [CrossRef]
- Zhang, Y.; Zhao, P. Optimal Reinsurance-Investment Problem with Dependent Risks Based on Legendre Transform. J. Ind. Manag. Optim. 2020, 16, 1457–1479. [Google Scholar] [CrossRef]
- Zhang, Y. Optimal Investment Strategies for Asset-Liability Management with Affine Diffusion Factor Processes and Hara Preferences. J. Ind. Manag. Optim. 2023, 19, 5767–5796. [Google Scholar] [CrossRef]
- Cox, J.C. Notes on Option Pricing I: Constant Elasticity of Variance Diffusion. Unpublished Note, Standford University, Graduate School of Business. 1975.
- Stein, E.M.; Stein, J.C. Stock Price Distributions with Stochastic Volatility: An Analytic Approach. Rev. Financ. Stud. 1991, 4, 727–752. [Google Scholar] [CrossRef]
- Heston, S.L. A Closed-Form Solution for Options with Stochastic Volatility with Applications to Bond and Currency Options. Rev. Financ. Stud. 1993, 6, 327–343. [Google Scholar] [CrossRef]
- Gu, A.; Guo, X.; Li, Z.; Zeng, Y. Optimal control of excess-of-loss reinsurance and investment for insurers under a CEV model. Insur. Math. Econ. 2012, 51, 674–684. [Google Scholar] [CrossRef]
- Wang, S.; Rong, X.; Zhao, H. Optimal time-consistent reinsurance-investment strategy with delay for an insurer under a defaultable market. J. Math. Anal. Appl. 2019, 474, 1267–1288. [Google Scholar] [CrossRef]
- Huang, Y.; Yang, X.; Zhou, J. Robust optimal investment and reinsurance problem for a general insurance company under Heston model. Math. Methods Oper. Res. 2017, 85, 305–326. [Google Scholar] [CrossRef]
- Zhu, H.; Cao, M.; Zhang, C. Time-consistent investment and reinsurance strategies for mean-variance insurers with relative performance concerns under the Heston model. Financ. Res. Lett. 2019, 30, 280–291. [Google Scholar] [CrossRef]
- Zhang, Y.; Zhao, P.; Kou, B. Optimal excess-of-loss reinsurance and investment problem with thinning dependent risks under Heston model. J. Comput. Appl. Math. 2021, 382, 113082. [Google Scholar] [CrossRef]
- Yan, T.; Wong, H. Open-loop equilibrium reinsurance-investment strategy under mean–variance criterion with stochastic volatility. Insur. Math. Econ. 2020, 90, 105–119. [Google Scholar] [CrossRef]
- Sheng, D. Explicit Solution of Reinsurance-Investment Problem for an Insurer with Dynamic Income under Vasicek Model. Adv. Math. Phys. 2016, 2016, 1967872. [Google Scholar] [CrossRef]
- Zhang, X.; Zheng, X. Optimal Investment-Reinsurance Policy with Stochastic Interest and Inflation Rates. Math. Probl. Eng. 2019, 2019, 5176172. [Google Scholar] [CrossRef]
- Yuan, Y.; Mi, H.; Chen, H. Mean-variance problem for an insurer with dependent risks and stochastic interest rate in a jump-diffusion market. Optimization 2022, 71, 2789–2818. [Google Scholar] [CrossRef]
- Guo, C.; Zhuo, X.; Constantinescu, C.; Pamen, O.M. Optimal Reinsurance-Investment Strategy Under Risks of Interest Rate, Exchange Rate and Inflation. Methodol. Comput. Appl. Probab. 2018, 20, 1477–1502. [Google Scholar] [CrossRef]
- Sun, Z.; Guo, J. Optimal mean–variance investment and reinsurance problem for an insurer with stochastic volatility. Math. Methods Oper. Res. 2018, 88, 59–79. [Google Scholar] [CrossRef]
- Wang, H.; Wang, R.; Wei, J. Time-consistent investment-proportional reinsurance strategy with random coefficients for mean–variance insurers. Insur. Math. Econ. 2019, 85, 104–114. [Google Scholar] [CrossRef]
- Guan, G.; Liang, Z. Robust optimal reinsurance and investment strategies for an AAI with multiple risks. Insur. Math. Econ. 2019, 89, 63–78. [Google Scholar] [CrossRef]
- Zhang, Y.; Wu, Y.; Wiwatanapataphee, B.; Angkola, F. Asset liability management for an ordinary insurance system with proportional reinsurance in a CIR stochastic interest rate and Heston stochastic volatility framework. J. Ind. Manag. Optim. 2020, 16, 71–101. [Google Scholar] [CrossRef]
- Grandell, J. Aspects of Risk Theory; Springer: New York, NY, USA, 1991. [Google Scholar]
- Yong, J.; Zhou, X.Y. Stochastic Controls: Hamiltonian Systems and HJB Equations; Springer: New York, NY, USA, 1999; pp. 241–246. [Google Scholar]
- Deelstra, G.; Grasselli, M.; Koehl, P.-F. Optimal investment strategies in the presence of a minimum guarantee. Insur. Math. Econ. 2003, 33, 189–207. [Google Scholar] [CrossRef]
- Guan, G.; Liang, Z. Optimal management of DC pension plan in a stochastic interest rate and stochastic volatility framework. Insur. Math. Econ. 2014, 57, 58–66. [Google Scholar] [CrossRef]
- Gao, J. Stochastic optimal control of DC pension funds. Insur. Math. Econ. 2008, 42, 1159–1164. [Google Scholar] [CrossRef]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2023 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).