Review

What Is the Right Price for Non-Fungible Tokens (NFTs)? A Systematic Review of the Current Literature

by
Marta Flamini
1,† and
Maurizio Naldi
2,*,†
1
Department of Engineering, International Telematic University UNINETTUNO, 00186 Roma, Italy
2
Department of Law, Economics, Politics and Modern Languages, LUMSA University, 00193 Roma, Italy
*
Author to whom correspondence should be addressed.
These authors contributed equally to this work.
FinTech 2025, 4(4), 73; https://doi.org/10.3390/fintech4040073
Submission received: 23 October 2025 / Revised: 30 November 2025 / Accepted: 8 December 2025 / Published: 11 December 2025

Abstract

Non-Fungible Tokens (NFTs) have transformed digital ownership, offering unique representations of assets such as art, collectibles, and virtual property. However, pricing NFTs remains a complex and underexplored issue. This study addresses two core questions: what determines NFT prices? And how are prices set in NFT markets? We conduct a comprehensive literature review and market analysis to identify both endogenous and exogenous price determinants. Trait rarity emerges as the most influential intrinsic factor, while cryptocurrency value stands out as a major external influence, albeit with ambiguous effects. Other factors include visual aesthetics, scarcity, utility in games, social media engagement, and broader market sentiment. As to pricing mechanisms, aside from fixed pricing (which is accepted in all marketplaces), NFT marketplaces primarily utilise auctions for art pieces and collectibles— especially English and Dutch formats—which are effective at capturing the buyer’s willingness-to-pay.
JEL Classification:
G12; G10; D44; L86; O33

1. Introduction

Non-Fungible Tokens (NFTs) have emerged as a transformative innovation in the digital economy, redefining how digital assets are created, owned, and traded, as described by [1]. Unlike cryptocurrencies such as Bitcoin or Ethereum, which are interchangeable and identical in value, NFTs are unique and indivisible, making them ideal for representing digital ownership of art, collectibles, music, virtual real estate, and even gaming items, as highlighted by [2]. Built primarily on blockchain technology, NFTs ensure authenticity, provenance, and scarcity, addressing long-standing challenges in digital ownership and intellectual property.
The rise of NFTs has been fuelled by their ability to empower artists and creators, offering them direct access to global markets without relying on traditional intermediaries. This has revolutionised industries like digital art, where creators can tokenise their work, sell it on NFT marketplaces, and earn royalties through smart contracts. Some descriptive data concerning the size of market participants and prices of NFTs in several categories are reported in [3]. Also, NFTs have been proposed as an alternative investment option and a mitigating strategy against fluctuations in the Bitcoin and gold markets [4].
However, the NFT space also faces challenges, including concerns about environmental impact, speculative bubbles, and copyright issues (see, e.g., the comments on jurisdiction by [5]). Some word of caution for creative industrial entrepreneurs has been spread by [6], who compared this market with Initial Coin Offerings. Also, ref. [7] purported that crypto-art is unrelated to real-world art: crypto-art prices are mostly determined by gains in the cryptocurrency of denomination, whereas real-world art is mostly unrelated to the financial markets. According to them, crypto-art is far from being another medium to express artistic content and is currently just a storage unit for crypto-money, in the absence of relevant alternatives.
The success of NFTs has been investigated by looking into the reason for the hype and its future, as highlighted by [8]. Excesses are clearly visible in some extremely high-priced sales, which raises some issues about their nature. Prices have also been shown to exhibit a multi-fractal nature by [9], who examined four NFTs (namely, Cryptokitties, Cryptopunks, SuperRare, and Decentraland) using daily price data encompassing the COVID period. The issue of value remains a critical one, and it may be a reason for a potential fall of the market, as argued even in NFT-supporting circles (see the webpage https://dappgambl.com/nfts/dead-nfts/ (accessed on 1 December 2025)). Are they commodities or pieces of art? What actually drives their price? Those questions are relevant to understanding how NFT markets should be organised and how prospective traders should approach those markets. We can formulate two major research questions (RQs):
  • RQ1 What are the determinants of NFT prices?
  • RQ2 How are prices to be set in NFT markets?
In this paper, we try to answer those questions by reviewing both the literature and the current practices in NFT markets. Our major findings are the following, with findings 1 through 3 being related to RQ1, and findings 4 and 5 being related to RQ2:
  • Trait rarity stands out as the most relevant endogenous factor;
  • The value of cryptocurrencies is the major exogenous factor under investigation, but no specific direction of influence is identified;
  • Both endogenous and exogenous factors influence prices;
  • Both auctions and fixed-price are allowed in most marketplaces;
  • However, auctions appear as the major price-setting mechanism, which allows for extracting as much value as possible from the willingness-to-pay of prospective buyers.
Our paper is organised as follows. We first provide some information about NFTs and describe the most important marketplaces where NFTs are traded (Section 2 and Section 4). The core analyses about market determinants and pricing mechanisms are carried out in Section 5 and Section 6, respectively.

2. Background Information

Non-Fungible Tokens

Non-fungible tokens (NFTs) are unique digital assets that represent ownership or proof of authenticity for a specific item or piece of content, typically using blockchain technology. Unlike cryptocurrencies like Bitcoin or Ethereum, which are fungible (meaning each unit is interchangeable and has the same value), NFTs are non-fungible, meaning each one is unique and cannot be exchanged on a one-to-one basis with another. Their uniqueness makes them a natural conveyor of art pieces, though the range of works sold through NFTs is much wider, as we shall see in Section 3.1.
Blockchain technology is employed to secure the digital property certificate. However, only blockchains that support smart contracts can be used. Blockchains maintain a permanent and tamper-proof record of transactional data, realising a distributed ledger. For that purpose, they rely on a peer-to-peer network, where each node in the network maintains a copy of the ledger, which provides significant robustness against failures, since there is not a single point of failure. Typically, the blockchain of choice is Ethereum. The first implementations of NFTs were based on the Ethereum Improvement Proposals EIP-721 (Ethereum Improvement Proposals describe the standards for the Ethereum platform) [10]. However, alternatives such as Solana [11] and Polygon [12] have recently appeared. A review of NFTs’ features has been proposed by [13]. Also, ref. [14] have synthesised the suite of NFT standards, examining NFT challenges such as usability, privacy, security, sustainability, and intellectual property.
The history of NFTs is relatively recent but has evolved rapidly over the past decade. Hereafter, we describe the main steps, but [15] have narrated a more detailed history. See also the brief history earlier reported by [16].
The precursors of NFTs can be traced back to the years 2012–2013, when some projects were launched to exploit blockchain technology, made popular by the advent of Bitcoin, to manage real-world assets. A notable example was Colored Coins, described by [17]. Also, the Counterparty platform was built on top of the Bitcoin blockchain. It allowed for the creation of assets, and some of the earliest experiments with NFTs occurred here, e.g., with the Rare Pepes project, which was a collection of meme trading cards (see the description of the Counterparty platform at https://www.counterparty.io/platform (accessed on 1 December 2025)).
The first true NFT appeared in 2014, created by digital artist Kevin McCoy and named Quantum, where a link pointing to a digital art file was recorded permanently on a blockchain, as described by [18] himself.
The boom of NFTs can be located in 2017, with the massive use of Ethereum and the launch of CryptoPunks (by Larva Labs), which offered 10,000 unique collectable characters (see the collection at https://cryptopunks.app (accessed on 1 December 2025)), and CryptoKitties (by Dapper Labs), which allowed users to breed and trade digital cats, each represented as a unique NFT (the catalogue can be explored at https://www.cryptokitties.co/catalogue (accessed on 1 December 2025)). The value of Cryptopunks as an alternative form of investment was also analysed by [19]. The boom continued in 2018–2019, which saw the emergence of marketplaces where NFTs could be easily traded. Platforms like OpenSea, Rarible, and SuperRare helped grow the NFT ecosystem by making it easier for creators to mint and sell their work. This period also marked the extension of NFTs beyond just gaming and collectibles, with artists and creators entering the space and using NFTs for digital art, music, and other forms of media.
The years 2020–2021 saw mainstream adoption of NFTs, with record sales and celebrities, brands, and major companies beginning to create and invest in NFTs, further pushing them into the mainstream. Musicians, athletes, and artists used NFTs to monetise their work and engage with fans in new ways. Also, NFTs gained wide resonance on social media sites like Twitter, with NFT projects being mentioned in tweets and used as profile picture images, as investigated by [20].
We are currently in a phase of consolidation and innovation [21]. New use cases have emerged in areas like virtual real estate (with the notable example of Decentraland, described in Section 4.2, whose financial and legal implications have been investigated by [22]), decentralised finance (DeFi), explored by [23], and identity verification.

3. Method

As hinted in the introduction, we have conducted a systematic literature review to answer our RQs. We have adopted the well-known PRISMA approach in its 2020 version [24].
Our literature search has been carried out without limitations on the year of publication, including only fully published sources (i.e., excluding those made of the abstract alone). We have limited our search to English publications, since English represents the dominant language in the technical literature and considering papers in other languages would have compelled us to properly define the terminology used in that language to describe readiness/maturity models, let alone the difficulty of reading other languages. Our bibliographic database of choice was Scopus. This database still represents the major reference for bibliographic analyses, in particular for the fields of Natural Science, Engineering, and Finance [25], which is where the theme of NFT lies.
We have employed the query (NFT AND (market OR pricing OR valuation)), applying it to the title, the abstract, and the keywords. All the papers in the query’s outcome have been independently examined by two researchers (the authors of the paper). The results of the preliminary screening (the last query was carried out in May 2025) are shown in Figure 1. No duplicates were found, as all the records come from the same bibliographic repository. A large fraction of the paper collected under the query described above was excluded (82.2%), as most mentioned pricing or valuation as a passing reference but did not actually include any specific analysis of pricing determinants. In most cases, the inclusion was due to the presence of the word market in the abstracts. The word pricing was included in the abstract of just 26 papers, while the word valuation (or its form evaluation, which was also included in the query) was observed in 32 abstracts. This effect was largely expected as a consequence of our query being extremely inclusive.
In order to assess the quality of our systematic search, we have made our search compliant with all the PRISMA-2020 checklist items that are applicable, though the PRISMA 2020 paradigm mainly applies to the systematic reviews of studies that evaluate the effects of health interventions (see the statement on https://prisma.shinyapps.io/checklist/ (accessed on 1 December 2025).
In particular, we have employed the Risk-of-Bias (RoB) model to carry out the critical appraisal of our analysis, though it is intended mostly for primary studies, particularly within medical and biomedical research. Although our review focuses on Non-Fungible Tokens (NFTs), a field outside the typical scope of RoB, we have adapted its fundamental principles to frame our critical analysis of the included papers. This approach is complicated by the inherent heterogeneity of the literature, where results from different papers are often not directly comparable due to the use of highly diverse metrics and analytical frameworks.
Here is the list of the main RoB checklist items and a corresponding commentary for each:
  • Objective and Criteria (PICO/RQ): Two clear RQs were formulated: “RQ1 What are the determinants of NFT prices?” and “RQ2 How are prices to be set in NFT markets?”
  • Protocol: The previous registration of a review protocol is a critical step in medical and clinical research to ensure transparency and prevent post hoc decisions. We consider this criterion Not Applicable to our research.
  • Search Strategy (Comprehensiveness): Although restricting the search to a single database like Scopus is conventionally viewed as a limitation in systematic reviews, we suggest that this assessment requires nuance within this specific field. Scopus is acknowledged as one of the largest and most widespread scientific research databases globally, offering extensive coverage across academic disciplines, including those relevant to NFT research (e.g., computer science, finance). Given that the primary alternative, Web of Science (WoS), shares a considerable overlap in indexed content with Scopus, the decision to rely solely on Scopus may mitigate, though not eliminate, the risk of missing critical high-impact publications.
  • Study Screening and Selection: The authors state that both contributors defined the independent set of articles on which the review was based. This strongly suggests that the initial study selection and screening (identifying and choosing the relevant papers from the search results) was performed independently and in duplicate, which is the required standard to minimise human error and selection bias.
  • Exclusion List: The exclusion criteria have been described in the section dedicated to the method.
  • Risk-of-Bias Assessment of Included Studies: The authors did not apply a formal quality assessment (Risk-of-Bias assessment) to the included primary papers. This is likely due to the highly heterogeneous nature of the reviewed literature. The included papers employ a wide array of completely different models and metrics—ranging from econometric and time-series analysis to machine learning and network modelling—to address the research questions.

3.1. What Is for Sale?

While most of the hype has been surrounding art objects, not all non-fungible tokens belong in that class. In this section, we review the different types of objects for sale as NFTs.
In [26], six categories of assets have been identified: Art, Collectibles, Games, Metaverse, Other, and Utility. That classification has also been adopted by [8]. The meaning of the first four categories in that list is quite obvious. However, we need to define the last two categories more precisely. Utility NFTs are digital items that are associated with a real-world asset or right to use, obtain, or exchange, including domain names, tickets, or pieces of land. Of course, the Other category is a miscellaneous one, covering anything that does not fall into any of the other five categories. As major examples of collections falling into the Other category, ref. [26] mention Miscellanea, Kennbosakgif and, Budfarm.leaf.
The Art category dominated the market till the end of 2018, especially with the CryptoKitties collection. NFT collectibles have been defined as NFTs with financial and aesthetic value that are to be collected and typically come in the form of profile pictures and digital art [27]. A subcategory of collectibles is related to sports. Several sports organisations offer NFTs recording, e.g., sports moments and memories, digital sports trading cards, and wearable sports NFTs [28,29]. Examples of such organisations are the National Basketball Association (NBA) and the National Football League (NFL). In 2019, the Games and Metaverse categories entered the market, and from July 2020, the Collectible assets (such as cards) broke into the market as well. From 2020 to date, transactions associated with Games and Collectible assets NFTs are the most numerous ([26]). As an example of the Utility category, Decentraland is a virtual space stored in an Ethereum smart contract, where parcels of space are for sale [30]. Their first price refers to undeveloped space and is doomed to grow as the owner starts building amenities. The space has some structure in that special locations, named roads, plazas, and districts are pre-defined on the map.
An alternative, finer classification has been proposed by [31]. In addition to the categories already proposed by [26], those authors included Entertainment, Sports, Media, NFT for Good, Virtual Fashion, and Real-world assets. Entertainment refers to digital items concerning events in the digital world, where NFTs give the right to join an event, like an ordinary ticket. Sports NFTs focus on historical or memorable events and persons in the world of sport and e-sport, e.g., a short video about a single NBA game moment. The Media category includes digitised photos, music, pictures, and texts. The NFT for Good includes NFTs that are sold to help a person, non-profit organisations, or NGOs. The Virtual Fashion category includes those NFTs that play the same role as fashion goods in the real world but are for use on social networks and virtual worlds. Finally, the Real-world assets category includes NFTs minted to provide cryptographic proof of ownership, access, and further rights to a real asset (in this sense, they could also be ascribed under the Utility category).

3.2. Remarkable Pricing Events

A naive indicator of the ungrounded nature of NFT prices is the occurrence of incredibly high prices. The phenomenon is so remarkable as to deserve a host of websites reporting the most expensive purchases, e.g., https://www.coindesk.com/learn/the-top-10-most-expensive-nfts-of-all-time/ (accessed on 1 December 2025) or https://coinmarketcap.com/nft/ (accessed on 1 December 2025). In this section, we report some of the highest-priced events for NFTs, according to the Top 10 list of most expensive NFTs ever, curated by Coindesk. A similar list has also been published in [32].
Beeple’s collage Everydays: The First 5000 Days sold for $69 million at Christie’s in March 2021. His large fan base (roughly 2.5 million at that time) has been considered a major reason for his success (https://www.theverge.com/2021/3/11/22325054/beeple-christies-nft-sale-cost-everydays-69-million (accessed on 1 December 2025)). The NFT represents a collage of 5000 of Beeple’s earlier artworks, showing his development as an artist over the course of his career.
Clock is reported as being the second-most expensive single NFT ever sold. It was priced at $52.7 million in February 2022. The NFT shows a timer that counts the number of days Assange has spent in prison. It was created by the artist Pak, who has remained anonymous throughout their entire career, and was bought by AssangeDAO, an organisation supporting the WikiLeaks founder.
Another work by Beeple, Human One, was sold for $28.9 million in November 2021 (The story of the art piece is told in https://human-one.xyz (accessed on 1 December 2025)). It is a physical/digital hybrid piece, a sculpture whose sides incorporate digital screens. The sculpture itself shows a person wearing a spacesuit and walking in a continually changing environment. The NFT and the electronic sculpture were auctioned as a single lot. They were bought by Ryan Zurrer, formerly a venture partner at Polychain Capital.
A CryptoPunk NFT, namely punk #5822, was sold for $23 million in February 2022 (See the description of that item in https://cryptopunks.app/cryptopunks/details/5822?ref=bloom-where-you-spend (accessed on 1 December 2025)). It was bought by Deepak Thapliyal, the CEO of Chain (a blockchain company). Its high price is deemed to be related to its rarity, as it is one of only nine aliens in the CryptoPunk collection.
Next in this Top 10 list is the CryptoPunk #3100 (https://cryptopunks.app/cryptopunks/details/3100 (accessed on 1 December 2025)), which was sold for $7.57 million in 2021 but has recently been sold for $16 million in March 2024. It is one of nine aliens in existence, making it an influential and rare Punk.
Another item in the CryptoPunk collection, namely punk #7523, was sold for $11.7 million in June 2021 (see its description in https://cryptopunks.app/cryptopunks/details/7523 (accessed on 1 December 2025)). Again, it is an alien. Its rarity and the medical mask attribute in COVID times were considered determinants for its high prices. It was sold within Sotheby’s Natively Digital auction (https://www.sothebys.com/en/buy/auction/2021/natively-digital-cryptopunk-7523?locale=en (accessed on 1 December 2025)). It was bought by Shalom Meckenzie, the largest shareholder of DraftKings (a sports betting company).
A rare “Joker” Tpunk #3442 (https://tpunks.com/detail/Tpunks/3442 (accessed on 1 December 2025)) was sold for $10.5 million in August 2021. The TPunk collection is considered to be inspired by the CryptoPunks collection. It was bought by Justin Sun, the founder of TRON (a blockchain-based DAO, i.e., a decentralised autonomous organisation, managed by a decentralised computer programme).
Another NFT in the CryptoPunk collection (namely #4156 (see a description in https://cryptopunks.app/cryptopunks/details/4156 (accessed on 1 December 2025))) is the very next in the list, selling for $10.2 million in December 2021. It represents a bandana ape and is thought to be closely associated with prominent NFT influencer and builder Punk4156.
Next, we have again an item in the CryptoPunk collection, #5577 (see the description in https://cryptopunks.app/cryptopunks/details/5577 (accessed on 1 December 2025)), which sold for $7.7 million in February 2022. It is believed to have been bought by Robert Leshner, CEO of Compound Finance (Compound is a protocol for algorithmic, efficient money markets on the Ethereum blockchain). It represents an ape punk (a feature it shares with 24 others) with a cowboy hat (which is a feature of 142 items in that collection).
The last item in this Top 10 list is yet another CryptoPunk, #7804 (https://cryptopunks.app/cryptopunks/details/7804 (accessed on 1 December 2025)), which sold for $7.56 million in March 2021. Rarity is again considered a major determinant for its high price, as it is one of only nine aliens in existence.
As can be seen, most of the highly priced NFTs we have listed above belong to the CryptoPunk collection. Another common characteristic is that seven out of these Top 10 items were sold in 2021 and just three in 2022. The year 2021 was probably the most frenzied year for the sale NFTs. The Top 10 list of NFT sales in 2023 (https://nftplazas.com/top-nft-sales-2023/ (accessed on 1 December 2025)) shows prices below the current bottom item in the current Top 10. The record sale of CryptoPunk #3100 can be seen as a sign of the market resurgence, as remarked by [33].

3.3. Survey Literature

Despite the growing interest in NFTs, only a couple of attempts have been made to provide an overall view of the phenomenon.
We can mention the recent survey by [15], which provided a history of NFTs and a detailed explanation of two major standards (ERC-721 and ERC-1155) employed in NFT projects, highlighting some major challenges faced by NFT developers, namely their usability, the permanent storage of NFTs, the crypto gas war spurred in Ethereum, and the interoperability of NFTs. A bibliometric survey has instead been offered by [34] to identify the key research themes. The authors identified several key streams, including NFTs’ pricing strategies.
A review specifically concerned with pricing determinants has been carried out in [35]. They surveyed eight papers and classified them into five approaches (some approaches are represented by a single paper): hedonic regression models, repeat sales regression, vector autoregressive models, machine learning, and wavelets. We have included those papers in the wider panorama reported in Section 5, so we do not delve into further detail here.

4. NFT Marketplaces

Marketplaces for NFTs have developed rapidly in the last few years. In this section, we go through the major marketplaces.

4.1. OpenSea

OpenSea was founded in 2017. It supports sales of a wide variety of NFTs, from art to gaming to photographs, music, and profile pictures (PFPs). Until late 2023, OpenSea charged a 2.5% marketplace fee on secondary-market NFT sales; this fee was later removed, and transactions are now subject primarily to creator royalties and blockchain fees (see the webpages https://docs.opensea.io/docs/opensea-fees?utm_source=chatgpt.com (accessed on 1 December 2025) and https://nftnow.com/news/breaking-opensea-announces-major-changes-to-fees-and-creator-royalties/?utm_source=chatgpt.com (accessed on 1 December 2025)). Though boasting a large customer base, it looks like the market is dominated by a small number of players [36]. Also, some collections are extremely popular, and some traders specialise in these collections. The range of clearing prices is extremely large, from a few dollars to some million. Purchases occur either at a fixed price set by the seller (which is the default mode) or through a timed English auction (with the chance for the seller to set a reserve price).

4.2. Decentraland

Decentraland is a decentralised platform that is based solely on Ethereum. It is not simply a marketplace where you can buy or sell NFTs. It is a complete platform where users can buy land and create a parallel life to their real one. As of December 2021, it claimed to have 300,000 monthly active users (see the page https://nwn.blogs.com/nwn/2021/12/decentraland-blockchain-metaverse-user-revenue-stats.html (accessed on 1 December 2025)), but those figures have been heavily criticised, with independent observers proposing daily users as low as some hundreds (see the page https://decentraland.org/blog/announcements/how-many-dau-does-decentraland-have (accessed on 1 December 2025)).
The entire economy of Decentraland is based on parcels of digital land, each represented as a unique non-fungible token (NFT) on the Ethereum blockchain, which users can trade. In addition to land, users can buy and sell virtual assets, such as wearables [37], and other NFTs. The platform also features a mode known as the Builder, which allows users to create new NFTs and resell them on the market.
Its infrastructure is peer-to-peer and consists of three layers: the Consensus Layer, which keeps track of purchased land, the Land Content Layer, which contains assets like objects, textures, and sounds, and the Real Time Layer, which tracks communications between users. This structure allows for error management and prevents the system from collapsing when issues arise.

4.3. CryptoKitties

CryptoKitties is another platform where registered users can play, buy, create, and sell NFTs. It was founded in 2017 by the company Axiom Zen and is also based on Ethereum. CryptoKitties NFTs represent kittens that can be bought, sold, and customised. Kittens are divided into four categories (Normal, Fancy, Special Editions, and Exclusive) and bear Cattributes, ranging from eye colour to fur colour. Each attribute is composed of four genes, one visible and three latent, and the characteristics of the kittens can be highly varied due to the different percentages of these genes. The first release was the Gen 0 collection, which had 50,000 CryptoKitties available. It was an immediate success: shortly after the release, the transactions were so numerous that they congested the entire Ethereum network (see the news on https://qz.com/1145833/cryptokitties-is-causing-ethereum-network-congestion (accessed on 1 December 2025)). Its rapid rise has been examined by [38], who noted that the platform owes its great success to the media attention it received. The peak in the number of participants occurred between the 10th and 18th days, after news of a $100,000 sale of a kitten. A record sale of $170,000 was reported in 2018 (see the news on https://www.inventiva.co.in/trends/someone-paid-170000-for-the-most-expensive-cryptokitty-ever/ (accessed on 1 December 2025)). From then onwards, active players decreased rapidly. The reasons for this decline are various, including the constant release of kittens, which led to the platform offering more than the actual demand. Consequently, the profits from their exchanges also decreased, as the value of NFTs is influenced by demand. Additionally, the disparity between rich and poor players in the game increased, causing poorer users to leave the game. The value of CryptoKitties depends on their characteristics. The rarest and most valuable ones are from the ’Gen 0’ category, with some of them not yet released and only released on special occasions, like Founder Cat 40, which was purchased for $1,064,022.75. The entire CryptoKitties marketplace has been designed with restrictions to prevent inflation. The number of kittens that can be created is limited, and the introduction of a reproduction fee ensures that users only create kittens if there is actual demand in the market.

4.4. Gods Unchained

Gods Unchained is a collectible-card game where the cards are NFTs. It was created in 2019 and was initially based on the Ethereum blockchain, but it later moved to the Immutable X51 blockchain. Unlike many pay-to-earn games, Gods Unchained is a free-to-play game, and therefore does not require purchases at the beginning. Aside from tutorial games, it consists of three game modes: Solo, which allows you to play against the computer; Ranked, which includes ranked challenges where you can win prizes such as cards; and Direct Challenge, which allows you to challenge friends in friendly matches.
New users are given 140 cards to start with and are rewarded with cards (and, consequently, NFTs) each time they win. Cards have a value that varies based on several factors, including supply and demand, as well as their rarity and characteristics, such as power. Cards may be traded on the Gods Unchained platform, where a commission fee is to be paid, or on other general-purpose platforms.
Hyperion, a legendary card from Gods Unchained, was sold in 2021 for 137.8 Ether (approximately $60,000 USD) (see https://portal.godsunchained.com/blog/the-62000-card/ (accessed on 1 December 2025)).

4.5. Atomic

Atomic is an open-source platform created to enable the tokenization and commercialization of NFTs (see the page https://wax.atomichub.io/market (accessed on 1 December 2025)). It was established in 2020 and is based on the Wax blockchain (https://www.wax.io/ (accessed on 1 December 2025)).
Atomic is integrated with its own personal wallet called Atomic Wallet, which allows users to securely store their assets and resources. Additionally, Atomic has developed its own app for connecting and conducting exchanges.
Atomic’s platform enables Atomic Swaps, a method for exchanging NFTs and cryptocurrencies developed on various blockchains. The acquisition process on this platform is similar to others, involving the following steps: creating or linking a personal wallet with available resources, finding the NFT of interest, and deciding whether to purchase it immediately at the seller’s proposed price or make an offer that the seller can choose to accept or decline. In the selling process, this platform allows for traditional methods such as auctions or setting a selling price. It also permits dynamic pricing, which means that the price can vary based on the market and certain factors such as time (the longer since the NFT’s creation, the higher the price), demand, supply, and other customizable factors like cryptocurrency prices.

4.6. Nifty Gateway

Another highly significant platform is Nifty Gateway (https://www.niftygateway.com/ (accessed on 1 December 2025)), launched in 2018 by Duncan and Griffin Cock Foster, two brothers from New York City. The platform offers a wide selection of digital artwork from emerging and renowned artists, as well as celebrities like Elon Musk and Paris Hilton.
Nifty Gateway operates on a drop system that periodically releases new NFTs. Each drop features a specific theme or artist, and users must purchase the NFTs within a specified timeframe, or they are removed from the market. This has created a sense of urgency and exclusivity around Nifty Gateway NFTs, increasing their demand and value.
Furthermore, Nifty Gateway was one of the first NFT platforms to accept credit card payments, simplifying NFT purchases for new users and expanding the market for artists and creators.

4.7. SuperRare

SuperRare (see its website https://superrare.com/ (accessed on 1 December 2025)) is an NFT platform focused on digital art. Founded in 2018, it boasts a careful selection of its artists. It is based on auctions, often dealing with exclusive artworks with limited editions.

4.8. Foundation

Foundation (see its website https://foundation.app/browse/nfts (accessed on 1 December 2025)), too, is an NFT platform dealing with digital art, though it focuses on emerging artists and niche markets. Though any individual with an Ethereum account may buy and sell NFTs on this platform, the possibility of minting NFTs on it is reserved for a closed group of special members. The market dynamics have been investigated in [39].

5. Pricing Determinants

Whatever the mechanism employed to clear the market, the price of NFTs may be influenced by a number of factors. In this section, we review which pricing determinants have been examined and found relevant in the literature. In some cases, the subject of analysis was not the price itself but its variation over time, i.e., the NFT return.
A recent review of pricing determinants for NFTs has been presented by [35], who focused on the methods to identify determinants and suggested a classification based on the following five classes: hedonic regression models, repeat sales regressions, vector autoregressive models, machine learning, and wavelet models. Their analysis, based on eight papers, shows a heavy dominance of hedonic regression models over the others, as that class of models is adopted in five out of eight papers, with repeated sales regressions and vector autoregressive models being employed just in one paper each. Hereafter, we also take into account the more recent literature, which has significantly increased over that considered by [35], and focus on the determinants rather than the methods.
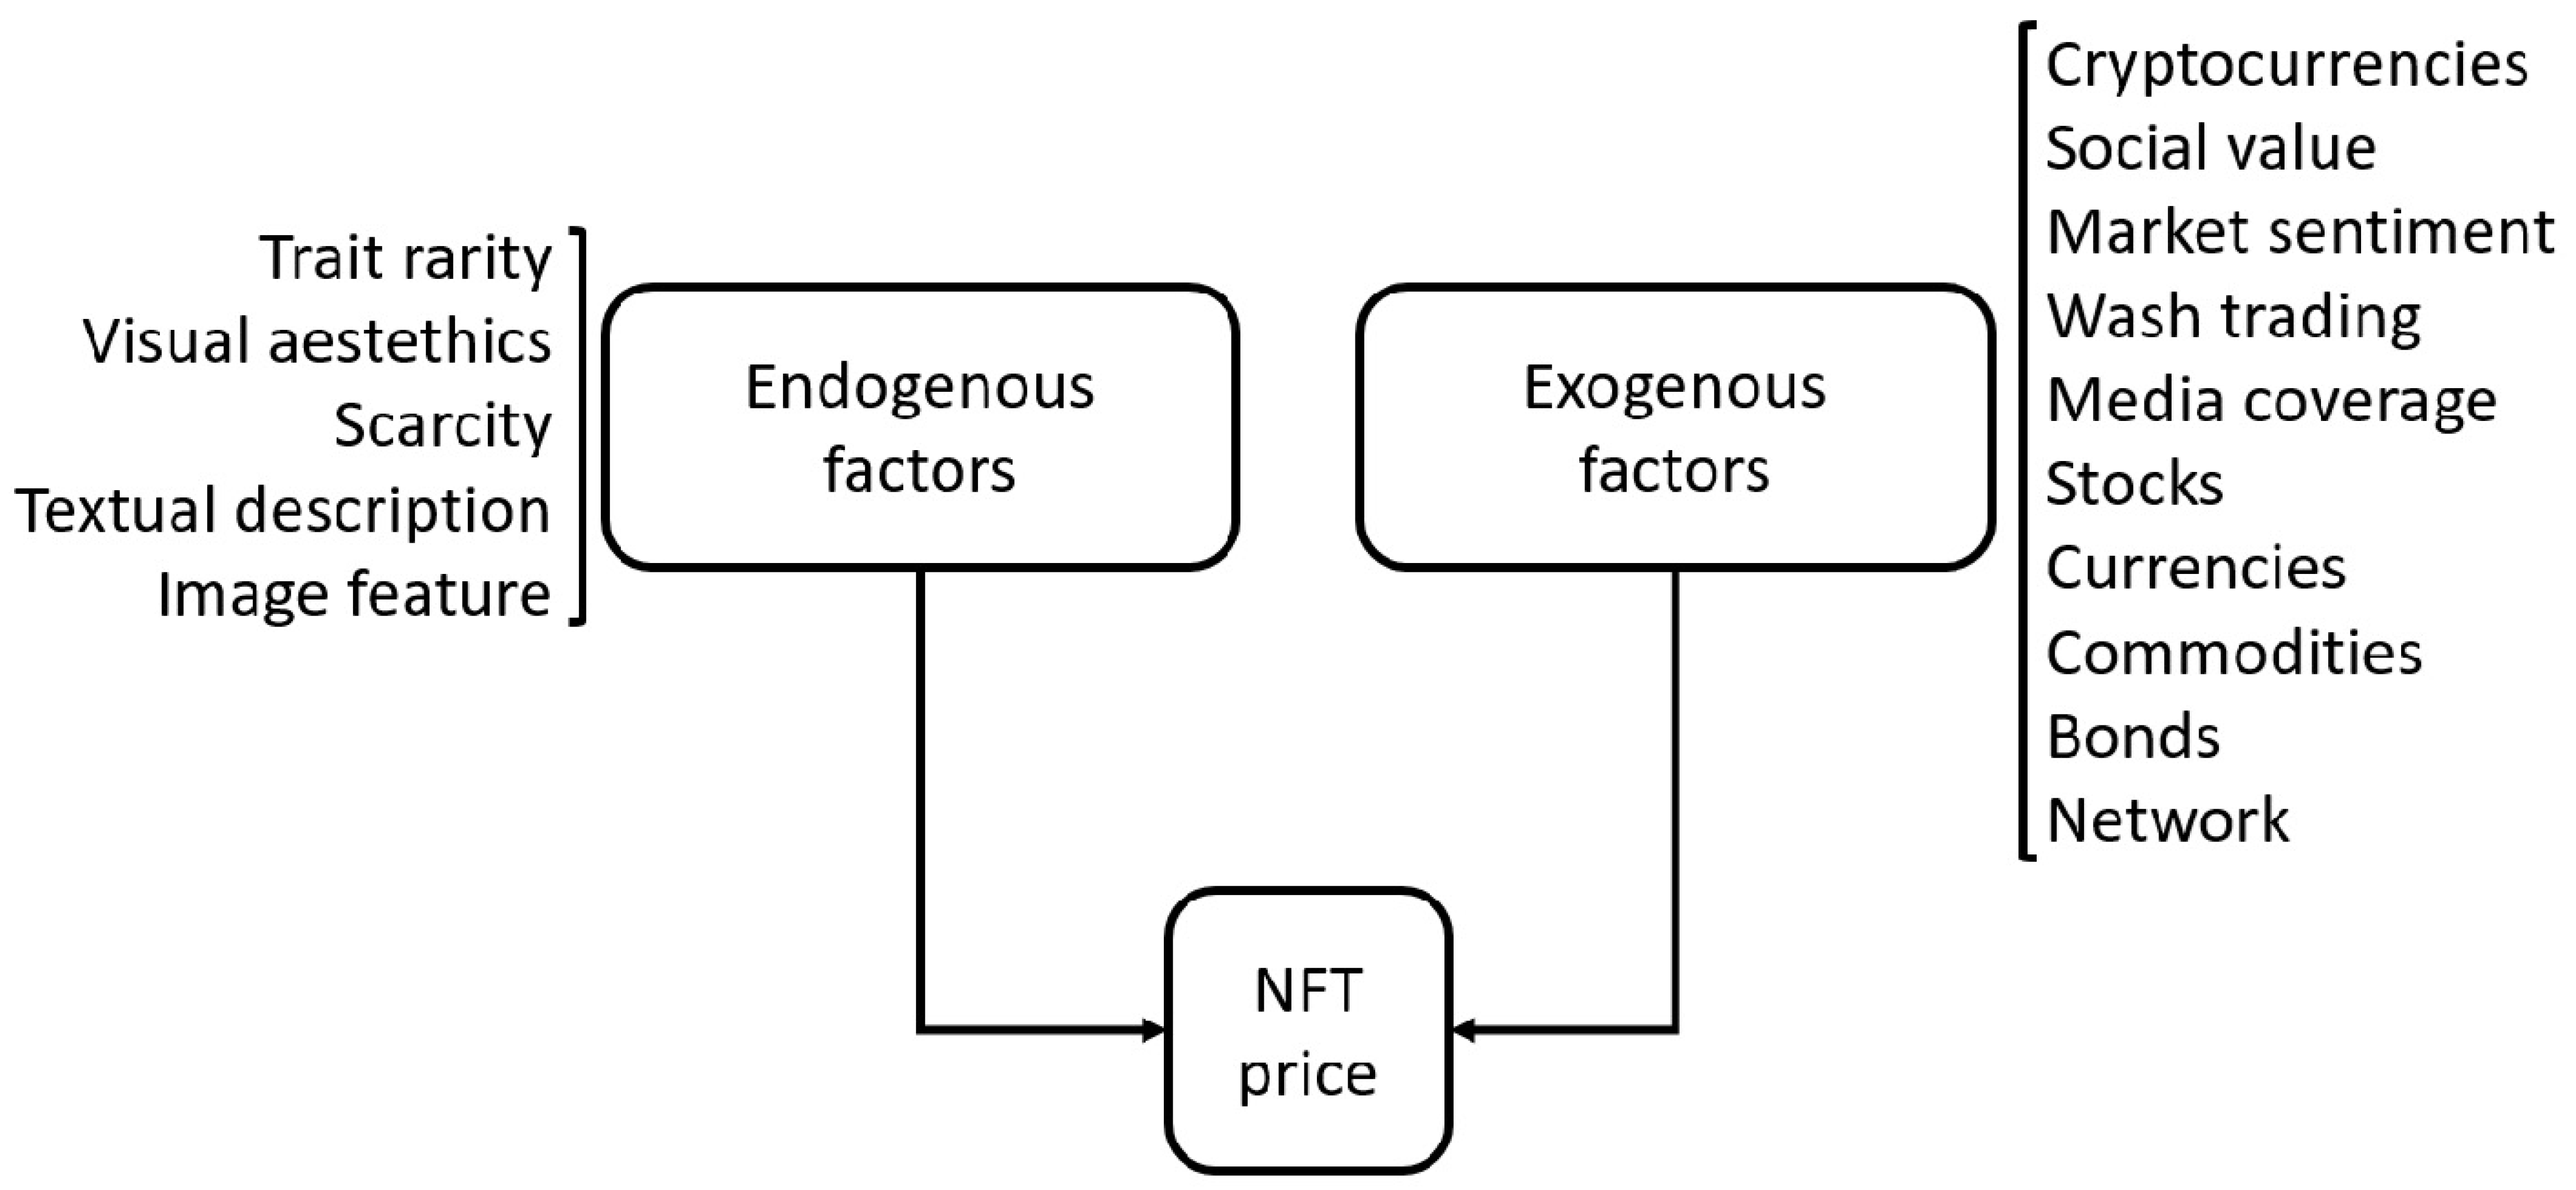
First, we distinguish between endogenous and exogenous factors. Endogenous factors relate to the intrinsic features of NFTs, such as their rarity or their traits. Exogenous factors do not depend on NFTs’ features, e.g., the value of cryptocurrencies. This distinction was clearly highlighted by [40], and the relevance of endogenous shocks for NFTs’ price dynamics (namely their return) was strongly advocated for by [41]. The contribution of both factor categories to the price of NFTs is depicted in Figure 2.

5.1. Endogenous Factors

Let us first consider the endogenous factors. Some may apply to all NFTs (or at least a wide majority of them), while others pertain only to specific NFTs. The factors suggested in the literature are reported in Table 1. The presence of a checkmark (✓) in a cell indicates that the corresponding endogenous factor was explicitly considered or discussed in the respective reference.
The textual description of NFTs was employed by [40] to extract relevant keywords through text mining that represent the endogenous features of the NFT. The relationship between endogenous features and price was established through a hedonic pricing approach relying on LASSO linear regression. The NFT market used for testing this approach was SuperRare.
For visual NFTs that exhibit traits (e.g., the gender or the type, such as zombie or ape) [42] have examined the impact of trait rarity on prices, where rarity is defined by the fraction of NFTs that share that trait in the collection. They analysed 410 collections containing almost 1.5 million NFTs. They found that rarity is positively correlated with the sale price and negatively correlated with the number of sales of an NFT (i.e., rare NFTs are less traded but sell for more). Rarity also leads to higher returns on investments and lower risk in the case of secondary sales. The rarity of traits is also suggested as a pricing determinant by [43]. Ref. [44] also explore the link between rarity and price in the Bored Ape Yacht Club (BAYC) NFT collection using formal concept analysis (FCA). The study finds that rarity significantly influences NFT prices, particularly in the medium rarity range. However, when rarity is extremely high or low, other factors such as uniqueness, visual appeal, and the naturalness of the NFT images become more important. The role of rarity in the game context is also analysed by [45], who suggest that the rarity score does not guarantee a high price. However, trait rarity is put forward as a possible base for recommendation tools, as explored in [46]. Schaar and Kampakis considered CryptoPunks NFTs as an alternative investment and found rarity (number and kind of attributes) to be a driver of price and discovered that the number of accessories also plays a significant role [19].
A hedonic price model was put forward by [47] based on some trait rarity, considering eight features for HV-MTL and six for Sappy Seal on the OpenSea platform. The performance was as low as R 2 = 0.27 .
Alsultan et al. [48] consider aesthetics instead, putting forward a linear regression model to analyse the relationship between NFT price and four quantities, based on the CryptoPunk collection. The four quantities embodying the aesthetic features of the NFT were as follows:
  • Number of hues (representative of colourfulness);
  • Brightness;
  • Saturation (colour intensity);
  • Range of texture (representative of visual complexity).

In addition to these quantities, the authors also considered some control variables, including time, the daily percentage change in sales volume, the ETH/USD exchange rate, and the type of CryptoPunk. They obtained a very good fitting, with R 2 = 0.92 . The influence of the four aesthetics variables was found to be significant (non-zero regression coefficient) at the 1% significance level. However, nearly all the control variables turned out to be significant as well, with the notable exception of sales volume changes.
A similar approach is taken by Chen et al. [49], where the influence of aesthetics factors on price is examined. The set of factors examined is not exactly the same as in [48], since they consider colour (embodied by hue, lightness, saturation, and hue counts), composition, edge, and image quality. The dataset is made up of two collections (Cool Cat and Doodles) extracted from OpenSea. The highest correlation with price is found to be due to the most frequent hue in the Cool Cat collection. However, the overall fitting quality in a linear regression model is rather poor, since the R 2 is just 0.15 for the Cool Cat collection and 0.24 for the Doodles one.
Scarcity refers to the overall supply volume (collection size) of the NFT series itself. It was considered by [50] in their moderation study, along with image features, obtained through image embedding. Scarcity (the authors here use the term rarity as a proxy of scarcity) is also considered an important factor in the selling prices of NFTs in the play-to-earn game Axie Infinity by [51]. They also employed a machine learning approach (using XGBoost) to predict the price of NFTs based on those predictors.
Among the endogenous factors, some may be very specific to the NFT type. For example, in Decentraland, where NFTs are exchanged for parcels of land, the price was found to be determined mainly by the location of the land and access to amenities (plazas and districts), as well as the prices of closely located parcels (describing the spatial auto-correlation of prices) [52]. They proposed a linear regression model to explain the price as a function of those features. Decentraland is also the subject of investigation for [53], who found, again, that location is a major driver, as plots cost more if they are located in the proximity of the city centre (as in the physical world) or in places whose name is easy to remember.
Table 1. Endogenous factors.
TDTRSIFAE
[40]
[52]
[50]
[43]
[44]
[54]
[48]
[49]
[55]
[19]
[47]
TD = textual description; TR = trait rarity; S = scarcity; IF = image features; AE = aesthetics.

5.2. Exogenous Factors

We can now turn to exogenous factors. A table to recap such factors proposed in the literature is shown in Table 2.
Ref. [56] investigates the returns and volatility of NFT segments and their relationship to media coverage since the beginning of the COVID-19 outbreak. They have shown that all the five NFT segments they investigated (Art, Collectibles, Games, Metaverse, and Utilities) show a very low correlation (between −0.03 and +0.04) with MCI (the Media Coverage Index).
The value of the underlying digital currency used for NFT-related transactions has been envisaged as having an impact on NFT prices. However, an analysis of volatility spillover between Bitcoin and Ether cryptocurrency markets on one side and Decentraland, CryptoPunk, and Axie Infinity NFT marketplaces on the other side has shown a very low spillover to and from NFT markets, though some co-movement (through a wavelet coherency analysis) is observed between Ether and Decentraland ([57]). A similar analysis has been carried out by [58], who employed the Granger test to examine directional causality relationships between cryptocurrencies and NFT prices. Their analysis shows that cryptocurrencies (namely Ethereum, Crypto Coin, and Bitcoin) influence NFT prices, while a reverse relationship also appears, in that NFT prices influence Ethereum.
Ref. [59] also investigated the interdependence between the cryptocurrencies market and NFTs’ value, also accounting for the influence of media attention towards NFTs. They examined three datasets: NonFungible.com, Google Search Volume Index, and Yahoo Finance. The interconnection among cryptocurrencies, people’s attention, and NFTs’ value was found to be significant only during the first period of the pandemic. Later, NFTs’ value seems to follow their own independent development.
In an effort to understand whether the NFT market is driven by the artistic value of the NFT or by the value of the underlying cryptocurrency employed to buy and sell those NFTs, Anselmi and Petrella [7] found the latter hypothesis to be more representative of reality, since prices, returns, and the volatility of NFTs correlates well with cryptocurrencies’ corresponding quantities and trading volumes, rather than art objects. Their work was based on data from the OpenSea marketplace. Ref. [60] also compared the period before and during COVID (from 2017 to 2021) to examine the correlation between the NFT market and alternative asset classes. They found that the price of NFTs was driven by bitcoin and stocks before the pandemic, while co-movements were observed between NFTs and bitcoin, bonds, and crude oil during the pandemic. The relationship between the NFT market and the crypto market is also put forward by [43], based on the work by [61].
A different flavour of influence of cryptocurrency on NFT prices is examined by [62]. Rather than analysing the correlation between cryptocurrency exchange values and NFT prices, they examine how the cryptocurrency chosen for settlement (the unit of account) affects willingness-to-pay. By using a hedonic pricing model applied to LAND sale transactions on the Sandbox game, they concluded that users pay more (3.4%) when using Sandbox’s native utility token (SAND) compared to ETH (in effective USD prices).
A quite wide view of the influence of financial assets on NFT prices (or, rather, their mutual relationship) is offered by [4], who focus on blue-chip NFTs, i.e., high-value non-fungible tokens that have a large floor market capitalization, including Bored Ape Yacht Club (BAYC), Mutant Ape Yacht Club (MAYC), and CryptoPunks (CP). They consider stock indices, cryptocurrencies (Bitcoin and Ethereum), foreign exchange markets, government bonds, and gold. Actually, their interest lies in examining the role of NFTs as hedges, safe-haven assets, and diversifiers against both traditional financial and digital assets. The opposite direction is taken by [63], who focus on gold-backed cryptocurrencies (GBCs) and examine their relationship to NFTs, emphasising the role of GBCs in stabilising portfolios during high volatility in DeFi and NFT markets.
An exogenous factor, though internal to the NFT market, is the influence of the prices of other NFTs, i.e., inside the same asset class. Ref. [43] observed that price co-movements exist both between NFTs in the same collection and between NFT collections. Ref. [26] also found the price of an NFT to be correlated to the price of other NFTs sold before in the same collection. They distinguished between primary sales (the first time an asset is sold) and secondary sales, observing that the secondary sale price is strongly correlated to the primary sale one.
Rather than examining the price of NFTs, ref. [64] examined the return observed on NFTs, considering them as an investment. They focussed on three NFTs (THETA, Tezos, and Enjin Coin), finding that returns are highly connected to volumes using the quantile Value-at-Risk (QVAR) approach. Also ref. [65] focused on returns and considered 23 potential drivers of the returns of the 10 most popular NFTs based on price, trading volume, and market capitalisation. The NFTs with the highest price were found to be primarily influenced by Ethereum returns, while the NFTs with the largest trading volume were more sensitive to market volatility. Ref. [41] investigated the interdependence between returns of NFTs and other traditional assets such as gold, oil, equities, bonds, and a cryptocurrency (Ethereum), employing daily data from nonfungible.com and investing.com (MSCI Word Index, PIMCO investment Grade Corporate Bond Index Exchange-Traded Fund, U.S. Dollar Index, crude oil, Ethereum (accessed on 1 December 2025)). They distinguished between the period preceding the COVID-19 pandemic and that during the pandemic. Ethereum and NFTs are shown to exhibit the highest correlation and volatility in the pandemic period. However, NFTs do not appear to be correlated with other common assets. Both the static and the dynamic analysis reveal that during the pandemic the overall interdependence increases. Nevertheless, the majority of NFTs’ return fluctuations can be attributed to endogenous shocks; only a small percentage is due to the trends of other assets. Similar results are reported in [66] where the authors analyse Pearson’s correlation, the Gerber Statistic for co-movement, and the spillover index for volatility transmission. They deduce that NFTs have a diversification effect on portfolio investing in common assets. Ref. [67] investigates the dependence between volume and return of NFTs during extreme market conditions in Cryptokitties, Cryptopunks, and Decentraland, using both quantile cross-spectral coherency and quantile regression techniques. Results show that the uncertainty, business condition, and term-spread of equity and gold markets are important predictors of Cryptokitties returns, while the uncertainty and geopolitical risks of the oil, equity, and gold markets significantly predict Cryptopunks and Decentraland markets’ returns. In all cases, increases in Bitcoin prices reduce NFT market returns.
Also, ref. [68] explored the relationship between Ethereum and Bitcoin and NFTs and found a high correlation between both cryptocurrencies and the price of NFTs. They considered four NFTs: Theta, Chiliz, Enjin, and Decentraland.
Alizadeh et al. built a network considering the transaction data of NFT transfers on Ethereum after extracting data from the Moralis platform [69]. They found that there is a high correlation between the price of ETH and the total value of transactions. They observe that the correlation coefficient achieves its peak after a lag of roughly 20 days. Hence, the ETH price may be seen as a driver of the NFT market.
A more comprehensive analysis of pricing determinants has been carried out by Alion et al. [70], who extracted data from the Signex company data repository over a six-month period. They considered a large number of predictors, grouped under the following categories:
  • Market conditions;
  • Network factors;
  • NFTs features.
Regarding market conditions, they considered the following features: price of cryptocurrencies, other asset classes such as gold or crude oil, market sentiment, market uncertainty, blockchain exchange rate, NFT market size, and participants. Network factors, on the other hand, included the centrality of buyers and sellers in the NFT graph, network membership (considering Twitter and Discord), network effects, and experts’ opinions. Finally, NFTs features were sales history, visual features, size of NFTs, data format, rarity, and NFT category. The transactions extracted from the platform were used to train a random forest algorithm where the NFT price was forecast as a function of all those features. They found that the most relevant features were the number of Twitter and Discord users. However, the regression metrics were not very good, scoring an R 2 as low as 0.47.
Cepni and Aysan [71] have instead examined the relationship between several NFT coins (namely, Theta, Tezos, Chiliz, Decentraland, Enjincoin, Digibyte, and Wax), finding a significant spillover effect. That spillover was found to be influenced by the news-media sentiment of investors.
The relationship between NFT prices and cryptocurrencies, namely, Bitcoin and Ether, is analysed by [72] using wavelets and fractal analysis. The influence of price and volume movements of Bitcoin and Ether over NFT prices and trading volumes is confirmed over time periods longer than a day.
An additional term of comparison was considered by [73], who introduced the tokens affiliated with NFTs. For example, Decentraland and Sandbox have their own affiliated tokens (similar to cryptocurrencies), respectively, MANA and SAND, which are used to trade NFTs. They found that the correlation between the returns of cryptocurrencies and NFT-affiliated tokens was moderate to strong, while that between the returns of NFTs and cryptocurrencies or NFT-affiliated tokens was low.
The influence of social media, namely Twitter, on the evaluation of NFTs has been examined in [74]. Rather than carrying out a regression task, they adopted a classification approach, where the average selling price over all the historic sales was considered for each asset and binned into one of five value classes. The authors considered 77 features of Twitter posts and 19 features of the OpenSea platform. Classification was tackled through a score of machine learning algorithms (logistic regression, SVM, random forests, lightGBM, and XGBoost), obtaining an accuracy of 69.5%. They also tried to predict the value of NFTs based on the image characteristics by employing a convolutional neural network, obtaining an accuracy slightly higher than 50%.
When NFTs are used for a specific purpose, their utility for that purpose can also be a determinant of their price. Since utility is determined by specific traits of the NFT at hand, we can consider utility to simply be a score assigned to NFT based on their traits. In the context of the play-to-earn game Axie Infinity, ref. [51] found utility (i.e., the NFT’s usefulness in that game) to be a significant price predictor. In a similar gaming context, ref. [45], by using the XGBoost regressor, suggested that utility (the usefulness of the game characters) is a useful predictor of the price.
Ante collected the data of the 14 NFT projects in different domains (gaming, collectables, art, and metaverse) to investigate their short-term and long-term interactions, employing a vector autoregressive model and Granger causality [2]. Results show that NFT markets are driven by other NFT markets.

5.3. Mixed Effects

Some authors have investigated the joint impact of endogenous and exogenous factors. In some cases (typically in studies involving the use of machine learning algorithms), the list of regressors is so large as to include many endogenous and many exogenous factors at the same time. In this subsection, we review those papers.
The interaction of endogenous and exogenous features was investigated by [50]. In particular, they examined the impact of social value (an exogenous variable) on the perceived value of scarcity (an endogenous variable). Social value was measured through two operational definitions, based respectively on the number of tweets related to the NFT or the number of likes received by that NFT. Those variables were measured on Twitter, considering the OpenSea collection. They found that, while scarcity per se has a positive impact on prices (the scarcer an NFT is, the higher its price), social value reverts that relationship: if the social value of an NFT is high, scarcer NFTs exhibit lower prices.
A more holistic view of the determinants of NFT prices has been taken by [54], who proposed an oracle to estimate the fair price of an NFT. Their proposal concerns artworks and is based on considering two different mechanisms impacting prices: the history of production and the history of effects. The former allows us to trace the whole history of the NFT back to its creators, so as to distinguish original NFTs from fake ones and avoid scams. The history of effects identifies real-world factors that impact on prices, such as scarcity, effects on the entertainment industry, participation in art exhibition events, tangibility, and transaction cost. The early version of the NFT price oracle proposed by the authors is based on the time-weighted average price model applied to similar sales (since the NFTs are not frequently traded) and on the scarcity of an artwork. Ref. [55] adopted a hedonic regression model, finding that the price depends on rarity, the centrality of the NFT investor in the network of sellers and buyers, and its experience (measured by the frequency of transactions and their diversity).
Rather than relying on an empirical analysis of NFT prices, ref. [75] proposed a theoretical model that links the price of NFTs to a value-generating mechanism based on the wish to achieve higher social ranking deriving from status, clout, and fame.
Rather than looking for determinants, Luo et al. [76] analysed the influence of Tweet activity on NFT prices. They used the presence of words (namely, their TF-IDF score) in tweets as regressors to predict price movements, obtaining an accuracy of 67% through a transformer architecture.
However, NFT prices may also be determined by questionable practices. An example is wash trading, which consists of a sequence of sell and subsequent buy operations by the same owner, as reported by [77], who propose three methods to identify the presence of wash trading. This practice leads to inflated transaction volumes and prices.
Kireyev and Lin compared two models for price, based on hedonic linear regression and gradient boosting (GBM) on decision trees [78]. Both models relied on a very large number of regressors (close to 300 for hedonic regression). The GBM was found to perform better than hedonic regression.
Also, the pricing mechanism may influence prices, aside from the well-known relationship between value and bid in auctions. In fact, ref. [79] analysed the interaction among seller, bidder, and market as a sequential game, showing that bidding costs (i.e., the cost of the pricing mechanism itself) affect NFT prices, together with marketplace design.
Another attempt based on machine learning was carried out by [80], who applied two ensemble algorithms (Random Forest and Adaboost) to predict NFT prices based on information concerning first the NFT, then the account, and finally the collection. They obtained an R 2 well in excess of 0.99 when they introduced information about the account (regarding both the creator and the owner).
Finally, ref. [81] examined the consequences of a secondary market by formulating a two-stage game-theoretic model where an NFT creator sets the optimal selling price and royalty rates, while consumers make purchase and resale decisions in response. The output reveals that creators are compelled to lower the selling price when a secondary market is introduced, even without applying royalties, and that despite the royalty setting, introducing a secondary market can result in unexpected revenue loss for the creator.
Table 2. Exogenous factors.
WTMCBSSVNFTUCCMON
[77]
[56]
[60]
[50]
[43]
[57]
[58]
[62]
[51]
[45]
[4]
[54]
[67]
[64]
[68]
[69]
[70]
[71]
[72]
[73]
[74]
[55]
[2]
[76]
[75]
WT = wash trading; MC = media coverage; B = cryptocurrencies; S = stocks; SV = social value; U = utility; C = currencies; CM = commodities; O = bonds; NFT = NFT prices and volumes; N = network effects

6. Pricing Mechanisms

Whatever the factors that drive prices, prices are actually set through various mechanisms. Currently, the mechanisms employed in the near totality of NFT marketplaces are either auctions or fixed-price settings. In this section, we review the basic features of those mechanisms and show which marketplaces use which.
NFT marketplaces predominantly employ auctions as their primary pricing mechanism, favoring the English (Ascending) and Dutch (Descending) formats. While theoretically robust, the Vickrey (second-price sealed-bid) auction is relatively uncommon, a trend supported by the limited number of platforms (e.g., Sealed (see the post on www.redlion.news (accessed on 1 December 2025)) and Euterpe (the news on https://www.coinspeaker.com/euterpe-ip-nft-vickrey-auction-was-a-huge-success-ip-nft-mystery-box-already-sold-out/ (accessed on 1 December 2025))) that have adopted it. This observed rarity is largely due to implementation challenges, particularly the vulnerability to seller-side manipulation in a decentralised context.
The fixed-price mechanism is very simple. Sellers set a fixed price for their NFT, and buyers can purchase it outright. Its speed and simplicity make it ideal for sellers who prefer instant sales without a bidding process. It is very common, e.g., on OpenSea and Rarible, but it is employed in many other marketplaces as well.
Turning to auctions, there are four basic types of auctions:
  • Ascending auctions;
  • Descending auctions;
  • First-price sealed-bid auctions;
  • Second-price sealed-bid auctions.
An English auction is a common type of auction in which the price of an item is gradually increased until only one bidder remains willing to pay the highest price. Participants openly bid against each other by calling out their offers, each bid higher than the last. Bidders can continue to increase their offers, often by predetermined increments, until no one is willing to bid higher. The auction ends when the item is declared as sold to the highest bidder. In online auctions, this is usually accomplished by a timing mechanism, so bids are stopped when time has elapsed. The winning bidder pays the final bid price and receives the item. The English auction is known for its transparency, as all bids are public, allowing bidders to gauge competition and adjust their strategy accordingly. Many marketplaces adopt English auctions, including OpenSea ([36]), Foundation (see the webpage https://foundation.app/), SuperRare (see the webpage https://help.superrare.com/en/collections/11764060-superrare-guides-and-tutorials), Rarible (see the webpage https://rarible.com/), Zora (see the webpage https://zora.co/collect/zora:0x3866dfcb54f90fe47fdc717193bfcb7ee09fbfdf/1), KnowOrigin (see the webpage https://knownorigin.io/), NiftyGateway (see the webpage https://www.niftygateway.com/), and Async Art (see the webpage https://async.art/ (accessed on 1 December 2025)).
Auctions may start with a reserve price, which is the minimum price that a seller is willing to accept for their item or asset. If bids do not meet or exceed the reserve price, the item will not be sold.

Time-Reset Mechanisms in NFT Auctions

The time-reset mechanism, often referred to as a “soft close,” is a crucial feature in many NFT marketplace auctions, designed to simulate the dynamics of a live auction and prevent “bid sniping”—the practice of placing a winning bid in the final seconds. This mechanism ensures that an item reaches its fair market price by giving all interested bidders a chance to respond to last-minute offers.
The applicability of the time-reset depends entirely on the auction format being used:
English auction is the most common format where the time-reset mechanism is implemented, as it is a time-limited auction where bids are openly placed, pushing the price upward. In a typical English NFT auction, the seller sets a starting price and a time limit (e.g., 24 h). A “critical period” is defined near the end of the auction (e.g., the final 5, 10, or 15 min). If a new bid is placed during this critical period, the auction timer resets to the full duration of that critical period. This loop continues indefinitely until the timer expires without receiving any further bids. For instance, if an auction is set to close in 10 min and a bid is placed at T-3 min, the clock resets back to T-10 min. This key implementation detail, which varies between platforms (e.g., Foundation might use a 15 min reset while SuperRare might use a 5 min reset), is vital because it directly impacts bidding strategy and is therefore a necessary detail to cite when describing a platform’s pricing mechanism.
A Dutch auction is a type of auction where the auctioneer starts with a high asking price, which is gradually lowered until a bidder accepts the current price (see the webpage https://getmojito.com/blog/dutch-auction-nft (accessed on 1 December 2025) for a brief review of Dutch auctions for NFTs). The initial price is typically high and above the expected market value. In the absence of bids, prices are then lowered incrementally at regular intervals until a bidder signals their willingness to buy. The first bidder to accept the current price wins the item. This bidder then pays that price and receives the item. Dutch auctions are known for their speed and efficiency. Decentraland (see the webpage https://decentraland.org/ (accessed on 1 December 2025)) ([52,82]), Nifty Gateway, Art Blocks, Foundation (see the webpage https://medium.com/geekculture/what-is-a-dutch-auction-and-why-it-matters-in-the-nft-space-59d5d26369f9 (accessed on 1 December 2025)), and SuperRare are among the NFT marketplaces that support Dutch auctions.
In a first-price sealed auction, bidders submit their bids privately (sealed), and the highest bidder wins but pays the exact amount they bid. It is probably the simplest auction mechanism. A major disadvantage of this mechanism is its lack of transparency. Bidders have no idea of their competitors’ evaluations. Zora, OpenSea, Foundation, Manifold Studio (see the webpage https://studio.manifold.xyz/auth/login (accessed on 1 December 2025)), and Private NFT Drops have sometimes employed first-price sealed auctions.
In contrast to the ascending nature of the English format, the Dutch auction starts with a high price that gradually decreases over time. In this format, the time-reset mechanism is not applicable. The auction is designed for a quick sale: the item is sold immediately to the first buyer who accepts the current, decreasing price, or when the price reaches a predetermined reserve minimum. The concept of preventing last-minute bids is irrelevant here, as the closing is determined by the first buyer’s action rather than by the final time limit.
A second-price auction, also known as a Vickrey auction, is a type of auction where the highest bidder wins the item, but they pay the second-highest bid rather than their own. Bids are sealed, meaning no one knows what others are bidding. Each bidder submits the maximum amount they are willing to pay for the item. After all bids are submitted, the highest bid is identified, and the bidder pays the amount of the second-highest bid. This type of auction encourages bidders to bid their true value for the item, as there is no advantage to underbidding (as in trying to win at a lower price) or overbidding. Ref. [45] have also shown that desirable properties for an auction are seller incentive compatibility, so that sellers do not gain from submitting fake bids; bidder incentive compatibility, so that bidders are induced into submitting their true valuation; and off-chain-agreement-resistance, so that sellers and bidders do not gain from looking for off-chain collusion. They also prove that no such perfect auction exists in a decentralised environment such as a blockchain, but they provide a protocol that is capable of approximating the perfect one, where each party is led to behave properly if their counterparty does the same (a property they call equilibrium truthfulness), and the resulting utility approximates that obtained under second-price auctions. The Vickrey auction is considered as relatively uncommon in the NFT space. Because the Vickrey auction is a non-incremental mechanism with a defined, single closing time for the submission of sealed offers, the time-reset mechanism is unnecessary and inapplicable. The auction closes rigidly at the predetermined time, and all bids are then revealed. The scarcity of the Vickrey format in NFT marketplaces is often attributed to the risk of seller manipulation (i.e., placing fake bids to inflate the winning price), which compromises its theoretical advantage of being incentive-compatible.
Some of the literature has been devoted to using auctions for NFTs in specific contexts. Ref. [83] have studied the possibility of using auctions to trade NFTs in the metaverse. What is different from other studies is the virtual context where auctions take place. They consider three virtual agents with different memory features, who adopt different bidding strategies. They test three different scenarios where virtual agents and humans interact and prove that an auction mechanism can lead to good interaction in the metaverse. Ref. [84] proposed securitizing NFTs, i.e., subdividing each NFT into units and selling it as part of a package, including other securities. They did not propose any pricing scheme for the securitised NFT, though they assumed that the price of the securitised NFT would be lower than the price of a non-securitised NFT. However, they also consider a repurchase mechanism, by which the owner of a large share of the units of an NFT may repurchase all the remaining units by submitting bids to the owners of the other units. They identify the optimal bidding as bidding through a Stackelberg game, where the transaction price is the arithmetic average of the bids submitted by the seller and the buyer.
Some issues have been reported for trading mechanisms that may affect pricing [85]. Though the highest bid in English auctions should set the price, those authors have highlighted the possibility of bid pollution, as off-chain bidding processes allow bidders not to lock funds, hence spurring the occurrence of many casual bids, which are not adequately supported by funds and fail on execution. By gathering information from DappRadar (see the webpage https://dappradar.com/ (accessed on 1 December 2025)), they found that bid pollution affected as much as 33% of auctions on OpenSea and 80.4% of auctions on Rarible.
Finally, the market efficiency was investigated for Decentraland by [86], who found the market to be inefficient for a significant portion of the nearly two-year period under investigation.

7. Critical Synthesis and Future Research Agenda

This section provides a critical synthesis of the collected evidence, highlighting the structural contradictions in the literature, defining key research gaps, and outlining the inherent limitations of the current research landscape.
The literature reviewed presents a highly heterogeneous body of work, frequently yielding non-univocal results, particularly concerning the influence of external factors. For instance, while the value of cryptocurrencies is a dominant exogenous factor, current methodologies often produce ambiguous effects, suggesting a need for greater analytical effort to reconcile discrepancies stemming from the diverse time windows and datasets employed. A deeper understanding reveals that these contradictions largely reflect the structural segmentation and microstructures of the NFT market, rather than fundamental theoretical conflicts. Specifically, studies exhibit contrasting approaches across several critical dimensions.
Platform heterogeneity: NFT marketplaces differ substantially in market design (curated vs. open admission), pricing mechanisms (fixed-price vs. auctions), fee structures, visibility algorithms, and verification policies. For example, curated art platforms such as SuperRare and Foundation operate under scarcity-by-design, whereas open platforms like OpenSea allow mass minting and high supply. This structural difference explains why similar features (e.g., rarity or aesthetics) can have divergent price effects across platforms that impose radically different levels of supply control, information disclosure, and quality filtering.
Differences in user demographics: We explicitly discuss how user composition (traders vs. collectors, speculators vs. gamers, investors vs. creators) affects price formation. For instance, gaming NFTs (e.g., in Axie Infinity) embed utilitarian value, while art-focused marketplaces reflect symbolic and aesthetic valuation mechanisms. As a result, the same variable (e.g., rarity) operates through different economic mechanisms, depending on user intent and community norms.
Market maturity and timing: Early-phase NFT markets exhibit extreme volatility, thin liquidity, and speculative behaviour, while more mature periods show greater differentiation and price dispersion. The revised discussion acknowledges that contradictory results often reflect different temporal windows of analysis rather than true theoretical conflict.
Data frequency and measurement choices: We highlight how differences in sampling frequency (transaction-level vs. daily aggregates) and dependent variables (price vs. return vs. volume) fundamentally influence estimated relationships. For example, cryptocurrency prices show strong short-term co-movement with NFT prices in some high-frequency studies but weaker effects at longer horizons.
Model dependence: We clarify that regression-based studies emphasise marginal effects, whereas machine learning models optimise predictive performance, often revealing different “important” variables. This methodological divergence naturally produces conflicting interpretive conclusions.

8. Conclusions

This study has provided an in-depth examination of the pricing mechanisms and value determinants in the rapidly evolving world of non-fungible tokens (NFTs), highlighting several key findings.
Auctions, particularly English and Dutch formats, have emerged as dominant price-setting mechanisms in NFT marketplaces for art pieces and collectibles, favoured for their ability to extract maximum willingness-to-pay, although fixed pricing remains widely accepted.
The price of an NFT is consistently influenced by a combination of endogenous factors (such as rarity, aesthetics, scarcity, and in-game utility) and exogenous factors (including cryptocurrency values, media coverage, economic uncertainty, investor sentiment, and social media activity). Among these, trait rarity consistently stands out as the most influential intrinsic feature.
While a relationship with cryptocurrencies like Ethereum and Bitcoin is evident, the direction and intensity of this influence vary, showing moderate correlations with crypto markets but limited connection to traditional financial assets. Furthermore, the application of predictive models, from machine learning to econometric approaches, yields varying degrees of accuracy, indicating that NFT pricing remains a partially unpredictable and sentiment-driven process.
The NFT ecosystem continues to evolve, blending elements of art, finance, and technology. Understanding these pricing dynamics is essential not only for investors and creators but also for the sustainable development of digital ownership economies. Future research should aim to refine predictive models, improve transparency, and explore the integration of NFTs in broader financial systems. Addressing these necessary advancements requires acknowledging several methodological and temporal characteristics of the current research, which present opportunities for future work, which we outline in the following.
The predominant reliance on a single bibliographic database suggests that expanding the search to multiple sources beyond Scopus could capture relevant studies that may have been previously omitted. Similarly, while the necessary inclusion of practitioner sources and web-based materials provides essential context, this approach introduces potential variability in reliability; thus, establishing consistent documentation standards remains a future challenge. Given the NFT market’s high volatility, rapid technological change, and evolving structures, the temporal generalizability of findings is naturally limited. This dynamic environment motivates the need for longitudinal study designs to ensure the long-term validity of conclusions. Finally, the evidence reviewed may be susceptible to publication dynamics, where studies reporting significant or novel results are more likely to be published than null findings. This possibility highlights the importance of systematic replication and meta-analysis to ensure the balance of the overall evidence. These characteristics collectively suggest the next steps for ongoing empirical validation: conducting multi-database searches, adopting longitudinal designs, and performing direct market-level data analysis.

Author Contributions

Conceptualisation, M.F. and M.N.; methodology, M.F. and M.N.; investigation, M.F.; resources, M.N.; writing—original draft preparation, M.F.; writing—review and editing, M.N.; visualisation, M.F.; supervision, M.N. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Institutional Review Board Statement

Not applicable.

Informed Consent Statement

Not applicable.

Data Availability Statement

No new data were created.

Conflicts of Interest

The authors declare no conflicts of interest.

References

  1. Wang, Q.; Li, R.; Wang, Q.; Chen, S. Non-fungible token (NFT): Overview, evaluation, opportunities and challenges. arXiv 2021, arXiv:2105.07447. [Google Scholar] [CrossRef] [Scilit]
  2. Ante, L. Non-fungible token (NFT) markets on the Ethereum blockchain: Temporal development, cointegration and interrelations. Econ. Innov. New Technol. 2022, 32, 1216–1234. [Google Scholar] [CrossRef] [Scilit]
  3. Darshan, M.; Raswanth, S.; Kumar, P. Data Analysis of Non Fungible Tokens (NFTs) Pricing using Brokerage Firm data. In Proceedings of the 2022 IEEE Global Conference on Computing, Power and Communication Technologies (GlobConPT), New Delhi, India, 23–25 September 2022; IEEE: Piscataway, NJ, USA, 2022; pp. 1–5. [Google Scholar]
  4. Havidz, S.A.H.; Santoso, M.D.; Alexander, T.; Caroline, C. Unpacking the financial attributes of blue-chip non-fungible tokens (NFTs) against traditional and digital assets. Asian J. Account. Res. 2024, 9, 309–324. [Google Scholar] [CrossRef] [Scilit]
  5. Chen, J.; Friedmann, D. Jumping from mother monkey to bored ape: The value of NFTs from an artist’s and intellectual property perspective. Asia Pac. Law Rev. 2022, 31, 100–122. [Google Scholar] [CrossRef] [Scilit]
  6. Chalmers, D.; Fisch, C.; Matthews, R.; Quinn, W.; Recker, J. Beyond the bubble: Will NFTs and digital proof of ownership empower creative industry entrepreneurs? J. Bus. Ventur. Insights 2022, 17, e00309. [Google Scholar] [CrossRef] [Scilit]
  7. Anselmi, G.; Petrella, G. Non-fungible token artworks: More crypto than art? Financ. Res. Lett. 2023, 51, 103473. [Google Scholar] [CrossRef] [Scilit]
  8. Pinto-Gutiérrez, C.; Gaitán, S.; Jaramillo, D.; Velasquez, S. The NFT hype: What draws attention to non-fungible tokens? Mathematics 2022, 10, 335. [Google Scholar] [CrossRef] [Scilit]
  9. Özdemir, O.; Kumar, A.S. Dynamic Efficiency and Herd Behavior During Pre-and Post-COVID-19 in the NFT Market: Evidence from Multifractal Analysis. Comput. Econ. 2024, 63, 1255–1279. [Google Scholar] [CrossRef] [Scilit]
  10. EIP-721; Non-Fungible Token Standard. Ethereum Foundation: Zug, Switzerland, 2018.
  11. Kong, D.; Li, X.; Li, W. Characterizing the Solana NFT Ecosystem. In Proceedings of the Companion Proceedings of the ACM on Web Conference 2024, Singapore, 13–17 May 2024; pp. 766–769. [Google Scholar]
  12. Sutopo, A.H. Blockchain Programming Smart Contract on Polygon; Topazart: Woodside, NY, USA, 2023. [Google Scholar]
  13. Hammi, B.; Zeadally, S.; Perez, A.J. Non-fungible tokens: A review. IEEE Internet Things Mag. 2023, 6, 46–50. [Google Scholar] [CrossRef] [Scilit]
  14. Ali, O.; Momin, M.; Shrestha, A.; Das, R.; Alhajj, F.; Dwivedi, Y.K. A review of the key challenges of non-fungible tokens. Technol. Forecast. Soc. Chang. 2023, 187, 122248. [Google Scholar] [CrossRef] [Scilit]
  15. Ko, K.; Jeong, T.; Woo, J.; Hong, J.W.K. Survey on blockchain-based non-fungible tokens: History, technologies, standards, and open challenges. Int. J. Netw. Manag. 2024, 34, e2245. [Google Scholar] [CrossRef] [Scilit]
  16. Steinwold, A. The history of non-fungible tokens (NFTs). Retrieved from Medium. 2019. Available online: https://medium.com/@Andrew.Steinwold/the-history-of-non-fungible-tokens-nfts-f362ca57ae10 (accessed on 1 December 2025).
  17. Rosenfeld, M. Overview of Colored Coins; Technical Report; Coinprism: Paris, France, 2012. [Google Scholar]
  18. McCoy, K. Art and nfts: Past and future. Colum. JL Arts 2021, 45, 353. [Google Scholar] [CrossRef] [Scilit]
  19. Schaar, L.; Kampakis, S. Non-fungible tokens as an alternative investment: Evidence from cryptopunks. J. Br. Blockchain Assoc. 2022, 5, 1–12. [Google Scholar]
  20. Casale-Brunet, S.; Zichichi, M.; Hutchinson, L.; Mattavelli, M.; Ferretti, S. The impact of NFT profile pictures within social network communities. In Proceedings of the 2022 ACM Conference on Information Technology for Social Good, Genoa, Italy, 7–9 September 2022; pp. 283–291. [Google Scholar]
  21. Popescu, A.D. Non-fungible tokens (nft)–innovation beyond the craze. In Proceedings of the 5th International Conference on Innovation in Business, Economics and Marketing Research, Virtual Conference, 15–17 June 2021; Volume 32, pp. 26–30. [Google Scholar]
  22. Hutson, J.; Banerjee, G.; Kshetri, N.; Odenwald, K.; Ratican, J. Architecting the metaverse: Blockchain and the financial and legal regulatory challenges of virtual real estate. J. Intell. Learn. Syst. Appl. 2023, 15, 1–23. [Google Scholar] [CrossRef]
  23. Musan, D.I.; William, J.; Gervais, A. NFT. Finance Leveraging Non-Fungible Tokens; Imperial College London, Department of Computing: London, UK, 2020; pp. 1–82. [Google Scholar]
  24. Page, M.J.; McKenzie, J.E.; Bossuyt, P.M.; Boutron, I.; Hoffmann, T.C.; Mulrow, C.D.; Shamseer, L.; Tetzlaff, J.M.; Akl, E.A.; Brennan, S.E.; et al. The PRISMA 2020 statement: An updated guideline for reporting systematic reviews. BMJ 2021, 372, n71. [Google Scholar] [CrossRef] [Scilit]
  25. Mongeon, P.; Paul-Hus, A. The journal coverage of Web of Science and Scopus: A comparative analysis. Scientometrics 2016, 106, 213–228. [Google Scholar] [CrossRef] [Scilit]
  26. Nadini, M.; Alessandretti, L.; Di Giacinto, F.; Martino, M.; Aiello, L.M.; Baronchelli, A. Mapping the NFT revolution: Market trends, trade networks, and visual features. Sci. Rep. 2021, 11, 20902. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  27. Cao, Y.; Xia, M.; Shigyo, K.; Cheng, F.; Yu, Q.; Yang, X.; Wang, Y.; Zeng, W.; Qu, H. NFTeller: Dual-centric Visual Analytics for Assessing Market Performance of NFT Collectibles. In Proceedings of the 16th International Symposium on Visual Information Communication and Interaction, Copenhagen, Denmark, 22–24 November 2023; pp. 1–8. [Google Scholar]
  28. Baker, B.; Pizzo, A.; Su, Y. Non-fungible tokens: A research primer and implications for sport management. Sport. Innov. J. 2022, 3, 1–15. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  29. Mereu, S. NFT Sports Collectibles: Characteristics and Factors of Consumer Value. In Global Applications of the Internet of Things in Digital Marketing; IGI Global: Hershey, PA, USA, 2023; pp. 310–331. [Google Scholar]
  30. Goanta, C. Selling LAND in Decentraland: The regime of non-fungible tokens on the Ethereum blockchain under the digital content directive. In Disruptive Technology, Legal Innovation, and the Future of Real Estate; Springer International Publishing: Cham, Switzerland, 2020; pp. 139–154. [Google Scholar]
  31. Firsova, N.; Ryzhkov, A. Analysis of cooling of the NFT market in 2022: Structure and Segments Exploration. In Proceedings of the DOKBAT 2022 18th International Bata Conference for Ph. D. Students and Young Researchers, Zlín, Czech Republic, 8–9 November 2022; Volume 108. [Google Scholar]
  32. Phillips, D.; Graves, S. The 10 Most Expensive NFTs ever Sold; Decrypt: New York, NY, USA, 2021. [Google Scholar]
  33. Chernikova, A. The Future Of NFTs: Will The Market Revive In 2024? 2023. Available online: https://www.forbes.com/sites/digital-assets/2023/11/13/the-future-of-nfts-will-the-market-revive-in-2024/?sh=4d1d1b614c8d (accessed on 23 April 2024).
  34. Alshater, M.; Nasrallah, N.; Khoury, R.; Joshipura, M. Deciphering the world of NFTs: A scholarly review of trends, challenges, and opportunities. Electron. Commer. Res. 2025, 25, 4193–4249. [Google Scholar] [CrossRef] [Scilit]
  35. Kräussl, R.; Tugnetti, A. Non-fungible tokens (NFTs): A review of pricing determinants, applications and opportunities. J. Econ. Surv. 2024, 38, 555–574. [Google Scholar] [CrossRef] [Scilit]
  36. White, B.; Mahanti, A.; Passi, K. Characterizing the OpenSea NFT marketplace. In Proceedings of the Companion Web Conference 2022, Lyon, France, 25–29 April 2022; pp. 488–496. [Google Scholar]
  37. Trujillo, A.; Bacciu, C. Toward Blockchain-based Fashion Wearables in the Metaverse: The Case of Decentraland. arXiv 2023, arXiv:2307.01322. [Google Scholar] [CrossRef] [Scilit]
  38. Jiang, X.J.; Liu, X.F. Cryptokitties transaction network analysis: The rise and fall of the first blockchain game mania. Front. Phys. 2021, 9, 57. [Google Scholar] [CrossRef] [Scilit]
  39. Fazli, M.; Owfi, A.; Taesiri, M.R. Under the skin of foundation nft auctions. arXiv 2021, arXiv:2109.12321. [Google Scholar] [CrossRef] [Scilit]
  40. Horky, F.; Rachel, C.; Fidrmuc, J. Price determinants of non-fungible tokens in the digital art market. Financ. Res. Lett. 2022, 48, 103007. [Google Scholar] [CrossRef] [Scilit]
  41. Aharon, D.Y.; Demir, E. NFTs and asset class spillovers: Lessons from the period around the COVID-19 pandemic. Financ. Res. Lett. 2022, 47, 102515. [Google Scholar] [CrossRef] [Scilit]
  42. Mekacher, A.; Bracci, A.; Nadini, M.; Martino, M.; Alessandretti, L.; Aiello, L.M.; Baronchelli, A. Heterogeneous rarity patterns drive price dynamics in NFT collections. Sci. Rep. 2022, 12, 13890. [Google Scholar] [CrossRef] [Scilit]
  43. Lommers, K.; Kim, J. A Framework for Asset Pricing in Non-Fungible Tokens. J. Altern. Investments 2024, 26, 96–108. [Google Scholar] [CrossRef] [Scilit]
  44. Lee, H.; Lee, G.C.; Koo, H.Y. Exploring the relationship between rarity and price of profile picture NFT: A formal concept analysis on the BAYC NFT collection. Blockchain Res. Appl. 2024, 5, 100191. [Google Scholar] [CrossRef] [Scilit]
  45. Milionis, J.; Hirsch, D.; Arditi, A.; Garimidi, P. A Framework for Single-Item NFT Auction Mechanism Design. In Proceedings of the 2022 ACM CCS Workshop on Decentralized Finance and Security, Los Angeles, CA, USA, 11 November 2022; pp. 31–38. [Google Scholar]
  46. Piyadigama, D.; Poravi, G. An analysis of the features considerable for NFT recommendations. In Proceedings of the 2022 15th International Conference on Human System Interaction (HSI), Gdansk, Poland, 28–30 June 2022; IEEE: Piscataway, NJ, USA, 2022; pp. 1–7. [Google Scholar]
  47. Xiong, W.; Wang, Y.; Li, W.; Zhang, J.; Guo, H. Pricing Mechanism of Non-fungible Token (NFT) Driven by Rarity Design. In Proceedings of the 2023 IEEE International Conference on Blockchain (Blockchain), Melbourne, VIC, Australia, 17–20 December 2023; IEEE: Piscataway, NJ, USA, 2023; pp. 74–79. [Google Scholar]
  48. Alsultan, S.; Kourtis, A.; Markellos, R.N. Can we price beauty? Aesthetics and digital art markets. Econ. Lett. 2024, 235, 111572. [Google Scholar] [CrossRef] [Scilit]
  49. Chen, Y.; Ye, Y.; Zeng, W. The Rich, the Poor, and the Ugly: An Aesthetic-Perspective Assessment of NFT Values. In Proceedings of the 16th International Symposium on Visual Information Communication and Interaction, Copenhagen, Denmark, 22–24 November 2023; pp. 1–8. [Google Scholar]
  50. Hofstetter, R.; Fritze, M.P.; Lamberton, C. Beyond scarcity: A social value-based lens for NFT pricing. J. Consum. Res. 2024, 51, 140–150. [Google Scholar] [CrossRef] [Scilit]
  51. Ho, K.H.; Hou, Y.; Chan, T.T.; Pan, H. Analysis of Non-Fungible Token Pricing Factors with Machine Learning. In Proceedings of the 2022 IEEE International Conference on Systems, Man, and Cybernetics (SMC), Prague, Czech Republic, 9–12 October 2022; IEEE: Piscataway, NJ, USA, 2022; pp. 1161–1166. [Google Scholar]
  52. Yencha, C. Spatial heterogeneity and non-fungible token sales: Evidence from Decentraland LAND sales. Financ. Res. Lett. 2023, 58, 103628. [Google Scholar] [CrossRef] [Scilit]
  53. Goldberg, M.; Kugler, P.; Schär, F. Land valuation in the metaverse: Location matters. J. Econ. Geogr. 2021, 24, 729–758. [Google Scholar] [CrossRef] [Scilit]
  54. Pierro, G.A.; Sawaf, M.; Tonelli, R. Original or Fake? How to Understand the Digital Artworks’ Value in the Blockchain. In Proceedings of the Software Engineering and Formal Methods. SEFM 2021 Collocated Workshops: CIFMA, CoSim-CPS, OpenCERT, ASYDE, Virtual, 6–10 December 2021; Revised Selected Papers. Springer: Berlin/Heidelberg, Germany, 2022; pp. 76–85. [Google Scholar]
  55. Kong, D.R.; Lin, T.C. Alternative investments in the Fintech era: The risk and return of Non-Fungible Token (NFT). Available online: https://ssrn.com/abstract=3914085 (accessed on 1 December 2025).
  56. Umar, Z.; Abrar, A.; Zaremba, A.; Teplova, T.; Vo, X.V. The return and volatility connectedness of NFT segments and media coverage: Fresh evidence based on news about the COVID-19 pandemic. Financ. Res. Lett. 2022, 49, 103031. [Google Scholar] [CrossRef] [Scilit]
  57. Dowling, M. Is non-fungible token pricing driven by cryptocurrencies? Financ. Res. Lett. 2022, 44, 102097. [Google Scholar] [CrossRef] [Scilit]
  58. Apostu, S.A.; Panait, M.; Vasa, L.; Mihaescu, C.; Dobrowolski, Z. NFTs and Cryptocurrencies—The Metamorphosis of the Economy under the Sign of Blockchain: A Time Series Approach. Mathematics 2022, 10, 3218. [Google Scholar] [CrossRef] [Scilit]
  59. Boido, C.; Aliano, M. Digital art and non-fungible-token: Bubble or revolution? Financ. Res. Lett. 2022, 52, 103380. [Google Scholar] [CrossRef] [Scilit]
  60. Umar, Z.; Gubareva, M.; Teplova, T.; Tran, D.K. Covid-19 impact on NFTs and major asset classes interrelations: Insights from the wavelet coherence analysis. Financ. Res. Lett. 2022, 47, 102725. [Google Scholar] [CrossRef] [Scilit]
  61. Borri, N.; Liu, Y.; Tsyvinski, A. The economics of non-fungible tokens. SSRN Electron. J. 2022. [Google Scholar] [CrossRef] [Scilit]
  62. Nakavachara, V.; Saengchote, K. Does unit of account affect willingness to pay? Evidence from metaverse LAND transactions. Financ. Res. Lett. 2022, 49, 103089. [Google Scholar] [CrossRef] [Scilit]
  63. Belguith, R.; Manzli, Y.S.; Bejaoui, A.; Jeribi, A. Can gold-backed cryptocurrencies have dynamic hedging and safe-haven abilities against DeFi and NFT assets? Digit. Bus. 2024, 4, 100077. [Google Scholar] [CrossRef] [Scilit]
  64. Yousaf, I.; Yarovaya, L. The relationship between trading volume, volatility and returns of non-fungible tokens: Evidence from a quantile approach. Financ. Res. Lett. 2022, 50, 103175. [Google Scholar] [CrossRef] [Scilit]
  65. Panagiotidis, T.; Papapanagiotou, G. A note on the determinants of non-fungible tokens returns. Int. J. Financ. Econ. 2024, 30, 3201–3211. [Google Scholar] [CrossRef] [Scilit]
  66. Ko, H.; Son, B.; Lee, Y.; Jang, H.; Lee, J. The economic value of NFT: Evidence from a portfolio analysis using mean–variance framework. Financ. Res. Lett. 2022, 47, 102784. [Google Scholar] [CrossRef] [Scilit]
  67. Urom, C.; Ndubuisi, G.; Guesmi, K. Dynamic dependence and predictability between volume and return of Non-Fungible Tokens (NFTs): The roles of market factors and geopolitical risks. Financ. Res. Lett. 2022, 50, 103188. [Google Scholar] [CrossRef] [Scilit]
  68. Gunay, S.; Kaskaloglu, K. Does utilizing smart contracts induce a financial connectedness between Ethereum and non-fungible tokens? Res. Int. Bus. Financ. 2022, 63, 101773. [Google Scholar] [CrossRef] [Scilit]
  69. Alizadeh, S.; Setayesh, A.; Mohamadpour, A.; Bahrak, B. A network analysis of the non-fungible token (NFT) market: Structural characteristics, evolution, and interactions. Appl. Netw. Sci. 2023, 8, 38. [Google Scholar] [CrossRef] [Scilit]
  70. Alon, I.; Bretas, V.P.; Katrih, V. Predictors of NFT prices: An automated machine learning approach. J. Glob. Inf. Manag. (JGIM) 2023, 31, 1–18. [Google Scholar] [CrossRef] [Scilit]
  71. Cepni, O.; Aysan, A.F. Coin Specific Sentiments Matter For The Non-Fungible Tokens Spillovers: How And When? Bull. Monet. Econ. Bank. 2023, 26, 637–658. [Google Scholar] [CrossRef] [Scilit]
  72. Christopher Westland, J. Periodicity, Elliott waves, and fractals in the NFT market. Sci. Rep. 2024, 14, 4480. [Google Scholar] [CrossRef] [Scilit]
  73. Ho, K.H.; Law, M.; Hou, Y.; Chan, T.T. Spillover analysis on NFTs, NFT-affiliated tokens and NFT submarkets. Financ. Res. Lett. 2024, 60, 104598. [Google Scholar] [CrossRef] [Scilit]
  74. Kapoor, A.; Guhathakurta, D.; Mathur, M.; Yadav, R.; Gupta, M.; Kumaraguru, P. Tweetboost: Influence of social media on nft valuation. In Proceedings of the Companion Web Conference 2022, Lyon, France, 25–29 April 2022; pp. 621–629. [Google Scholar]
  75. Kraizberg, E. Non-fungible tokens: A bubble or the end of an era of intellectual property rights. Financ. Innov. 2023, 9, 32. [Google Scholar] [CrossRef] [Scilit]
  76. Luo, J.; Jia, Y.; Liu, X. Understanding NFT Price Moves through Tweets Keywords Analysis. In Proceedings of the 2023 ACM Conference on Information Technology for Social Good, Monterrey, Mexico, 5–7 June 2023; pp. 410–418. [Google Scholar]
  77. Serneels, S. Detecting wash trading for nonfungible tokens. Financ. Res. Lett. 2022, 52, 103374. [Google Scholar] [CrossRef] [Scilit]
  78. Kireyev, P.; Lin, R. Infinite but Rare: Valuation and Pricing in Marketplaces for Blockchain-Based Nonfungible Tokens. 2021. Available online: https://ssrn.com/abstract=3737514 (accessed on 1 December 2025).
  79. Kireyev, P. NFT Marketplace Design and Market Intelligence. 2022. Available online: https://ssrn.com/abstract=4002303 (accessed on 1 December 2025).
  80. Wang, J.N.; Lee, Y.H.; Liu, H.C.; Hsu, Y.T. Dissecting returns of non-fungible tokens (NFTs): Evidence from CryptoPunks. N. Am. J. Econ. Financ. 2023, 65, 101892. [Google Scholar] [CrossRef] [Scilit]
  81. Zou, D.; Gu, M.; Liu, D. When ownership and copyright are separated: Economics of non-fungible token marketplaces with secondary markets. Decis. Support Syst. 2024, 183, 114247. [Google Scholar] [CrossRef] [Scilit]
  82. Zuppinger, G. Get Ready for Decentraland Second Auction! Available online: https://medium.com/nonfungible/get-ready-for-decentraland-second-auction-14ac44494105 (accessed on 8 September 2023).
  83. Yilmaz, M.; Hacaloğlu, T.; Clarke, P. Examining the use of non-fungible tokens (NFTs) as a trading mechanism for the metaverse. In Proceedings of the Systems, Software and Services Process Improvement: 29th European Conference, EuroSPI 2022, Salzburg, Austria, 31 August–2 September 2022; Springer: Berlin/Heidelberg, Germany, 2022; pp. 18–28. [Google Scholar]
  84. Chen, H.; Cheng, Y.; Deng, X.; Huang, W.; Rong, L. Absnft: Securitization and repurchase scheme for non-fungible tokens based on game theoretical analysis. In Proceedings of the Financial Cryptography and Data Security: 26th International Conference, FC 2022, St. George’s, Grenada, 2–6 May 2022; Revised Selected Papers. Springer: Berlin/Heidelberg, Germany, 2022; pp. 407–425. [Google Scholar]
  85. Das, D.; Bose, P.; Ruaro, N.; Kruegel, C.; Vigna, G. Understanding security issues in the NFT ecosystem. In Proceedings of the 2022 ACM SIGSAC Conference on Computer and Communications Security, Los Angeles, CA, USA, 7–11 November 2022; pp. 667–681. [Google Scholar]
  86. Dowling, M. Fertile LAND: Pricing non-fungible tokens. Financ. Res. Lett. 2022, 44, 102096. [Google Scholar] [CrossRef] [Scilit]
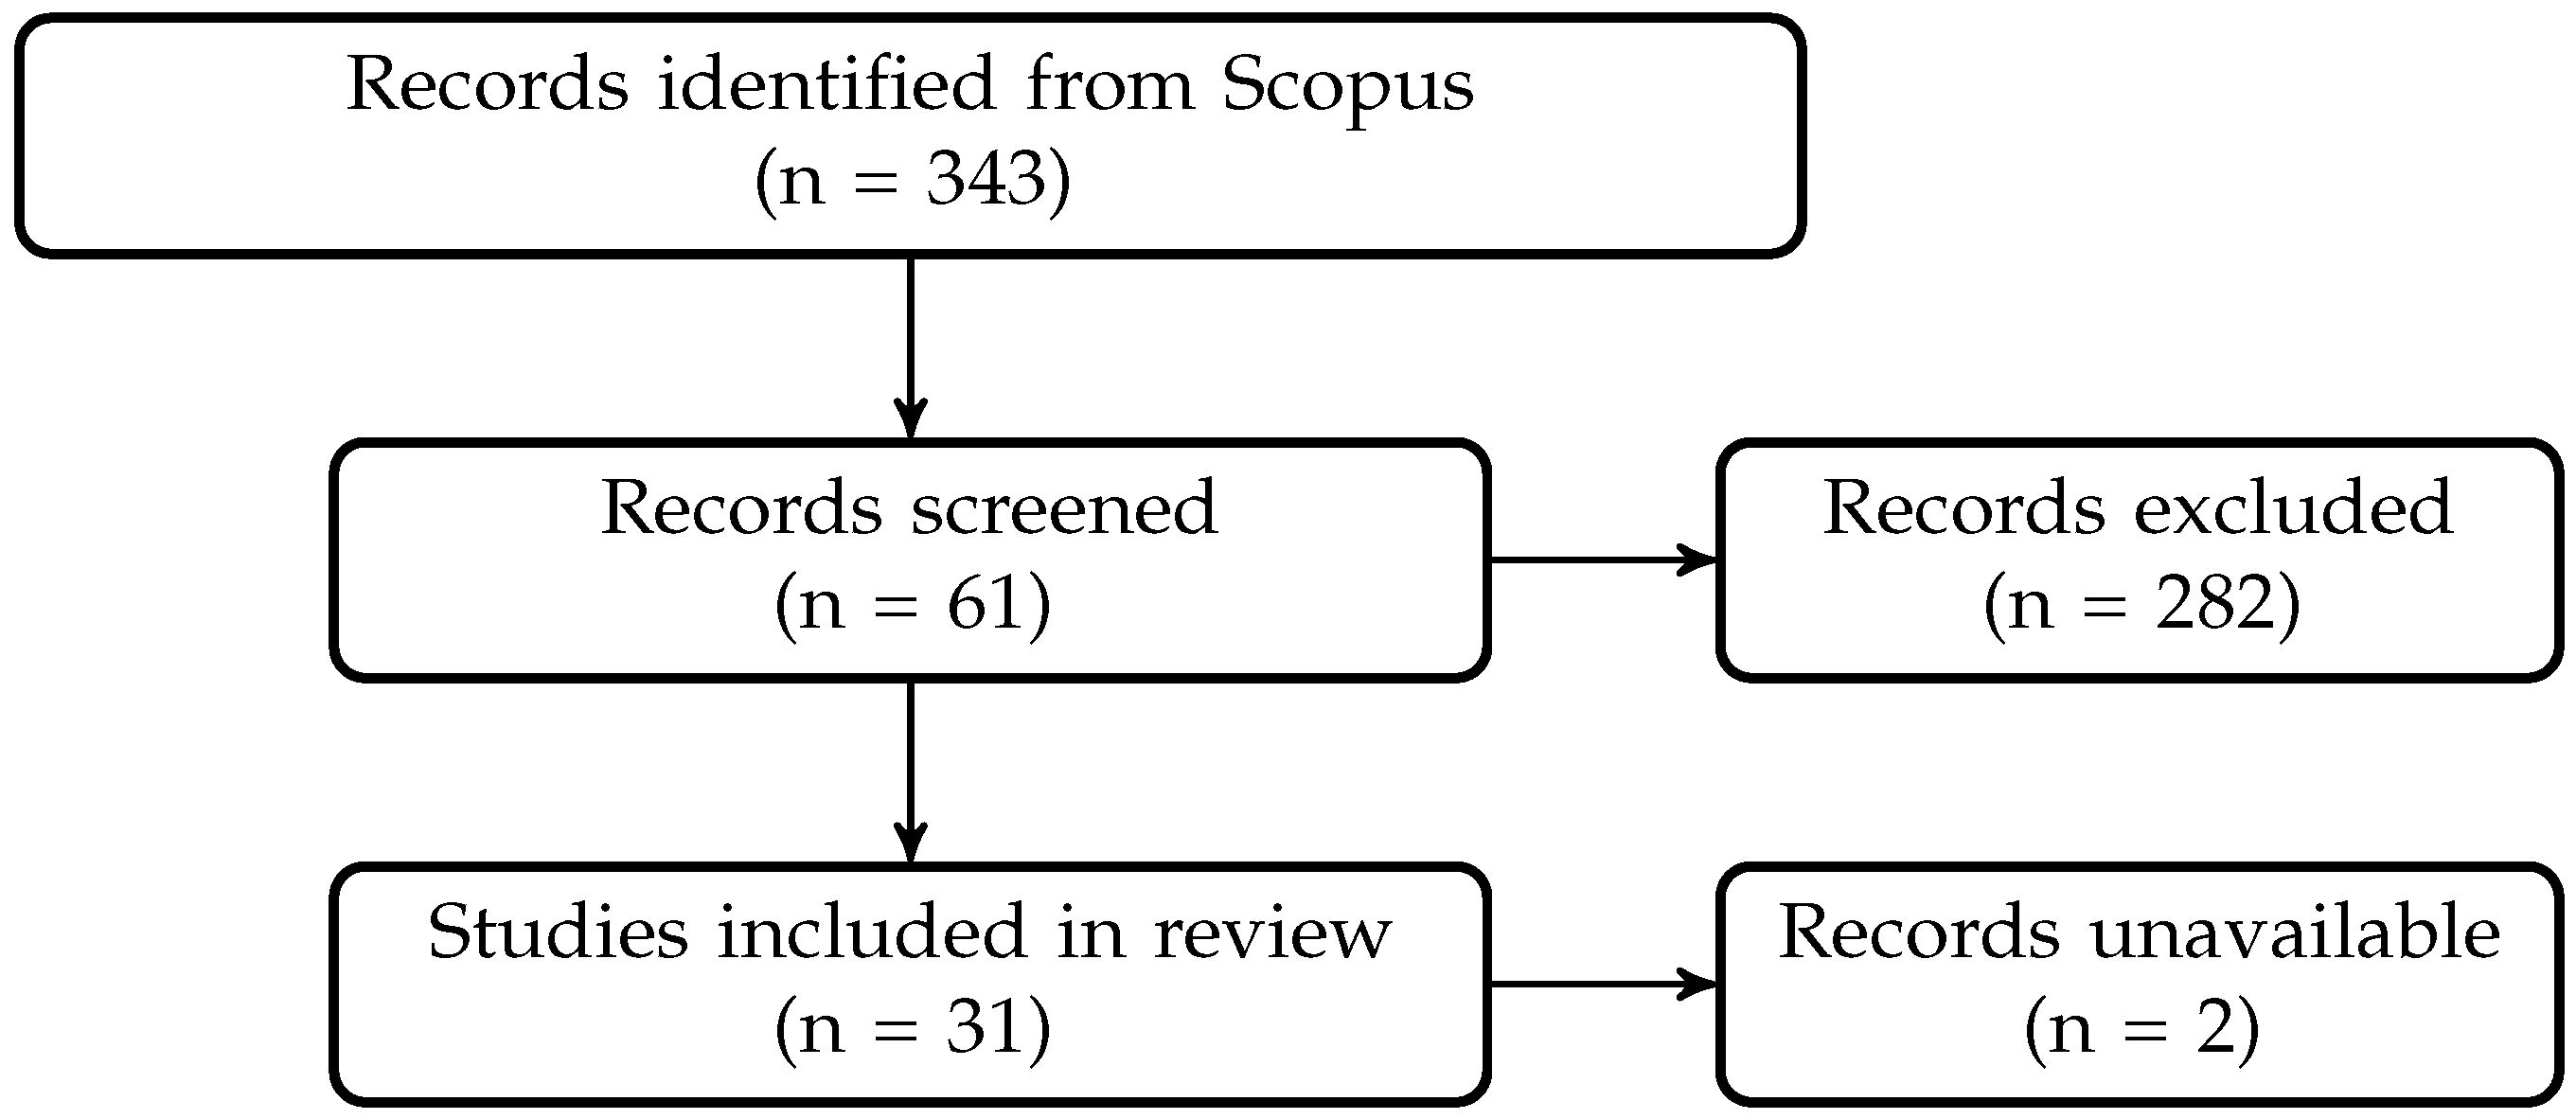
Figure 1. Systematic search flowchart.
Fintech 04 00073 g001
Figure 2. Factors influencing NFT price.
Fintech 04 00073 g002
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.