Green Accounting

1
Department of Business Administration and Tourism, Hellenic Mediterranean University, 714 10 Iraklio, Greece
2
Department of Economics and Business, Neapolis University Pafos, Pafos 8042, Cyprus
Encyclopedia 2026, 6(9), 186; https://doi.org/10.3390/encyclopedia6090186
Submission received: 17 July 2026
/
Revised: 8 August 2026
/
Accepted: 21 August 2026
/
Published: 28 August 2026
(This article belongs to the Section Social Sciences)
Definition
Green accounting is an extension of conventional accounting that incorporates environmental considerations into economic measurement and reporting. It examines the relationships between economic activity and the natural environment by identifying environmental costs, resource use, ecological impacts and related responsibilities. Green accounting may be applied within organisations to support management and reporting or at the national level to assess how economic development affects natural resources and environmental quality. Its main purpose is to provide a broader understanding of performance by showing that economic value cannot be evaluated independently of environmental sustainability. In this way, it supports more responsible decision-making, greater accountability and long-term planning.
1. Historical Development
Green accounting did not emerge as a single, clearly defined accounting method. It developed gradually as governments, organisations, economists and accounting professionals recognised that conventional economic measures provided an incomplete picture of development. Traditional accounting concentrated on financial transactions and economic performance, while natural-resource use and the environmental consequences of production were often treated as external to the accounting system. As industrial activity expanded, pollution, resource depletion and ecological deterioration made that separation increasingly difficult to sustain [1,2,3].
Environmental concerns gained greater international attention during the 1960s and 1970s. Rapid industrialisation and economic growth created benefits for many societies, but they also produced visible environmental pressures, including air and water pollution, increasing volumes of waste, deforestation and the intensive use of energy and raw materials. The United Nations Conference on the Human Environment, held in Stockholm in 1972, was an important milestone because it placed environmental protection on the international political agenda and emphasised the relationship between environmental quality and economic development [4].
During this early period, economists and policymakers began to question whether indicators such as gross domestic product could adequately represent social progress. Economic output could increase even while forests, minerals, water resources and other natural assets were being depleted. Expenditure undertaken to repair environmental damage could also increase measured economic activity even though it reflected a loss of environmental quality. These limitations encouraged the search for accounting approaches that could connect economic performance with changes in the natural environment [5].
A major conceptual development occurred in 1987 with the publication of Our Common Future by the World Commission on Environment and Development. The report established sustainable development as an influential international principle and argued that present needs should be met without compromising the ability of future generations to meet their own needs. This understanding strengthened the view that economic decisions should consider their long-term environmental consequences. It also encouraged the development of measurement systems capable of assessing whether economic growth was being achieved at the expense of natural resources or ecological stability [6].
The United Nations Conference on Environment and Development, held in Rio de Janeiro in 1992, provided further momentum. Agenda 21 called for environmental and developmental considerations to be integrated into decision-making and specifically encouraged systems that combine environmental and economic accounting. This represented an important shift from treating environmental information as a separate collection of statistics towards incorporating it into established systems of economic measurement [7].
In response to these developments, the United Nations published the first Handbook of National Accounting: Integrated Environmental and Economic Accounting in 1993. This framework later became known as the System of Environmental-Economic Accounting (SEEA). It was designed to extend conventional national accounts by including information about natural-resource stocks, environmental flows, resource depletion and environmental protection expenditure. A revised and more comprehensive version was issued in 2003, reflecting growing international experience with environmental–economic accounts. The framework enabled governments to examine how economic activities depended on natural resources and how those activities affected the condition of the environment [8,9].
At the organisational level, the development of green accounting followed a related but distinct path. During the 1980s and 1990s, companies faced stronger environmental regulation and increasing public concern about corporate environmental conduct. Many organisations began to disclose information about pollution control, environmental expenditure, waste management and compliance with environmental legislation. At first, these disclosures were often limited and largely voluntary. Nevertheless, they contributed to recognition that environmental matters could create financial costs, legal responsibilities, operational risks and reputational consequences [1,2].
Environmental management accounting subsequently developed as a means of improving internal decision-making. It sought to identify environmental costs that were frequently hidden within general production and administrative expenses. It also combined monetary information with physical information concerning flows of energy, water, materials and waste. The United Nations published guidance on environmental management accounting in 2001, and the International Federation of Accountants issued an international guidance document in 2005. These initiatives helped establish environmental management accounting as a practical approach to resource efficiency, cost control, investment appraisal and pollution prevention [10,11].
The expansion of corporate sustainability reporting also influenced the development of green accounting. The Global Reporting Initiative (GRI) was established in 1997 with the initial objective of promoting more consistent corporate environmental disclosure. Its scope later expanded to include wider economic, social and governance impacts. As sustainability reporting became more common, organisations were increasingly expected to explain not only their financial performance but also their use of natural resources and their effects on the environment [12].
A further milestone was reached in 2012 when the United Nations Statistical Commission adopted the SEEA Central Framework as an international statistical standard. The framework provided internationally agreed concepts for connecting environmental data with economic information and supported the preparation of comparable accounts relating to energy, water, materials, emissions, environmental expenditure and natural resources. In March 2021, the Commission adopted SEEA Ecosystem Accounting, which broadened this work by examining the extent and condition of ecosystems, the services they provide and their relationship with economic and human activity [13,14].
In the contemporary period, green accounting has continued to evolve in response to climate change, biodiversity loss, resource scarcity and demands for greater organisational accountability. Carbon accounting, natural capital accounting and sustainability-related financial reporting have become increasingly prominent. Modern green accounting therefore reflects the convergence of several earlier developments, including environmental economics, national environmental accounts, corporate environmental reporting and environmental management accounting. Although no single framework captures every environmental effect, the history of green accounting demonstrates a continuing effort to make the environmental consequences of economic activity more visible within measurement, reporting and decision-making systems.
2. Forms of Green Accounting
Green accounting appears in several forms, depending on the level at which it is applied and the purpose it serves. At the organisational level, it may support internal management or external reporting. At the national level, it is used to examine the relationship between economic activity and the condition of natural resources [2,13].
2.1. Conceptual Boundaries
In this entry, green accounting is used as an umbrella term for accounting practices that make environmental dependencies, impacts, costs and obligations visible. Environmental accounting refers mainly to organisational accounting, including financial and management uses. Environmental–economic accounting refers to macro-statistical accounts that integrate environmental and economic data for a country or region. Sustainability reporting is broader: it communicates an organisation’s material impacts, risks and opportunities to external users and may include social and governance matters as well as environmental information. The distinctions therefore rest primarily on the reporting boundary and user, while the unit of account—monetary, physical or narrative—clarifies the measurement approach [2,3,12,13,14].
2.2. Main Forms
Environmental financial accounting focuses on the recognition and disclosure of environmental matters in financial statements. It covers items such as restoration obligations, pollution-control equipment, environmental provisions and costs arising from legal compliance. Its purpose is to show how environmental matters affect the financial position and performance of an organisation. Under IAS 37, for example, a provision is recognised when a present obligation arising from a past event is expected to require a probable outflow of resources and can be estimated reliably [15].
Environmental management accounting is used internally. It provides managers with information about the use of materials and energy as well as the costs associated with waste and inefficient production. By linking physical data with monetary data, it helps identify where resources are being lost and where operating processes can be improved [10,11].
Material flow cost accounting is a more specific approach within environmental management accounting. It traces the movement of materials through production and assigns costs to both finished output and material losses. This method can reveal the full economic consequences of inefficient material use that remain hidden in conventional accounting systems [16].
Carbon accounting concentrates on greenhouse gas emissions. Under the GHG Protocol, Scope 1 comprises direct emissions from sources owned or controlled by the organisation; Scope 2 covers indirect emissions from purchased energy; and Scope 3 covers other indirect emissions across the value chain. Carbon accounts support emission reduction targets, climate-related reporting and assessment of exposure to carbon regulation [17,18].
At the national level, environmental–economic accounting extends conventional national accounts by including information about natural resources and environmental change. It may record depletion of forests, water, minerals and other natural assets, measure environmental expenditure and represent physical flows between the economy and the environment [13].
These forms are related, but they do not serve the same purpose. Some are designed for financial reporting, while others support operational decisions, broad stakeholder accountability or public policy. Their common feature is the effort to make environmental dependencies and effects visible within structured information systems. Table 1 summarises their principal differences.
3. Environmental Measurement and Valuation
Environmental measurement in green accounting begins with defining the accounting boundary. The boundary may refer to a specific plant or facility, a production process, a product, an organisation, a value chain or a national territory. This choice determines which environmental inputs and outputs are included and prevents results from becoming inconsistent or misleading [13,17,18].
The next step is the collection of physical data. Electricity is usually measured in kilowatt-hours, water in cubic metres, materials in tonnes and greenhouse gas emissions in tonnes of carbon dioxide equivalent. These data may come from utility meters, production records, purchasing documents, waste transfer records or technical calculations. The quality of the final accounting information depends directly on the reliability of these measurements.
Physical data must then be linked to the activity that caused them. Attribution is straightforward when a process has its own meter or record. It becomes more difficult when several departments share the same energy supply or waste treatment system. In such cases, the organisation must use an allocation method that reflects actual consumption as closely as possible and apply that method consistently across reporting periods.
Monetary valuation translates physical information into accounting amounts. When a market price exists, the quantity consumed or lost can be multiplied by the relevant purchase price or treatment cost. This procedure is commonly applied to energy, water, raw materials and waste disposal. The value of discarded material should include not only the disposal charge but also the purchasing and processing costs already absorbed before the material became waste [16].
Some environmental effects cannot be valued through direct market prices. In these cases, other methods may be used. Restoration cost estimates the expenditure required to return a damaged site to an acceptable condition. Replacement cost measures the amount needed to substitute for a depleted or damaged environmental asset. Avoided-cost valuation estimates the future expenditure prevented by environmental action. The selected method should match the purpose of the account, and its assumptions and limitations should be explained clearly [14].
After valuation, an amount must be classified according to its accounting treatment. Environmental expenditure related to current operations is normally recognised as an expense. Expenditure that creates a future economic benefit may be recorded as an asset under the applicable recognition requirements. A present obligation for environmental restoration may require recognition of a provision when the IAS 37 criteria are met; when a possible obligation does not meet those criteria, disclosure as a contingent liability may instead be required [15].
The measurement and valuation process therefore converts environmental effects into information that can enter an accounting system. Figure 1 presents the sequence from identifying an environmental activity to recognising and reporting the resulting amount. Once these steps are complete, the resulting information can be connected to specific corporate and public policy decisions, as illustrated in Section 4.
4. Corporate and National Applications
Green accounting is applied when environmental information is connected to a specific management or policy decision. Corporate applications may influence procurement, investment and internal budgets. National applications provide evidence for managing natural resources and appraising public policy.
Kering provides a prominent corporate example through its Environmental Profit and Loss (EP&L) account. The company published its first group-level accounts in 2015, covering the environmental effects of its operations and supply chain. The account converts these effects into monetary values so that they can be examined alongside conventional business information. Its scope extends from raw material production to manufacturing and distribution and also considers product use and end-of-life impacts. The group-level method built on PUMA’s pioneering 2011 EP&L exercise [24,25].
The results showed Kering that a substantial part of its environmental burden arose before products reached its own facilities. This finding directed attention towards raw material production and sourcing. The company has used the account to support the selection of lower-impact materials and the development of environmental standards for suppliers. In this case, green accounting is not limited to reporting past performance; it informs purchasing decisions at the stage where much of the environmental effect is created [24].
Microsoft demonstrates a different application through its internal carbon fee. Since 2012, the company has calculated emissions associated with its business activities and charged the responsible business groups. The programme initially covered Scope 1 and Scope 2 emissions and business air travel. In 2020, Microsoft began charging business groups for all Scope 3 emissions [26].
The internal fee gives carbon emissions a financial consequence within the organisation. A business group that generates more emissions bears a higher internal charge. The funds collected support carbon-reduction and carbon-removal activities. This practice places responsibility within operational budgets rather than treating emissions solely as a matter for the sustainability department. It also allows managers to consider carbon consequences when planning travel, procurement and other activities [26].
At the national level, the United Kingdom applies green accounting through natural capital accounts produced by the Office for National Statistics (ONS). These accounts estimate habitat extent and condition, physical flows and the annual and asset values of selected services. The services include provisioning services such as food and water, regulating services such as pollution removal and cultural services such as recreation [27].
The 2025 UK Natural Capital Accounts estimated the total asset value of UK natural capital in 2023 at approximately GBP 1.6 trillion. This figure represents the expected value of the future stream of selected services generated by natural assets; it is a partial valuation rather than an estimate of nature’s intrinsic or total value. It is not included in gross domestic product because GDP measures current economic activity rather than the condition of the assets supporting that activity [27].
The accounts have a practical role in public sector analysis. The United Kingdom’s natural capital guidance assists government economists and public organisations in considering environmental effects when appraising policies and projects. A proposed flood-management project, for instance, can be assessed not only through its construction cost but also through its effects on habitats and the protection provided by natural systems.
Australia provides another national illustration through the Water Account prepared by the Australian Bureau of Statistics (ABS). The account connects the physical movement of water with monetary transactions in the economy. It shows how water is extracted and distributed and attributes its use to industries and households. The account follows the System of Environmental-Economic Accounting so that its information can be compared with established economic statistics [28].
For the 2023–2024 financial year, the Australian account recorded the extraction of 58,447 gigalitres of water from the environment. Of the 12,496 gigalitres extracted for distribution, 10,635 gigalitres were supplied to industries, including distribution losses and the water industry’s own use, and 1861 gigalitres were supplied to households. This information helps analysts examine which economic activities depend most heavily on water and how changes in availability may affect them. It is especially relevant in Australia because agricultural production and urban supply are exposed to substantial variation in rainfall and water storage [28].
These cases demonstrate that the application of green accounting depends on the decision being addressed. Kering uses it to examine environmental pressures within its supply chain. Microsoft applies it through internal financial responsibility for emissions. The United Kingdom uses natural capital accounts to represent environmental assets in policy analysis. Australia connects water use with the industries and households that depend on it.
In practice, these applications show why green accounting matters beyond descriptive reporting. It converts environmental dependencies, impacts and risks into information that can guide capital budgeting, procurement, product design and risk management. The same information can support sustainable finance assessments, ESG reporting and climate-related disclosures by linking physical indicators and monetary effects to governance and strategy. When integrated with scenario analysis and internal controls, green accounting can also strengthen organisational resilience by identifying exposure to resource scarcity, carbon costs, regulatory change and supply chain disruption [17,18,19,20,24,25,26,27,28]. These benefits must nevertheless be evaluated alongside the implementation and regulatory challenges discussed in Section 5.
5. Challenges in the Application of Green Accounting
5.1. Practical and Regulatory Challenges
The application of green accounting is complicated by the absence of a single accounting framework that applies in the same way to every organisation and jurisdiction. Environmental information may be prepared for internal management, statutory reporting, investment analysis or national economic accounts. Each purpose can require a different reporting boundary and method. An organisation may therefore produce several environmental calculations that are valid for their intended uses but cannot be combined without adjustment.
Legal requirements create a further challenge because they continue to evolve. In the European Union, the Corporate Sustainability Reporting Directive established mandatory sustainability reporting for undertakings within its scope. Directive (EU) 2025/794 postponed the second and third application waves by two years, to financial years starting on or after 1 January 2027 and 1 January 2028, respectively. Directive (EU) 2026/470 subsequently limited the core scope, for financial years starting on or after 1 January 2027, to undertakings exceeding both EUR 450 million in net turnover and an average of more than 1000 employees, subject to its detailed provisions; it also permits Member States to exempt certain undertakings outside the revised scope for financial years starting in 2025 and 2026 [29,30,31]. These changes illustrate the difficulty of designing accounting systems while legal scope and reporting obligations are developing.
The European Sustainability Reporting Standards (ESRS) require companies to determine which sustainability matters are material before selecting the information to disclose. Double materiality has two interrelated dimensions. Impact materiality concerns an undertaking’s actual or potential positive and negative impacts on people or the environment. Financial materiality concerns sustainability-related risks or opportunities that may affect cash flows, access to finance or the cost of capital. A matter is material if it meets the criteria for either dimension or both. A weak assessment may omit an important environmental effect, whereas an overbroad assessment may produce a report that is difficult to understand [32].
Information from the value chain is particularly difficult to obtain. A reporting company may depend on environmental data from suppliers that use different systems or do not collect the requested information, and the problem becomes greater when a supply chain extends across several countries. Directive (EU) 2026/470 introduced protections for value chain undertakings with no more than 1000 employees by limiting the sustainability information that reporting undertakings may demand from them. It also permits reporting undertakings to use estimates where necessary value chain information is unavailable after the applicable transition arrangements [31].
The EU Taxonomy Regulation presents a different practical issue. It establishes common criteria for determining whether an economic activity qualifies as environmentally sustainable. A company must examine whether an activity contributes substantially to at least one environmental objective, does no significant harm to the others, complies with minimum safeguards and satisfies applicable technical screening criteria. Classification may be difficult when an activity spans several business functions or when available records were not designed to provide the technical evidence required. The accounting system must therefore connect financial amounts with technical information concerning the activity [33].
Multinational organisations may also have to reconcile European requirements with the IFRS Sustainability Disclosure Standards. IFRS S1 and IFRS S2 were issued by the International Sustainability Standards Board in June 2023 and are effective for annual reporting periods beginning on or after 1 January 2024, with earlier application permitted if both standards are applied [19,20]. Their legal use depends on adoption or other action by individual jurisdictions. Interoperability efforts can reduce duplication, but differences in objectives and materiality perspectives may still require additional mapping and reconciliation [19,20,32].
Assurance creates another implementation challenge. Environmental information often originates outside the financial ledger and may be drawn from meters, engineering models, suppliers, questionnaires or scientific estimates. The organisation must preserve evidence showing how each reported amount was calculated and who approved the method. Directive (EU) 2026/470 retains a limited assurance approach and requires the European Commission to adopt limited assurance standards by 1 July 2027 [31].
National green accounting faces related problems. Regulation (EU) No 691/2011 establishes a common framework for European environmental–economic accounts. However, the necessary information may be held by separate public bodies responsible for economic statistics, energy, water, agriculture or environmental protection. Preparing a coherent account depends on compatible classifications and regular data exchange between these institutions. Differences in data availability can still affect the detail and timeliness of national accounts even when countries follow the same legal framework [23].
The treatment of estimates remains a persistent concern. Environmental liabilities may depend on future restoration work, while contingent values may rely on assumptions that cannot be verified through an observable market price. Two organisations can apply reasonable assumptions and still produce different results. Green accounting must therefore distinguish measured information from estimated information and explain the basis of significant assumptions.
Implementation can also be costly. Larger organisations may install dedicated software and employ specialist staff, while smaller entities may rely on spreadsheets and external advisers. A system that demands more information than management can verify may create an appearance of precision without sufficient reliability. The reporting process should therefore reflect the scale of the organisation and the significance of its environmental effects.
Compliance with legislation does not itself guarantee meaningful green accounting. A report may satisfy formal disclosure requirements while presenting environmental performance selectively. Reliable application requires consistent boundaries, transparent estimation methods and explanations of changes in methodology so that users can distinguish genuine environmental progress from changes in calculation.
5.2. Monetisation, Commensurability and Legitimation
Monetary valuation can place material losses, restoration obligations and ecosystem services into a familiar decision frame, but it is neither neutral nor comprehensive. Hines’s insight that accounting representations help construct the reality they describe applies directly: the selection of boundaries, prices and discount rates can make some environmental effects visible while excluding others [34]. Schaltegger and Burritt and Bebbington and Larrinaga therefore treat environmental and sustainability accounting as a plural set of practices rather than a single monetary calculus [2,3].
Commensurability is contested because ecological integrity, cultural significance and irreversible harm may not be meaningfully reducible to a single currency metric. Monetary estimates can still support particular decisions if their purpose, assumptions, uncertainty and omissions are disclosed and if physical indicators and qualitative evidence remain alongside them. Treating a partial valuation as nature’s total value would be misleading [14,27,35].
A further legitimation critique is that polished environmental accounts may normalise business as usual or confer credibility without demonstrating ecological sufficiency. Gray and Milne argue that reporting systems can privilege organisationally manageable indicators over the conditions needed to sustain ecological systems [1,36]. Green accounting should therefore be judged not only by compliance or internal consistency but also by whether it changes decisions, exposes trade-offs and remains accountable to affected stakeholders.
6. Conclusions
Green accounting expands the capacity of accounting to represent the environmental consequences of economic activity. Its importance lies not in replacing conventional financial accounting but in supplying information that conventional records do not always make visible. By connecting financial information with evidence about resource use and environmental effects, it supports a more complete assessment of organisational and economic performance.
Its application differs according to purpose. Within organisations, green accounting can improve cost allocation, strengthen investment decisions, support environmental reporting and inform the recognition of environmental obligations. At the national level, environmental–economic accounts provide governments with information about the condition of natural resources and the environmental pressures associated with economic activity. These applications show that green accounting is not a single method but a group of related accounting practices designed for different users and decisions.
The usefulness of green accounting depends on the quality of the information on which it is based. Physical measurements must be reliable, valuation methods must be explained and reporting boundaries must remain consistent. Difficulties become greater when environmental effects occur across a supply chain or when natural assets do not have observable market prices. Legal requirements can improve consistency, but differences between national rules and reporting standards continue to create implementation challenges.
Green accounting should therefore be treated as a set of accounting processes rather than as a collection of environmental indicators. Its contribution becomes meaningful when environmental information is integrated into established systems of control, measurement and decision-making. Sustainability reporting is a related but broader practice: it may draw on green accounting data while also communicating social and governance impacts, risks and opportunities. As environmental regulation develops and demand for credible sustainability information increases, green accounting is likely to become more closely connected with financial management, external reporting and public policy. Its continued development will depend on transparent methods, professional judgement, plural forms of evidence and cooperation between accounting specialists and environmental experts.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
No new data were created or analysed in this study. Data sharing is not applicable to this article.
Conflicts of Interest
The author declares no conflicts of interest.
References
- Gray, R. Accounting and environmentalism: An exploration of the challenge of gently accounting for accountability, transparency and sustainability. Account. Organ. Soc. 1992, 17, 399–425. [Google Scholar] [CrossRef] [Scilit]
- Schaltegger, S.; Burritt, R. Contemporary Environmental Accounting: Issues, Concepts and Practice; Greenleaf Publishing: Sheffield, UK, 2000. [Google Scholar]
- Bebbington, J.; Larrinaga, C. Accounting and sustainable development: An exploration. Account. Organ. Soc. 2014, 39, 395–413. [Google Scholar] [CrossRef] [Scilit]
- United Nations. Report of the United Nations Conference on the Human Environment, Stockholm, 5–16 June 1972; A/CONF.48/14/Rev.1; United Nations: New York, NY, USA, 1973. [Google Scholar]
- Stiglitz, J.E.; Sen, A.; Fitoussi, J.-P. Report by the Commission on the Measurement of Economic Performance and Social Progress; Commission on the Measurement of Economic Performance and Social Progress. Available online: https://ec.europa.eu/eurostat/documents/8131721/8131772/Stiglitz-Sen-Fitoussi-Commission-report.pdf (accessed on 8 August 2026).
- World Commission on Environment and Development. Our Common Future; Oxford University Press: Oxford, UK, 1987. [Google Scholar]
- United Nations. Report of the United Nations Conference on Environment and Development, Rio de Janeiro, 3–14 June 1992, Volume I: Resolutions Adopted by the Conference; A/CONF.151/26/Rev.1 (Vol. I); United Nations: New York, NY, USA, 1993. [Google Scholar]
- United Nations. Handbook of National Accounting: Integrated Environmental and Economic Accounting—Interim Version; Studies in Methods, Series F, No. 61; United Nations: New York, NY, USA, 1993. [Google Scholar]
- United Nations; European Commission; International Monetary Fund; Organisation for Economic Co-Operation and Development; World Bank. Handbook of National Accounting: Integrated Environmental and Economic Accounting 2003; Studies in Methods, Series F, No. 61, Rev. 1; United Nations: New York, NY, USA, 2003. [Google Scholar]
- United Nations Division for Sustainable Development. Environmental Management Accounting: Procedures and Principles; United Nations: New York, NY, USA, 2001. [Google Scholar]
- International Federation of Accountants. International Guidance Document: Environmental Management Accounting; IFAC: New York, NY, USA, 2005. [Google Scholar]
- Global Reporting Initiative. Who We Are. Available online: https://www.globalreporting.org/about-gri/who-we-are/ (accessed on 16 July 2026).
- United Nations; European Union; Food and Agriculture Organization of the United Nations; International Monetary Fund; Organisation for Economic Co-Operation and Development; World Bank. System of Environmental-Economic Accounting 2012—Central Framework; United Nations: New York, NY, USA, 2014. [Google Scholar]
- United Nations; European Union; Food and Agriculture Organization of the United Nations; International Monetary Fund; Organisation for Economic Co-Operation and Development; World Bank. System of Environmental-Economic Accounting—Ecosystem Accounting; United Nations: New York, NY, USA, 2021. [Google Scholar]
- International Accounting Standards Board. IAS 37: Provisions, Contingent Liabilities and Contingent Assets. Available online: https://www.ifrs.org/issued-standards/list-of-standards/ias-37-provisions-contingent-liabilities-and-contingent-assets/ (accessed on 8 August 2026).
- ISO 14051:2011; Environmental Management—Material Flow Cost Accounting—General Framework. International Organization for Standardization: Geneva, Switzerland, 2011.
- World Resources Institute; World Business Council for Sustainable Development. The Greenhouse Gas Protocol: A Corporate Accounting and Reporting Standard, revised ed.; WRI: Washington, DC, USA; WBCSD: Geneva, Switzerland, 2004. [Google Scholar]
- World Resources Institute; World Business Council for Sustainable Development. Corporate Value Chain (Scope 3) Accounting and Reporting Standard; WRI: Washington, DC, USA; WBCSD: Geneva, Switzerland, 2011. [Google Scholar]
- IFRS Foundation. IFRS S1 General Requirements for Disclosure of Sustainability-Related Financial Information; IFRS Foundation: London, UK, 2023; Available online: https://www.ifrs.org/issued-standards/ifrs-sustainability-standards-navigator/ifrs-s1-general-requirements.html/content/dam/ifrs/publications/html-standards-issb/english/2026/issued/issbs1/ (accessed on 8 August 2026).
- IFRS Foundation. S2 Climate-Related Disclosures; IFRS Foundation: London, UK, 2023; Available online: https://www.ifrs.org/issued-standards/ifrs-sustainability-standards-navigator/ifrs-s2-climate-related-disclosures.html/content/dam/ifrs/publications/html-standards-issb/english/2026/issued/issbs2/ (accessed on 8 August 2026).
- GRI Standards. Available online: https://www.globalreporting.org/standards/ (accessed on 8 August 2026).
- UNEP Finance Initiative. European Sustainability Reporting Standards (ESRS); UNEP Finance Initiative: Geneva, Switzerland, 2023; Available online: https://www.unepfi.org/impact/interoperability/european-sustainability-reporting-standards-esrs/ (accessed on 8 August 2026).
- European Parliament and Council of the European Union. Regulation (EU) No 691/2011 of 6 July 2011 on European Environmental Economic Accounts. 2011. Available online: https://eur-lex.europa.eu/eli/reg/2011/691/oj/eng (accessed on 16 July 2026).
- Kering. EP&L: Environmental Measurement Tool for Sustainable Luxury. Available online: https://www.kering.com/en/sustainability/measuring-our-impact/our-ep-l/ (accessed on 8 August 2026).
- Kering. PUMA and PPR HOME Announce First Results of Unprecedented Environmental Profit and Loss Account. 15 May 2011. Available online: https://www.kering.com/en/news/puma-ppr-home-announce-first-results-unprecedented-environmental-profit-loss-account/ (accessed on 8 August 2026).
- Microsoft. How Microsoft Is Using an Internal Carbon Fee to Reach Its Carbon Negative Goal. 24 March 2022. Available online: https://www.microsoft.com/en-us/microsoft-cloud/blog/general/2022/03/24/how-microsoft-is-using-an-internal-carbon-fee-to-reach-its-carbon-negative-goal/ (accessed on 8 August 2026).
- Office for National Statistics. UK Natural Capital Accounts: 2025. 5 December 2025. Available online: https://www.ons.gov.uk/economy/environmentalaccounts/bulletins/uknaturalcapitalaccounts/2025 (accessed on 8 August 2026).
- Australian Bureau of Statistics. Water Account, Australia. 11 December 2025. Available online: https://www.abs.gov.au/statistics/environment/environmental-accounts/water-account-australia/latest-release (accessed on 8 August 2026).
- European Parliament and Council of the European Union. Directive (EU) 2022/2464 of 14 December 2022 as Regards Corporate Sustainability Reporting. 2022. Available online: https://eur-lex.europa.eu/eli/dir/2022/2464/oj/eng (accessed on 16 July 2026).
- European Parliament and Council of the European Union. Directive (EU) 2025/794 of 14 April 2025 as Regards the Dates from Which Member States Are to Apply Certain Corporate Sustainability Reporting and Due Diligence Requirements. 2025. Available online: https://eur-lex.europa.eu/eli/dir/2025/794/oj/eng (accessed on 16 July 2026).
- European Parliament and Council of the European Union. Directive (EU) 2026/470 of 24 February 2026 as Regards Certain Corporate Sustainability Reporting Requirements and Certain Corporate Sustainability Due Diligence Requirements. 2026. Available online: https://eur-lex.europa.eu/eli/dir/2026/470/oj/eng (accessed on 16 July 2026).
- European Commission. Commission Delegated Regulation (EU) 2023/2772 of 31 July 2023 Supplementing Directive 2013/34/EU as Regards Sustainability Reporting Standards. 2023. Available online: https://eur-lex.europa.eu/eli/reg_del/2023/2772/oj/eng (accessed on 16 July 2026).
- European Parliament and Council of the European Union. Regulation (EU) 2020/852 of 18 June 2020 on the Establishment of a Framework to Facilitate Sustainable Investment. 2020. Available online: https://eur-lex.europa.eu/eli/reg/2020/852/oj/eng (accessed on 16 July 2026).
- Hines, R.D. Financial accounting: In communicating reality, we construct reality. Account. Organ. Soc. 1988, 13, 251–261. [Google Scholar] [CrossRef] [Scilit]
- Spash, C.L. How much is that ecosystem in the window? The one with the bio-diverse trail. Environ. Values 2008, 17, 259–284. [Google Scholar] [CrossRef] [Scilit]
- Milne, M.J.; Gray, R. W(h)ither ecology? The Triple Bottom Line, the Global Reporting Initiative, and corporate sustainability reporting. J. Bus. Ethics 2013, 118, 13–29. [Google Scholar] [CrossRef] [Scilit]
Figure 1.
Conceptual process framework for environmental measurement and valuation in green accounting. Author’s elaboration.
Figure 1.
Conceptual process framework for environmental measurement and valuation in green accounting. Author’s elaboration.
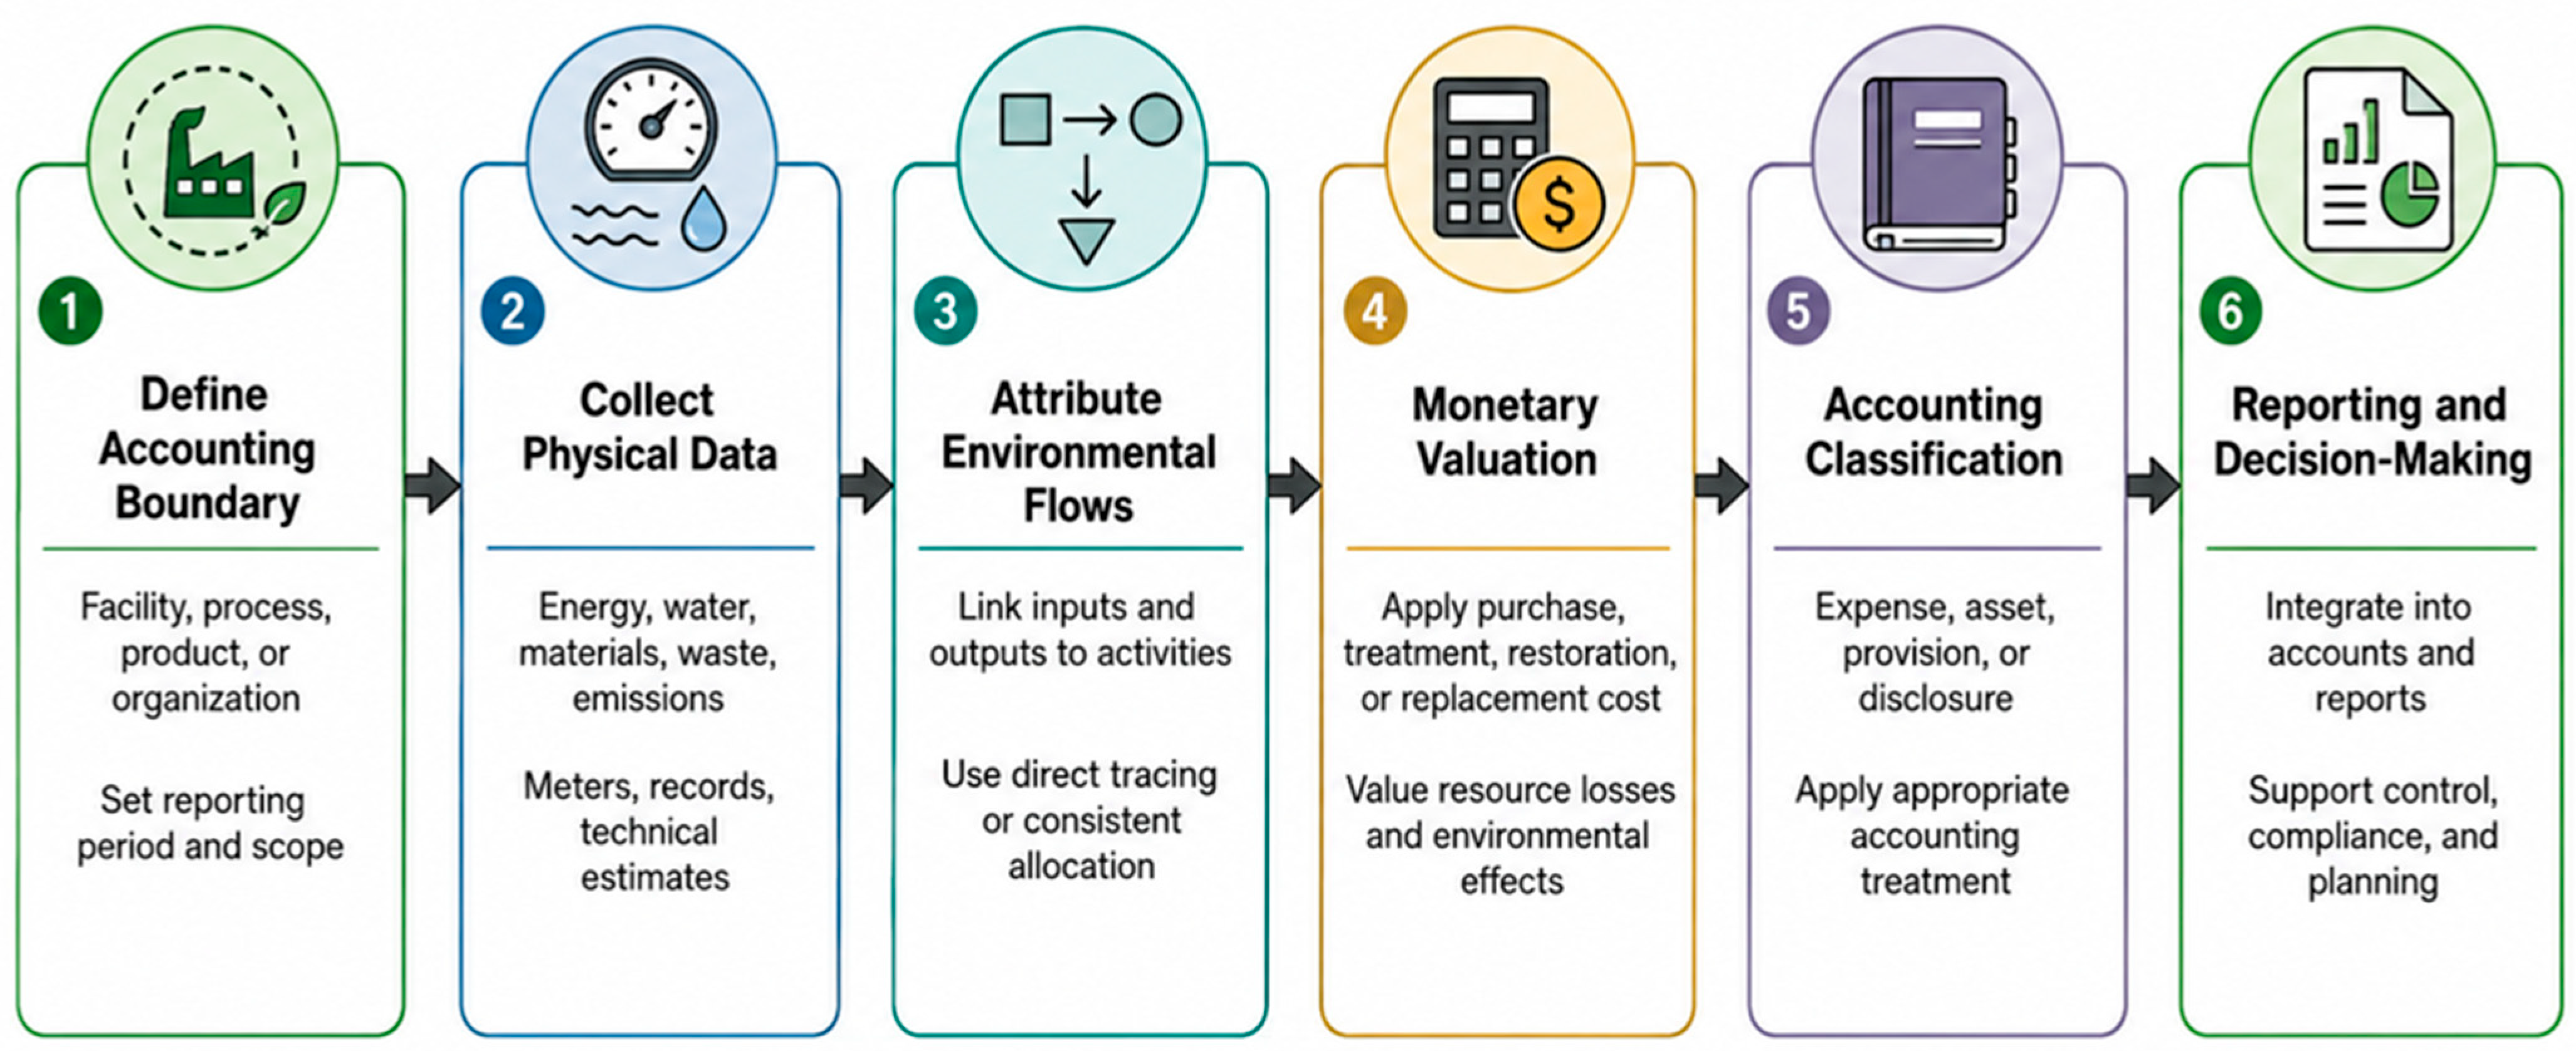

Table 1.
Main forms of green accounting: boundaries, users, units and governing frameworks.
| Form | Level | Primary Users | Unit | Typical Framework |
|---|---|---|---|---|
| Environmental financial accounting | Organisation | Investors, creditors, regulators | Primarily monetary | IFRS or national GAAP; IAS 37 for provisions [15,19,20] |
| Environmental management accounting | Organisation, site or process | Managers and operational teams | Physical and monetary | UN and IFAC EMA guidance; ISO 14051 for MFCA [16] |
| Carbon accounting | Organisation, product or value chain | Managers, investors, regulators | tCO2e; sometimes monetary | GHG Protocol; applicable reporting standards |
| Sustainability reporting | Organisation and value chain | Investors and wider stakeholders | Physical, monetary and narrative | GRI Standards, ESRS, IFRS S1/S2 [19,20,21,22] |
| Environmental–economic accounting | National or subnational economy | Governments, statisticians, policymakers | Physical and monetary | SEEA Central Framework; Regulation (EU) No 691/2011 [23] |
| Ecosystem and natural capital accounting | Ecosystem, landscape or national territory | Governments, communities, organisations | Extent, condition, services and selected monetary values | SEEA Ecosystem Accounting; national methods |
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.
Share and Cite
MDPI and ACS Style
Garefalakis, A. Green Accounting. Encyclopedia 2026, 6, 186. https://doi.org/10.3390/encyclopedia6090186
AMA Style
Garefalakis A. Green Accounting. Encyclopedia. 2026; 6(9):186. https://doi.org/10.3390/encyclopedia6090186
Chicago/Turabian StyleGarefalakis, Alexandros. 2026. "Green Accounting" Encyclopedia 6, no. 9: 186. https://doi.org/10.3390/encyclopedia6090186
APA StyleGarefalakis, A. (2026). Green Accounting. Encyclopedia, 6(9), 186. https://doi.org/10.3390/encyclopedia6090186