Article

On Preliminarily Exploring Multiple-Objective Capital Asset Pricing Models for the Investments of Carbon Offset: Heuristically Proving Different Tangent Planes


1
College of Business Administration, Fujian Business University, 8 Tingjiang Road, Fuzhou 350016, China
2
Department of Financial Management, Business School, Nankai University, 94 Weijin Road, Tianjin 300071, China
*
Author to whom correspondence should be addressed.
Mathematics 2026, 14(17), 3156; https://doi.org/10.3390/math14173156
Submission received: 14 May 2026 / Revised: 19 August 2026 / Accepted: 21 August 2026 / Published: 2 September 2026

Abstract

Our environment deteriorates primarily due to the emissions of carbon dioxide. Scientists and entrepreneurs promote carbon offset to reduce the emissions. Scientists and investors explore the investments of carbon offset. Some scientists encouragingly construct portfolio selection models but do not completely optimize them. Some scientists encouragingly construct capital asset pricing models (CAPM) but do not completely justify them. Under such contexts, this paper proposes a model of multiple-objective portfolio selection (MOPS) and preliminarily explores multiple-objective capital asset pricing models (MOCAPM). By the classical transition from portfolio selection to CAPM, we introductorily conjecture the extended transition from MOPS to MOCAPM. Specifically, we prove mathematical properties for the model. For instance, its minimum-variance surface is convex, and its feasible region is bounded by the convex surface. We examine whether a point on the minimum-variance surface is nondominated. By the properties, we heuristically prove different tangent planes for MOCAPM (instead of the unique tangent line for CAPM). We tentatively hint the conditions for a unique tangent plane. This paper acts as a footstep of the introductory conjecture.

Graphical Abstract

1. Introduction

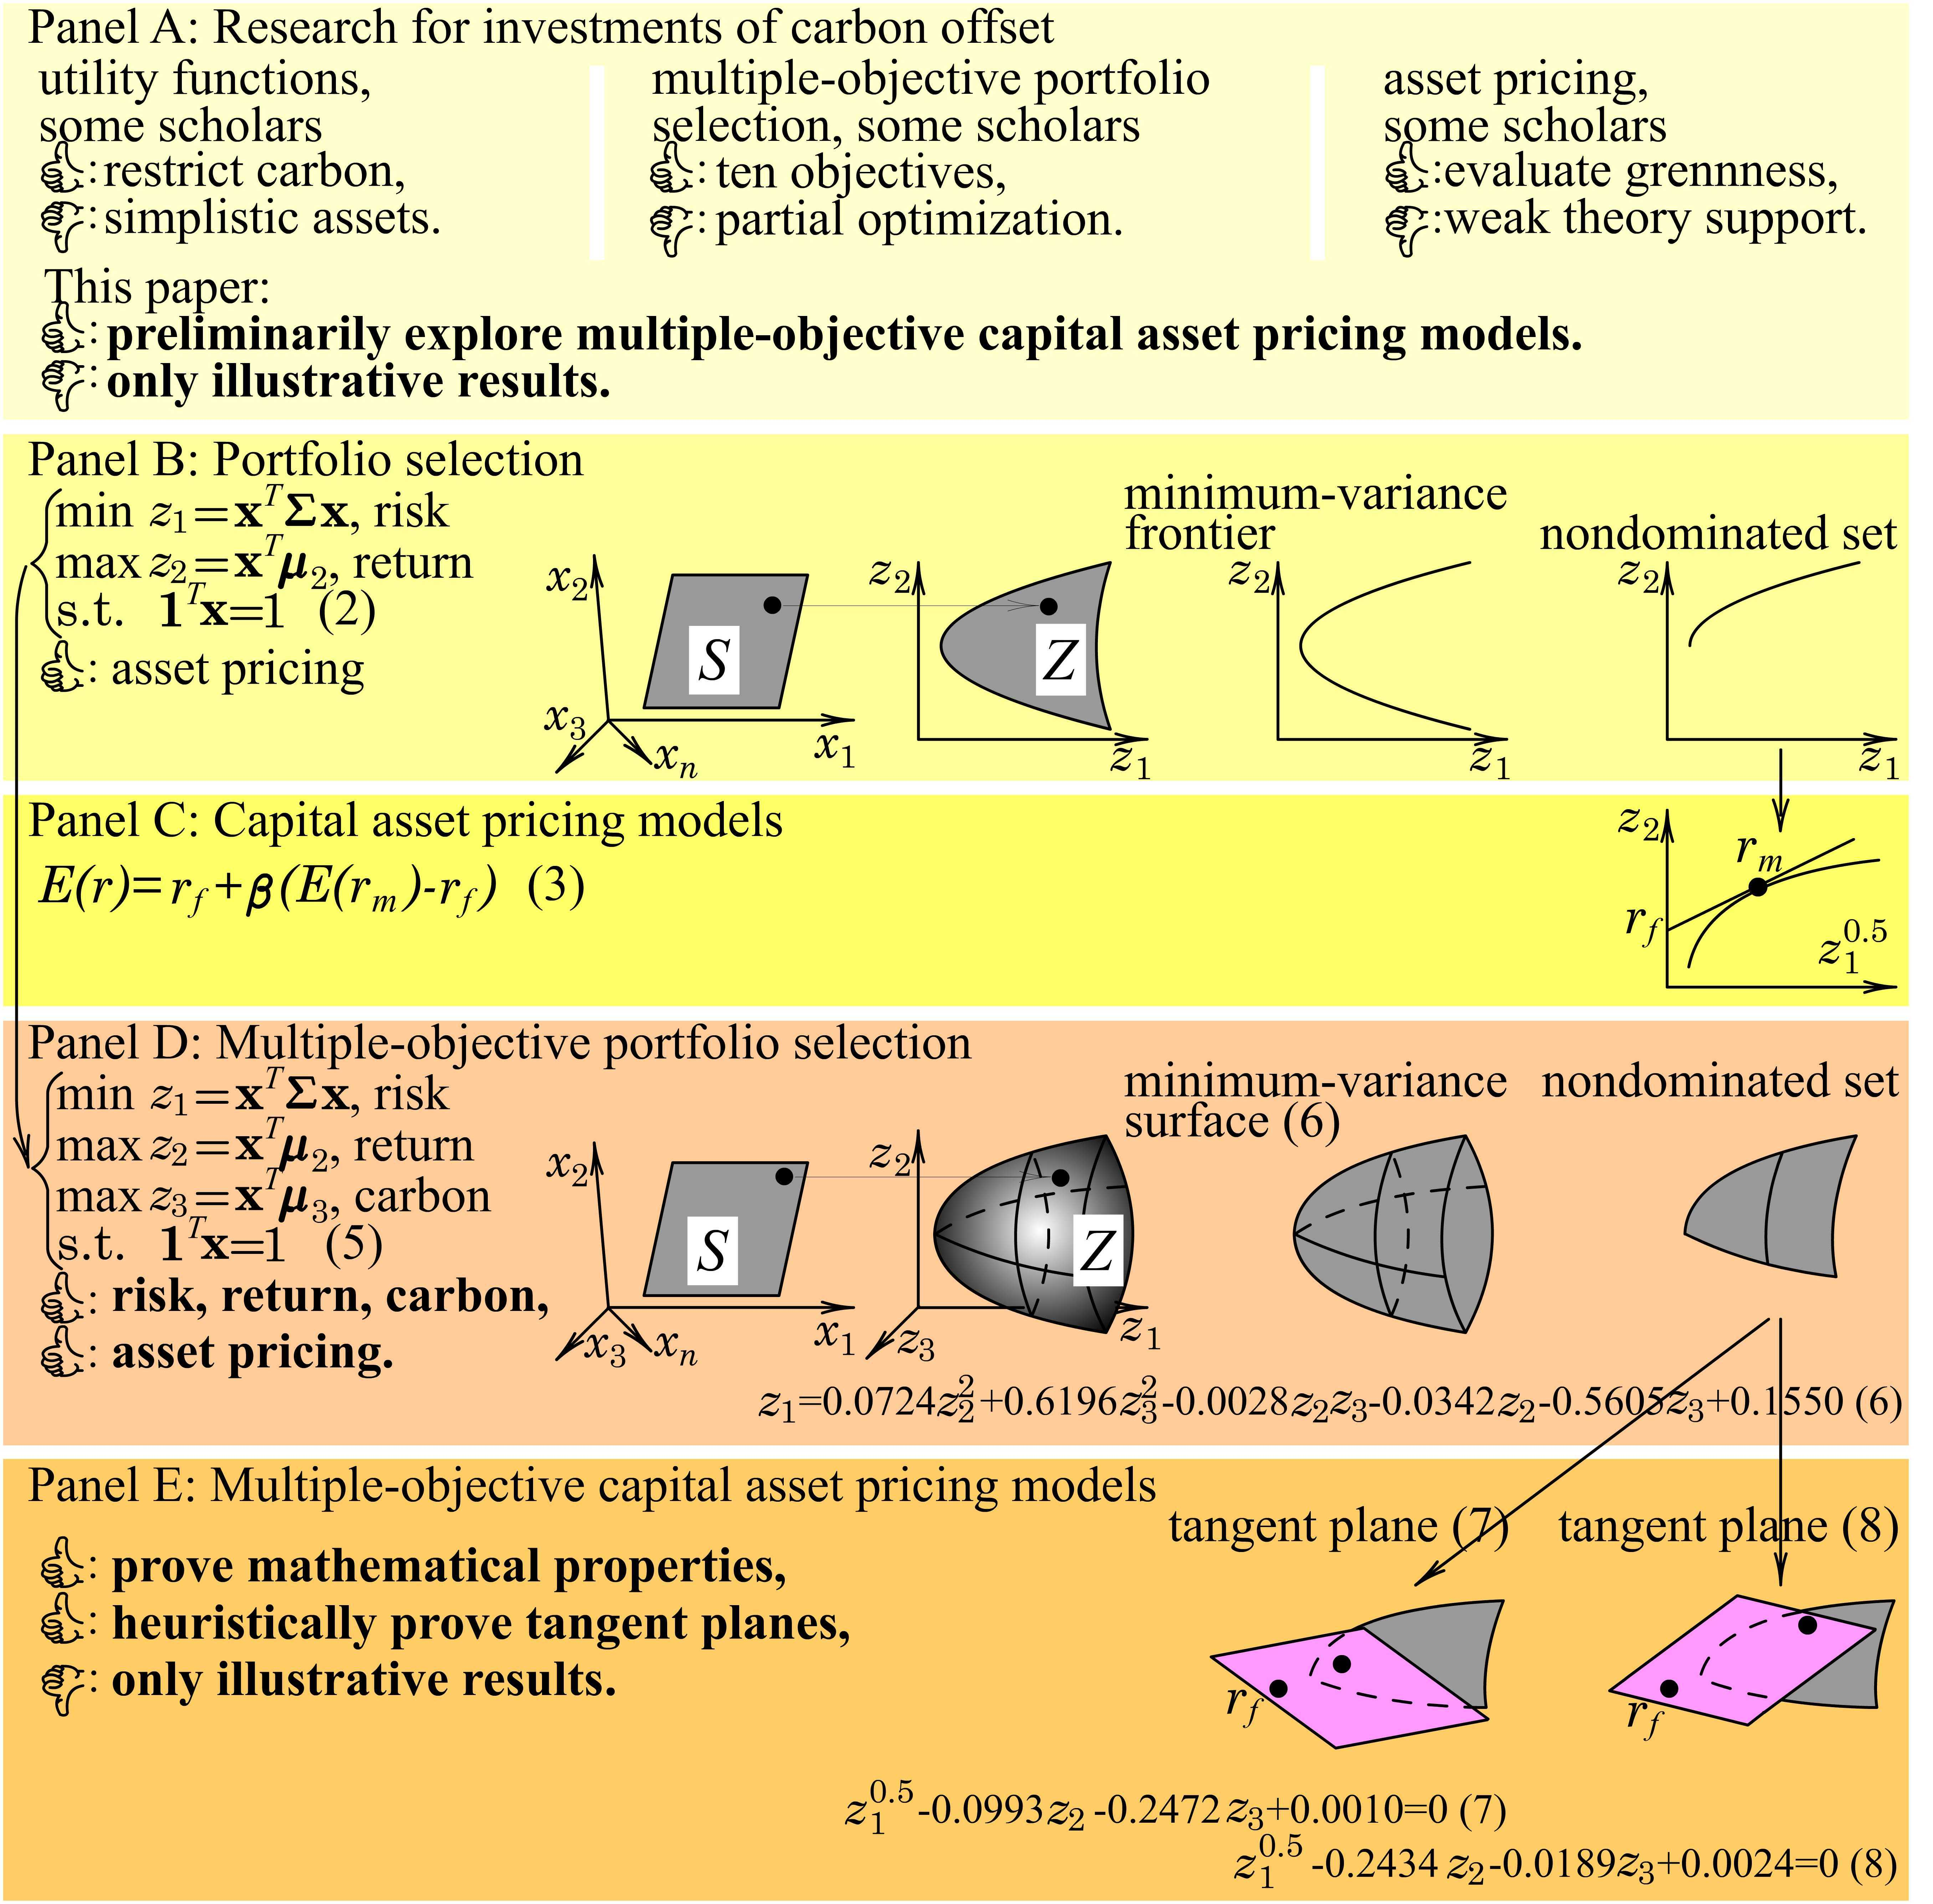
To firstly illustrate this paper’s theme, we delineate a graphical abstract. It carries five panels for research advancement. Structurally, Panels B and C depict the research lines of progressing from portfolio selection to CAPM. As extensions, Panels D and E depict the research lines of progressing from MOPS to MOCAPM. Particularly, Panel E depicts the highlight.

1.1. Characteristic Research for the Investments of Carbon Offset and Preliminary Contributions of This Paper

As our environment deteriorates primarily due to the emissions of carbon dioxide, scientists and entrepreneurs promote carbon offset to restrict the emissions. Investors and scientists explore the investments of carbon offset (the markets and investments of carbon offset will be introduced in Section 2). Chen et al. [1] encouragingly utilize utility functions, restrict carbon offset, and optimize for green investments. Unfortunately, Chen et al. (p. 1 [1]) constrain their universe of assets. Moreover, their optimization can be convoluted, because Markowitz (p. 100, [2]) argues that their optimization is much more demanding than portfolio selection.
Anquetin et al. [3] and Xue et al. [4] propose MOPS. Xue et al. [4] encouragingly probe copula and CVaR and build 10-objective portfolio selection. Unfortunately, Xue et al. (pp. 5–7, [4]) incompletely optimize the models. (We will contrast major methods of multiple-objective portfolio optimization in Section 2.2).
Alessi et al. [5] encouragingly propose asset pricing models and discover greenness premium. However, Alessi et al. (pp. 3–4, [5]) empirically propose the models and lack completely theoretical support. We cite these three papers in the Panel A of the graphical abstract.
Under such contexts, this paper preliminarily contributes to the literature of MOCAPM and the investments of carbon offset as follows:
  • We propose MOPS, completely optimize, and free the universe of assets.
  • We extend the classical research lines of progressing from portfolio selection to CAPM into the research lines of progressing from MOPS to MOCAPM.
However, our methodology is geometrically exploratory with illustrative results. We document the contributions in Panel A of the graphical abstract.

1.2. Portfolio Selection

Portfolio selection is commonly acclaimed as the birthplace of modern finance (as appraised by Rubinstein [6] and Fabozzi et al. [7]). Nobel Laureate Markowitz (p. 6, [8]) targets risk and return. Markowitz (p. 83, [9]) formulates portfolio selection as two-objective optimization as follows (multiple-objective optimization will be introduced in Section 2):
min z 1 = x T Σ x , variance of portfolio return max z 2 = x T μ 2 , expectation of portfolio return s . t . x S , feasible region
where, by n stocks, a portfolio is determined by its weight vector x . (Bold-face symbols (e.g., x ) symbolize vectors or matrices. Normal symbols (e.g., n) symbolize scalars or sets). Σ symbolizes the matrix of covariances of stock returns. μ 2 symbolizes a vector of the expectations of stock returns. z 1 measures the portfolio return’s variance. z 2 measures the portfolio return’s expectation. z 1 0.5 is the square root of z 1 and measures the standard deviation. Standard deviation can be preferred over variance z 1 in finance, because standard deviation has the same unit as the expectation z 2 . Variance z 1 can be preferred over standard deviation z 1 0.5 in mathematics and operations research, because variance is simpler. We considerately adopt variance z 1 or standard deviation z 1 0.5 . In R n , S symbolizes a feasible region. Scientists (e.g., Hillier and Lieberman [10]) typically assume that S is formed by linear constraints. In ( z 1 , z 2 ) space, Z symbolizes the feasible region.
Formula (1) formulates a map from S to Z. In the central part of Panel B of the graphical abstract, we delineate the map by and delineate S as a shaded region and Z as a shaded region (our delineation of S is hypothetical, because we can barely visualize its space R n ).
The left boundary of the feasible region Z is called a minimum-variance frontier which includes the nondominated set. In multiple-objective optimization, nondominated sets are optimal sets (minimum-variance frontiers will be introduced in Section 3).
Sharpe (pp. 59–62, [11]), Merton [12], and Campbell (p. 34, [13]) scrutinize the following model:
min z 1 = x T Σ x max z 2 = x T μ 2 s . t . 1 T x = 1
where 1 symbolizes a vector of ones. Merton [12] derives the minimum-variance frontier analytically. The term “analytically” signifies closed-form formulae by calculus and linear algebra and is easy to understand. In Panel B of the graphical abstract, we present (2) and its minimum-variance frontier and nondominated set.

1.3. CAPM

On the basis of (2), Nobel Laureate Sharpe [14] instigates his CAPM by
  • Determining a line which is tangent to the nondominated set of (2) and is through the risk-free asset r f (as defined by Bodie et al. (p. 136, [15]));
  • Reasoning the tangent portfolio as the market portfolio (as defined by Bodie et al. (pp. 115 and 285, [15])); and
  • Concluding the following model:
    E ( r ) = r f + β ( E ( r m ) r f )
    where E ( r ) symbolizes the expectation of a stock return. E ( r m ) symbolizes the expectation of the market portfolio’s return. β symbolizes the stock’s risk and is computed as the covariance between r and r m divided by the variance of r m .
In Panel C of the graphical abstract, we delineate (3) and the tangency. In Panels B and C by ↓, we delineate the research lines of progressing from portfolio selection (2) to CAPM (3).

1.4. MOPS

Markowitz [16] and Sharpe [17] perceive extra objectives after originating portfolio selection and CAPM. For instance, Markowitz [18] investigates long-term variance and short-term variance. Fama (pp. 445–447, [19]) and Cochrane (pp. 1081–1082, [20]) target multiple factors. Harvey and Siddique [21] consider skewness. Lo et al. [22] probe liquidity. Pedersen et al. [23] contemplate ESG.
Dorfleitner et al. [24], Hirschberger et al. [25], Qi et al. [26], and Utz and Steuer [27] expand portfolio selection into MOPS as follows:
min z 1 = x T Σ x , variance of portfolio return max z 2 = x T μ 2 , expectation of portfolio return max z 3 = x T μ 3 , expectation of general portfolio objective 3 max z k = x T μ k , expectation of general portfolio objective k s . t . x S , feasible region
where μ 3 μ k symbolize vectors of the expectations of general stock objectives. z 3 z k symbolize the expectations of general portfolio objectives. Z symbolizes the feasible region in ( z 1 , , z k ) space.
Formula (4) formulates a map from S to Z. In the central part of Panel D of the graphical abstract, we delineate the map by and delineate S as a shaded region and Z as a shaded region. For visualization reasons, we delineate ( z 1 , z 2 , z 3 ) space (instead of ( z 1 , , z k ) space).
The left boundary of the feasible region Z of (4) is called a minimum-variance surface which includes the nondominated set. The minimum-variance surface becomes extensions of the minimum-variance frontier (minimum-variance surfaces will be formulated in Section 3).
We follow Qi et al. [26] and expand (2) into the following model:
min z 1 = x T Σ x , variance of portfolio return max z 2 = x T μ 2 , expectation of portfolio return max z 3 = x T μ 3 , expectation of portfolio carbon offset s . t . 1 T x = 1
where μ 3 symbolizes a vector of the expectations of stock carbon offsets. z 3 symbolizes the expectation of portfolio carbon offset. In the left part of Panel D of the graphical abstract, we report (5). Qi et al. [26] derive the minimum-variance surface analytically. In the right part of Panel D, we delineate the following minimum-variance surface:
z 1 = 0.0724 z 2 2 + 0.6196 z 3 2 0.0028 z 2 z 3 0.0342 z 2 0.5605 z 3 + 0.1550
The derivation will be explained in Section 3. We also delineate the nondominated set in the right part of Panel D.

1.5. Scant Research for MOCAPM

Scholars are developing MOPS (as surveyed by Steuer and Na [28], Zopounidis et al. [29], Aouni et al. [30], La Torre et al. [31], and Ehrgott et al. [32]).
Despite the development, there barely exists research to progress from MOPS to MOCAPM (as classically innovated by Markowitz [9] and Sharpe [14]). The researchers of the survey above barely record the progress.

1.6. Highlight of This Paper: Proving Mathematical Properties of (5) and Heuristically Proving Different Tangent Planes for MOCAPM

This paper has the following highlight in theorems, corollaries, and propositions:
  • We prove mathematical properties for (5) (e.g., convex minimum-variance surface).
  • We heuristically prove the following two tangent planes which are tangent to the nondominated set of (5) and pass through the risk-free asset:
    z 1 0.5 0.0993 z 2 0.2472 z 3 + 0.0010 = 0
    z 1 0.5 0.2434 z 2 0.0189 z 3 + 0.0024 = 0
We delineate the highlight in Panel E of the graphical abstract.

1.7. Paper Structure

We develop the other sections of this paper as follows: In Section 2, we review multiple-objective optimization, tangent planes, asset pricing, and the investments of carbon offset. In Section 3, we model the investments of carbon offset by MOPS. In Section 4, we heuristically prove different tangent planes for MOCAPM. In Section 5, we preliminarily probe the conditions for a unique tangent plane. We conclude in Section 6. We enumerate main symbols in Appendix A.

2. Theoretical Knowledge: Multiple-Objective Optimization, Tangent Planes, Tangent Lines, Asset Pricing, and the Investments of Carbon Offset

In this section, we briefly review multiple-objective optimization, tangent planes, tangent lines, asset pricing, and the investments of carbon offset.

2.1. Multiple-Objective Optimization

Scientists (e.g., Steuer [33] and Wang and Rangaiah [34]) exhibit multiple-objective optimization as follows:
max z 1 = f 1 ( x ) max z k = f k ( x ) s . t . x S
where, in decision space, x R n symbolizes a decision vector, and S R n symbolizes a feasible region. In criterion space, z = z 1 z k T symbolizes a criterion vector, and Z = { z x S } symbolizes the feasible region. k symbolizes the number of objectives.
Scientists commence the following definitions:
Definition 1.
For z ¯ Z and z Z , that z ¯  dominates  z is defined as z ¯ 1 z 1 , , z ¯ k z k with at least one strict inequality.
Definition 2.
That z ¯ Z is nondominated is defined as that there does not exist a z Z such that z dominates z ¯ . Then, if x ¯ S is an inverse image of z ¯ (i.e., z ¯ = f 1 ( x ¯ ) f k ( x ¯ ) T ), x ¯ is efficient.
One goal of multiple-objective optimization is locating the
  • Efficient set as the set of efficient x ;
  • Nondominated set as the set of nondominated z .
“Nondominated” and “efficient” generalize the optimality of common 1-objective optimization in criterion space and decision space. For terms, the optimal outcome of (1) in ( z 1 , z 2 ) space is usually called efficient frontiers. On the contrary, we use the terms “nondominated” for criterion space and “efficient” for decision space by Definition 2 and call the outcome nondominated sets.
To solve (9), scientists (e.g., Steuer (pp. 202–205, [33]) utilize the following e-constraint methods:
max z 1 = f 1 ( x ) s . t . f 2 ( x ) = e 2 f k ( x ) = e k x S
where e 2 e k symbolize the parameters and (10) is an ordinary 1-objective optimization.
Alternatively, scientists (e.g., Steuer (pp. 165–170, [33])) utilize the following weighted-sums methods:
max z w = λ 1 f 1 ( x ) + + λ k f k ( x ) s . t . x S
where λ 1 λ k T 0 are the parameters.
For models with min z k = f k ( x ) (in contrast to just max), we adjust Definition 1 as follows:
max z 1 = f 1 ( x ) max z k 1 = f k 1 ( x ) min z k = f k ( x ) s . t . x S
Definition 3.
For z ¯ Z and z Z , that z ¯  dominates  z is defined as z ¯ 1 z 1 , , z ¯ k 1 z k 1 and z ¯ k z k with at least one strict inequality.

2.2. Graphically Contrasting Major Methods of Multiple-Objective Portfolio Optimization

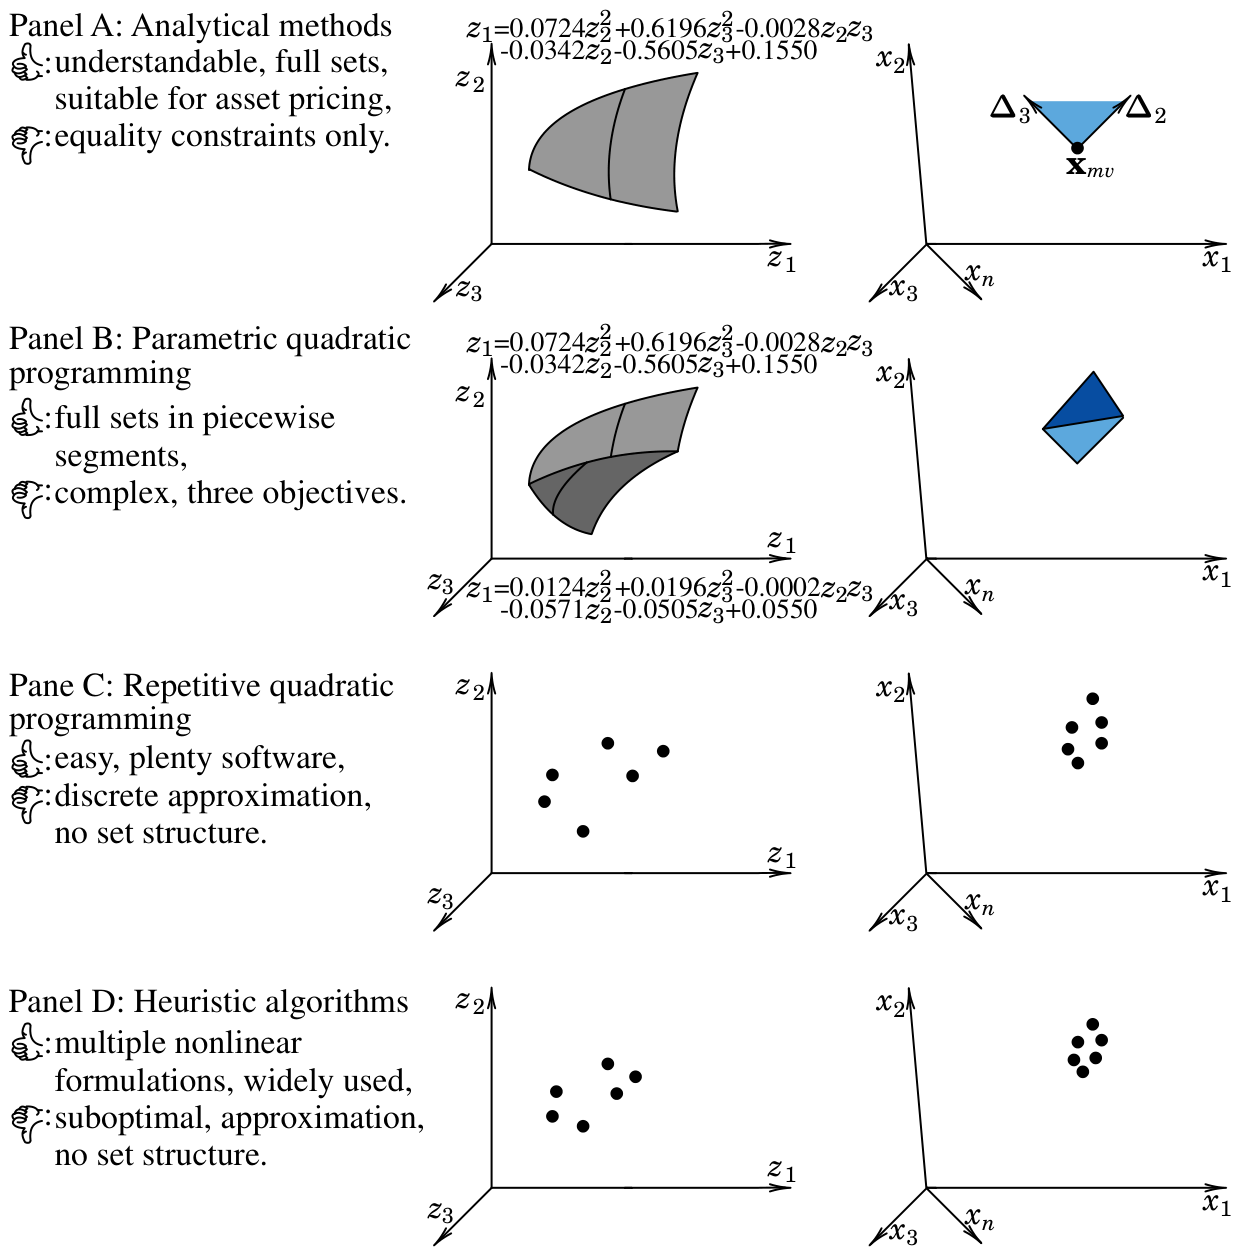
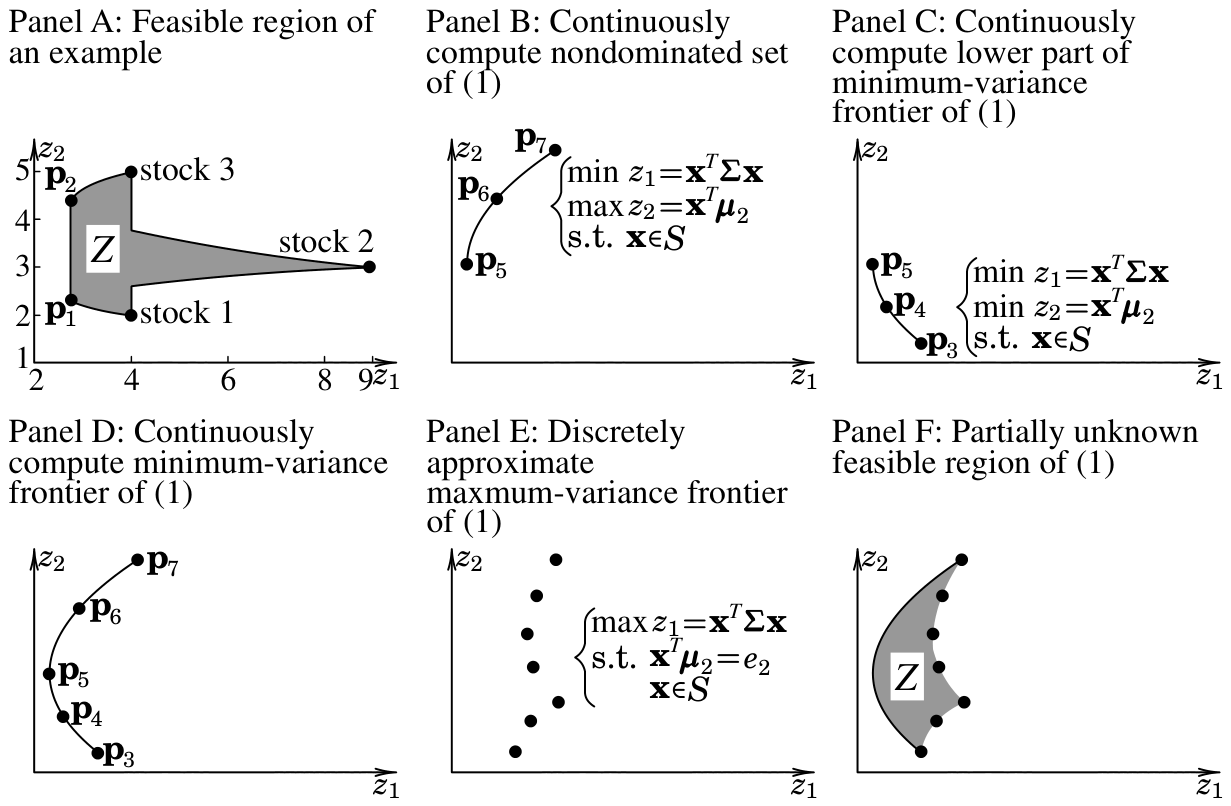
We graphically contrast major methods of multiple-objective portfolio optimization for (4) in Figure 1.

2.2.1. Analytical Methods

By analytical methods on the basis calculus and linear algebra, Merton [12], Qi et al. [26], and Qi and Steuer [35] understandably derive full nondominated sets. Analytical methods could have the following advantages: Firstly, the scholars prove the sets’ paraboloidal structure. For instance in Panel A of Figure 1, we depict a nondominated set as a segment of the following paraboloid:
z 1 = 0.0724 z 2 2 + 0.6196 z 3 2 0.0028 z 2 z 3 0.0342 z 2 0.5605 z 3 + 0.1550
Secondly, the scholars derive the efficient sets and prove the sets’ conical structure. In Panel A of Figure 1, we depict a cone. Thirdly, the scholars derive the minimum-variance surfaces, and we will elaborate this advantage in Section 3.3, Section 3.4 and Section 3.5. In contrast, researchers hardly derive minimum-variance surfaces by other methods of multiple-objective portfolio optimization. Fourthly, due to the analyticity, analytical methods are suitable for asset pricing. Lastly, researchers can obtain mathematical results on tangent hyperplanes and convex surfaces, and we will prove the minimum-variance surface as convex in Theorem 4. In contrast, to the best of our knowledge, researchers hardly obtain the results by other methods of multiple-objective portfolio optimization.
However, one disadvantage is that the scholars are restricted to equality constraints only.

2.2.2. Parametric Quadratic Programming

Bank et al. [36] describe parametric optimization. Best [37], Goh and Yang [38], Hirschberger et al. [25], Jayasekara et al. [39], and Jayasekara et al. [40] suggest their parametric quadratic programming algorithms.
However, parametric quadratic programming is much more complex than quadratic programming. Moreover, the researchers do not explicitly prove the nondominated sets’ structure. For instance, Best [37] and Goh and Yang [38] launch active-set algorithms but do not prove the structure. Jayasekara et al. [39] and Jayasekara et al. [40] contrast optimization methods and propose generalized scalarization algorithms but do not prove the structure. Hirschberger et al. [25] suggest that the nondominated sets for just three objectives are composed of piecewise paraboloidal segments but do not prove the structure. Hirschberger et al. [25] also suggest that the efficient sets are composed of piecewise linear segments but do not prove the structure. For instance in Panel B of Figure 1, we depict that a nondominated set is composed of two segments of the following two paraboloids:
z 1 = 0.0724 z 2 2 + 0.6196 z 3 2 0.0028 z 2 z 3 0.0342 z 2 0.5605 z 3 + 0.1550 z 1 = 0.0124 z 2 2 + 0.0196 z 3 2 0.0002 z 2 z 3 0.0571 z 2 0.0505 z 3 + 0.0550
We also depict that the efficient set is composed of two piecewise linear segments in Panel B.
Furthermore, the researchers do not offer public-domain software, so practical optimization is still absent. Hirschberger et al. [25] code the software for three objectives. Utz et al. [41], Utz et al. [42], and Utz and Steuer [27] utilize the software. Unfortunately, the software is still private.

2.2.3. Repetitive Quadratic Programming

Researchers can utilize e-constraint methods (10) with a group of preset e 2 e k or weighted-sums methods (11) with a group of preset λ 1 λ k T , transform (4) into (ordinary) quadratic programming, and repetitively solve.
Repetitive quadratic programming is easy to execute with plenty of software. However, it offers discrete approximations for nondominated sets and efficient sets. For instance in Panel C of Figure 1, we depict six points as an approximation for the nondominated set and six points as an approximation for the efficient set. Moreover, repetitive quadratic programming cannot reveal nondominated sets’ structure (e.g., the paraboloidal structure of (5)).

2.2.4. Heuristic Algorithms

Researchers often utilize heuristic algorithms (e.g., evolutionary algorithms, Tabu search, and simulated annealing of Woodside-Oriakhi et al. [43]). As an advantage, heuristic algorithms can handle multiple nonlinear formulations. However, heuristic algorithms offer suboptimal solutions. Moreover, heuristic algorithms also suffer from disadvantages of repetitive quadratic programming. For instance in Panel D of Figure 1, we depict six points as an approximation for the nondominated set and six points as an approximation for the efficient set.

2.3. Tangent Planes and Tangent Lines

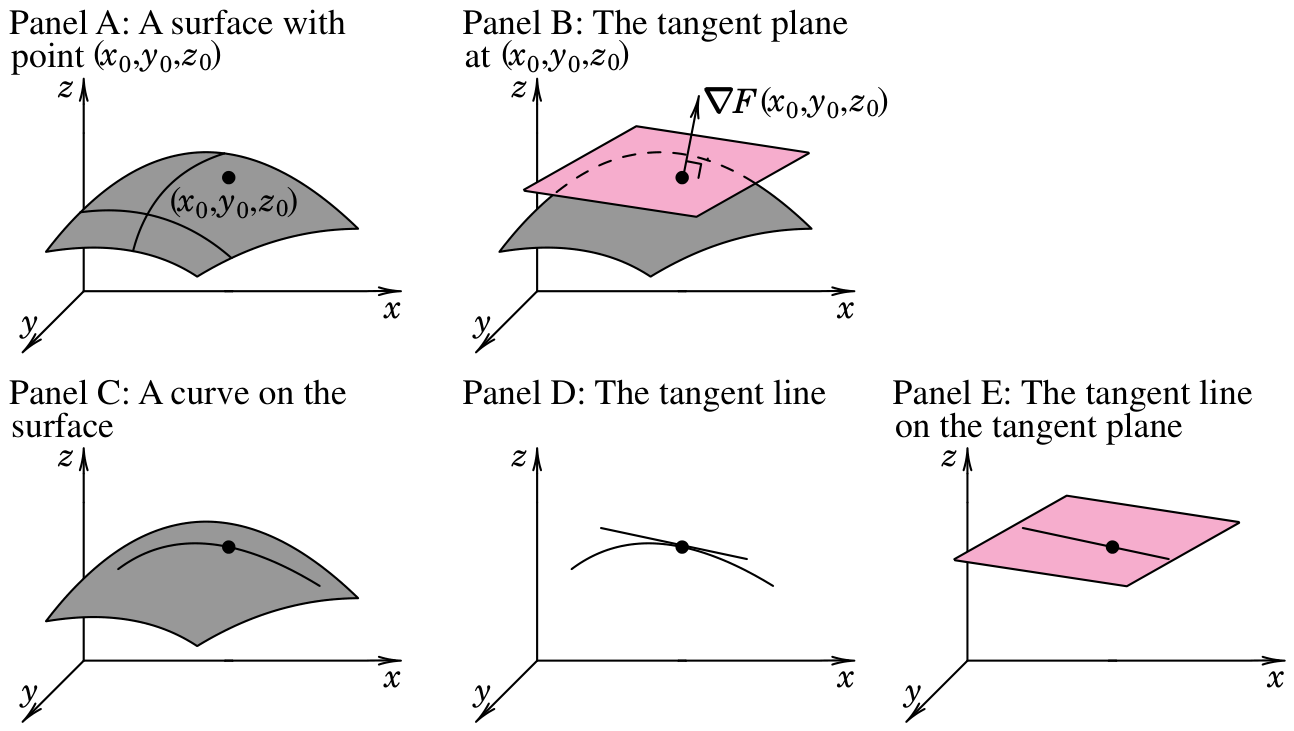
Scholars (e.g., Larson and Edwards [44] and Stewart et al. [45]) describe tangent planes and tangent lines. We present the relationship between tangent planes and tangent lines in Figure 2. In ( x , y , z ) space, a surface is symbolized as follows:
F ( x , y , z ) = 0
On the surface, a point ( x 0 , y 0 , z 0 ) is chosen. A surface with ( x 0 , y 0 , z 0 ) is delineated in Panel A of Figure 2.
Definition 4.
If F ( x , y , z ) is differentiable at ( x 0 , y 0 , z 0 ) with the nonzero gradient F ( x 0 , y 0 , z 0 ) , the tangent plane to the surface F ( x , y , z ) = 0 at ( x 0 , y 0 , z 0 ) is expressed as follows:
F x ( x 0 , y 0 , z 0 ) ( x x 0 ) + F y ( x 0 , y 0 , z 0 ) ( y y 0 ) + F z ( x 0 , y 0 , z 0 ) ( z z 0 ) = 0
F ( x 0 , y 0 , z 0 ) = F x ( x 0 , y 0 , z 0 ) F y ( x 0 , y 0 , z 0 ) F z ( x 0 , y 0 , z 0 ) T F x = F x F y = F y F z = F z
The tangent plane’s normal vector is F ( x 0 , y 0 , z 0 ) .
A tangent plane with the normal vector is delineated in Panel B of Figure 2.
On the surface, a curve passing through ( x 0 , y 0 , z 0 ) is chosen as follows:
x = x ( t ) y = y ( t ) z = z ( t ) t R x 0 = x ( t 0 ) y 0 = y ( t 0 ) z 0 = z ( t 0 )
Definition 5.
If x ( t ) , y ( t ) , and z ( t ) of a curve are differentiable at t 0 with the nonzero derivatives (i.e., x ( t 0 ) 0 , y ( t 0 ) 0 , and z ( t 0 ) 0 ), the tangent line to the curve at tangent point ( x 0 , y 0 , z 0 ) is expressed as follows:
x x 0 x ( t 0 ) = y y 0 y ( t 0 ) = z z 0 z ( t 0 )
On the surface, a curve passing through ( x 0 , y 0 , z 0 ) is delineated in Panel C of Figure 2. The tangent line to the curve at ( x 0 , y 0 , z 0 ) is delineated in Panel D. Moreover, the tangent line lies on the tangent plane (as delineated in Panel E). The relationship is stated in the following theorem:
Theorem 1.
For the tangent plane in Definition 4 and tangent line in Definition 5, the tangent line lies on the tangent plane.
Proof. 
The curve (15) is on the surface (12), so (15) satisfies (12) as follows:
F ( x ( t ) , y ( t ) , z ( t ) ) = 0
We calculate the derivative with respect to t = t 0 and rearrange by (14) as follows:
F x ( x 0 , y 0 , z 0 ) x ( t 0 ) + F y ( x 0 , y 0 , z 0 ) y ( t 0 ) + F z ( x 0 , y 0 , z 0 ) z ( t 0 ) = 0 F x ( x 0 , y 0 , z 0 ) F y ( x 0 , y 0 , z 0 ) F z ( x 0 , y 0 , z 0 ) x ( t 0 ) y ( t 0 ) z ( t 0 ) = 0 F ( x 0 , y 0 , z 0 ) x ( t 0 ) y ( t 0 ) z ( t 0 ) = 0
Formula (17) indicates that the tangent line’s direction vector x ( t 0 ) y ( t 0 ) z ( t 0 ) T is perpendicular to the tangent plane’s normal vector F ( x 0 , y 0 , z 0 ) . Moreover, ( x 0 , y 0 , z 0 ) is on the tangent plane. The tangent line is determined by its direction vector and ( x 0 , y 0 , z 0 ) , so the tangent line lies on the tangent plane. Theorem 1 is proved. □

2.4. Asset Pricing

The purpose of asset pricing is to price assets in financial markets. Asset pricing is fundamental in finance. We sketch the advance of asset pricing through the following typical phases:
  • Portfolio selection (since the 1950s), especially by Markowitz [9];
  • CAPM (since the 1960s), especially by Sharpe [14];
  • Arbitrage formulations and continuous-time formulations (since the 1970s), especially by Ross [46] and Black and Scholes [47];
  • Factor models (since the 1990s), especially by Fama and French [48];
  • Behavioral analyses (since the 1990s), especially by Thaler [49];
  • Machine learning analyses (since the 2010s), especially by Gu et al. [50].

2.5. Advance of Carbon Offset Markets

The markets of carbon offset evolve through the following typical phases:
i.  
Foundations (since the 1980s), especially by the United Nations Framework Convention on Climate Change;
ii. 
Births (since the 1990s), especially by the Kyoto Protocol;
iii.
The launch of the European Union Emissions Trading System (since 2005);
iv.
Modern period (since 2015), especially by the Paris Agreement with the globalization of the markets.

2.6. Literature for the Investments of Carbon Offset

Generally, scientists investigate the investments of carbon offset primarily in the following aspects: For environment and carbon offset, Wagner and Weitzman [51] evaluate climate change and emphasize risk management for carbon offset projects. Dechezlepretre et al. [52] report the effect of carbon offset markets.
For portfolio selection and MOPS, Luo and Wu [53] inspect time-varying correlations of carbon dioxide allowance and financial markets. Mueller et al. [54] incorporate carbon offset into portfolio selection and find positive effects.
For asset pricing, Bolton and Kacperczyk [55] document that assets with higher carbon emissions require higher returns. Giroux et al. [56] establish a premium for carbon risk.
For derivatives, Kumar et al. [57] assess carbon offset futures and analyze economic indicators. Qi and Wang [58] assess carbon offset options for Asian styles with jumps and Brownian motions.

3. Studying the Investments of Carbon Offset by MOPS

In this section, we formulate the investments of carbon offset by MOPS (5). Although (5) is simplistic, we prove that (5) has mathematically convenient properties. Particularly, its minimum-variance surface is convex, its feasible region in ( z 1 , z 2 , z 3 ) space is bounded by the convex minimum-variance surface, and we examine whether a point on the minimum-variance surface is nondominated. We illustrate by the components of the Shanghai Stock Exchange 50 Index. By the properties, we will heuristically prove different tangent planes in the next section.

3.1. Studying the Investments of Carbon Offset by MOPS (5)

For the investments of carbon offset, we expand classical portfolio selection models (2) by minimizing variance of the portfolio return, maximizing the expected portfolio return, and maximizing the expected portfolio carbon offset.
The nondominated set of (2) is a 2-dimensional curve (as depicted in Panel B of the graphical abstract) in ( z 1 , z 2 ) space. As extensions, the nondominated set of (5) expands into a 3-dimensional surface (as depicted in Panel D of the graphical abstract) in ( z 1 , z 2 , z 3 ) space. The surface serves as a collection of the optimal variance of portfolio return ( z 1 ), expectation of portfolio return ( z 2 ), and expectation of portfolio carbon offset ( z 3 ). Investors perceive the surface as a detailed depiction of the tradeoffs among z 1 , z 2 , and z 3 . Investors consider carbon offset and generally balance z 1 , z 2 , and z 3 on the surface. Investors appreciate having much more freedom of options on the surface than on the curve.

3.2. The Assumptions of (5) and Extensions of the Risk-Free Asset

Qi et al. [26] make the following assumptions for (5):
Assumption 1.
The number of stocks n is greater than the number of objectives (i.e., n > 3 ).
Assumption 2.
Vectors μ 2 , μ 3 and 1 are linearly independent.
Assumption 3.
Covariance matrix Σ is invertible and thus positive definite.
Brockwell and Davis (pp. 33 and 35, [59]) define covariance matrices as symmetric and positive semidefinite. By Assumption 3, Σ is positive definite.
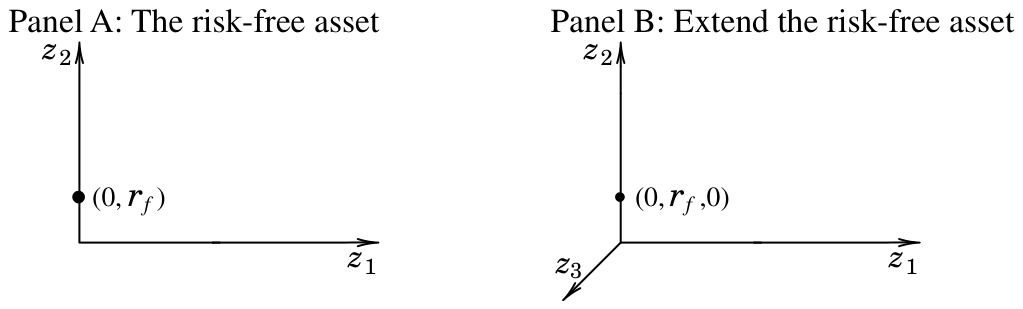
By the framework of portfolio selection (1), researchers (e.g., Bodie et al. (p. 136, [15])) model the risk-free asset with z 1 variance as 0 and z 2 expected return as r f (as depicted in Panel A of Figure 3).
By the framework of MOPS (5), we assume the risk-free asset with z 1 variance as 0 and z 2 expected return as r f and z 3 as 0 (as depicted in Panel B of Figure 3) as follows:
Assumption 4.
In ( z 1 , z 2 , z 3 ) space of (5), the risk-free asset is modeled as ( 0 , r f , 0 ) .
However, assuming z 3 as 0 is convenient but subjective, because the risk-free asset can carry nonzero values. For instance with z 3 for expected ESG, Steuer [60] contends that different investors can designate distinctive ESG values to the risk-free asset. Namely, some investors can disconnect return and ESG and designate zero. Some investors can positively connect return and ESG and designate positive values. Some investors can negatively connect return and ESG and designate negative values.

3.3. The Analytic Properties of the Minimum-Variance Surface of (5)

By e-constraint methods (10), we formulate the minimum-variance frontier of (2) in the following model:
min z 1 = x T Σ x s . t . x T μ 2 = e 2 1 T x = 1
where e 2 R symbolizes the parameter. As e 2 changes, the optimal solutions of the model above constitute the minimum-variance frontier in ( z 1 , z 2 ) space. Merton [12] derives the frontier analytically and verifies it as a parabola.
By e-constraint methods (10), we formulate the minimum-variance surface of (5) in the following model:
min z 1 = x T Σ x s . t . x T μ 2 = e 2 x T μ 3 = e 3 1 T x = 1
where e 2 R and e 3 R symbolize the parameters. As e 2 and e 3 change, the optimal solutions of (18) constitute the minimum-variance surface in ( z 1 , z 2 , z 3 ) space. We prove the feasibility of (18) in the following theorem:
Theorem 2.
(18) is always feasible for any e 2 R and e 3 R . Namely, the following feasible region S ( 18 ) is not empty:
S ( 18 ) = { x R n μ 2 T x = e 2 , μ 3 T x = e 3 , 1 T x = 1 }
Proof. 
We rephrase S ( 18 ) of (19) into the following linear equations:
μ 2 T μ 3 T 1 T 3 × n x n × 1 = e 2 e 3 1 3 × 1
where the subscripts (e.g., 3 × n ) demonstrate the matrix dimensions. Because μ 2 , μ 3 and 1 are linearly independent by Assumption 2, the rank of matrix μ 2 T μ 3 T 1 T is 3. Furthermore with n > 3 by Assumption 1, we follow the knowledge of solvability of linear equations (e.g., that of Strang (pp. 39–56, [61])) and determine (20) as solvable (i.e., S ( 18 ) as not empty). We accordingly express S ( 18 ) in the form of the solutions of (20) as follows:
S ( 18 ) = { x R n x = x ¯ + t 1 x ¯ 1 + + t n 3 x ¯ n 3 , t 1 , , t n 3 R }
where x ¯ is a solution of (20). x ¯ 1 0 x ¯ n 3 0 are the basis of the solutions of the following homogeneous linear equations:
μ 2 T μ 3 T 1 T x = 0
Theorem 2 is proved. □
Theorem 2 is an advantage of (5), because we can readily preset e 2 and e 3 in (18) and confirm the feasibility. Conversely for MOPS (4), we can encounter infeasibility for computing the minimum-variance surface as follows:
min z 1 = x T Σ x s . t . x T μ 2 = e 2 x T μ k = e k x S
where e 2 R e k R symbolize the parameters. Namely, (22) can be infeasible for inappropriate e 2 e k .
Qi et al. [26] derive the optimal solution of (18) as follows:
x = x 1 + e 2 d 2 + e 3 d 3
where
C a b c b d e c e f μ 2 T Σ 1 μ 2 μ 2 T Σ 1 μ 3 1 T Σ 1 μ 2 μ 2 T Σ 1 μ 3 μ 3 T Σ 1 μ 3 1 T Σ 1 μ 3 1 T Σ 1 μ 2 1 T Σ 1 μ 3 1 T Σ 1 1
| C | = a d f a e 2 b 2 f + 2 b c e c 2 d > 0
x 1 = 1 | C | [ ( b e c d ) Σ 1 μ 2 + ( b c a e ) Σ 1 μ 3 + ( a d b b ) Σ 1 1 ]
d 2 = 1 | C | [ ( d f e e ) Σ 1 μ 2 + ( c e b f ) Σ 1 μ 3 + ( b e c d ) Σ 1 1 ]
d 3 = 1 | C | [ ( c e b f ) Σ 1 μ 2 + ( a f c c ) Σ 1 μ 3 + ( b c a e ) Σ 1 1 ]
Discretely, (23) is the optimal solution for (18). Continuously, Qi et al. [26] and Qi [62] derive the (whole) minimum-variance surface of (5) analytically as follows:
z 1 = z 2 z 3 1 1 × 3 D 3 × 3 z 2 z 3 1 3 × 1
D = d 2 T Σ d 2 d 2 T Σ d 3 d 2 T Σ x 1 d 2 T Σ d 3 d 3 T Σ d 3 d 3 T Σ x 1 d 2 T Σ x 1 d 3 T Σ x 1 x 1 T Σ x 1
where
d 2 T Σ d 2 = 1 | C | 2 ( a d 2 f 2 2 a d e 2 f + a e 4 b 2 d f 2 + b 2 e 2 f + 2 b c d e f 2 b c e 3 c 2 d 2 f + c 2 d e 2 )
d 2 T Σ d 3 = 1 | C | 2 ( a b d f 2 + a b e 2 f + a c d e f a c e 3 + b 3 f 2 + b c 2 d f 3 b 2 c e f + 2 b c 2 e 2 c 3 d e )
d 3 T Σ d 3 = 1 | C | 2 ( a 2 d f 2 a 2 e 2 f a b 2 f 2 + 2 a b c e f 2 a c 2 d f + a c 2 e 2 + b 2 c 2 f 2 b c 3 e + c 4 d )
d 2 T Σ x 1 = 1 | C | 2 ( a b d e f a b e 3 a c d 2 f + a c d e 2 b 3 e f + b 2 c d f + 2 b 2 c e 2 3 b c 2 d e + c 3 d 2 )
d 3 T Σ x 1 = 1 | C | 2 ( a 2 d e f + a 2 e 3 + a b 2 e f + a b c d f 3 a b c e 2 + a c 2 d e b 3 c f + 2 b 2 c 2 e b c 3 d )
x 1 T Σ x 1 = 1 | C | 2 ( a 2 d 2 f a 2 d e 2 2 a b 2 d f + a b 2 e 2 + 2 a b c d e a c 2 d 2 2 b 3 c e + b 4 f + b 2 c 2 d )
Obtaining a continuous expression (29) is an advantage of (5). Conversely for MOPS (4), a continuous expression of the minimum-variance surface is typically unavailable.
For the minimum-variance surface (29), Qi et al. [26] derive the inverse image (i.e., the set of x ) analytically as follows:
{ x R n x = x 1 + z 2 d 2 + z 3 d 3 , z 2 R , z 3 R }
For the minimum-variance surface’s inverse image, Qi et al. [26] prove d 2 and d 3 in (27) and (28) as linearly independent as follows:
Theorem 3.
d 2 and d 3 are linearly independent.
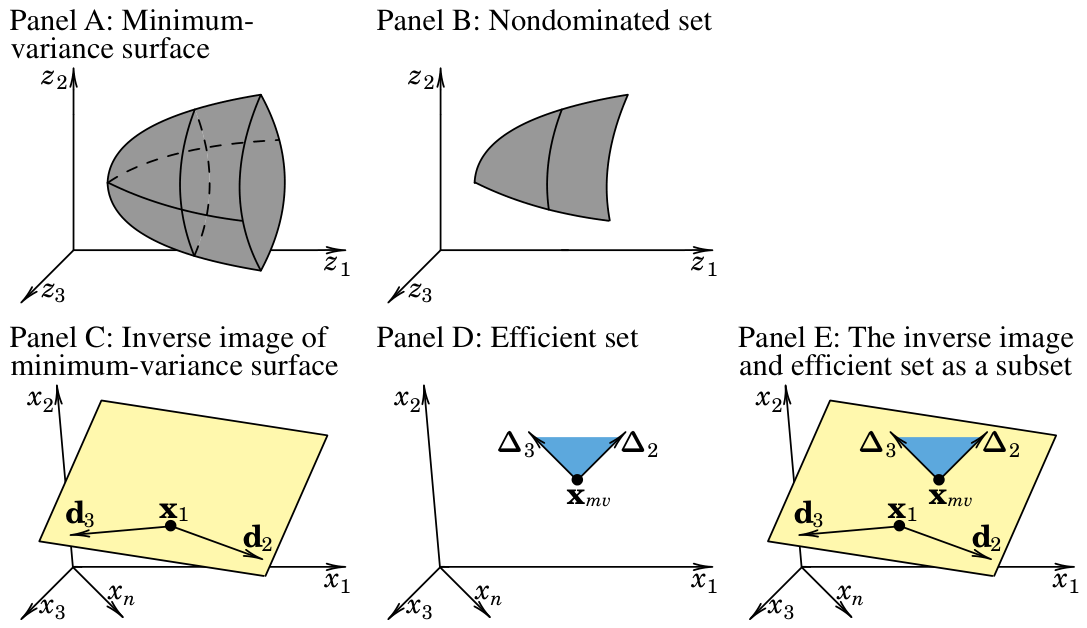
Geometrically by Theorem 3, the minimum-variance surface’s inverse image (37) is a 2-dimensional affine set. Explicitly in R n , the set is created by d 2 and d 3 at the origin and translated by x 1 .
In order to further analyze the geometric properties of the minimum-variance surface and feasible region of (5), we prove the surface’s convexity as follows:
Theorem 4.
The minimum-variance surface of (5) is convex. Namely in (29), z 1 is a convex function with respect to z 2 and z 3 .
Proof. 
Because z 1 is twice differentiable with respect to z 2 and z 3 , we compute the Hessian matrix as follows:
2 z 1 z 2 2 2 z 1 z 2 z 3 2 z 1 z 2 z 3 2 z 1 z 3 2 = d 2 T Σ d 2 d 2 T Σ d 3 d 2 T Σ d 3 d 3 T Σ d 3
Qi et al. (p. 170, [26]) prove D in (30) as positive definite. The Hessian matrix in (38) is a principal submatrix of D and thus positive definite. By the knowledge of the positive semidefinite Hessian matrix and convexity (e.g., that of Boyd and Vandenberghe (p. 71, [63])), z 1 is a convex function with respect to z 2 and z 3 . Theorem 4 is proved. □

3.4. The Analytic Properties of the Feasible Region of (5)

By Theorem 2, we prove the feasible region S ( 18 ) as unbounded as follows:
Theorem 5.
S ( 18 ) in (19) is unbounded.
Proof. 
We simply take t 2 = 0 t n 3 = 0 in (21) and obtain as follows:
x = x ¯ + t 1 x ¯ 1
For (39), we determine x as t 1 , because x ¯ 1 0 . Therefore, S ( 18 ) is unbounded. Theorem 5 is proved. □
We prove the feasible region Z ( 18 ) as unbounded above as follows:
Theorem 6.
For (18), the feasible region Z ( 18 ) (as follows) is unbounded above:
Z ( 18 ) = { z 1 = x T Σ x x S ( 18 ) }
Proof. 
We adopt (39) and substitute it into z 1 = x T Σ x as follows:
z 1 = ( x ¯ + t 1 x ¯ 1 ) T Σ ( x ¯ + t 1 x ¯ 1 ) = ( x ¯ 1 ) T Σ x ¯ 1 t 1 2 + 2 ( x ¯ ) T Σ x ¯ 1 t 1 + ( x ¯ ) T Σ x ¯ , as t 1
because the limit is determined by the quadratic-term coefficient ( x ¯ 1 ) T Σ x ¯ 1 and we determine ( x ¯ 1 ) T Σ x ¯ 1 > 0 by Assumption 3. Therefore, Z ( 18 ) is unbounded above. Theorem 6 is proved. □
By Theorems 4 and 6, we prove the geometric property and the shape of the feasible region of (5) as follows:
Theorem 7.
For (5) in ( z 1 , z 2 , z 3 ) space, the feasible region Z ( 5 ) (as follows) is bounded by the convex minimum-variance surface (29) along the negative z 1 -direction. The feasible region Z ( 5 ) is unbounded along the positive z 1 -direction. Therefore, the minimum-variance surface (29) forms the only boundary of Z ( 5 ) .
Z ( 5 ) = { z 1 = x T Σ x , z 2 = x T μ 2 , z 3 = x T μ 3 x S ( 5 ) } S ( 5 ) = { x R n 1 T x = 1 }
Proof. 
For any e 2 and e 3 , we formulate the negative z 1 -direction by min z 1 in (18) and obtain the optimal solution (23). We formulate the positive z 1 -direction by max z 1 and determine max z 1 = by Theorem 6. Continuously, the convex minimum-variance surface (29) forms the only boundary of Z ( 5 ) . Theorem 7 is proved. □

3.5. Difficulties in Determining the Minimum-Variance Surface and Feasible Region of MOPS

Theorem 7 is an advantage of (5). Conversely for MOPS (4) and even for portfolio selection (1), the geometric property and the shape of the feasible region are typically unknown. We present the unknown status in Figure 4.
In order to demonstrate the partially unknown and thus potentially odd shape of the feasible region, we initially borrow an example from Qi et al. (pp. 316–319, [64]). The example is for the standard portfolio selection model (as termed by Markowitz (p. 3, [8])) as follows:
min z 1 = x T Σ x max z 2 = x T μ 2 s . t . 1 T x = 1 x 0
The example is for three stocks with unique parameters as follows: Investors can rescale the parameters (e.g., by dividing each element by 100) to fit empirical data.
Σ = 4 0 4 0 9 0 4 0 4 μ 2 = 2 3 5 correlation matrix = 1 0 1 0 1 0 1 0 1
Qi et al. (pp. 316–319, [64]) exploit the three stock status and parameters and prove the feasible region (instead of utilizing mathematical programming). We present the feasible region Z as a shaded region in Panel A of Figure 4.
As the first uniqueness, there exist vertical linear segments for a nonlinear model (40). As the second uniqueness, there exist alternative optima for the minimum-variance portfolio of (40). The minimum-variance portfolio is formulated as follows:
min z 1 = x T Σ x s . t . 1 T x = 1 x 0
In Panel A of Figure 4, vertical linear segment p 1 to p 2 corresponds to all optima of (41). Moreover, vertical linear segment p 1 to p 2 poses a challenge for optimizing (41), because quadratic programming solvers (e.g., Matlab) typically locate only one point on the segment and can not locate the whole segment for all optima. Furthermore, the parametric quadratic programming solver of Hirschberger et al. [65] cannot solve (40).
We present (1) and its nondominated set in Panel B of Figure 4. Markowitz [66] and Markowitz and Todd (p. 176, [67]) deploy parametric quadratic programming to continuously and exactly resolve (1) and prove the piecewise parabolic segment structure in the following theorem:
Theorem 8.
The nondominated set of (1) is a continuous, strictly increasing, and strictly concave curve in ( z 1 , z 2 ) space. Moreover, the set is piecewise composed of connected parabolic segments. Correspondingly, the efficient set is piecewise composed of connected linear segments.
For instance, we presume that the nondominated set is piecewise composed of two connected parabolic segments: segment p 5 to p 6 and segment p 6 to p 7 with the following expressions respectively:
z 1 = 295.46 z 2 2 4.20 z 2 + 0.02 z 1 = 168.80 z 2 2 2.25 z 2 + 0.01
The expressions above are a continuous and exact description of the nondominated set.
Moreover, Markowitz and Todd (pp. 301–338, [67]) code their algorithm in Excel VBA. Jacobs et al. [68], Stein et al. [69], Niedermayer and Niedermayer [70], and Hirschberger et al. [65] also propose their parametric quadratic programming algorithms.
For (1), the nondominated set is the upper part of the minimum-variance frontier. We formulate the lower part of the minimum-variance frontier as follows:
min z 1 = x T Σ x min z 2 = x T μ 2 s . t . x S
Because min z 2 = x T μ 2 is equivalent to ( max z 2 = x T ( μ 2 ) ) , we continuously and exactly compute the lower part of the minimum-variance frontier by Theorem 8 in the following corollary:
Corollary 1.
The lower part of the minimum-variance frontier of (1) is a continuous, strictly decreasing, and strictly convex curve in ( z 1 , z 2 ) space. Moreover, the part is piecewise composed of connected parabolic segments.
In Panel C of Figure 4, we present (42) and the lower part of the minimum-variance frontier and presume that the part is piecewise composed of two connected parabolic segments: segment p 3 to p 4 and segment p 4 to p 5 .
We combine the nondominated set in Panel B of Figure 4 and the lower part of the minimum-variance frontier in Panel C and present the minimum-variance frontier in Panel D.
For (1), we formulate the maximum-variance frontier (as the right boundary of the feasible region) as follows:
max z 1 = x T Σ x s . t . x T μ 2 = e 2 , e 2 [ e 2 m i n , e 2 m a x ] x S
where e 2 is the parameter and [ e 2 m i n , e 2 m a x ] is the range. e 2 m i n and e 2 m a x are respectively the optimal values of (44) and (45) as follows:
min x T μ 2 x S
max x T μ 2 x S
However, we encounter the following difficulties: Firstly, we maximize a convex function z 1 = x T Σ x in (43), so the maximization is complex. Secondly, we can discretely select numerous e 2 [ e 2 m i n , e 2 m a x ] , repetitively solve (43) with the e 2 , and obtain numerous optimal solutions. We present the solutions as points in Panel E of Figure 4. However, the points are only discrete approximations of the maximum-variance frontier. Lastly, the maximum-variance frontier is continuous with unknown mathematical properties (e.g., possibly piecewise monotonicity and convexity). Therefore, the frontier’s intricate structure (e.g., stock 2 as a local maximal value in Panel A) can be overlooked by the discrete approximations.
We combine Panels D and E of Figure 4 and present the approximated feasible region in Panel F.
Determining the minimum-variance surface and feasible region of MOPS (4) is much more complicated than for portfolio selection (1) due to the following reasons: Firstly, researchers have not continuously and exactly resolved (4). Even only for three objectives, Hirschberger et al. [25] harness parametric quadratic programming, design an algorithm, but do not prove the structure of the nondominated set (as comparable to Theorem 8). Secondly for the minimum-variance surface (22), we can encounter infeasibility with inappropriate e 2 e k . Thirdly, setting a single parameter e 2 in (43) is possible, but setting and coordinating e 2 e k in (22) are exponentially more challenging. Lastly, we discretely approximate the minimum-variance surface and maximum-variance surface (as extensions of maximum-variance frontiers (43)) but cannot reveal their structure.

3.6. The Efficient Set and Nondominated Set of (5)

Analytically, Qi et al. [26] derive the efficient set of (5) as follows:
{ x R n x = x m v + λ 2 Δ 2 + λ 3 Δ 3 , λ 2 0 , λ 3 0 }
where
x m v = 1 f Σ 1 1
Δ 2 = Σ 1 μ 2 c f Σ 1 1
Δ 3 = Σ 1 μ 3 e f Σ 1 1
Qi et al. [26] prove Δ 2 and Δ 3 in (48) and (49) as linearly independent as follows:
Theorem 9.
Δ 2 and Δ 3 are linearly independent.
Geometrically by Theorem 9, the efficient set (46) is a 2-dimensional cone. Explicitly in R n , the cone is spanned by Δ 2 and Δ 3 at the origin and translated by x m v . We substitute (46) into (5) and obtain the nondominated set.

3.7. Examining Whether a Point on the Minimum-Variance Surface Is Nondominated

For (5), we present the relationship between the minimum-variance surface and nondominated set and relationship between the minimum-variance surface’s inverse image and efficient set in Figure 5. In Panel A, we present the minimum-variance surface (30). In Panel B, we present the nondominated set by (46). In Panel C, we present the minimum-variance surface’s inverse image (37). We delineate the inverse image as a 2-dimensional affine set (i.e., as created by d 2 and d 3 at the origin and translated by x 1 in R n ) by Theorem 3. In Panel D, we present the efficient set (46). We delineate the efficient set as a 2-dimensional cone (i.e., as spanned by Δ 2 and Δ 3 at the origin and translated by x m v in R n ) by Theorem 9. We prove the efficient set as a subset of the minimum-variance surface’s inverse image below. We delineate the subset relationship in Panel E.
Theorem 10.
The efficient set of (5) is a subset of the minimum-variance surface’s inverse image.
Proof. 
The nondominated set of (5) is a subset of the minimum-variance surface. The efficient set of (5) is the inverse image of the nondominated set of (5). Therefore, the subset relationship holds for the inverse images. Namely, the efficient set of (5) is a subset of the minimum-variance surface’s inverse image. Theorem 10 is proved. □
With λ 2 0 , λ 3 0 in (46), the efficient set is a cone and a subset of the minimum-variance surface’s inverse image. When generalizing the nonnegative condition into λ 2 R , λ 3 R , we prove that the generalized set equals the minimum-variance surface’s inverse image as follows:
Theorem 11.
The minimum-variance surface’s inverse image (37) equals the following set on the basis of the efficient set:
{ x R n x = x m v + λ 2 Δ 2 + λ 3 Δ 3 , λ 2 R , λ 3 R }
Proof. 
By Theorem 3, the minimum-variance surface’s inverse image (37) is 2-dimensional. By Theorem 9, the efficient set (46) is also 2-dimensional. With λ 2 0 , λ 3 0 in (46), the efficient set is a cone and a subset of the minimum-variance surface’s inverse image. When λ 2 0 , λ 3 0 is generalized into λ 2 R , λ 3 R , the generalized set (50) equals the minimum-variance surface’s inverse image. Theorem 11 is proved. □
For a portfolio with weight vector x on the minimum-variance surface (29), we examine whether the portfolio is nondominated by checking whether x is efficient in the following theorem:
Corollary 2.
For any element x of the minimum-variance surface’s inverse image (37), the following linear equations with λ 2 and λ 3 as the unknown is solvable and there is only one solution:
x = x m v + λ 2 Δ 2 + λ 3 Δ 3
Proof. 
Because x is an element of the minimum-variance surface’s inverse image (37), x is an element of (50) by Theorem 11. Namely, there exist λ 2 R , λ 3 R such that (51) holds. Therefore, (51) is solvable.
Suppose that there are multiple solutions for (51). Namely, there are λ 2 b R , λ 3 b R such that
λ 2 b λ 3 b T λ 2 λ 3 T
x = x m v + λ 2 b Δ 2 + λ 3 b Δ 3
We subtract (51) from (53) and obtain as follows:
0 = 0 + ( λ 2 λ 2 b ) Δ 2 + ( λ 3 λ 3 b ) Δ 3
By the equation above, we determine ( λ 2 λ 2 b ) ( λ 3 λ 3 b ) T 0 by (52) and conclude the linear dependence of Δ 2 and Δ 3 . However, the conclusion contradicts the linear independence of Δ 2 and Δ 3 in Theorem 9. Therefore, the supposition is incorrect. Namely, there is only one solution for (51).
Corollary 2 is proved. □

3.8. An Illustration

To illustrate, we select the 47 components of Shanghai Stock Exchange 50 Index from 1 January 2020 to 31 December 2022. We adopt the tentative rating of carbon offset of Qi et al. [71] (Qi et al. [71] preliminarily suggest a scheme of rating carbon offset. They classify carbon offset into four levels of indicators and assign carbon offset as the first-level indicator. They design six second-level indicators (e.g., information disclosure), twenty third-level indicators (e.g., information disclosure willingness), and fifty four fourth-level indicators. They set all fourth-level indicators as binary variables, annually estimate them, and assign them as one with supportive evidences or as zero without supportive evidences. They sum all fourth-level indicators under a third-level indicator and assign it the sum. They sum all third-level indicators under a second-level indicator and assign it the sum. They sum all second-level indicators and assign the sum as carbon offset. They normalize the carbon offset into [ 0 , 1 ] to be compatible with the scale of expected returns. The original data presented in the study are openly available in Mendeley Data at https://data.mendeley.com/datasets/dfd3f8jtft/1). We presume the components’ carbon offset in 2020 as μ 3 in (5).
We collect the components’ monthly returns from 1 January 2020 to 31 December 2020. We compute the sample means of the components’ returns and thus presume the means as μ 2 in (5). We compute the sample covariance matrix of the components’ returns. Because there are only 12 monthly returns, the rank of the 47 × 47 sample covariance is maximally 12. We follow Ledoit and Wolf [72] and compute Σ in (5) as follows:
Σ = 0.5 × I + ( 1 0.5 ) × sample covariance matrix
where I is a 47 × 47 identity matrix. We compute the rank and condition number of Σ as 47 and 5.1385. Σ is invertible and positive definite.
Ledoit and Wolf [72] encouragingly shrink sample covariance matrices. However, it could be a pity that, in their series of research (e.g., Ledoit and Wolf [73]), they do not suggest the appropriate shrinkage intensity. Or the appropriate shrinkage intensity may not exist consistently. To the best of our knowledge, researchers distinctively report the appropriate shrinkage intensity. For instance, Ranazzi et al. [74] suggest the appropriate shrinkage intensity as 0.5 under some conditions. Therefore, we adopt 0.5 in (54).
After assigning the parameters of (5), we utilize (29) and obtain the minimum-variance surface (6). We have reported (6) in the graphical abstract and introduction. We also obtain the efficient set and nondominated set (the code presented in the study is openly available in Mendeley Data at https://data.mendeley.com/datasets/dfd3f8jtft/1 accessed on 18 August 2026).

4. Heuristically Proving Different Tangent Planes for MOCAPM

We emphasize the scant literature for MOCAPM in Section 3. In this section, we heuristically prove the presence of different tangent planes which are tangent to the nondominated set of (5) and pass through the risk-free asset. To the best of our knowledge, there exists no such research.

4.1. Suggesting and Justifying MOCAPM for the Investments of Carbon Offset

To the best of our knowledge, the literature for MOCAPM is limited. Ingersoll [75] investigates skewness, conjures the nondominated set and a tangent line, and conjures CAPM. Qi et al. [71] demonstrate the presence of different tangent lines. Qi [62] tries to categorize minimum-variance surfaces (some scientists (e.g., Jurczenko and Maillet [76] and Harvey and Siddique [21]) probe CAPM with skewness and kurtosis by utility function methods. Here, we deploy MOPS).
We have sketched the research for asset pricing in Section 2. We contrast CAPM with factor models as follows:
  • For the presumptions, CAPM entail strong presumptions, while factor models entail empirical presumptions.
  • For the factors, CAPM entail precisely one factor as the market portfolio, while factor models may indistinctly entail multiple factors.
  • For the justification, CAPM theoretically justify the market portfolio by presumptions of homogeneity and market equilibrium. Inversely, factor models justify the factors historically instead of theoretically.
  • For the integrity, the research lines of progressing from portfolio selection to CAPM are rational, and the research for portfolio selection and the research for CAPM jointly benefit. Inversely, the association between portfolio selection and factor models is weak.
In order to formulate the investments of carbon offset, we extend portfolio selection into MOPS and CAPM into MOCAPM. We compare MOCAPM with factor models as follows:
  • For presumptions, MOCAPM entail strong presumptions, while factor models entail practical presumptions.
  • For the factors, MOCAPM entail precisely one factor as the market portfolio, while factor models may indistinctly entail multiple factors.
  • For the justification, MOPS can act as a theoretical basis of MOCAPM. By the classical transition from portfolio selection to CAPM, the extended transition from MOPS to MOCAPM can be introductorily envisioned. However, key steps for definitely deriving MOCAPM (e.g., presumptions of homogeneity, a common tangent plane, the market portfolio as the tangent point, and market equilibrium) must be rigorously proved. In contrast, factor models justify the factors historically instead of theoretically.
  • For the integrity, the research lines of progressing from MOPS to MOCAPM are rational, and the research for MOPS and the research for MOCAPM jointly benefit. Inversely, the association between MOPS and factor models is weak.

4.2. Geometrical Guidance

Initially, we emphasize the difficulty in readily locating tangent planes to the nondominated set of (5) for the following reasons:
  • The minimum-variance surface as a superset of the nondominated set is complex (as expressed in (29)–(36)).
  • With the cross-term z 2 z 3 in (29), the surface is even rotated (as proved by Qi et al. [26]).
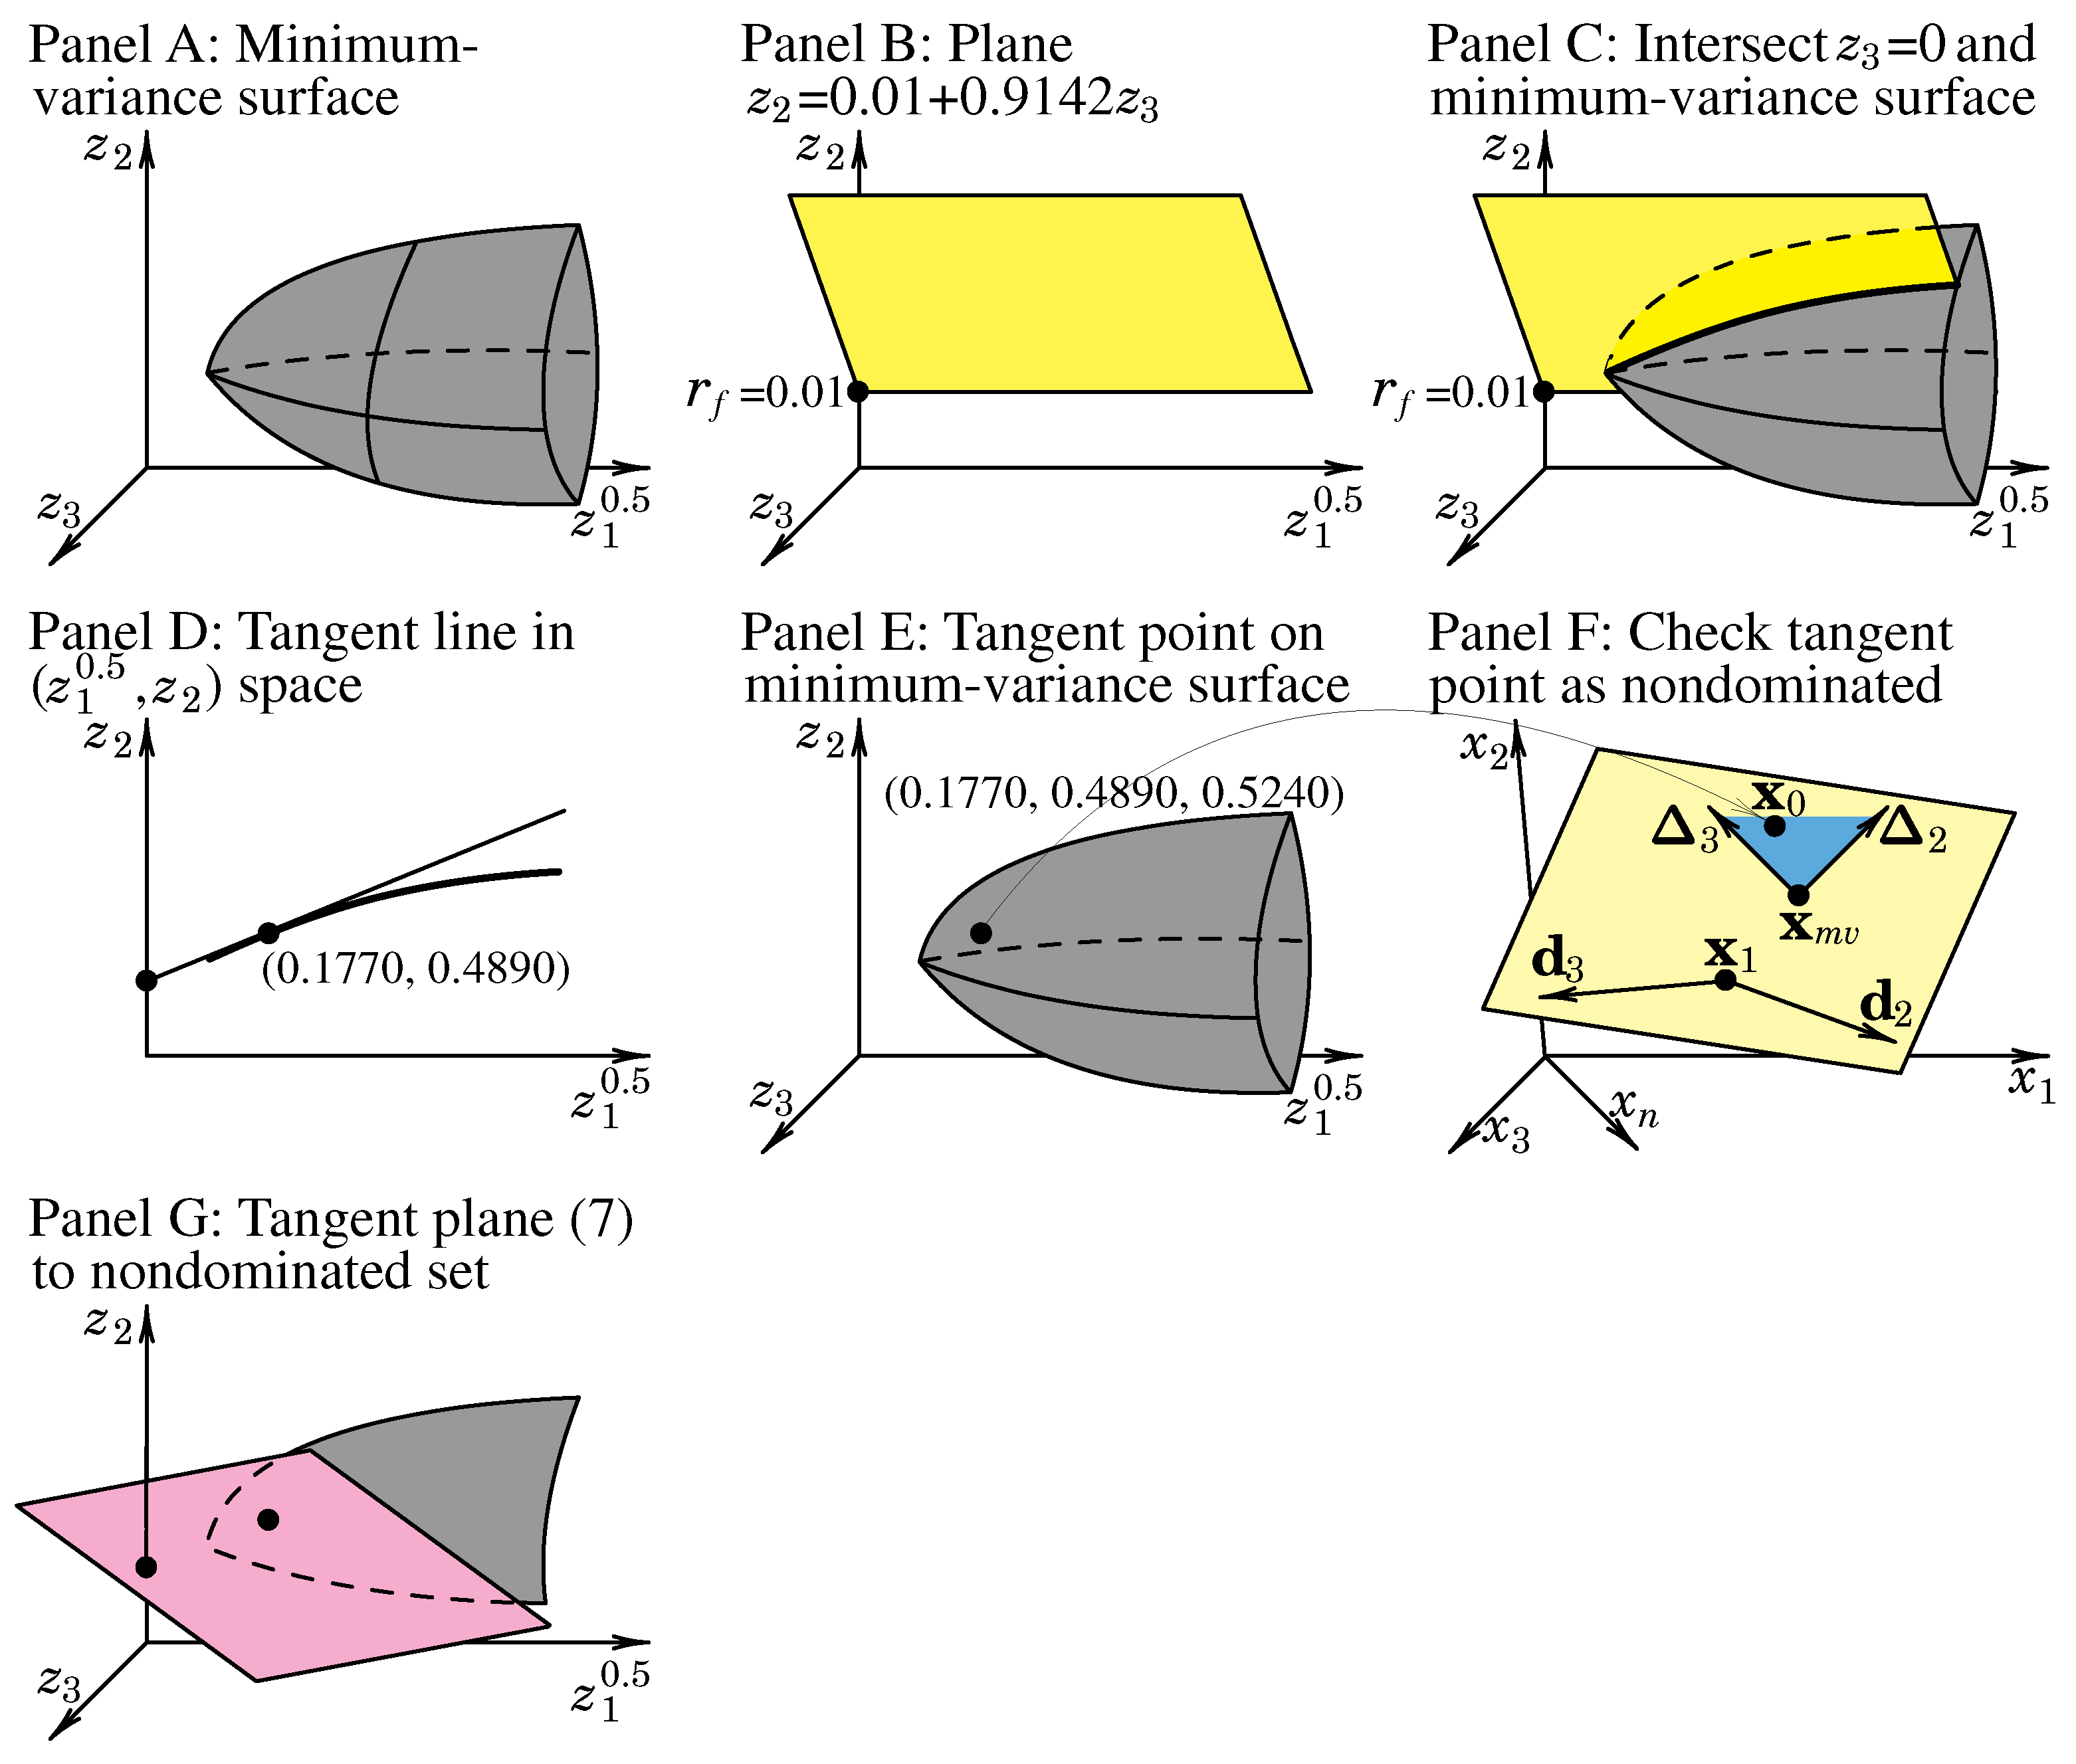
Therefore, we present a geometrical guidance for locating tangent planes in Figure 6.
We analyze ( z 1 0.5 , z 2 , z 3 ) space and rephrase the minimum-variance surface (6) as follows:
z 1 0.5 = ( 0.0724 z 2 2 + 0.6196 z 3 2 0.0028 z 2 z 3 0.0342 z 2 0.5605 z 3 + 0.1550 ) 0.5
  • In Panel A of Figure 6, we present the minimum-variance surface in ( z 1 0.5 , z 2 , z 3 ) space.
  • In Panel B, we present the risk-free asset ( 0 , r f , 0 ) with r f = 0.01 by Assumption 4 and a plane z 2 = 0.01 + 0.9142 z 3 . The plane passes through the risk-free asset.
  • In Panel C, plane z 2 = 0.01 + 0.9142 z 3 intersects the minimum-variance surface. We present the intersection as a thick curve.
  • In Panel D, we target the circumstance only on plane z 2 = 0.01 + 0.9142 z 3 or z 3 = z 2 0.01 0.9142 , ignore z 3 = 0 , and analyze in ( z 1 0.5 , z 2 ) space. We follow Sharpe [14] and draw a tangent line which is tangent to the intersection and passes through the risk-free asset. We determine the tangent point ( 0.1770 , 0.4890 ) .
  • In Panel E, we rephrase the tangency in ( z 1 0.5 , z 2 , z 3 ) space with the tangent point ( 0.1770 , 0.4890 , 0.5240 ) .
  • In Panel F, we check the tangent point as nondominated by Corollary 2.
  • In Panel G, we compute the tangent plane with the tangent point ( 0.1770 , 0.4890 , 0.5240 ) by Definition 4. The plane contains the tangent line by Theorem 1 and thus passes through the risk-free asset.

4.3. Estimating the First Tangent Plane via the Intersecting Plane z 2 = 0.01 + 0.9142 z 3

We follow the guidance and calculate the first tangent plane in this subsection.

4.3.1. Locating the Intersection in Panels A–C of Figure 6

We substitute the intersecting plane z 2 = 0.01 + 0.9142 z 3 or z 3 = z 2 0.01 0.9142 to (55) and locate the intersection (as a hyperbola) as follows:
z 1 0.5 = ( 0.0724 z 2 2 + 0.6196 ( z 2 0.01 0.9142 ) 2 0.0028 z 2 z 2 0.01 0.9142 0.0342 z 2 0.5605 z 2 0.01 0.9142 + 0.1550 ) 0.5 = ( 0.0724 z 2 2 + 0.6196 z 2 2 0.02 z 2 + 0.0001 0.8358 0.0028 z 2 2 0.01 z 2 0.9142 0.0342 z 2 0.5605 z 2 0.01 0.9142 + 0.1550 ) 0.5 = ( 0.0724 z 2 2 + 0.7414 z 2 2 0.0148 z 2 + 0.0001 0.0031 z 2 2 + 0.00003 z 2 0.0342 z 2 0.6131 z 2 + 0.0061 + 0.1550 ) 0.5 = ( 0.8107 z 2 2 0.6621 z 2 + 0.1612 ) 0.5

4.3.2. Estimating the Tangency in Panel D of Figure 6

In 2-dimensional ( z 1 0.5 , z 2 ) space, we directly visualize and analyze. We follow classical textbooks (e.g., Larson and Edwards (p. 102, [44])) and calculate the tangent line in the following proposition:
Proposition 1.
In ( z 1 0.5 , z 2 ) space, there exists a tangent line which is tangent to the intersection (56) and is through the risk-free asset r f with the following expression:
0.4790 z 1 0.5 0.1770 z 2 + 0.0018 = 0
The tangent point is as follows:
( 0.1770 , 0.4890 )
Proof. 
For the tangent line, we suppose the tangent point to the intersection (56) in ( z 1 0.5 , z 2 ) space as follows:
( z 10 0.5 , z 20 )
We fix the line by connecting the tangent point (59) and ( 0 , r f ) with r f = 0.01 . We evaluate the line slope as follows:
z 10 0.5 0 z 20 0.01
We follow Larson and Edwards (pp. 102 and 111, [44]) and measure the derivative of the intersection (56) as follows:
d ( z 1 0.5 ) d z 2 = 1.6214 z 2 0.6621 2 z 1 0.5
At the tangent point (59), the tangent line’s slope equals the derivative. We equalize (60) and (61) at the tangent point (59) as follows:
z 10 0.5 z 20 0.01 = 1.6214 z 20 0.6621 2 z 10 0.5 ( z 20 0.01 ) ( 1.6214 z 20 0.6621 ) = 2 z 10
We substitute z 10 of (56) into (62) and determine the root z 20 as follows:
( z 20 0.01 ) ( 1.6214 z 20 0.6621 ) = 2 ( 0.8107 z 2 2 0.6621 z 2 + 0.1612 ) 1.6214 z 20 2 0.0162 z 20 0.6621 z 20 + 0.0066 = 1.6214 z 20 2 1.3242 z 20 + 0.3224 0.6459 z 20 = 0.3158 z 20 = 0.4890
We substitute (63) into (56) and compute z 10 0.5 as follows:
z 10 0.5 = ( 0.8107 × 0.4890 2 0.6621 × 0.4890 + 0.1612 ) 0.5 = 0.1770
We have calculated the tangent point (58) by (63) and (64). Eventually, we calculate the tangent line by connecting the tangent point (58) and ( 0 , r f ) with r f = 0.01 as follows:
z 1 0.5 0 z 2 0.01 = 0.1770 0 0.4890 0.01 z 1 0.5 z 2 0.01 = 0.1770 0.4790 0.4790 z 1 0.5 0.1770 z 2 + 0.0018 = 0
The equation above matches (57). Proposition 1 is numerically proved. □

4.3.3. Rephrasing the Tangency in ( z 1 0.5 , z 2 , z 3 ) Space in Panel E of Figure 6

We insert z 20 = 0.4890 in (58) into the intersecting plane z 2 = 0.01 + 0.9142 z 3 and compute z 30 as follows:
z 30 = 0.4890 0.01 0.9142 = 0.5240
With (65), we rephrase the tangent point (58) in ( z 1 0.5 , z 2 , z 3 ) space as follows:
( 0.1770 , 0.4890 , 0.5240 )
Similarly, with the intersecting plane z 2 = 0.01 + 0.9142 z 3 or z 3 = z 2 0.01 0.9142 , we rephrase the tangent line (57) in ( z 1 0.5 , z 2 , z 3 ) space as follows:
0.4790 z 1 0.5 0.1770 z 2 + 0.0018 = 0 z 3 = z 2 0.01 0.9142

4.3.4. Examining Whether the Tangent Point Is Nondominated in Panel F of Figure 6

We substitute z 20 = 0.4890 and z 30 = 0.5240 in (66) into (37) and compute the tangent point’s portfolio weight vector x 0 as follows:
x 0 = x 1 + 0.4890 d 2 + 0.5240 d 3
By Corollary 2, we substitute x 0 in (68) into (51) as follows:
x 0 = x m v + λ 2 Δ 2 + λ 3 Δ 3
We solve the equations above and report λ 2 and λ 3 as follows:
λ 2 = 0.0352 > 0 λ 3 = 0.0874 > 0
With λ 2 > 0 and λ 3 > 0 , we determine x 0 in (68) as efficient by (46). Therefore, we determine the tangent point in (66) as nondominated.

4.3.5. Estimating the First Tangent Plane (7) in Panel G of Figure 6

With the tangent point (66), we utilize Definition 4 and calculate the first tangent plane in the following proposition:
Proposition 2.
With the tangent point (66), the tangent plane to (55) is (7).
Proof. 
We rephrase the minimum-variance surface (55) in the form of F ( z 1 0.5 , z 2 , z 3 ) = 0 as follows:
F ( z 1 0.5 , z 2 , z 3 ) = z 1 0.5 ( 0.0724 z 2 2 + 0.6196 z 3 2 0.0028 z 2 z 3 0.0342 z 2 0.5605 z 3 + 0.1550 ) 0.5 = 0
We compute the partial derivatives of F ( z 1 0.5 , z 2 , z 3 ) as follows:
F z 1 0.5 = F z 1 0.5 = 1
F z 2 = F z 2 = 0.1448 z 2 + 0.0028 z 3 + 0.0342 2 ( 0.0724 z 2 2 + 0.6196 z 3 2 0.0028 z 2 z 3 0.0342 z 2 0.5605 z 3 + 0.1550 ) 0.5
F z 3 = F z 3 = 1.2392 z 3 + 0.0028 z 2 + 0.5605 2 ( 0.0724 z 2 2 + 0.6196 z 3 2 0.0028 z 2 z 3 0.0342 z 2 0.5605 z 3 + 0.1550 ) 0.5
We follow (14), substitute the tangent point ( 0.1770 , 0.4890 , 0.5240 ) in (66) into (69)–(71), and compute the gradient at the tangent point as follows:
F z 1 0.5 ( 0.1770 , 0.4890 , 0.5240 ) = 1 F z 2 ( 0.1770 , 0.4890 , 0.5240 ) = 0.0993 F z 3 ( 0.1770 , 0.4890 , 0.5240 ) = 0.2472
With the tangent point ( 0.1770 , 0.4890 , 0.5240 ) (66) and its gradient (72), we utilize Definition 4, compute the tangent plane, and rearrange it as follows:
1 ( z 1 0.5 0.1770 ) 0.0993 ( z 2 0.4890 ) 0.2472 ( z 3 0.5240 ) = 0 z 1 0.5 0.0993 z 2 0.2472 z 3 + 0.0010 = 0
The model above matches (7). Proposition 2 is numerically proved. □
Moreover, we confirm Theorem 1 and prove that the tangent line (67) lies on the tangent plane (7) in the following proposition:
Proposition 3.
The tangent line (67) lies on the tangent plane (7).
Proof. 
We substitute the tangent line (67) into the tangent plane (7) as follows:
z 1 0.5 0.0993 z 2 0.2472 z 3 + 0.0010 = 0 0.1770 z 2 0.0018 0.4790 0.0993 z 2 0.2472 z 2 0.01 0.9142 + 0.0010 = 0.3695 z 2 0.0038 0.0993 z 2 0.2704 z 2 + 0.0027 + 0.0010 = 0
With the result 0, the tangent line lies on the tangent plane. Proposition 3 is numerically proved. □

4.4. Estimating the Second Tangent Plane via the Intersecting Plane z 2 = 0.01 + 3.1243 z 3

We follow the computation style of the previous subsection.

4.4.1. Locating the Intersection in Panels A–C

We substitute the intersecting plane z 2 = 0.01 + 3.1243 z 3 or z 3 = z 2 0.01 3.1243 to (55) and locate the intersection (as a hyperbola) as follows:
z 1 0.5 = ( 0.0724 z 2 2 + 0.6196 ( z 2 0.01 3.1243 ) 2 0.0028 z 2 z 2 0.01 3.1243 0.0342 z 2 0.5605 z 2 0.01 3.1243 + 0.1550 ) 0.5 = ( 0.0724 z 2 2 + 0.6196 z 2 2 0.02 z 2 + 0.0001 9.7613 0.0028 z 2 2 0.01 z 2 3.1243 0.0342 z 2 0.5605 z 2 0.01 3.1243 + 0.1550 ) 0.5 = ( 0.0724 z 2 2 + 0.0635 z 2 2 0.0013 z 2 + 0.0000 0.0009 z 2 2 + 0.0000 z 2 0.0342 z 2 0.1794 z 2 + 0.0018 + 0.1550 ) 0.5 = ( 0.1350 z 2 2 0.2149 z 2 + 0.1568 ) 0.5

4.4.2. Estimating the Tangency in Panel D

We calculate the tangent line in the following proposition:
Proposition 4.
In ( z 1 0.5 , z 2 ) space, there exist a tangent line which is tangent to the intersection (73) and is through the risk-free asset r f with the following expression:
1.4583 z 1 0.5 0.3638 z 2 + 0.0036 = 0
The tangent point is as follows:
( 0.3638 , 1.4683 )
Proof. 
We follow the proof structure of Proposition 1. We suppose the tangent point to the intersection (73) as follows:
( z 10 0.5 , z 20 )
We fix the tangent line by connecting the tangent point (76) and ( 0 , r f ) with r f = 0.01 . We evaluate the line slope as follows:
z 10 0.5 0 z 20 0.01
We measure the derivative of the intersection (73) as follows:
d ( z 1 0.5 ) d z 2 = 0.2700 z 2 0.2149 2 z 1 0.5
We equalize (77) and (78) as follows:
z 10 0.5 z 20 0.01 = 0.2700 z 20 0.2149 2 z 10 0.5 ( z 20 0.01 ) ( 0.2700 z 20 0.2149 ) = 2 z 10
We substitute z 10 of (73) into (79) and determine the root z 20 as follows:
( z 20 0.01 ) ( 0.2700 z 20 0.2149 ) = 2 ( 0.1350 z 2 2 0.2149 z 2 + 0.1568 ) 0.2700 z 20 2 0.0027 z 20 0.2149 z 20 + 0.0021 = 0.2700 z 20 2 0.4297 z 20 + 0.3136 0.2122 z 20 = 0.3115 z 20 = 1.4683
We substitute (80) into (73) and compute z 10 0.5 as follows:
z 10 0.5 = ( 0.1350 × 1.4683 2 0.2149 × 1.4683 + 0.1568 ) 0.5 = 0.3638
We have calculated the tangent point (75) by (80) and (81). Eventually, we calculate the tangent line by connecting the tangent point (75) and ( 0 , r f ) with r f = 0.01 as follows:
z 1 0.5 0 z 2 0.01 = 0.3638 0 1.4683 0.01 z 1 0.5 z 2 0.01 = 0.3638 1.4583 1.4583 z 1 0.5 0.3638 z 2 + 0.0036 = 0
The equation above matches (74). Proposition 4 is numerically proved. □

4.4.3. Rephrasing the Tangency in ( z 1 0.5 , z 2 , z 3 ) Space in Panel E

We insert z 20 = 1.4683 in (75) into the intersecting plane z 2 = 0.01 + 3.1243 z 3 and compute z 30 as follows:
z 30 = 1.4683 0.01 3.1243 = 0.4667
With (82), we rephrase the tangent point (75) in ( z 1 0.5 , z 2 , z 3 ) space as follows:
( 0.3638 , 1.4683 , 0.4667 )
Similarly with the intersecting plane z 2 = 0.01 + 3.1243 z 3 or z 3 = z 2 0.01 3.1243 , we rephrase the tangent line (74) in ( z 1 0.5 , z 2 , z 3 ) space as follows:
1.4583 z 1 0.5 0.3638 z 2 + 0.0036 = 0 z 3 = z 2 0.01 3.1243

4.4.4. Examining Whether the Tangent Point Is Nondominated in Panel F

We substitute z 20 = 1.4683 and z 30 = 0.4667 in (83) into (37) and compute the tangent point’s portfolio weight vector x 0 as follows:
x 0 = x 1 + 1.4683 d 2 + 0.4667 d 3
By Corollary 2, we substitute x 0 in (85) into (51) as follows:
x 0 = x m v + λ 2 Δ 2 + λ 3 Δ 3
We solve the equations above and report λ 2 and λ 3 as follows:
λ 2 = 0.1771 > 0 λ 3 = 0.0138 > 0
With λ 2 > 0 and λ 3 > 0 , we determine x 0 in (85) as efficient by (46). Therefore, we determine the tangent point in (83) as nondominated.

4.4.5. Estimating the Second Tangent Plane (8) in Panel G

With the tangent point (83), we calculate the second tangent plane in the following proposition:
Proposition 5.
With the tangent point (83), the tangent plane to (55) is (8).
Proof. 
We follow the proof structure of Proposition 2. We substitute the tangent point ( 0.3638 , 1.4683 , 0.4667 ) in (83) into (69)–(71) and compute the gradient at the tangent point as follows:
F z 1 0.5 ( 0.3638 , 1.4683 , 0.4667 ) = 1 F z 2 ( 0.3638 , 1.4683 , 0.4667 ) = 0.2434 F z 3 ( 0.3638 , 1.4683 , 0.4667 ) = 0.0189
With the tangent point ( 0.3638 , 1.4683 , 0.4667 ) (83) and its gradient (86), we compute the tangent plane and rearrange it as follows:
1 ( z 1 0.5 0.3638 ) 0.2434 ( z 2 1.4683 ) 0.0189 ( z 3 0.4667 ) = 0 z 1 0.5 0.2434 z 2 0.0189 z 3 + 0.0024 = 0
The model above matches (8). Proposition 5 is numerically proved. □
We heuristically prove that the tangent line (84) lies on the tangent plane (8) in the following proposition:
Proposition 6.
The tangent line (84) lies on the tangent plane (8).
Proof. 
We substitute the tangent line (84) into the tangent plane (8) as follows:
z 1 0.5 0.2434 z 2 0.0189 z 3 + 0.0024 = 0 0.3638 z 2 0.0036 1.4583 0.2434 z 2 0.0189 z 2 0.01 3.1243 + 0.0024 = 0.2495 z 2 0.0025 0.2434 z 2 0.0060 z 2 + 0.0001 + 0.0024 = 0
With the result 0, the tangent line lies on the tangent plane. Proposition 6 is numerically proved. □

4.5. Generalizing from the First Two Tangent Planes to More Tangent Planes

In the two subsections before, by r f = 0.01 (i.e., ( 0 , 0.01 , 0 ) in ( z 1 0.5 , z 2 , z 3 ) space), we identify the
  • First tangent plane by choosing plane z 2 = 0.01 + 0.9142 z 3 ;
  • Second tangent plane by choosing plane z 2 = 0.01 + 3.1243 z 3 .
Similarly, we can identify more tangent planes by choosing more planes (e.g., z 2 = 0.01 + 2.0192 z 3 ) which pass through ( 0 , 0.01 , 0 ) . Of course, we prefer choosing planes z 2 = 0.01 or z 3 = 0 for their simple expressions, but the resultant tangent points are dominated (instead of nondominated) in Panel F of Figure 5.

5. Preliminarily Probing the Conditions for a Unique Tangent Plane for MOCAPM

In Section 4, we heuristically prove different tangent planes as a preliminary geometric exploration for MOCAPM. In this section, we provisionally study the conditions for a unique tangent plane.

5.1. Analyzing the Necessary Conditions for a Unique Tangent Plane

5.1.1. Theoretically Suggesting the Necessary Conditions

We provisionally study the conditions for a unique tangent plane in the following proposition:
Proposition 7.
In order to determine a unique tangent plane which is through the risk-free asset r f and is tangent to (55) at the tangent point as follows:
( z 10 0.5 , z 20 , z 30 ) ,
a necessary condition is that z 20 and z 30 satisfy the following relationship
h ( z 20 , z 30 ) = 0
Proof. 
By Definition 4, the tangent point ( z 10 0.5 , z 20 , z 30 ) (87) decides the tangent plane. Therefore, we need to determine the tangent point.
We follow (14), substitute the tangent point ( z 10 0.5 , z 20 , z 30 ) into (69)–(71), and compute the gradient at the tangent point as follows:
F z 1 0.5 ( z 10 0.5 , z 20 , z 30 ) = 1
F z 2 ( z 10 0.5 , z 20 , z 30 ) = 0.1448 z 20 + 0.0028 z 30 + 0.0342 2 ( 0.0724 z 20 2 0.0028 z 20 z 30 + 0.6196 z 30 2 0.0342 z 20 0.5605 z 30 + 0.1550 ) 0.5
F z 3 ( z 10 0.5 , z 20 , z 30 ) = 0.0028 z 20 1.2392 z 30 + 0.5605 2 ( 0.0724 z 20 2 0.0028 z 20 z 30 + 0.6196 z 30 2 0.0342 z 20 0.5605 z 30 + 0.1550 ) 0.5
With the gradient (89)–(91), we utilize Definition 4, and compute the tangent plane as follows:
1 ( z 1 0.5 z 10 0.5 ) + F z 2 ( z 10 0.5 , z 20 , z 30 ) ( z 2 z 20 ) + F z 3 ( z 10 0.5 , z 20 , z 30 ) ( z 3 z 30 ) = 0
Because the tangent plane passes through the risk-free asset (i.e., ( 0 , r f , 0 ) in ( z 1 0.5 , z 2 , z 3 ) space), we substitute ( 0 , r f , 0 ) into (92) and rearrange as follows:
1 ( 0 z 10 0.5 ) + F z 2 ( z 10 0.5 , z 20 , z 30 ) ( r f z 20 ) + F z 3 ( z 10 0.5 , z 20 , z 30 ) ( 0 z 30 ) = 0 f ( z 10 0.5 , z 20 , z 30 ) = 0 f ( z 10 0.5 , z 20 , z 30 ) = 1 ( 0 z 10 0.5 ) + F z 2 ( z 10 0.5 , z 20 , z 30 ) ( r f z 20 ) + F z 3 ( z 10 0.5 , z 20 , z 30 ) ( 0 z 30 )
Because the tangent point ( z 10 0.5 , z 20 , z 30 ) lies on the surface (55) and satisfies the following:
z 10 0.5 = ( 0.0724 z 20 2 0.0028 z 20 z 30 + 0.6196 z 30 2 0.0342 z 20 0.5605 z 30 + 0.1550 ) 0.5
We substitute (94) into (93), drop z 10 0.5 , and rearrange as follows:
f ( ( 0.0724 z 20 2 0.0028 z 20 z 30 + 0.6196 z 30 2 0.0342 z 20 0.5605 z 30 + 0.1550 ) 0.5 , z 20 , z 30 ) = 0 g ( z 20 , z 30 ) = 0 g ( z 20 , z 30 ) = f ( ( 0.0724 z 20 2 0.0028 z 20 z 30 + 0.6196 z 30 2 0.0342 z 20 0.5605 z 30 + 0.1550 ) 0.5 , z 20 , z 30 )
With merely g ( z 20 , z 30 ) = 0 (95), we cannot uniquely determine z 20 and z 30 . We additionally consider h ( z 20 , z 30 ) = 0 (88) as follows:
g ( z 20 , z 30 ) = 0 h ( z 20 , z 30 ) = 0
With the two equations above for two unknown variables z 20 and z 30 , it is possible that we can solve the equations, compute a group of z 20 and z 30 , and pinpoint a unique z 20 and z 30 . However, solving the equations is difficult, because they are both nonlinear. Moreover, we wish that we can pinpoint a unique z 20 and z 30 , because either a unique z 20 and z 30 is the only solution or we can discard other solutions as inappropriate. Therefore, we underscore (88) as “necessary conditions”.
With the unique z 20 and z 30 , we compute z 10 0.5 by (94) and locate the unique tangent point ( z 10 0.5 , z 20 , z 30 ) . Then, we locate the unique tangent plane by Definition 4. Proposition 7 is illustratively proved. □
Theoretically, h ( z 20 , z 30 ) = 0 (88) is a modeling convention as a preliminary or illustrative mechanism for selecting one tangent plane from several possible tangent planes.

5.1.2. Possibility of Practically Adopting the Necessary Conditions

Practically, adopting Proposition 7 is difficult, because researchers are only preliminarily envisioning MOCAPM and far from obtaining a complete MOCAPM equilibrium equation. Therefore, researchers and investors are not ready for practically adopting Proposition 7.
Only after researchers obtain a complete MOCAPM equilibrium equation and empirically verify it, we could orient investors toward constructing h ( z 20 , z 30 ) = 0 (88) as a preference.

5.2. Designing the Assumptions for MOCAPM

In order to progress from portfolio selection (2) to CAPM (3), Sharpe [14] and Bodie et al. (p. 284, [15]) design homogeneity and perfect markets as follows:
Assumption 5.
Investors are all homogenous and stock markets perfectly function as follows:
  • Investors all operate portfolio selection (2).
  • Investors all plan an identical time horizon and collect an identical set of information for the parameters of (2).
  • Investors all draw tangent lines which are tangent to the nondominated set and are through the risk-free asset.
  • Investors all can freely trade without trading cost or taxes.
On the basis of Assumption 5, Sharpe [14] and Bodie et al. (pp. 288–291, [15]) deduce the market portfolio as all investors’ ultimate choice and reason CAPM (3). We could generalize Assumption 5 to attempt progressing from MOPS to MOCAPM as follows:
Assumption 6.
Investors are all homogenous. Stock markets and carbon offset markets perfectly function as follows:
  • Investors all operate MOPS (5).
  • Investors all plan an identical time horizon and collect an identical set of information for the parameters of (5).
  • Investors all draw tangent planes which are tangent to the nondominated set and are through the risk-free asset.
  • Investors all set an identical h ( z 20 , z 30 ) = 0 in Proposition 7.
  • Investors all can freely trade without trading cost or taxes.
On the basis of Assumption 6, investors and scientists begin the journey for accomplishing MOPS by drawing a unique tangent plane, concluding the tangent point as the market portfolio, and reasoning MOCAPM. However, the journey is challenging, because we shall generalize (3) and price for (5). The generalizing and pricing are difficult due to
  • Pinpointing the tangent point;
  • Estimating a stock’s contribution to the market portfolio’s premium;
  • Linking the contribution with the other objectives;
  • Explicitly deducing MOCAPM.

6. Conclusions

In this section, we list advantages, disadvantages, and future research directions of this paper and conclude.

6.1. Advantages and Disadvantages

Generally, we attempt to enrich the classical research lines of progressing from portfolio selection to CAPM into the extended research lines of progressing from MOPS to MOCAPM. Particularly, we heuristically prove multiple tangent planes for MOCAPM and analyze the conditions for a unique tangent plane.
Meanwhile, we realize this paper’s disadvantages as follows: Firstly, we follow Merton [12] and install only one constraint 1 T x = 1 in (5). The constraint formulation is insufficient, because 1 T x = 1 allows unrealistic short sales. Secondly, there can exist many constraints (e.g., liquidity). Thirdly, we devise (5) for unified markets instead of fragmented markets. In practice, carbon offset markets become fragmented. For instance, carbon offset markets are classified into compliance markets and voluntary markets with different operations. For a firm with financial assets on both kinds of markets, the different operations can trigger different prices which impede (5). Lastly, we overlook the country difference when devising (5). Developing countries can have higher risks in regulation and legislation than developed countries. Investors actually distinguish different countries for the investments of carbon offset and require extra compensations for the investments in developing countries.

6.2. Future Research Directions

We envision the following future research directions: Firstly, we only heuristically prove two tangent planes by numerically analyzing a minimum-variance surface (6) and illustratively verifying Propositions 1–7. In the future, we will try to (generally) prove the existence of infinitely many tangent planes. Namely,
  • We symbolically analyze the minimum-variance surface (29)–(36).
  • We prove that infinitely many planes intersect the minimum-variance surface (29) in ( z 1 0.5 , z 2 , z 3 ) space.
  • We compute tangent points on the intersecting planes.
  • We examine the tangent points as distinct and nondominated.
  • We compute infinitely many tangent planes by the tangent points.
Secondly, we follow the tentative rating of carbon offset of Qi et al. [71] and assign μ 3 in (5). The assignment is preliminary, and we will consider more assignment styles (e.g., by carbon credits, avoided emissions, carbon intensity, ESG greenness, or other environmental metrics).
Thirdly, we offer a pilot illustration by the components of Shanghai Stock Exchange 50 Index here. Although the pilot illustration demonstrates that we can devise the investments of carbon offset by MOPS and MOCAPM, the sampling is restrictive. We will adopt larger samples (e.g., the 500 components of S&P 500 Index). Moreover, we will use the historical risk-free rates (instead of the usage of conceptual risk-free rate r f = 0.01 ), although this paper’s theme is proving different tangent planes heuristically (instead of empirically).
Fourthly, we will apply this paper’s method to ESG and green-asset pricing, because ESG and greenness are relevant to carbon offset. Investors typically utilize portfolio selection for ESG investments (e.g., Integrating ESG in Portfolios by MSCI) (data source: An ESG Framework for Asset Owners Integrating ESG in Portfolios and Benchmarks, MSCI, https://www.msci.com/documents/1296102/23164160/MSCI-ESG-Framework-For-Asset-Owners.pdf, accessed on 20 June 2026). Researchers (e.g., Pástor et al. [77]) typically investigate ESG asset pricing empirically. Therefore, we could try MOPS and preliminarily explore MOCAPM.
Fifthly, as a universal principle in mathematics and finance, models are abstractions of practical worlds (instead of exact formulations). By the models, we simplify complex reality by making assumptions and focusing on core mechanisms and thus inevitably overlook technical factors. For example, our sampling period covers the span of COVID-19 and many policy interventions are introduced in stock markets and the carbon offset markets. We will investigate the interventions, formulate them as constraints, and consider other volatile sampling periods.
Lastly, we will contrast MOPS with utility function methods. von Neumann and Morgenstern [78] instigate maximizing expected utility functions as a fundamental principle for finance. Campbell [13] exhibits the utilization in portfolio selection. Maximizing expected utility functions is more consistent with economic and financial theory than MOPS is. Conversely, maximizing expected utility functions is more complicated than MOPS, because Markowitz (p. 100, [2]) emphasizes the computation burden of maximizing expected utility functions. We will compare the two methods for parameter estimation, optimization, and sensitivity.

6.3. Summarizations

Tentatively, we analytically characterize the minimum-variance surface, construct two distinct tangent planes numerically, verify that the associated tangent points belong to the nondominated set, and propose a preliminary condition for selecting a unique tangent plane. Meanwhile, we fully aware that we do not yet derive a complete MOCAPM equilibrium equation and the derivation is considerably challenging.

6.4. Conclusions

Theoretically, Markowitz [9] and Sharpe [14] pioneer portfolio selection and CAPM. Scientists are enriching portfolio selection into MOPS and experimenting with MOCAPM. Practically, investors are pursuing the investments of carbon offset and aspiring new tools.

Author Contributions

Conceptualization, L.L.; methodology, L.L.; software, L.L.; validation, L.L.; formal analysis, L.L.; investigation, L.L.; resources, L.L.; data curation, Y.Q.; writing—original draft preparation, L.L. and Y.Q.; writing—review and editing, L.L. and Y.Q.; visualization, L.L.; supervision, L.L.; project administration, L.L. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Data Availability Statement

Data are available in a publicly accessible repository. The data presented in this study are openly available in Mendeley at https://data.mendeley.com/datasets/m8vdy86nk9/1 (accessed on 18 August 2026).

Acknowledgments

We would very much like to thank the two anonymous referees for their highly constructive comments.

Conflicts of Interest

The authors declare no conflicts of interest.

Abbreviations

The following abbreviations are used in this manuscript:
CAPMcapital asset pricing models
MOPSmultiple-objective portfolio selection
MOCAPMmultiple-objective capital asset pricing models

Appendix A. Lists of Main Symbols

Appendix A.1. English Symbols

1.  
1 is a vector and is introduced in (2).
2.  
E ( r ) = r f + β ( E ( r m ) r f ) is a model and is introduced in (3).
3.  
F ( x , y , z ) = 0 is a function and is introduced in Definition 4.
4.  
f 1 ( x ) f k ( x ) are objective functions and are introduced in (9).
5.  
k is a scalar, symbolizes the number of objectives, and is introduced in (9).
6.  
n is a scalar and is introduced in Section 1.2.
7.  
S is a set and is introduced in (1) and (9).
8.  
x is a vector and is introduced in Section 1.2.
9.  
x m v is a vector and is introduced in (46).
10.
( x 0 , y 0 , z 0 ) is a vector and is introduced in Definition 4.
11.
Z is a set and is introduced in (9).
12.
z is a vector and is introduced in (9).
13.
z 1 and z 2 are scalars and are introduced in (1).
14.
z 1 0.5 is a scalar and introduced in Section 1.2.
15.
z 3 z k are scalars and are introduced in (4).

Appendix A.2. Greek Symbols

  • F ( x 0 , y 0 , z 0 ) is a vector and is introduced in Definition 4.
  • Δ 2 and Δ 3 are vectors and are introduced in (46).
  • μ 2 is a vector and is introduced in (1).
  • μ 3 μ k are vectors and are introduced in (4).
  • Σ is a matrix and is introduced in (1).

References

  1. Chen, A.; Gerick, L.; Jin, Z. Optimizing portfolios under carbon risk constraints: Setting effective constraints to favor green investments. Energy Econ. 2025, 148, 108634. [Google Scholar] [CrossRef] [Scilit]
  2. Markowitz, H.M. Normative portfolio analysis: Past, present, and future. J. Econ. Bus. 1990, 42, 99–103. [Google Scholar] [CrossRef] [Scilit]
  3. Anquetin, T.; Coqueret, G.; Tavin, B.; Welgryn, L. Scopes of carbon emissions and their impact on green portfolios. Econ. Model. 2022, 115, 105951. [Google Scholar] [CrossRef] [Scilit]
  4. Xue, J.; Dai, X.; Xiao, L.; Wang, Q.; Li, M.C. Multi-objective carbon-energy portfolio optimization under investment horizon heterogeneity. Res. Int. Bus. Financ. 2025, 79, 103036. [Google Scholar] [CrossRef] [Scilit]
  5. Alessi, L.; Ossola, E.; Panzica, R. When do investors go green? Evidence from a time-varying asset-pricing model. Int. Rev. Financ. Anal. 2023, 90, 102898. [Google Scholar] [CrossRef] [Scilit]
  6. Rubinstein, M. Markowitz’s “portfolio selection”: A fifty-year retrospective. J. Financ. 2002, 57, 1041–1045. [Google Scholar] [CrossRef] [Scilit]
  7. Fabozzi, F.J.; Jacobs, B.I.; Levy, K.N. Editors’ introduction: The birth of portfolio theory. J. Portf. Manag. 2024, 50, 2–5. [Google Scholar] [CrossRef] [Scilit]
  8. Markowitz, H.M. Portfolio Selection: Efficient Diversification in Investments, 1st ed.; John Wiley & Sons: New York, NY, USA, 1959. [Google Scholar]
  9. Markowitz, H.M. Portfolio selection. J. Financ. 1952, 7, 77–91. [Google Scholar] [CrossRef] [Scilit]
  10. Hillier, F.S.; Lieberman, G.J. Introduction to Operations Research, 11th ed.; McGraw-Hill Education: New York, NY, USA, 2021. [Google Scholar]
  11. Sharpe, W.F. Portfolio Theory and Capital Markets, 1st ed.; McGraw-Hill: New York, NY, USA, 1970. [Google Scholar]
  12. Merton, R.C. An analytical derivation of the efficient portfolio frontier. J. Financ. Quant. Anal. 1972, 7, 1851–1872. [Google Scholar] [CrossRef] [Scilit]
  13. Campbell, J.Y. Financial Decisions and Markets: A Course in Asset Pricing, 1st ed.; Princeton University Press: Princeton, NJ, USA, 2018. [Google Scholar]
  14. Sharpe, W.F. Capital asset prices: A theory of market equilibrium under conditions of risk. J. Financ. 1964, 19, 425–442. [Google Scholar] [CrossRef] [Scilit]
  15. Bodie, Z.; Kane, A.; Marcus, A.J. Investments, 13th ed.; McGraw Hill LLC: New York, NY, USA, 2024. [Google Scholar]
  16. Markowitz, H.M. Foundations of portfolio selection. J. Financ. 1991, 46, 469–477. [Google Scholar] [CrossRef]
  17. Sharpe, W.F. Optimal Portfolios Without Bounds on Holdings. Online Lecture. Graduate School of Business, Stanford University. 2001. Available online: https://web.stanford.edu/~wfsharpe/mia/opt/mia_opt2.htm (accessed on 1 January 2020).
  18. Markowitz, H.M. How to represent mark-to-market possibilities with the general portfolio selection model. J. Portf. Manag. 2013, 39, 1–3. [Google Scholar]
  19. Fama, E.F. Multifactor portfolio efficiency and multifactor asset pricing. J. Financ. Quant. Anal. 1996, 31, 441–465. [Google Scholar] [CrossRef] [Scilit]
  20. Cochrane, J.H. Presidential address: Discount rates. J. Financ. 2011, 66, 1047–1108. [Google Scholar] [CrossRef] [Scilit]
  21. Harvey, C.R.; Siddique, A. Conditional skewness in asset pricing tests. J. Financ. 2000, 55, 1263–1296. [Google Scholar] [CrossRef] [Scilit]
  22. Lo, A.W.; Petrov, C.; Wierzbicki, M. It’s 11pm—Do you know where your liquidity is? The mean-variance-liquidity frontier. J. Invest. Manag. 2003, 1, 55–93. [Google Scholar]
  23. Pedersen, L.H.; Fitzgibbons, S.; Pomorski, L. Responsible investing: The ESG-efficient frontier. J. Financ. Econ. 2021, 142, 572–597. [Google Scholar] [CrossRef] [Scilit]
  24. Dorfleitner, G.; Leidl, M.; Reeder, J. Theory of social returns in portfolio choice with application to microfinance. J. Asset Manag. 2012, 13, 384–400. [Google Scholar] [CrossRef] [Scilit]
  25. Hirschberger, M.; Steuer, R.E.; Utz, S.; Wimmer, M.; Qi, Y. Computing the nondominated surface in tri-criterion portfolio selection. Oper. Res. 2013, 61, 169–183. [Google Scholar] [CrossRef] [Scilit]
  26. Qi, Y.; Steuer, R.E.; Wimmer, M. An analytical derivation of the efficient surface in portfolio selection with three criteria. Ann. Oper. Res. 2017, 251, 161–177. [Google Scholar] [CrossRef] [Scilit]
  27. Utz, S.; Steuer, R.E. Empirical analysis of the trade-offs among risk, return, and climate risk in multi-criteria portfolio optimization. Ann. Oper. Res. 2025, 353, 53–76. [Google Scholar] [CrossRef] [Scilit]
  28. Steuer, R.E.; Na, P. Multiple criteria decision making combined with finance: A categorized bibliography. Eur. J. Oper. Res. 2003, 150, 496–515. [Google Scholar] [CrossRef] [Scilit]
  29. Zopounidis, C.; Galariotis, E.; Doumpos, M.; Sarri, S.; Andriosopoulos, K. Multiple criteria decision aiding for finance: An updated bibliographic survey. Eur. J. Oper. Res. 2015, 247, 339–348. [Google Scholar] [CrossRef] [Scilit]
  30. Aouni, B.; Doumpos, M.; Pérez-Gladish, B.; Steuer, R.E. On the increasing importance of multiple criteria decision aid methods for portfolio selection. J. Oper. Res. Soc. 2018, 69, 1525–1542. [Google Scholar] [CrossRef] [Scilit]
  31. La Torre, D.; Boubaker, S.; Pérez-Gladish, B.; Zopounidis, C. Preface to the special issue on multidimensional finance, insurance, and investment. Int. Trans. Oper. Res. 2023, 30, 2137–2138. [Google Scholar] [CrossRef] [Scilit]
  32. Ehrgott, M.; Köksalan, M.; Kadziński, M.; Deb, K. Fifty years of multi-objective optimization and decision-making: From mathematical programming to evolutionary computation. Eur. J. Oper. Res. 2025, 330, 1–25. [Google Scholar] [CrossRef] [Scilit]
  33. Steuer, R.E. Multiple Criteria Optimization: Theory, Computation, and Application; John Wiley & Sons: New York, NY, USA, 1986. [Google Scholar]
  34. Wang, Z.; Rangaiah, G.P. Multi-Criteria Decision-Making: Principles, Methods and Programs; CRC Press: Boca Raton, FL, USA, 2026. [Google Scholar]
  35. Qi, Y.; Steuer, R.E. On the analytical derivation of efficient sets in quad-and-higher criterion portfolio selection. Ann. Oper. Res. 2020, 293, 521–538. [Google Scholar] [CrossRef] [Scilit]
  36. Bank, B.; Guddat, J.; Klatte, D.; Kummer, B.; Tammer, K. Non-Linear Parametric Optimization; Birkhäuser Verlag: Basel, Switzerland, 1983. [Google Scholar]
  37. Best, M.J. An algorithm for the solution of the parametric quadratic programming problem. In Proceedings of the Applied Mathematics and Parallel Computing: Festschrift for Klaus Ritter; Fischer, H., Riedmüller, B., Schäffler, S., Eds.; Physica-Verlag: Berlin/Heidelberg, Germany, 1996; pp. 57–76. [Google Scholar]
  38. Goh, C.; Yang, X. Analytic efficient solution set for multi-criteria quadratic programs. Eur. J. Oper. Res. 1996, 92, 166–181. [Google Scholar] [CrossRef] [Scilit]
  39. Jayasekara, P.L.; Adelgren, N.; Wiecek, M.M. On convex multiobjective programs with application to portfolio optimization. J.-Multi-Criteria Decis. Anal. 2019, 27, 189–202. [Google Scholar] [CrossRef] [Scilit]
  40. Jayasekara, P.L.; Pangia, A.C.; Wiecek, M.M. On solving parametric multiobjective quadratic programs with parameters in general locations. Ann. Oper. Res. 2023, 320, 123–172. [Google Scholar] [CrossRef] [Scilit]
  41. Utz, S.; Wimmer, M.; Hirschberger, M.; Steuer, R.E. Tri-criterion inverse portfolio optimization with application to socially responsible mutual funds. Eur. J. Oper. Res. 2014, 234, 491–498. [Google Scholar] [CrossRef] [Scilit]
  42. Utz, S.; Wimmer, M.; Steuer, R.E. Tri-criterion modeling for constructing more-sustainable mutual funds. Eur. J. Oper. Res. 2015, 246, 331–338. [Google Scholar] [CrossRef] [Scilit]
  43. Woodside-Oriakhi, M.; Lucas, C.; Beasley, J. Heuristic algorithms for the cardinality constrained efficient frontier. Eur. J. Oper. Res. 2011, 213, 538–550. [Google Scholar] [CrossRef] [Scilit]
  44. Larson, R.; Edwards, B. Calculus, 12th ed.; Cengage Learning, Inc.: Boston, MA, USA, 2023. [Google Scholar]
  45. Stewart, J.; Clegg, D.; Watson, S. Calculus: Early Transcendentals, 9th ed.; Cengage Learning, Inc.: Boston, MA, USA, 2021. [Google Scholar]
  46. Ross, S.A. The arbitrage theory of capital asset pricing. J. Econ. Theory 1976, 13, 343–362. [Google Scholar] [CrossRef] [Scilit]
  47. Black, F.; Scholes, M. The pricing of options and corporate liabilities. J. Political Econ. 1973, 81, 637–654. [Google Scholar] [CrossRef] [Scilit]
  48. Fama, E.F.; French, K.R. Common risk factors in the returns on stocks and bonds. J. Financ. Econ. 1993, 33, 3–56. [Google Scholar] [CrossRef] [Scilit]
  49. Thaler, R.H. Advances in Behavioral Finance; Princeton University Press: Princeton, NJ, USA, 2005. [Google Scholar]
  50. Gu, S.; Kelly, B.; Xiu, D. Empirical asset pricing via machine learning. Rev. Financ. Stud. 2020, 33, 2223–2273. [Google Scholar] [CrossRef] [Scilit]
  51. Wagner, G.; Weitzman, M.L. Climate Shock: The Economic Consequences of a Hotter Planet; Princeton University Press: Princeton, NJ, USA, 2015. [Google Scholar]
  52. Dechezleprêtre, A.; Nachtigall, D.; Venmans, F. The joint impact of the European Union emissions trading system on carbon emissions and economic performance. J. Environ. Econ. Manag. 2023, 118, 102758. [Google Scholar] [CrossRef] [Scilit]
  53. Luo, C.; Wu, D. Environment and economic risk: An analysis of carbon emission market and portfolio management. Environ. Res. 2016, 149, 297–301. [Google Scholar] [CrossRef] [Scilit]
  54. Mueller, C.; Orgen, P.; Behr, P. Portfolio allocation and optimization with carbon offsets: Is it worth the while? J. Clim. Financ. 2023, 5, 100019. [Google Scholar] [CrossRef] [Scilit]
  55. Bolton, P.; Kacperczyk, M. Do investors care about carbon risk? J. Financ. Econ. 2021, 142, 517–549. [Google Scholar] [CrossRef] [Scilit]
  56. Giroux, T.; Royer, J.; Zerbib, O.D. Empirical asset pricing with score-driven conditional betas. J. Financ. Econom. 2024, 22, 1310–1344. [Google Scholar] [CrossRef] [Scilit]
  57. Kumar, N.; Kayal, P.; Maiti, M. A study on the carbon emission futures price prediction. J. Clean. Prod. 2024, 483, 144309. [Google Scholar] [CrossRef] [Scilit]
  58. Qi, Y.; Wang, Y. Innovating and pricing carbon-offset options of Asian styles on the basis of jump diffusions and fractal Brownian motions. Mathematics 2023, 11, 3614. [Google Scholar] [CrossRef] [Scilit]
  59. Brockwell, P.J.; Davis, R.A. Time Series: Theory and Methods, 1st ed.; Springer: New York, NY, USA, 1987. [Google Scholar]
  60. Steuer, R.E. On the differences between bi-criterion and tri-criterion portfolio selection in graphs. In Proceedings of the 12th International Conference on Information Technology and Quantitative Management, Newark, NJ, USA, 15–17 August 2025; Elsevier: Amsterdam, The Netherlands, 2025. [Google Scholar]
  61. Strang, G. Introduction to Linear Algebra, 6th ed.; Wellesley-Cambridge Press: Wellesley, MA, USA, 2023. [Google Scholar]
  62. Qi, Y. Classifying the minimum-variance surface of multiple-objective portfolio selection for capital asset pricing models. Ann. Oper. Res. 2022, 311, 1203–1227. [Google Scholar] [CrossRef] [Scilit]
  63. Boyd, S.P.; Vandenberghe, L. Convex Optimization, 1st ed.; Cambridge University Press: Cambridge, UK, 2004. [Google Scholar]
  64. Qi, Y.; Wang, Z.; Zhang, S. On analyzing and detecting multiple optima of portfolio optimization. J. Ind. Manag. Optim. 2018, 14, 309–323. [Google Scholar] [CrossRef] [Scilit]
  65. Hirschberger, M.; Qi, Y.; Steuer, R.E. Large-scale MV efficient frontier computation via a procedure of parametric quadratic programming. Eur. J. Oper. Res. 2010, 204, 581–588. [Google Scholar] [CrossRef] [Scilit]
  66. Markowitz, H.M. The optimization of a quadratic function subject to linear constraints. Nav. Res. Logist. Q. 1956, 3, 111–133. [Google Scholar] [CrossRef] [Scilit]
  67. Markowitz, H.M.; Todd, G.P. Mean-Variance Analysis in Portfolio Choice and Capital Markets; Frank J. Fabozzi Associates: New Hope, PA, USA, 2000. [Google Scholar]
  68. Jacobs, B.I.; Levy, K.N.; Markowitz, H.M. Portfolio optimization with factors, scenarios, and realistic short positions. Oper. Res. 2005, 53, 586–599. [Google Scholar] [CrossRef] [Scilit]
  69. Stein, M.; Branke, J.; Schmeck, H. Efficient implementation of an active set algorithm for large-scale portfolio selection. Comput. Oper. Res. 2008, 35, 3945–3961. [Google Scholar] [CrossRef] [Scilit]
  70. Niedermayer, A.; Niedermayer, D. Applying Markowitz’s critical line algorithm. In Proceedings of the Handbook of Portfolio Construction: Contemporary Applications of Markowitz Techniques; Guerard, J.B., Jr., Ed.; Springer: New York, NY, USA, 2010; pp. 383–400. [Google Scholar]
  71. Qi, Y.; Huang, J.; Qi, Z.; Li, Y. On devising carbon offset investments by multiple-objective portfolio selection and exploring multiple-objective capital asset pricing models. Mathematics 2026, 14, 1080. [Google Scholar] [CrossRef] [Scilit]
  72. Ledoit, O.; Wolf, M. Honey, I shrunk the sample covariance matrix. J. Portf. Manag. 2004, 30, 110–119. [Google Scholar] [CrossRef] [Scilit]
  73. Ledoit, O.; Wolf, M. The power of (non-)linear shrinking: A review and guide to covariance matrix estimation. J. Financ. Econom. 2022, 20, 187–218. [Google Scholar] [CrossRef] [Scilit]
  74. Ranazzi, P.H.; Luo, X.; Sampaio, M.A. Covariance scaling: Theory, extension, and applications to ensemble-based history matching. Comput. Geosci. 2026, 30, 13. [Google Scholar] [CrossRef] [Scilit]
  75. Ingersoll, J. Multidimensional security pricing. J. Financ. Quant. Anal. 1975, 10, 785–798. [Google Scholar] [CrossRef] [Scilit]
  76. Jurczenko, E.; Maillet, B. (Eds.) Multi-Moment Asset Allocation and Pricing Models; John Wiley & Sons Ltd.: Chichester, UK, 2006. [Google Scholar]
  77. Pástor, Ľuboš.; Stambaugh, R.F.; Taylor, L.A. Sustainable investing in equilibrium. J. Financ. Econ. 2021, 142, 550–571. [Google Scholar] [CrossRef] [Scilit]
  78. von Neumann, J.; Morgenstern, O. Theory of Games and Economic Behavior, 3rd ed.; Princeton University Press: Princeton, NJ, USA, 1953. [Google Scholar]
Figure 1. Contrasting major methods of multiple-objective portfolio optimization for (4).
Mathematics 14 03156 g001
Figure 2. The relationship between tangent planes and tangent lines.
Mathematics 14 03156 g002
Figure 3. Extending the risk-free asset.
Mathematics 14 03156 g003
Figure 4. The difficulties in determining the feasible region of even portfolio selection (1).
Mathematics 14 03156 g004
Figure 5. The relationships between the minimum-variance surface and nondominated set of (5) and their inverse images.
Mathematics 14 03156 g005
Figure 6. Geometrically locating the first tangent plane.
Mathematics 14 03156 g006
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.