Article

Does Policy Uncertainty Distort Green Innovation? Evidence from Heavy-Polluting Firms in China

1
Department of Economics, Gachon University, Seongnam 13120, Republic of Korea
2
Department of Business Administration, Gachon University, Seongnam 13120, Republic of Korea
*
Author to whom correspondence should be addressed.
These authors contributed equally to this work.
Systems 2026, 14(9), 1082; https://doi.org/10.3390/systems14091082
Submission received: 10 June 2026 / Revised: 15 August 2026 / Accepted: 31 August 2026 / Published: 2 September 2026

Highlights

Please indicate how your work links to systems science via your contributions to systems practice, theory, and/or methodology.
  • Links economic policy uncertainty, financing conditions, and innovation-portfolio composition within a unified systems framework of corporate green transformation.
  • Distinguishes invention from utility-model green patents, a methodological approach that reveals structural shifts hidden by aggregate patent counts.
What are the main findings and/or the implications of the main findings?
  • Economic policy uncertainty reduces substantive green innovation and shifts heavy-polluting firms’ portfolios toward strategic, shorter-cycle patents, even as total green patenting stays stable.
  • Financing constraints are the most robust channel behind this shift, implying that stable economic policy expectations and sustained financing are key to genuine green transformation.

Abstract

Green innovation is essential to the low-carbon transition, but aggregate patent counts may conceal changes in the technological quality of corporate innovation. Using this observation as a starting point, this study asks how economic policy uncertainty (EPU) affects green innovation and its quality structure among Chinese heavy-polluting firms. Using panel data on A-share listed firms from 2010 to 2023, we distinguish green invention patents from green utility model patents and estimate two-way fixed-effects models. We find that EPU significantly reduces substantive green innovation and weakens the relative position of green invention patents, even though strategic green innovation does not decline correspondingly. These patterns hold across alternative patent measures, quality indicators, EPU specifications, and placebo tests. EPU is also associated with tighter financing constraints, higher cash holdings, and weaker bank credit access, and among these three responses, financing constraints offer the most robust independent explanation. Taken together, the results suggest that policy uncertainty can alter the composition of green innovation even when visible patenting activity is maintained, underscoring the importance of stable policy expectations and sustained financing for substantive green innovation.

1. Introduction

Green innovation has become an important pathway through which firms respond to environmental regulation and contribute to sustainable development. Existing studies show that environmental regulation, market incentives, and policy instruments can redirect technological change toward cleaner production and environmental technologies [1,2,3,4,5]. Among the firms facing this pressure most directly are heavy-polluting firms, which face stronger regulatory scrutiny, higher compliance pressure, and greater transition risk. For these firms, green innovation is both a response to environmental requirements and an important means of maintaining long-term competitiveness [6,7].
Yet not all green innovation is created equal. Patents differ substantially in their technological and economic value [8]. In China’s patent system, invention patents generally involve greater technological novelty, more demanding examination requirements, and longer development periods, whereas utility model patents tend to represent more incremental improvements with lower technical thresholds and shorter application cycles. Following the distinction between substantive and strategic green innovation in the existing literature [9], this study treats green invention patents as a proxy for substantive green innovation and green utility model patents as a proxy for strategic green innovation. This classification does not imply that every utility model patent is purely strategic; rather, it captures the relative differences in technological depth, development period, and resource commitment between the two patent types.
Uncertainty adds another layer to this picture. Economic policy uncertainty may influence both the level and the composition of firms’ green innovation: uncertainty shocks can delay investment and alter corporate resource allocation [10,11], and policy uncertainty further affects investment and innovation decisions by increasing ambiguity regarding future demand, financing conditions, regulatory enforcement, and expected returns [12,13]. These effects are particularly relevant for substantive green innovation, since invention-oriented projects generally require sustained financing, longer R&D cycles, and greater tolerance for technological and commercial uncertainty.
Yet the evidence on how EPU actually relates to green innovation remains mixed. Provincial-level research suggests that EPU may stimulate green innovation, particularly in regions with higher levels of marketization and trade openness [14], whereas firm-level evidence indicates that EPU can suppress corporate green innovation in China [15]. These different conclusions may arise from differences in the level of analysis, institutional conditions, firm exposure, and the measurement of green innovation. What matters more for this study is that existing research generally focuses on aggregate green innovation and provides limited evidence on whether uncertainty changes the internal composition of firms’ green patent portfolios.
This is precisely why the distinction between substantive and strategic green innovation is important: because firms may not respond to uncertainty by reducing all green innovation activities uniformly. A heavy-polluting firm may continue to produce visible green patent output while postponing technologically demanding invention projects and relying more heavily on shorter-cycle utility model innovation. Aggregate patent counts may therefore conceal a deterioration in the technological quality of corporate green transformation.
Financial conditions help explain why firms adjust in this particular way. Prior research shows that corporate cash holdings are closely related to financing needs, cash-flow risks, and precautionary liquidity motives [16,17,18], while the SA Index provides a relatively exogenous measure of firms’ financing constraints based on size and age [19]. This is especially true for heavy-polluting firms, whose environmental and transition exposure may increase the risk perceived by creditors and investors, even as substantive green innovation requires stable and continuous funding. When EPU rises, firms may face tighter financing constraints, retain more cash, and experience weaker access to bank credit, making long-term green invention projects more difficult to sustain.
It is this combination of pressures that makes heavy-polluting firms a particularly relevant setting for examining the quality consequences of policy uncertainty: they are simultaneously exposed to general economic uncertainty and industry-specific environmental pressures arising from regulation, credit allocation, compliance costs, and public scrutiny. The combination of stronger external pressure and greater financing vulnerability may lead them to shift from substantive toward strategic green innovation rather than uniformly reducing all green patenting activities.
Against this background, this study examines how EPU affects green innovation and its internal quality structure among Chinese heavy-polluting firms. Using firm-year observations from Chinese A-share listed firms between 2010 and 2023, we distinguish green invention patent applications from green utility model patent applications and construct two indicators of their relative composition. Two-way fixed-effects models are used to determine whether heavy-polluting firms respond differently to changes in EPU after controlling for firm characteristics and common annual shocks.
We find that EPU significantly reduces substantive green innovation and weakens the relative position of invention patents within the green innovation portfolios of heavy-polluting firms, while strategic green innovation does not decline correspondingly—an asymmetry that indicates uncertainty changes the composition of green innovation rather than uniformly reducing all green patenting activities. The findings remain stable across alternative patent measures, alternative quality indicators, standardized and lagged EPU measures, and placebo tests. The financial-channel analysis further shows that EPU is associated with tighter financing constraints, greater cash holdings, and weaker bank credit access; when the three financial responses are considered jointly, financing constraints provide the most robust independent explanation.
Taken together, this study extends the existing literature by shifting attention from the aggregate quantity of green innovation to its internal quality composition. It identifies a form of innovation distortion in which visible green patent output may be maintained while firms reduce their commitment to technologically substantive innovation. The focus on heavy-polluting firms also clarifies how general economic uncertainty interacts with environmental exposure, regulatory pressure, and transition risk. In addition, the study compares financing constraints, precautionary cash holdings, and bank credit access within a common framework, showing that these financial responses are interconnected rather than completely independent. From a systems perspective, the findings illustrate how policy conditions, financial resources, firm characteristics, and innovation portfolio choices jointly shape corporate green transformation.
The remainder of this paper is organized as follows. Section 2 reviews the relevant literature and develops the research hypotheses. Section 3 describes the sample, variables, and empirical models. Section 4 presents the main empirical findings and robustness tests. Section 5 and Section 6 report the financial-channel and heterogeneity analyses, respectively. Section 7 discusses the findings and concludes the study.

2. Literature Review and Hypothesis Development

2.1. Economic Policy Uncertainty and Substantive Green Innovation

Economic policy uncertainty makes it more difficult for firms to anticipate the direction, timing, and continuity of future fiscal, monetary, industrial, and regulatory policies. It creates ambiguity regarding market demand, financing costs, regulatory enforcement, and expected investment returns. Because investment is often difficult to reverse and additional information may become available over time, this uncertainty increases the value of waiting and encourages firms to postpone long-term commitments [20,21]. It can also alter firms’ risk assessments and expected returns, weakening their willingness to undertake projects whose value depends heavily on future policy and market conditions [22,23].
Innovation is not immune to these pressures—if anything, it is especially exposed to them. R&D projects require continuous investment, involve uncertain technological outcomes, and often generate returns only after a prolonged development period, and these characteristics are magnified in substantive green innovation. Compared with shorter-cycle and less technologically demanding innovation, green invention projects generally require greater sunk costs, longer R&D periods, and more sustained resource commitments. Because their innovation assets offer limited collateral value and their commercial prospects are difficult for external investors to evaluate, firms in this position may also encounter substantial information asymmetry and financing frictions [24,25].
Yet existing research offers no uniform answer on how EPU actually affects green innovation. Provincial-level evidence suggests that uncertainty may stimulate green innovation under favorable institutional and market conditions [14], whereas firm-level evidence from China shows that EPU can suppress corporate green innovation [15]. These differing findings indicate that the effect may depend on the level of analysis, firms’ exposure to uncertainty, and the particular type of innovation being examined. They may also point to something the aggregate measures themselves obscure: differences between long-term invention activities and less costly forms of green innovation.
Heavy-polluting firms are where this potential effect should be most visible. Their potential effect is especially relevant for heavy-polluting firms. Their production, investment, and financing decisions are closely connected to environmental regulation, industrial policy, green credit allocation, and future transition requirements. They therefore face not only general uncertainty about economic conditions but also uncertainty concerning emission standards, compliance costs, enforcement intensity, and the future economic value of environmental investment. Research on environmental innovation similarly shows that firms’ innovation decisions are jointly shaped by regulatory pressure, technological opportunities, market demand, and compliance costs [26,27].
The difficulty is that substantive green innovation is difficult to adjust once significant resources have been committed, yet its returns depend strongly on future regulatory and market conditions. So when policy signals become less predictable, heavy-polluting firms may therefore delay new invention projects, reduce the scale of ongoing R&D, or redirect resources toward activities that require shorter commitments. Their stronger environmental exposure and financing sensitivity make such adjustment more likely than in firms facing lower transition and regulatory risks. Accordingly, we propose:
H1. 
Economic policy uncertainty reduces substantive green innovation in heavy-polluting firms.

2.2. Economic Policy Uncertainty and the Quality Structure of Green Innovation

Not all innovation looks the same. Different green innovation is not homogeneous. Different green innovation activities vary in their technological depth, development period, resource requirements, and potential contribution to environmental performance [5]. Patent-based measures should therefore capture not just how much green innovation a firm produces but what kind of technological activity different patents represent.
Existing studies distinguish between substantive and strategic or symbolic green innovation. Substantive green innovation involves relatively deeper technological improvement and greater commitment to long-term environmental transformation, whereas strategic green innovation places greater emphasis on rapid, visible, and comparatively less resource-intensive responses to external expectations [9,28]. Following this distinction, empirical research on Chinese firms commonly treats green invention patents as a proxy for substantive green innovation, and green utility model patents as a proxy for strategic or symbolic green innovation [9,28].
It is worth emphasizing that this distinction is relative, not absolute. It does not imply that every utility model patent is technologically unimportant or that every invention patent necessarily generates substantial environmental value. Rather, invention patents generally represent a greater degree of technological commitment, while utility model patents provide a more observable indication of incremental and shorter-cycle innovation. The classification is therefore used to compare the relative orientation of firms’ green innovation portfolios rather than to determine the value of each individual patent.
Building on this distinction, we define the quality structure of green innovation as the relative composition of substantive and strategic innovation within a firm’s green patent portfolio. A greater share or relative predominance of green invention patents indicates a more invention-oriented and substantive innovation structure; conversely, a relative shift toward green utility model patents indicates that the firm’s green innovation activities have become more concentrated in incremental and shorter-cycle projects. This portfolio perspective captures something aggregate green patent counts alone cannot.
Firms do not necessarily choose this composition freely—regulatory and stakeholder pressure can shape it. Environmental innovation decisions depend on regulatory requirements, technological opportunities, market demand, and the expected costs and returns of innovation [29,30,31]. Prior research also shows that firms may respond to external pressure through highly visible environmental actions without making equally extensive changes in their underlying technologies or production processes [32,33,34]. This is not to say utility model patents should automatically be read as symbolic behavior—but their relatively incremental nature does make them more compatible with firms’ need to demonstrate a prompt environmental response while limiting long-term resource commitments.
Economic policy uncertainty makes this kind of flexibility even more attractive. When future policy direction, enforcement conditions, and investment returns become difficult to predict, firms become more cautious about committing resources to projects that are costly, irreversible, and slow to generate returns. Substantive green innovation is particularly exposed here, because invention-oriented projects require sustained R&D expenditure and longer development periods, whereas strategic green innovation generally permits firms to retain greater flexibility and obtain more immediate and observable innovation outputs.
This trade-off bites hardest for heavy-polluting firms, which must continue to respond to environmental regulation and public scrutiny even when future policy and financing conditions are uncertain. Environmental regulation can encourage firms to undertake technological innovation and improve their long-term competitiveness [35]. Yet when the continuity or implementation of policy becomes difficult to anticipate, heavy-polluting firms may be reluctant to maintain large and long-term invention projects, choosing instead to preserve environmental responsiveness through less resource-intensive green innovation activities.
Taken together, we expect EPU to reduce substantive green innovation more strongly than strategic green innovation. Such an asymmetric response would reduce the relative predominance of green invention patents and weaken the quality structure of firms’ green innovation portfolios. Accordingly, we propose the following hypothesis:
H2. 
Economic policy uncertainty reduces the relative importance of substantive green innovation in heavy-polluting firms.

2.3. Financial Responses and Green Innovation Quality

Substantive green innovation depends on stable and continuous financial support. Existing firm-level evidence indicates that investment and financing decisions are important for understanding how EPU affects corporate green innovation [36]. Compared with strategic green innovation, invention-oriented green projects generally involve larger sunk costs, longer payback periods, and greater uncertainty regarding technological and commercial outcomes [37,38], which makes such projects particularly sensitive to changes in firms’ external financing conditions and internal liquidity allocation. External finance, in other words, is not a peripheral add-on to this story—it is a central link between policy uncertainty and firms’ ability to sustain substantive green innovation.
Policy uncertainty can tighten financing constraints simply by raising the risk perceived by external investors and creditors. Credit markets are affected by information asymmetry, which may lead lenders to ration capital when the quality and expected returns of investment projects are difficult to evaluate [39], and firms facing stronger financing constraints are consequently less able to maintain R&D investment when uncertainty rises [40,41].
This problem cuts especially deep for heavy-polluting firms. Their exposure to environmental regulation, compliance costs, and transition risks may increase creditors’ concerns about future cash flows and investment returns, so when EPU rises, these firms may find it more difficult or expensive to obtain external funds. Because substantive green innovation requires sustained financing over a relatively long period, tighter financing constraints may encourage firms to postpone invention projects or redirect resources toward shorter-cycle green innovation.
Bank credit adds a second layer to this story. It represents an especially important source of external finance for capital-intensive firms, and changes in credit supply and lending standards can affect firms’ access to funding and their ability to undertake long-term investment [42]. Under heightened uncertainty, banks may become more cautious toward heavy-polluting firms precisely because their future compliance costs, environmental liabilities, and transition prospects are difficult to assess.
When bank credit access narrows, firms’ capacity to support invention-oriented green projects narrows with it. Strategic green innovation generally requires smaller and shorter financial commitments and may be easier to preserve when long-term credit becomes less available, so a contraction in bank lending may alter not only the amount of green innovation but also its internal quality composition.
A third channel operates through firms’ own liquidity decisions. When future financing conditions and investment returns become less predictable, firms have stronger incentives to retain cash as a buffer against potential liquidity shortages, and corporate cash holdings are closely related to financing frictions, future investment needs, and precautionary motives [16,17,43,44,45,46].
Holding additional cash can improve short-term financial flexibility, but this comes at a cost: it may also reduce the funds that firms are willing to commit to long-term and uncertain R&D projects. For heavy-polluting firms, the desire to preserve liquidity under regulatory and financial uncertainty may therefore crowd out substantive green innovation, as firms retain cash and limit invention-oriented investment while continuing less costly utility model activities.
These three financial responses are conceptually distinct, but they are far from independent. Financing constraints describe the overall difficulty of obtaining external capital, bank credit access captures the availability of a major financing source, and cash holdings reflect firms’ internal liquidity-preservation decisions. Tighter external financing conditions may simultaneously reduce bank borrowing and encourage precautionary cash accumulation, so the three channels should be viewed as interconnected dimensions of financial conservatism rather than completely independent mechanisms.
As EPU intensifies these conservative financial responses, heavy-polluting firms may become less willing and less able to sustain technologically demanding green invention projects. The resulting resource reallocation is expected to reduce the relative importance of substantive innovation within their green patent portfolios. Accordingly, we propose:
H3. 
Financial conservatism is a channel through which economic policy uncertainty reduces green innovation quality in heavy-polluting firms.

3. Research Methodology

3.1. Sample Selection and Data Sources

This study uses Chinese A-share listed firms from 2010 to 2023 as the research sample. Firm-level financial data are obtained from the China Stock Market & Accounting Research Database (CSMAR), and green patent data are collected from the Chinese Research Data Services Platform (CNRDS).
Economic policy uncertainty is measured using the China EPU index developed by Davis et al. [47], which is constructed from mainland Chinese newspaper coverage following the methodology of Baker et al. [23]. Since the index is available at the monthly frequency, we aggregate monthly values to the annual level using the arithmetic mean and divide by 100 for ease of interpretation, following Li et al. [48].
Heavy-polluting firms are identified following Liu et al. [49], based on the Guidelines on Environmental Information Disclosure of Listed Companies issued by the Ministry of Environmental Protection in 2010 and the Guidelines on Industry Classification of Listed Companies issued by the China Securities Regulatory Commission in 2012. Firms in designated heavy-polluting industries are coded as 1 and all others as 0.
The sample is constructed as follows. Financial firms are excluded because their financial structure and regulatory environment differ substantially from those of non-financial firms. ST and *ST firms are removed to avoid the influence of abnormal financial conditions. Firm-year observations with missing values for key variables are excluded. Finally, continuous variables are winsorized at the 1st and 99th percentiles to mitigate the influence of extreme values. The final sample contains 25,210 firm-year observations.

3.2. Variable Definitions

The dependent variables capture substantive green innovation, strategic green innovation, and the quality structure of green innovation. The key explanatory variable is economic policy uncertainty interacted with a heavy-polluting firm dummy. The model also includes firm-level controls for size, leverage, profitability, growth, cash flow, firm age, ownership concentration, and governance structure. Table 1 reports all variable definitions.
Substantive green innovation is operationalized as the natural logarithm of one plus the number of green invention patent applications. Patent-based measures are a natural starting point here: they are widely used to measure technological and environmental innovation because they provide observable and comparable records of firms’ inventive activities [2,3,4,50], and more recent studies further show that patent-based indicators can capture meaningful differences in the technological and economic value of innovation outputs [51,52]. Compared with utility model patents, invention patents are subject to more demanding requirements regarding novelty, inventiveness, and substantive technological improvement, and generally involve greater technological complexity, longer development periods, and more sustained resource commitment. Green invention patents therefore serve as an appropriate proxy for substantive and relatively high-quality green innovation [6,7,30,31].
Strategic green innovation is operationalized as the natural logarithm of one plus the number of green utility model patent applications. Utility model patents generally involve incremental improvements to the shape, structure, or practical application of existing products and technologies, and relative to invention patents, they have lower technological thresholds, shorter development and examination cycles, and lower application costs—characteristics that make them more compatible with short-term, low-cost, and externally visible responses to regulatory or stakeholder pressure [30,31,32,33,34]. Accordingly, this study uses green utility model patents as a proxy for strategic green innovation. This is not to say that every utility model patent is purely symbolic; rather, the classification captures the relative tendency of utility models to represent less technologically demanding and shorter-cycle innovation than invention patents.
We use patent applications, rather than granted patents, as the baseline measure for two reasons. First, an application is recorded close to the time when a firm makes and discloses its innovation decision, and therefore responds more promptly to contemporaneous changes in economic policy uncertainty. Second, granted patents are affected not only by firms’ innovation activities but also by examination duration, administrative processing, and approval outcomes, and these delays may create a temporal mismatch between the EPU shock and the year in which a patent is granted. Using applications therefore provides a more timely measure of firms’ innovation responses and ensures that invention and utility model patents are observed at a comparable procedural stage. That said, patent grants provide a more stringent indication of successfully examined inventions, so we replace green invention applications with green invention grants in the robustness analysis to mitigate concerns that the baseline results are driven by unsuccessful applications or measurement error.
Patent counts are highly right-skewed and contain a substantial number of zero observations. We therefore apply the transformation l n ( 1 + X ) , which retains observations with no patent applications, reduces the influence of firms with exceptionally large patent portfolios, and improves the comparability of patent activity across firms and years. The transformation does not alter the distinction between invention and utility model patents but produces a continuous measure that is more suitable for the firm-level panel regressions used in this study.
To capture the quality structure of green innovation itself, we construct two complementary indicators. The first, GI Quality Share, is defined as the number of green invention applications divided by the sum of green invention and green utility model applications: a higher value indicates that substantive green innovation accounts for a larger proportion of the firm’s green patent portfolio. Because the denominator is zero for firms without any green patent applications, this measure is defined only for firm-year observations with positive green innovation output.
The second indicator, GI Quality Ratio, is calculated as:
G I Q u a l i t y R a t i o i t = l n ( 1 + G r e e n I n v e n t i o n ) i t l n ( 1 + G r e e n U t i l i t y M o d e l ) i t
Equivalently, this measure can be expressed as the logarithm of the ratio between 1 + green invention applications and 1 + green utility model applications. A higher value indicates a stronger relative predominance of substantive green innovation, whereas a lower value indicates that the firm’s green innovation portfolio is more heavily concentrated in strategic green innovation. GI Quality Ratio is used as the principal quality-structure measure because it retains firm-year observations with zero patent output while still capturing the relative balance between the two types of green innovation; GI Quality Share serves as a complementary indicator for assessing the robustness of the results.
The interaction term between EPU and Heavy Polluter is the main variable of interest, capturing whether heavy-polluting firms respond differently to policy uncertainty in terms of green innovation quality—consistent with prior evidence that policy uncertainty can delay or reduce corporate investment and innovation decisions, especially when projects are irreversible or financially demanding [11].

3.3. Empirical Model

This study employs a two-way fixed-effects panel regression for three reasons. First, the research question concerns whether changes in economic policy uncertainty are associated with different innovation responses between heavy-polluting and other firms over time, and the panel structure allows the analysis to exploit both within-firm temporal variation and cross-sectional differences in firms’ exposure to environmental and transition risks. Second, firm fixed effects absorb time-invariant characteristics, such as persistent managerial style, organizational culture, and industry-related technological capability, while year fixed effects control for macroeconomic, regulatory, and technological shocks common to all firms. Third, the interaction between EPU and the heavy-polluting firm indicator directly captures whether heavy-polluting firms exhibit a differential response to policy uncertainty once these fixed effects and observable firm characteristics are controlled for. Together, this framework provides a suitable empirical approach for testing the directional predictions derived from H1 and H2.
The empirical specifications map directly onto the three hypotheses. Equation (1) tests H1 by using Substantive GI as the dependent variable and tests H2 by using GI Quality Share and GI Quality Ratio as measures of the green innovation quality structure. Equation (2) examines whether EPU alters the three financial responses proposed in H3. Equations (3) and (4) then assess whether these financial responses are associated with green innovation quality, first separately and then jointly. This sequential design lets us distinguish the baseline innovation effect from the proposed financial channels. Because the models rely on observational panel data, however, we interpret the coefficients as conditional associations consistent with the proposed hypotheses rather than definitive causal mediation effects.
To examine whether economic policy uncertainty affects green innovation and its quality structure in heavy-polluting firms, this study estimates the following baseline model:
Y i t = α + β 1 E P U t + β 2 H P i + β 3 E P U t × H P i + γ C o n t r o l s i t + μ i + λ t + ε i t ,
where Y i t represents the dependent variables, including Substantive GI, Strategic GI, GI Quality Share, and GI Quality Ratio. E P U t denotes the annual economic policy uncertainty index divided by 100. H P i is the heavy-polluting firm dummy. C o n t r o l s i t represents the set of firm-level control variables. μ i denotes firm fixed effects, and λ t denotes year fixed effects.
The coefficient of interest is β 3 , which captures the differential effect of economic policy uncertainty on heavy-polluting firms relative to non-heavy-polluting firms. A sig-nificantly negative β 3 in the regression of Substantive GI indicates that EPU reduces high-quality green innovation more strongly in heavy-polluting firms. A significantly negative β 3 in the regression of GI Quality Ratio indicates that EPU deteriorates the qual-ity structure of green innovation in heavy-polluting firms.
To examine the financial conservatism channel, we further estimate the following mechanism model:
M i t = α + δ 1 E P U t + δ 2 H P i + δ 3 E P U t × H P i + γ C o n t r o l s i t + μ i + λ t + ε i t ,
where M i t represents the mechanism variables, including SA Index, Cash Holdings, and Bank Credit Access. These variables capture three related but distinct dimensions of firms’ financial responses to policy uncertainty: overall financing conditions, precautionary liquidity preservation, and access to bank credit. The coefficient of interest is δ 3 . If EPU induces financial conservatism among heavy-polluting firms, δ 3 is expected to be negative for the SA Index, positive for Cash Holdings, and negative for Bank Credit Access. A negative coefficient on the SA Index implies tighter external financing conditions, given that a lower SA value indicates stronger financing constraints.
To further examine whether these financial responses are associated with changes in green innovation quality, we estimate the following model:
Y i t = α + β E P U t × H P i + θ M i t + γ C o n t r o l s i t + μ i + λ t + ε i t ,
where Y i t denotes the GI Quality Ratio, and M i t represents the financial-channel variables, including the SA Index, cash holdings, and bank credit access. We first introduce the three financial variables separately to examine their individual associations with green innovation quality. A positive coefficient on the SA Index indicates that weaker financing constraints are associated with higher green innovation quality; we expect the coefficient on cash holdings to be negative, reflecting the potential crowding-out of long-term innovation investment, and the coefficient on bank credit access to be positive.
Because the national EPU index varies only over time, and the heavy-polluting firm indicator does not vary over time at all, their standalone effects are already absorbed by the year and firm fixed effects, respectively—which is why the interaction term E P U t × H P i remains the primary coefficient of interest.
Given that the three financial responses may not be fully independent of one another, we further estimate the following joint specification:
Y i t = α + β E P U t × H P i + θ 1 S A i t + θ 2 C a s h i t + θ 3 B a n k C r e d i t i t + γ C o n t r o l s i t + μ i + λ t + ε i t ,
Equation (4) simultaneously includes the three financial variables, letting us examine whether each channel retains independent explanatory power after accounting for the other financial responses. We interpret these specifications as financial-channel tests, not as strict causal mediation estimates.
All specifications include firm fixed effects to absorb time-invariant firm characteristics and year fixed effects to control for common macroeconomic and policy shocks, with standard errors clustered at the firm level to account for heteroskedasticity and within-firm serial correlation [53,54]. All statistical analyses were conducted using Stata 16.0 (StataCorp LLC, College Station, TX, USA).

4. Empirical Results

4.1. Descriptive Statistics

Table 2 reports the descriptive statistics of the main variables. Most variables are based on 25,210 firm-year observations, while GI Quality Share has fewer observations because it is defined only for firms with non-zero green innovation output. The mean values of Substantive GI and Strategic GI are 0.666 and 0.647, respectively, with medians of zero for both—a pattern reflecting the uneven distribution of green innovation across firms, consistent with evidence that innovation outcomes tend to concentrate among firms with stronger innovative capacity [55].
The mean value of GI Quality Share is 0.492, indicating that green invention patents account for approximately half of total green innovation among firms with green innovation output. GI Quality Ratio has a mean of 0.019 and a standard deviation of 0.727, reflecting substantial cross-firm variation in the relative balance between substantive and strategic green innovation [9]. About 34.0% of sample firms belong to heavy-polluting industries, providing sufficient cross-sectional variation for the heterogeneity analysis.

4.2. Baseline Regression Results

Table 3 and Table 4 report the baseline regression results. Table 3 presents the parsimonious specification without additional firm-level controls, while Table 4 presents the full specification after including firm-level controls. Across both specifications, the coefficient on EPU × HP is consistently negative and statistically significant in the regressions of Substantive GI, GI Quality Share, and GI Quality Ratio, indicating that EPU exerts a disproportionately negative effect on green innovation quality among heavy-polluting firms [56].
In Table 3, the coefficient on EPU × HP is −0.0732 and significantly negative for Substantive GI at the 1% level, confirming that heavy-polluting firms curtail substantive green innovation more sharply when policy uncertainty rises. The coefficient is also significantly negative for GI Quality Share (−0.0358, significant at the 1% level) and GI Quality Ratio (−0.0929, significant at the 1% level), indicating that EPU affects not only the level of substantive green innovation but also the relative quality composition of firms’ green innovation portfolios. In contrast, the coefficient on EPU × HP for Strategic GI is positive but statistically insignificant (0.0196), suggesting that the negative effect of EPU is concentrated in substantive green innovation activities rather than strategic ones.
Adding firm-level controls in Table 4 leaves the results largely intact. The interaction term EPU × HP remains negative and statistically significant for Substantive GI (−0.0652, p < 0.01), GI Quality Share (−0.0366, p < 0.01), and GI Quality Ratio (−0.0917, p < 0.01), confirming that the baseline finding is robust to controlling for observable firm characteristics. The coefficient on EPU × HP for Strategic GI turns positive and marginally significant (0.0265, p < 0.10), consistent with the interpretation that heavy-polluting firms reallocate innovation efforts toward lower-cost, shorter-cycle patent forms when uncertainty rises [57,58], reflecting a compositional adjustment rather than aggregate expansion.
Together, these results support H1 and H2: EPU suppresses substantive green innovation and deteriorates the green innovation quality structure of heavy-polluting firms.
This negative effect on substantive green innovation echoes firm-level evidence that EPU suppresses corporate green innovation [15], though it stands in contrast to provincial-level evidence reporting a positive relationship between EPU and green innovation [14]. This divergence may simply reflect the present study’s different focus—on heavy-polluting firms and on the internal quality composition of green innovation, rather than on aggregate regional innovation output. More importantly, the fact that strategic green innovation does not decline correspondingly suggests that EPU changes the composition of firms’ green innovation portfolios rather than uniformly reducing all forms of green innovation.

4.3. Marginal Effects of EPU by Firm Type

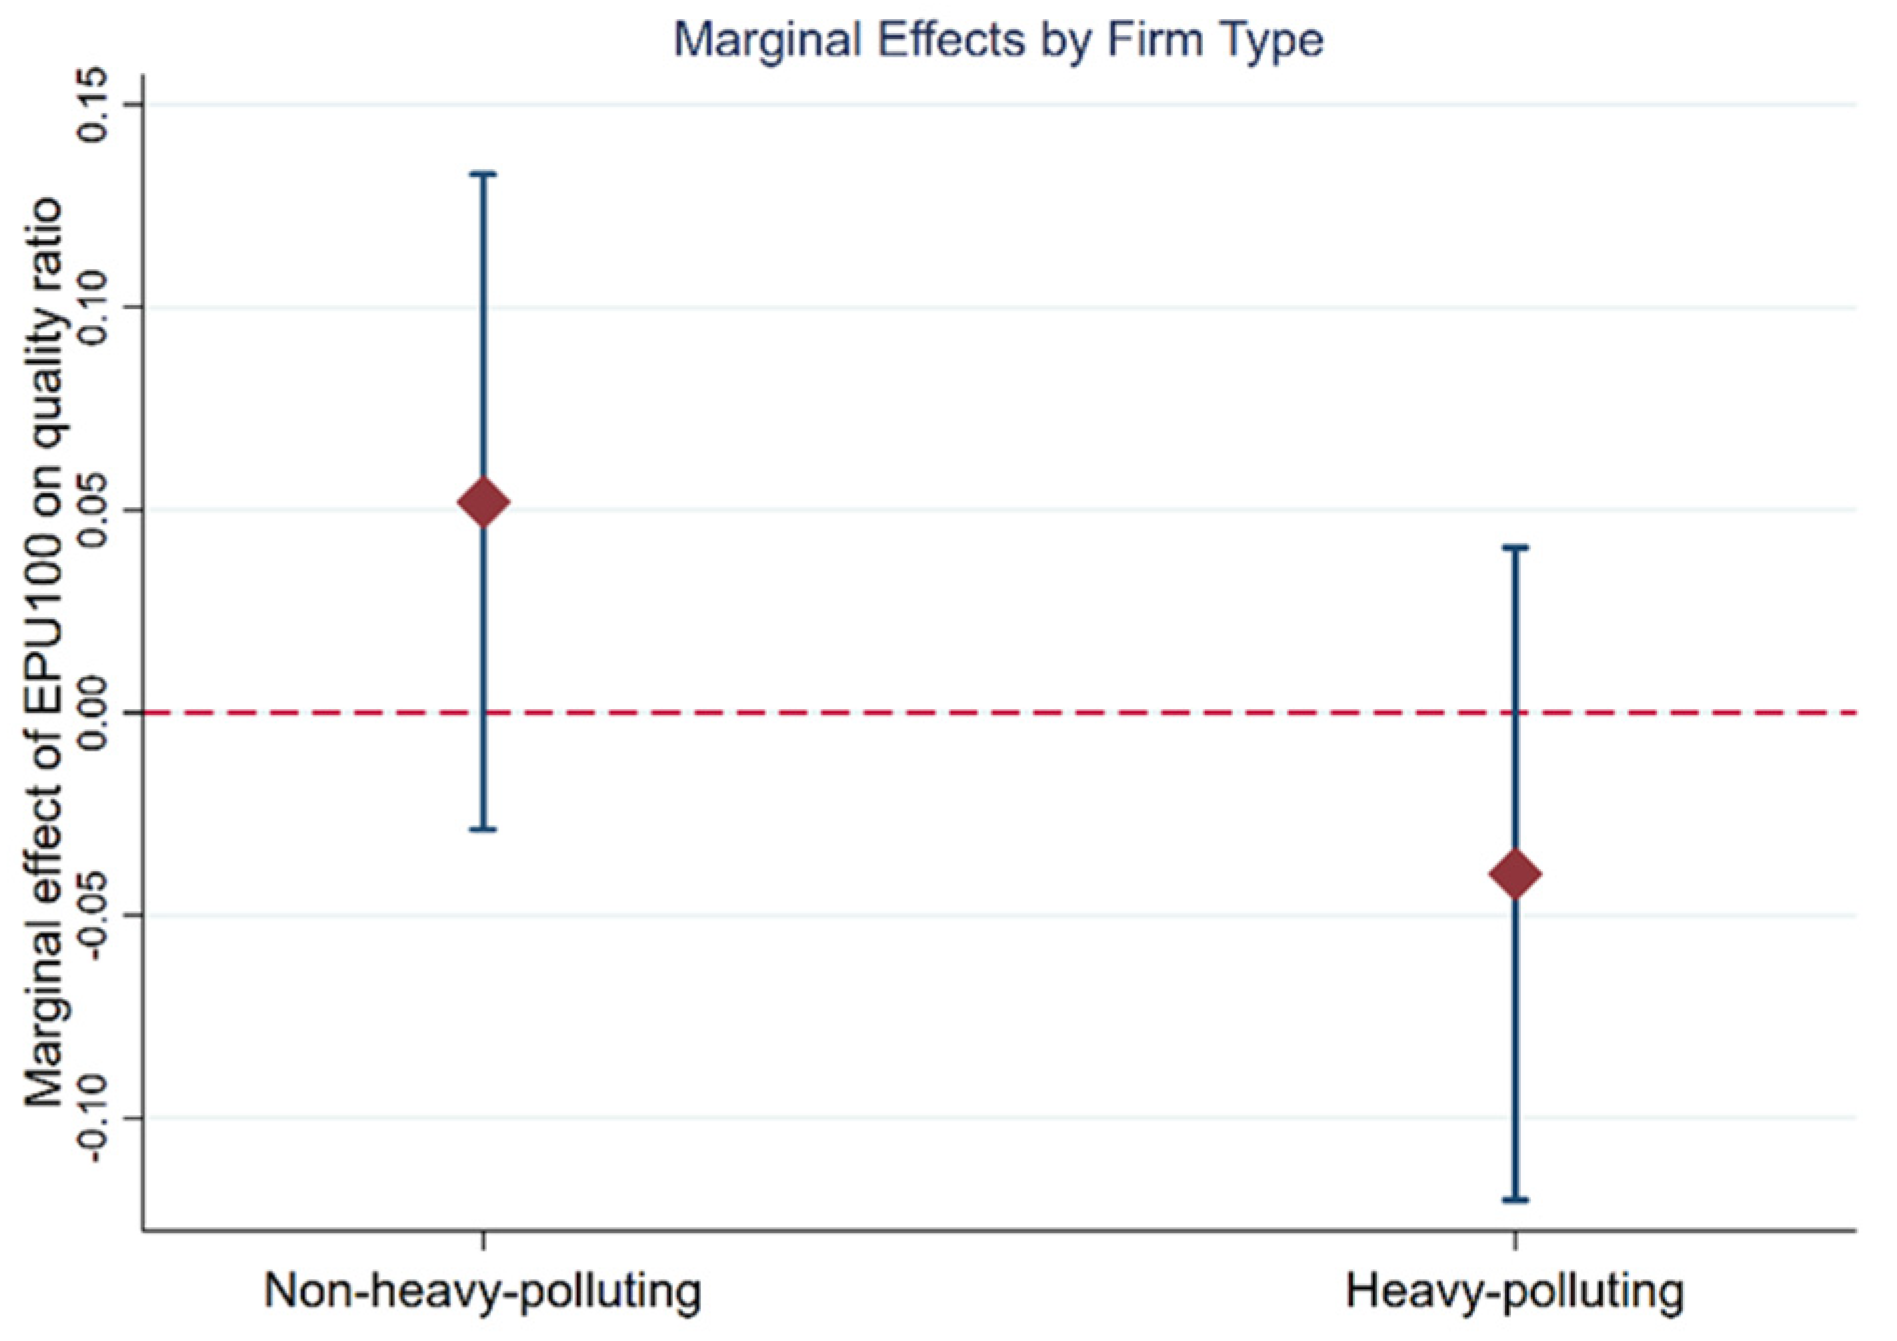
To make the interaction term easier to interpret, Figure 1 presents the marginal effect of EPU on the GI Quality Ratio separately for heavy-polluting and non-heavy-polluting firms. Because a coefficient on an interaction term does not, by itself, represent the conditional effect for either group, the corresponding marginal effects and confidence intervals provide a more informative interpretation [59].
For non-heavy-polluting firms, the estimated marginal effect of EPU is positive but statistically indistinguishable from zero, since the 95% confidence interval crosses zero. For heavy-polluting firms, by contrast, the estimated marginal effect is negative, indicating that higher EPU is associated with a less invention-oriented green innovation portfolio.
This contrast between the two groups aligns with the baseline interaction results and suggests that the deterioration in green innovation quality is primarily associated with the response of heavy-polluting firms, which face greater environmental exposure, transition risk, and policy sensitivity. Figure 1 thus offers a more intuitive representation of the differential relationship captured by the EPU × HP coefficient.

4.4. Robustness Checks

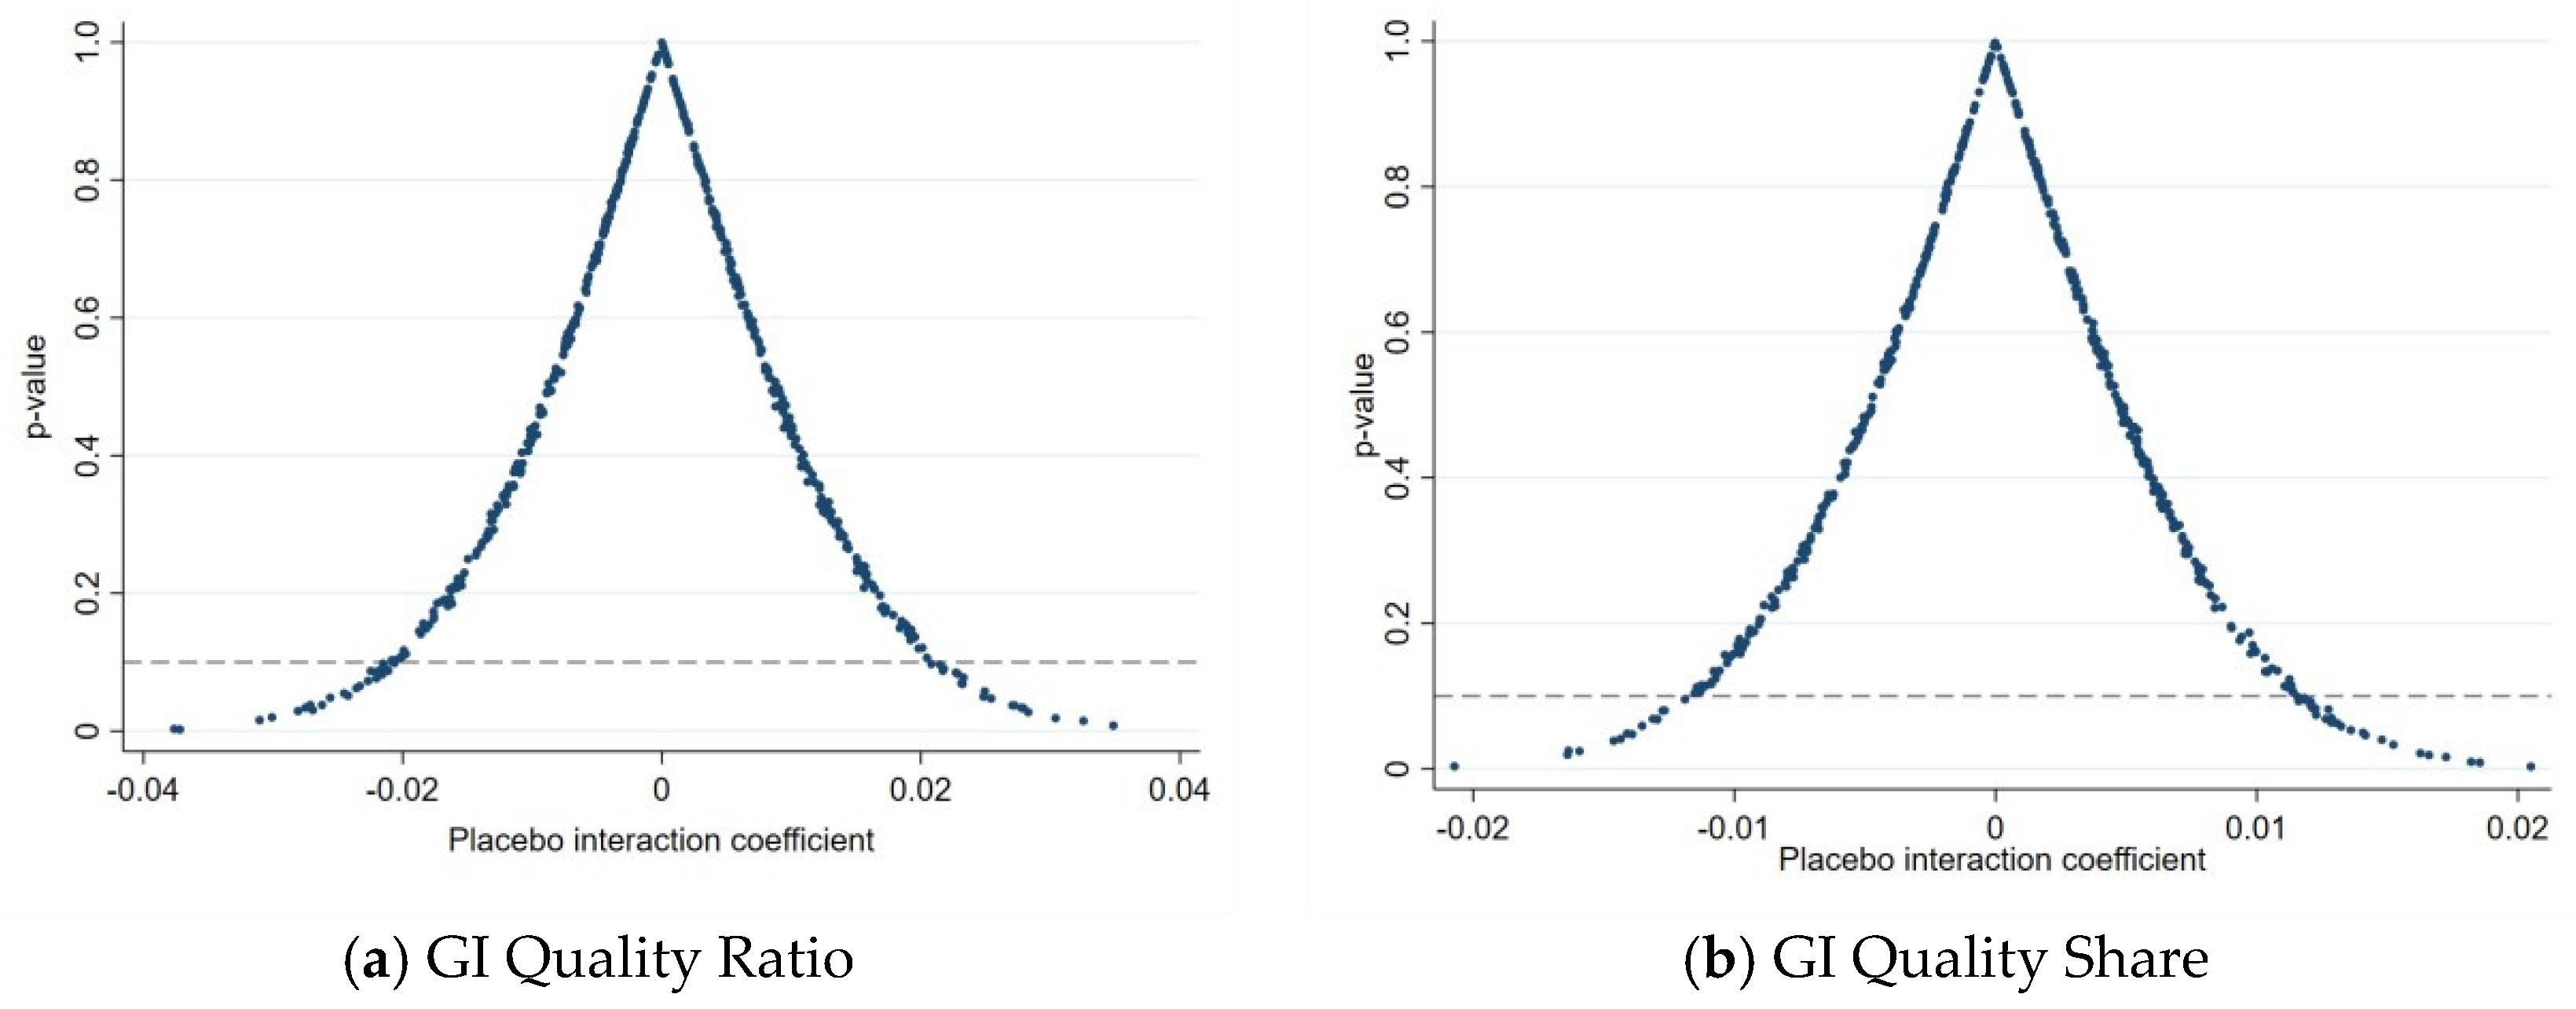
Table 5 evaluates whether the baseline findings are sensitive to alternative patent measures, different indicators of green innovation quality, and alternative specifications of the EPU variable. Figure 2 complements these tests by examining whether the estimated effects could be reproduced under randomly assigned heavy-polluting firm status.
The baseline analysis measures substantive green innovation using patent applications. Since application counts might include unsuccessful or relatively weak inventions, Column (1) replaces applications with granted green invention patents as a check. The coefficient on EPU × HP remains negative and statistically significant, and because granted invention patents have passed the examination process, this result provides additional evidence that the decline in substantive green innovation is not driven solely by the use of patent applications.
Column (2) turns to non-invention green patents. Here, the estimated interaction coefficient is positive but statistically insignificant, indicating that EPU does not produce a comparable decline in this category of green innovation. This contrast reinforces the paper’s main point: the adverse effect of policy uncertainty is concentrated in invention-oriented innovation rather than representing a general reduction in all green patenting activities.
Column (3) takes a different approach to measuring the quality structure of firms’ green innovation portfolios. High-Quality Dominance identifies whether green invention patents occupy the dominant position in a firm’s green patent portfolio, and here too, the negative and statistically significant coefficient on EPU × HP shows that greater uncertainty reduces the likelihood that substantive innovation remains dominant among heavy-polluting firms—a result consistent with the evidence obtained from the GI Quality Ratio.
The findings hold up equally well when we modify the measurement and timing of EPU. Columns (4) and (5) use standardized EPU and one-period-lagged EPU, respectively, and in both cases the interaction coefficient remains negative and statistically significant. The standardized specification confirms that the result is not sensitive to the original scale of the index, while the lagged specification suggests that the association between EPU and green innovation quality is not limited to the contemporaneous period [60].
Across all of these alternative specifications, the direction and significance of the main interaction effect stay stable, which supports the conclusion that EPU weakens the substantive orientation of green innovation among heavy-polluting firms, rather than reflecting a particular variable construction or model specification.
Figure 2 reports the placebo-test results obtained by randomly reassigning heavy-polluting firm status. The logic here is straightforward: if the baseline estimates were driven by arbitrary differences between firm groups, the simulated interaction coefficients would frequently resemble the actual estimates. Instead, they do not—the placebo coefficients are concentrated around zero and remain clearly separated from the baseline effects [61]. We observe similar distributions for both the GI Quality Ratio and GI Quality Share, which further reduces the concern that the main findings arise from random group assignment.

5. Mechanism Analysis

This section examines whether economic policy uncertainty affects the quality structure of green innovation through firms’ financial responses. We focus on three related but conceptually distinct channels: financing constraints, precautionary cash holdings, and bank credit access. Specifically, the SA Index captures firms’ overall external financing conditions, cash holdings reflect internal liquidity-preservation behavior, and bank credit access measures the availability of an important source of external finance. This focus builds on prior work showing that policy uncertainty can tighten firms’ financing conditions and alter their financial decisions [62], and that climate-related policy uncertainty may also affect firms’ environmental behavior through increased financial pressure [63]. Accordingly, Table 6 examines whether EPU changes these financial responses among heavy-polluting firms, while Table 7 evaluates their individual and joint associations with green innovation quality.

5.1. Effects of EPU on Financial Responses

Table 6 reports the effects of EPU on the three financial-response variables. Column (1) uses the SA Index as the dependent variable, where the coefficient on EPU × HP is negative and statistically significant at the 5% level. Because a lower SA Index indicates stronger financing constraints, this suggests that higher policy uncertainty tightens the external financing conditions faced by heavy-polluting firms—a finding that echoes prior evidence that uncertainty increases perceived risk, restricts firms’ access to external capital, and strengthens the real effects of financing constraints [62,64].
Column (2) turns to firms’ cash holdings, where the coefficient on EPU × HP is positive and statistically significant at the 1% level, indicating that heavy-polluting firms accumulate more cash when policy uncertainty rises. This response fits a precautionary liquidity-preservation story: when future financing conditions, investment returns, and regulatory requirements become less predictable, firms may retain a larger share of internal funds to buffer potential liquidity shocks rather than commit resources immediately to long-term projects. This echoes previous studies showing that corporate cash holdings are closely related to financing frictions, cash-flow risk, and precautionary saving motives [43,44,45,46].
Column (3) examines bank credit access. Here, the coefficient on EPU × HP is negative and statistically significant at the 1% level, suggesting that heavy-polluting firms experience weaker access to bank financing under higher policy uncertainty. This is plausible: banks may become more conservative when lending to environmentally exposed firms, since such firms face greater compliance costs, transition risks, and uncertainty regarding future regulatory enforcement. Existing studies show that credit supply and banking conditions can substantially affect firms’ investment and innovation activities [65,66,67,68], and recent evidence from China also indicates that policy uncertainty can weaken bank credit allocation and increase credit-market risk [69,70].
Taken together, the results in Table 6 show that EPU is associated with three concurrent financial responses among heavy-polluting firms: tighter overall financing constraints, greater precautionary cash accumulation, and reduced bank credit access. On their own, however, these results do not tell us whether the financial responses are associated with subsequent changes in green innovation quality. Table 7 addresses this issue by examining the individual and joint relationships between the three financial variables and the GI Quality Ratio.

5.2. Individual and Joint Tests of Financial Channels

Table 7 examines whether financing constraints, cash holdings, and bank credit access are associated with the quality structure of green innovation. Columns (1)–(3) introduce the three financial variables separately, while Column (4) includes them simultaneously to account for their potential interrelationships.
Column (1) reports the result for the SA Index, whose coefficient is positive and statistically significant at the 5% level. Because a higher SA Index indicates weaker financing constraints, this implies that firms facing less severe financing constraints exhibit a higher GI Quality Ratio; conversely, tighter financing constraints are associated with a shift away from substantive green innovation. This is consistent with previous evidence that financing constraints restrict firms’ ability to sustain long-term and technologically demanding R&D investment [40,41,63], and combined with the negative effect of EPU × HP on the SA Index reported in Table 6, the result lends support to the financing-constraint channel.
Column (2) turns to cash holdings, where the coefficient is negative and statistically significant at the 10% level when cash holdings are introduced separately. This fits the argument that precautionary liquidity preservation may crowd out long-term and resource-intensive green innovation: although greater cash reserves improve short-term financial flexibility, excessive liquidity retention under uncertainty may reduce the resources allocated to substantive green R&D and encourage firms to favor shorter-cycle and less costly forms of green innovation [43,44,45,46].
Column (3) reports the result for bank credit access. Here, the coefficient is positive and statistically significant at the 10% level, suggesting that firms with greater access to bank financing maintain a higher-quality green innovation structure. This makes sense given that stable bank credit can support the continuous funding required for green invention projects, which generally involve longer development periods, greater technological uncertainty, and larger upfront investment—an interpretation consistent with evidence that bank credit supply and banking-sector conditions significantly influence corporate innovation [65,66,67,68]. Together with the negative effect of EPU × HP on bank credit access in Table 6, this result supports the proposed credit-access channel when examined separately.
Column (4) brings all three variables together—the SA Index, cash holdings, and bank credit access—in a single specification. The coefficient on the SA Index remains positive and statistically significant, whereas cash holdings and bank credit access retain their expected signs but lose statistical significance. This pattern suggests that the three financial responses are not fully independent of one another: cash accumulation and reduced bank borrowing may partly reflect the broader deterioration in firms’ financing conditions captured by the SA Index [62]. Once these interrelationships are accounted for, financing constraints emerge as the most robust independent explanation for changes in green innovation quality.
Across all specifications in Table 7, the coefficient on EPU × HP remains negative and statistically significant, and its magnitude changes only modestly after the financial variables are introduced. The three financial responses therefore account for only part of the relationship between EPU and green innovation quality. The separate specifications are consistent with all three proposed channels, but only the SA Index remains statistically significant in the joint model. The results therefore provide partial support for H3, with financing constraints emerging as the most robust independent financial channel.

6. Heterogeneity Analysis

The baseline results indicate that economic policy uncertainty is associated with a deterioration in the green innovation quality structure of heavy-polluting firms. Yet firms are not all alike—they differ substantially in their policy exposure, resource endowments, and accumulated innovation capabilities, and these differences may shape both their sensitivity to uncertainty and their capacity to adjust the composition of green innovation. We therefore examine heterogeneity along three dimensions: ownership structure, firm size, and the initial green innovation base. The dependent variable in all specifications is the GI Quality Ratio, and Table 8 reports the corresponding subgroup results.

6.1. Ownership Structure

Columns (1) and (2) of Table 8 divide the sample into state-owned enterprises (SOEs) and non-state-owned enterprises (non-SOEs). The coefficient on EPU × HP is negative and statistically significant in both groups, which tells us that the deterioration in green innovation quality is not confined to a particular ownership structure. Still, the magnitudes differ: the coefficient is −0.1025 for SOEs and −0.0674 for non-SOEs, and although we do not formally test the difference between the two, the larger absolute magnitude for SOEs suggests that state-owned heavy-polluting firms may be more sensitive to policy uncertainty.
This pattern is plausible given the stronger institutional and policy embeddedness of SOEs. State-owned firms are more closely connected to government policy objectives and are generally subject to greater administrative oversight, environmental responsibility, and public scrutiny. Existing evidence shows that climate-related policy uncertainty can alter corporate green governance decisions [71], and state ownership affects firms’ green innovation through institutional and organizational conditions [72]. Consequently, SOEs’ assessments of green innovation projects may depend more heavily on expectations regarding future policy priorities, regulatory standards, and enforcement intensity.
When policy signals become less predictable, this creates a real difficulty for state-owned heavy-polluting firms: they may find it harder to evaluate the expected compliance value and economic returns of long-term green invention projects. Because substantive green innovation involves larger sunk costs and longer development cycles, such firms may respond by postponing these projects or redirecting resources toward less costly and shorter-cycle forms of innovation. The larger absolute coefficient among SOEs, then, may reflect their greater exposure to changes in policy direction—not an absolute lack of resources or innovation capacity.
Non-SOEs are not exempt either: their coefficient is also negative and statistically significant, indicating that private and other non-state firms are not insulated from EPU. For these firms, uncertainty appears to operate more strongly through expected market demand, external financing risk, and the irreversibility of long-term green investment. Ownership structure, in other words, seems to shape the magnitude of the EPU–green innovation quality relationship, but not its direction.

6.2. Firm Size

Columns (3) and (4) of Table 8 present the results for large and small firms, respectively. The interaction term EPU × HP remains negative and statistically significant in both subsamples, though the magnitudes diverge: the coefficient is −0.1074 for large firms and −0.0326 for small firms, suggesting that the adverse association between EPU and green innovation quality appears more pronounced among large heavy-polluting firms.
This is not entirely surprising, since firm size affects not only the amount of R&D investment but also the nature and allocation of firms’ innovation activities [73]. Large firms generally possess more diversified innovation portfolios and are more likely to undertake capital-intensive, technologically complex, and long-horizon projects. Yet despite typically having stronger internal resources, their substantive green innovation projects may involve greater sunk costs, more organizational coordination, and longer expected payback periods—characteristics that leave such projects more exposed to uncertainty concerning future regulation, market conditions, and technology standards.
Large heavy-polluting firms also tend to be more visible to regulators, investors, financial institutions, and the public, and may consequently face stronger environmental expectations and maintain a larger portfolio of policy-sensitive green projects. When EPU rises, these firms have greater scope to postpone invention-oriented projects, reduce new R&D commitments, or redirect resources toward lower-cost utility model innovation. The stronger estimated association among large firms may therefore reflect two things at once: greater policy exposure, and simply a larger margin for adjustment.
Small firms are not immune either—they also experience a significant decline in the GI Quality Ratio, though the coefficient is smaller in magnitude. This may simply be because small firms already undertake relatively limited substantive green innovation, given persistent financial, technological, and human-capital constraints: their smaller innovation portfolios leave less room for further compositional adjustment when uncertainty rises. The weaker coefficient should not, therefore, be read as evidence that small firms are unaffected by EPU; it more likely reflects a lower initial level of substantive green innovation that can be postponed or replaced.

6.3. Initial Green Innovation Base

Columns (5) and (6) of Table 8 divide firms according to their initial green innovation base. The coefficient on EPU × HP is negative and statistically significant in both groups. Its magnitude is −0.1271 among firms with a high initial green innovation base and −0.0393 among firms with a low initial green innovation base. The results therefore suggest that firms with stronger prior green innovation capabilities experience a larger adjustment in the quality composition of their green patent portfolios when uncertainty increases.
A stronger initial green innovation base generally reflects greater accumulated technological knowledge, more developed innovation capabilities, and a larger portfolio of ongoing green projects [74]. The absorptive-capacity literature further emphasizes that firms’ ability to recognize, assimilate, and apply new knowledge depends on their prior related knowledge and accumulated R&D experience [75]. Under stable conditions, these capabilities support substantive green innovation and allow firms to undertake more technologically demanding projects.
However, stronger innovation capabilities can also create greater exposure to uncertainty. Firms with a high initial green innovation base have more ongoing invention-oriented projects and more resources committed to long-term green technology development. When policy uncertainty rises, they consequently have a larger number of projects that can be delayed, scaled back, or replaced by shorter-cycle innovation activities. The larger estimated coefficient is therefore consistent with a greater adjustment margin, rather than suggesting that accumulated green innovation capability is inherently disadvantageous.
By contrast, firms with a low initial green innovation base already undertake relatively little substantive green innovation. Their limited technological capabilities and smaller project portfolios restrict the extent to which they can further shift away from high-quality innovation. This potential floor effect helps explain why the interaction coefficient remains negative but is smaller in magnitude in the low-initial-GI group.
Across all three dimensions, the coefficient on EPU × HP remains negative and statistically significant. The adverse association between policy uncertainty and green innovation quality is therefore broadly present across ownership structures, firm sizes, and initial innovation conditions. The coefficient patterns further suggest greater sensitivity among SOEs, large firms, and firms with a stronger initial green innovation base. These firms generally have greater policy exposure or larger substantive innovation portfolios, providing more scope for uncertainty-induced adjustments in the composition of green innovation. Because no formal cross-group coefficient-difference test is conducted, these results should be interpreted as suggestive heterogeneity patterns rather than statistically established differences between groups.

7. Discussion and Conclusions

7.1. Discussion

This study examines how economic policy uncertainty affects green innovation among heavy-polluting firms, with particular attention to changes in the internal quality composition of their green innovation portfolios. Rather than treating all green patents as equivalent, the analysis distinguishes between substantive green innovation, represented by green invention patents, and strategic green innovation, represented by green utility model patents. The empirical findings support H1 and H2, while H3 receives partial support.
Higher EPU significantly reduces substantive green innovation among heavy-polluting firms, while strategic green innovation does not decline in the same way—and even turns marginally positive once firm-level characteristics are controlled for. This asymmetry indicates that firms do not simply cut back on green innovation across the board when policy conditions grow more uncertain; instead, they reallocate within their innovation portfolios, withdrawing resources from costlier, slower invention projects while sustaining, or even expanding, lighter-weight utility model activity—a pattern that follows naturally from how the two forms of innovation differ in cost, duration, and dependence on stable regulatory and financing conditions.
This compositional effect shows up in both the GI Quality Share and the GI Quality Ratio, confirming H2: EPU does not just reduce the number of invention patents, it erodes their relative standing within firms’ green patent portfolios. The implication is that total patent counts alone can be misleading—a firm may keep applying for green patents even as the technological substance behind that activity deteriorates. Distinguishing invention from utility model patents therefore offers a more informative window into whether a firm’s green transition remains technologically substantive.
The mechanism analysis offers partial support for H3. Greater EPU is associated with tighter financing constraints, higher cash holdings, and weaker bank credit access among heavy-polluting firms, consistent with a broader shift toward financial conservatism under uncertainty. Examined individually, all three variables relate to green innovation quality as expected—weaker financing constraints and greater bank credit access raise the GI Quality Ratio, while higher cash holdings lower it. Once combined in a single model, however, only the SA Index remains statistically significant; cash holdings and bank credit access keep their expected signs but lose significance, suggesting that cash retention and reduced borrowing partly reflect the same underlying financing pressure captured by the SA Index. Financing constraints therefore stand out as the most robust independent financial channel.
That EPU × HP remains significant even after the financial variables are added indicates these channels account for only part of the story—managerial expectations, regulatory ambiguity, investment timing, and demand concerns likely play a role as well. The mechanism results should accordingly be read as evidence consistent with the proposed financial channels, not as proof that they fully explain the relationship between EPU and green innovation quality.
The main results also prove robust: they hold when granted invention patents replace applications, when alternative quality measures or standardized/lagged EPU specifications are used, and when heavy-polluting status is randomly reassigned in placebo tests—evidence that the findings are not an artifact of any single variable or modeling choice. The negative relationship between EPU and green innovation quality likewise persists across ownership structures, firm sizes, and initial innovation conditions, with somewhat larger coefficients among SOEs, large firms, and firms with stronger initial green innovation bases—consistent with the institutional, resource, and adjustment-margin explanations developed in Section 6, though these subgroup differences were not formally tested for statistical significance.
The study contributes to the existing literature by shifting attention from the quantity of green innovation to its internal quality structure. The results identify a form of innovation distortion in which firms continue to generate visible green patent output while reducing the relative importance of technologically substantive innovation. This distinction helps explain why aggregate green patent indicators may conceal meaningful changes in firms’ innovation strategies.
Heavy-polluting firms also provide a particularly relevant setting for examining the consequences of policy uncertainty. These firms are simultaneously exposed to macroeconomic uncertainty, environmental regulation, transition risks, financing scrutiny, and public pressure. Their innovation decisions reflect not only expected technological returns but also expectations regarding future compliance costs and regulatory enforcement. The findings therefore show how broad policy uncertainty can interact with industry-specific environmental exposure.
The mechanism analysis adds a further contribution by examining financing constraints, cash holdings, and bank credit access within a common framework. Rather than treating these variables as completely separate mechanisms, the joint analysis reveals their overlap. Financing constraints emerge as the most robust independent channel, while cash preservation and bank credit access appear to represent related dimensions of firms’ broader financial conditions.
From a systems perspective, green innovation quality is shaped by the interaction of policy conditions, financial institutions, firm characteristics, and the internal allocation of innovation resources. Policy uncertainty does not affect corporate green transformation through a single isolated pathway. It changes firms’ expectations and financing conditions, which then influence how resources are distributed between substantive and strategic innovation.
The findings also have implications for policy design. Environmental policy effectiveness depends not only on regulatory stringency but also on the stability and predictability of implementation. Unclear transition schedules, frequent changes in qualification standards, and inconsistent enforcement may discourage long-term green invention projects. More transparent policy communication, advance notice of major adjustments, and stable implementation arrangements can reduce uncertainty surrounding the expected returns from substantive green innovation.
Innovation-support policies should place greater emphasis on technological quality rather than total patent output. Subsidies, tax incentives, and performance evaluations that rely mainly on the number of green patents may unintentionally encourage firms to favor utility model patents because they are less costly and faster to obtain. Greater attention should be given to invention-oriented innovation, successful patent grants, technological novelty, commercialization potential, and measurable environmental outcomes.
The financial results suggest that banks should avoid uniformly restricting credit to all heavy-polluting firms during periods of elevated uncertainty. Credit evaluation should distinguish between financing used to sustain pollution-intensive production and financing used to support substantive green transformation. Longer-term green credit products may be more appropriate for invention-oriented projects because their financing maturity can better match extended R&D and commercialization cycles.
These implications should also be calibrated to firm characteristics. The heterogeneity results in Section 6 indicate that state-owned enterprises, larger firms, and firms with a stronger initial green innovation base experience a more pronounced decline in green innovation quality under policy uncertainty, reflecting their greater policy exposure and larger portfolios of long-cycle invention projects. For these firms, regulators and financial institutions should prioritize stable, predictable policy communication and continuity of long-term green financing, since disruptions carry a larger adjustment margin and thus a larger potential loss of substantive innovation. By contrast, non-state, smaller, and low-initial-base firms—whose green innovation activity is already limited—may benefit more from capacity-building measures, such as technical assistance, matching grants, or simplified access to green credit, that help them establish substantive innovation capability in the first place rather than measures designed mainly to protect existing large-scale projects.
Corporate managers should also consider the long-term costs of excessive financial conservatism. Retaining additional cash may provide short-term protection against liquidity risks, but prolonged reductions in substantive R&D can weaken technological competitiveness and delay green transformation. Protecting core green innovation budgets, prioritizing projects according to technological and environmental value, and diversifying long-term financing sources may help firms maintain substantive innovation during uncertain periods.

7.2. Conclusions and Future Research

Using 25,210 firm-year observations from Chinese A-share listed firms between 2010 and 2023, this study examines how economic policy uncertainty affects green innovation among heavy-polluting firms. The results show that EPU significantly reduces substantive green innovation and weakens the relative position of invention patents within firms’ green innovation portfolios. Strategic green innovation does not decline correspondingly, indicating that uncertainty leads to a change in innovation composition rather than a uniform reduction in all green patenting activities.
The financial analysis shows that EPU is associated with tighter financing constraints, greater precautionary cash holdings, and weaker bank credit access. Each financial variable exhibits the expected relationship with green innovation quality when examined separately. Once the three variables are considered jointly, financing constraints remain significant, while the effects of cash holdings and bank credit access become weaker. Financing constraints therefore provide the most robust independent financial explanation for the deterioration in green innovation quality.
The central conclusion is that policy uncertainty affects not only how much green innovation heavy-polluting firms undertake but also what kind of innovation they pursue. Firms may maintain visible green patent activity while reducing their commitment to technologically demanding invention projects. Stable policy expectations, quality-oriented innovation evaluation, and financing arrangements that support long-term green R&D are therefore important for sustaining substantive corporate green transformation.
Several limitations point to directions for future work. On the measurement side, patent type alone cannot fully capture commercial value, actual implementation, or environmental effectiveness—invention patents involve higher technological requirements than utility model patents, but utility model patents do not necessarily represent purely strategic behavior, and the use of applications rather than grants, while more timely, may include some applications that are ultimately rejected or commercially unsuccessful (a concern the granted-patent robustness test only partially addresses). Future research could combine patent classifications with citation counts, patent renewals, claim characteristics, commercialization outcomes, pollution emissions, or energy-efficiency indicators, and could track the full process from application and authorization through commercialization and measurable environmental outcomes.
The EPU measure and the empirical design carry their own limitations. The national annual EPU index captures broad changes in China’s policy environment but cannot distinguish among different sources of uncertainty—fiscal, monetary, industrial, trade, and environmental policy uncertainty may operate through different channels, and regional indices, firm-level textual measures, or policy-specific indicators could offer a more granular picture. Similarly, although firm and year fixed effects, control variables, robustness tests, and placebo analysis address several sources of estimation bias, they cannot fully rule out unobserved time-varying confounders, and the mechanism results should be read as evidence consistent with the proposed financial channels rather than formal causal estimates. Future work could draw on identifiable policy shocks, quasi-natural experiments, instrumental-variable approaches, or dynamic mediation methods to strengthen causal identification, and could apply interaction-based tests, cross-group coefficient comparisons, or permutation procedures to formally assess whether the heterogeneity patterns across ownership types, firm sizes, and initial innovation conditions are statistically distinct.
The sample is limited to Chinese listed firms, whose financing conditions, patent incentives, and regulatory exposure may differ from those of unlisted firms or firms operating in other institutional environments. Extending the analysis to privately held companies, other countries, and alternative regulatory systems would help assess the broader applicability of the findings. Updating the sample as more recent and comparable patent and financial data become available would also allow future studies to evaluate whether the relationship changes under newer environmental and industrial policies.

Author Contributions

Conceptualization, D.W. and Q.Z.; methodology, D.W. and H.L.; software, D.W. and H.L.; validation, D.W., H.L. and Q.Z.; formal analysis, D.W. and Q.Z.; investigation, H.L.; resources, H.L. and Q.Z.; data curation, D.W. and Q.Z.; writing—original draft preparation, D.W. and Q.Z.; writing—review and editing, H.L. and Q.Z. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Institutional Review Board Statement

Not applicable.

Informed Consent Statement

Not applicable.

Data Availability Statement

The raw data supporting the conclusions of this article will be made available by the authors on request.

Conflicts of Interest

The authors declare no conflicts of interest.

References

  1. Porter, M.E.; Linde, C.V.D. Toward a new conception of the environment-competitiveness relationship. J. Econ. Perspect. 1995, 9, 97–118. [Google Scholar] [CrossRef] [Scilit]
  2. Jaffe, A.B.; Palmer, K. Environmental regulation and innovation: A panel data study. Rev. Econ. Stat. 1997, 79, 610–619. [Google Scholar] [CrossRef] [Scilit]
  3. Popp, D. Induced innovation and energy prices. Am. Econ. Rev. 2002, 92, 160–180. [Google Scholar] [CrossRef] [Scilit]
  4. Brunnermeier, S.B.; Cohen, M.A. Determinants of environmental innovation in US manufacturing industries. J. Environ. Econ. Manag. 2003, 45, 278–293. [Google Scholar] [CrossRef] [Scilit]
  5. Rennings, K. Redefining innovation—Eco-innovation research and the contribution from ecological economics. Ecol. Econ. 2000, 32, 319–332. [Google Scholar] [CrossRef] [Scilit]
  6. Berrone, P.; Fosfuri, A.; Gelabert, L.; Gomez-Mejia, L.R. Necessity as the mother of ‘green’inventions: Institutional pressures and environmental innovations. Strateg. Manag. J. 2013, 34, 891–909. [Google Scholar] [CrossRef] [Scilit]
  7. Amore, M.D.; Bennedsen, M. Corporate governance and green innovation. J. Environ. Econ. Manag. 2016, 75, 54–72. [Google Scholar] [CrossRef] [Scilit]
  8. Hall, B.H.; Jaffe, A.B.; Trajtenberg, M. Market value and patent citations: A first look. RAND J. Econ. 2000, 36, 16–38. [Google Scholar]
  9. Zhao, S.; Abbassi, W.; Hunjra, A.I.; Zhang, H. How do government R&D subsidies affect corporate green innovation choices? Perspectives from strategic and substantive innovation. Int. Rev. Econ. Financ. 2024, 93, 1378–1396. [Google Scholar] [CrossRef] [Scilit]
  10. Bloom, N. The impact of uncertainty shocks. Econometrica 2009, 77, 623–685. [Google Scholar] [CrossRef] [Scilit]
  11. Julio, B.; Yook, Y. Political uncertainty and corporate investment cycles. J. Financ. 2012, 67, 45–83. [Google Scholar] [CrossRef] [Scilit]
  12. Gulen, H.; Ion, M. Policy uncertainty and corporate investment. Rev. Financ. Stud. 2016, 29, 523–564. [Google Scholar] [CrossRef] [Scilit]
  13. Bhattacharya, U.; Hsu, P.H.; Tian, X.; Xu, Y. What affects innovation more: Policy or policy uncertainty? J. Financ. Quant. Anal. 2017, 52, 1869–1901. [Google Scholar] [CrossRef] [Scilit]
  14. Peng, X.Y.; Zou, X.Y.; Zhao, X.X.; Chang, C.P. How does economic policy uncertainty affect green innovation? Technol. Econ. Dev. Econ. 2023, 29, 114–140. [Google Scholar] [CrossRef] [Scilit]
  15. Cui, X.; Wang, C.; Sensoy, A.; Liao, J.; Xie, X. Economic policy uncertainty and green innovation: Evidence from China. Econ. Model. 2023, 118, 106104. [Google Scholar] [CrossRef] [Scilit]
  16. Opler, T.; Pinkowitz, L.; Stulz, R.; Williamson, R. The determinants and implications of corporate cash holdings. J. Financ. Econ. 1999, 52, 3–46. [Google Scholar] [CrossRef] [Scilit]
  17. Almeida, H.; Campello, M.; Weisbach, M.S. The cash flow sensitivity of cash. J. Financ. 2004, 59, 1777–1804. [Google Scholar] [CrossRef] [Scilit]
  18. Acharya, V.V.; Almeida, H.; Campello, M. Is cash negative debt? A hedging perspective on corporate financial policies. J. Financ. Intermediat. 2007, 16, 515–554. [Google Scholar] [CrossRef] [Scilit]
  19. Hadlock, C.J.; Pierce, J.R. New evidence on measuring financial constraints: Moving beyond the KZ index. Rev. Financ. Stud. 2010, 23, 1909–1940. [Google Scholar] [CrossRef] [Scilit]
  20. Bernanke, B.S. Irreversibility, uncertainty, and cyclical investment. Q. J. Econ. 1983, 98, 85–106. [Google Scholar] [CrossRef] [Scilit]
  21. McDonald, R.; Siegel, D. The value of waiting to invest. Q. J. Econ. 1986, 101, 707–727. [Google Scholar] [CrossRef] [Scilit]
  22. Pastor, L.; Veronesi, P. Uncertainty about government policy and stock prices. J. Financ. 2012, 67, 1219–1264. [Google Scholar] [CrossRef] [Scilit]
  23. Baker, S.R.; Bloom, N.; Davis, S.J. Measuring economic policy uncertainty. Q. J. Econ. 2016, 131, 1593–1636. [Google Scholar] [CrossRef] [Scilit]
  24. Czarnitzki, D.; Hottenrott, H. R&D investment and financing constraints of small and medium-sized firms. Small Bus. Econ. 2011, 36, 65–83. [Google Scholar] [CrossRef] [Scilit]
  25. Brown, J.R.; Martinsson, G.; Petersen, B.C. Do financing constraints matter for R&D? Eur. Econ. Rev. 2012, 56, 1512–1529. [Google Scholar] [CrossRef] [Scilit]
  26. Horbach, J. Determinants of environmental innovation—New evidence from German panel data sources. Res. Policy 2008, 37, 163–173. [Google Scholar] [CrossRef] [Scilit]
  27. Kesidou, E.; Demirel, P. On the drivers of eco-innovations: Empirical evidence from the UK. Res. Policy 2012, 41, 862–870. [Google Scholar] [CrossRef] [Scilit]
  28. Lian, G.; Xu, A.; Zhu, Y. Substantive green innovation or symbolic green innovation? The impact of ER on enterprise green innovation based on the dual moderating effects. J. Innov. Knowl. 2022, 7, 100203. [Google Scholar] [CrossRef] [Scilit]
  29. Horbach, J.; Rammer, C.; Rennings, K. Determinants of eco-innovations by type of environmental impact—The role of regulatory push/pull, technology push and market pull. Ecol. Econ. 2012, 78, 112–122. [Google Scholar] [CrossRef] [Scilit]
  30. Calel, R.; Dechezleprêtre, A. Environmental policy and directed technological change: Evidence from the European carbon market. Rev. Econ. Stat. 2016, 98, 173–191. [Google Scholar] [CrossRef] [Scilit]
  31. Aghion, P.; Dechezleprêtre, A.; Hemous, D.; Martin, R.; Van Reenen, J. Carbon taxes, path dependency, and directed technical change: Evidence from the auto industry. J. Political Econ. 2016, 124, 1–51. [Google Scholar] [CrossRef] [Scilit]
  32. Delmas, M.A.; Burbano, V.C. The drivers of greenwashing. Calif. Manag. Rev. 2011, 54, 64–87. [Google Scholar] [CrossRef] [Scilit]
  33. Lyon, T.P.; Maxwell, J.W. Greenwash: Corporate environmental disclosure under threat of audit. J. Econ. Manag. Strategy 2011, 20, 3–41. [Google Scholar] [CrossRef] [Scilit]
  34. Marquis, C.; Toffel, M.W.; Zhou, Y. Scrutiny, norms, and selective disclosure: A global study of greenwashing. Organ. Sci. 2016, 27, 483–504. [Google Scholar] [CrossRef] [Scilit]
  35. Ambec, S.; Cohen, M.A.; Elgie, S.; Lanoie, P. The Porter hypothesis at 20: Can environmental regulation enhance innovation and competitiveness? Rev. Environ. Econ. Policy 2013, 7, 2–22. [Google Scholar] [CrossRef] [Scilit]
  36. Zhou, W.; Huang, X.; Dai, H.; Xi, Y.; Wang, Z.; Chen, L. Research on the impact of economic policy uncertainty on enterprises’ green innovation—Based on the perspective of corporate investment and financing decisions. Sustainability 2022, 14, 2627. [Google Scholar] [CrossRef] [Scilit]
  37. Roper, S.; Tapinos, E. Taking risks in the face of uncertainty: An exploratory analysis of green innovation. Technol. Forecast. Soc. Change 2016, 112, 357–363. [Google Scholar] [CrossRef] [Scilit]
  38. Ghisetti, C.; Rennings, K. Environmental innovations and profitability: How does it pay to be green? An empirical analysis on the German innovation survey. J. Clean. Prod. 2014, 75, 106–117. [Google Scholar] [CrossRef] [Scilit]
  39. Stiglitz, J.E.; Weiss, A. Credit rationing in markets with imperfect information. Am. Econ. Rev. 1981, 71, 393–410. [Google Scholar]
  40. Whited, T.M.; Wu, G. Financial constraints risk. Rev. Financ. Stud. 2006, 19, 531–559. [Google Scholar] [CrossRef] [Scilit]
  41. Czarnitzki, D.; Hottenrott, H. Financial constraints: Routine versus cutting edge R&D investment. J. Econ. Manag. Strategy 2011, 20, 121–157. [Google Scholar] [CrossRef] [Scilit]
  42. Kashyap, A.K.; Stein, J.C.; Wilcox, D.W. Monetary policy and credit conditions: Evidence from the composition of external finance: Reply. Am. Econ. Rev. 1996, 86, 310–314. [Google Scholar]
  43. Faulkender, M.; Wang, R. Corporate financial policy and the value of cash. J. Financ. 2006, 61, 1957–1990. [Google Scholar] [CrossRef] [Scilit]
  44. Harford, J.; Mansi, S.A.; Maxwell, W.F. Corporate governance and firm cash holdings in the US. J. Financ. Econ. 2008, 87, 535–555. [Google Scholar] [CrossRef] [Scilit]
  45. Bates, T.W.; Kahle, K.M.; Stulz, R.M. Why do US firms hold so much more cash than they used to? J. Financ. 2009, 64, 1985–2021. [Google Scholar] [CrossRef] [Scilit]
  46. Han, S.; Qiu, J. Corporate precautionary cash holdings. J. Corp. Financ. 2007, 13, 43–57. [Google Scholar] [CrossRef] [Scilit]
  47. Davis, S.J.; Liu, D.; Sheng, X.S. Economic policy uncertainty in China since 1949: The view from mainland newspapers. In Fourth Annual IMF-Atlanta Fed Research Workshop on China’s Economy Atlanta; Federal Reserve Bank of Atlanta: Atlanta, GA, USA, 2019; Volume 19, pp. 1–37. [Google Scholar]
  48. Li, C.; Zhao, L.; Zhang, Y. Economic policy uncertainty and cash dividend policy: Evidence from China. Humanit. Soc. Sci. Commun. 2024, 11, 1–17. [Google Scholar] [CrossRef] [Scilit]
  49. Liu, Y.; Wang, A.; Wu, Y. Environmental regulation and green innovation: Evidence from China’s new environmental protection law. J. Clean. Prod. 2021, 297, 126698. [Google Scholar] [CrossRef] [Scilit]
  50. Griliches, Z. Patent statistics as economic indicators: A survey. In R&D and Productivity: The Econometric Evidence; University of Chicago Press: Chicago, IL, USA, 1998; pp. 287–343. [Google Scholar]
  51. Hall, B.; Helmers, C.; Rogers, M.; Sena, V. The choice between formal and informal intellectual property: A review. J. Econ. Lit. 2014, 52, 375–423. [Google Scholar] [CrossRef] [Scilit]
  52. Kogan, L.; Papanikolaou, D.; Seru, A.; Stoffman, N. Technological innovation, resource allocation, and growth. Q. J. Econ. 2017, 132, 665–712. [Google Scholar] [CrossRef] [Scilit]
  53. Bertrand, M.; Duflo, E.; Mullainathan, S. How much should we trust differences-in-differences estimates? Q. J. Econ. 2004, 119, 249–275. [Google Scholar] [CrossRef] [Scilit]
  54. Petersen, M.A. Estimating standard errors in finance panel data sets: Comparing approaches. Rev. Financ. Stud. 2008, 22, 435–480. [Google Scholar] [CrossRef] [Scilit]
  55. Hsu, P.H.; Tian, X.; Xu, Y. Financial development and innovation: Cross-country evidence. J. Financ. Econ. 2014, 112, 116–135. [Google Scholar] [CrossRef] [Scilit]
  56. He, F.; Ma, Y.; Zhang, X. How does economic policy uncertainty affect corporate Innovation?–Evidence from China listed companies. Int. Rev. Econ. Financ. 2020, 67, 225–239. [Google Scholar] [CrossRef] [Scilit]
  57. Fang, V.W.; Tian, X.; Tice, S. Does stock liquidity enhance or impede firm innovation? J. Financ. 2014, 69, 2085–2125. [Google Scholar] [CrossRef] [Scilit]
  58. Atanassov, J. Do hostile takeovers stifle innovation? Evidence from antitakeover legislation and corporate patenting. J. Financ. 2013, 68, 1097–1131. [Google Scholar] [CrossRef] [Scilit]
  59. Brambor, T.; Clark, W.R.; Golder, M. Understanding interaction models: Improving empirical analyses. Political Anal. 2006, 14, 63–82. [Google Scholar] [CrossRef] [Scilit]
  60. Wan, E.; Li, Z.; Zhao, L.; Zhang, X. Economic policy uncertainty and Chinese companies’ overseas investment. Int. Rev. Econ. Financ. 2024, 96, 103563. [Google Scholar] [CrossRef] [Scilit]
  61. Imai, K.; King, G.; Stuart, E.A. Misunderstandings between experimentalists and observationalists about causal inference. J. R. Stat. Soc. Ser. A Stat. Soc. 2008, 171, 481–502. [Google Scholar] [CrossRef] [Scilit]
  62. Ma, H.; Hao, D. Economic policy uncertainty, financial development, and financial constraints: Evidence from China. Int. Rev. Econ. Financ. 2022, 79, 368–386. [Google Scholar] [CrossRef] [Scilit]
  63. Zhang, Z.; Feng, Y.; Zhou, H.; Chen, L.; Liu, Y. The impact of climate policy uncertainty on the ESG performance of enterprises. Systems 2024, 12, 495. [Google Scholar] [CrossRef] [Scilit]
  64. Campello, M.; Graham, J.R.; Harvey, C.R. The real effects of financial constraints: Evidence from a financial crisis. J. Financ. Econ. 2010, 97, 470–487. [Google Scholar] [CrossRef] [Scilit]
  65. Benfratello, L.; Schiantarelli, F.; Sembenelli, A. Banks and innovation: Microeconometric evidence on Italian firms. J. Financ. Econ. 2008, 90, 197–217. [Google Scholar] [CrossRef] [Scilit]
  66. Amore, M.D.; Schneider, C.; Žaldokas, A. Credit supply and corporate innovation. J. Financ. Econ. 2013, 109, 835–855. [Google Scholar] [CrossRef] [Scilit]
  67. Chava, S.; Oettl, A.; Subramanian, A.; Subramanian, K.V. Banking deregulation and innovation. J. Financ. Econ. 2013, 109, 759–774. [Google Scholar] [CrossRef] [Scilit]
  68. Cornaggia, J.; Mao, Y.; Tian, X.; Wolfe, B. Does banking competition affect innovation? J. Financ. Econ. 2015, 115, 189–209. [Google Scholar] [CrossRef] [Scilit]
  69. Yao, J.; Fan, J. The impact of policy uncertainty and risk taking on the credit resource allocation of urban commercial banks. Int. Rev. Econ. Financ. 2025, 97, 103766. [Google Scholar] [CrossRef] [Scilit]
  70. Zhang, M.; Zhang, R.; Zhao, Y. Economic policy uncertainty and volatility of corporate bond credit spread: Evidence from China and the United States. Int. Rev. Econ. Financ. 2024, 93, 827–841. [Google Scholar] [CrossRef] [Scilit]
  71. Sun, H.; Lu, H.; Hunt, A. Climate policy uncertainty and corporate green governance: Evidence from China. Systems 2025, 13, 635. [Google Scholar] [CrossRef] [Scilit]
  72. Wang, K.; Jiang, W. State ownership and green innovation in China: The contingent roles of environmental and organizational factors. J. Clean. Prod. 2021, 314, 128029. [Google Scholar] [CrossRef] [Scilit]
  73. Cohen, W.M.; Klepper, S. Firm size and the nature of innovation within industries: The case of process and product R&D. Rev. Econ. Stat. 1996, 78, 232–243. [Google Scholar] [CrossRef] [Scilit]
  74. Xu, J.; Zhai, J. Research on the evaluation of green innovation capability of manufacturing enterprises in innovation network. Sustainability 2020, 12, 807. [Google Scholar] [CrossRef] [Scilit]
  75. Cohen, W.M.; Levinthal, D.A. Absorptive capacity: A new perspective on learning and innovation. Adm. Sci. Q. 1990, 35, 128–152. [Google Scholar] [CrossRef] [Scilit]
Figure 1. Marginal Effects of EPU on GI Quality Ratio by Firm Type. Note: This figure presents the estimated marginal effects of EPU on the GI Quality Ratio for heavy-polluting and non-heavy-polluting firms. The vertical bars represent 95% confidence intervals. HP denotes heavy-polluting firms.
Systems 14 01082 g001
Figure 2. Placebo Distributions for Green Innovation Quality.
Systems 14 01082 g002
Table 1. Definitions of Main Variables.
VariableDefinition
Substantive GILn(1 + green invention applications)
Strategic GILn(1 + green utility model applications)
GI Quality ShareGreen invention/(green invention + green utility model)
GI Quality RatioLn(1 + green invention) − Ln(1 + green utility model)
Heavy Polluter1 for heavy-polluting firms, 0 otherwise
EPUAnnual EPU index/100
SizeNatural logarithm of total assets
LevTotal liabilities divided by total assets
RoaNet income divided by total assets
GrowthPercentage change in operating revenue from year t − 1
CashflowRatio of cash and cash equivalents to total assets
AgeNatural logarithm of number of years listed
Top1Shareholding ratio of the largest shareholder
Dual1 if CEO and chair are the same person, 0 otherwise
Note: GI denotes green innovation. GI Quality Share is defined only for firm-year observations with non-zero green innovation output.
Table 2. Descriptive Statistics of Variables.
VariableObsMeanSDMinMedianMax
Substantive GI25,2100.6661.055004.905
Strategic GI25,2100.6470.987004.234
GI Quality Share12,3640.4920.35400.5001
GI Quality Ratio25,2100.0190.727−3.63804.905
EPU25,2102.0841.0390.9212.0663.904
Heavy Polluter25,2100.3400.474001
Size25,21022.491.37018.3722.3228.70
Lev25,2100.4520.2090.0080.4501.957
Roa25,2100.0350.0710−1.3240.0331.285
Growth25,2100.1420.298−0.2900.0781.979
Cashflow25,2100.0460.074−1.0770.0450.876
Age25,2102.9630.3470.6932.9964.248
Top125,21033.7615.181.84431.3889.99
Dual25,2100.2270.419001
Table 3. Baseline Results: Parsimonious Specification.
VariableSubstantive GIStrategic GIGI Quality ShareGI Quality Ratio
(1)(2)(3)(4)
EPU0.4993 ***0.3946 ***0.0636 ***0.1047 ***
(0.0173)(0.0154)(0.0120)(0.0152)
HP0.0118−0.1510 **0.04260.1629 ***
(0.0692)(0.0656)(0.0385)(0.0546)
EPU × HP−0.0732 ***0.0196−0.0358 ***−0.0929 ***
(0.0148)(0.0148)(0.0076)(0.0122)
Constant−0.3030 ***−0.1320 ***0.3698 ***−0.1710 ***
(0.0413)(0.0371)(0.0329)(0.0337)
Firm FEYESYESYESYES
Year FEYESYESYESYES
# of Obs.25,21025,21012,36425,210
R-squared0.18570.16400.01170.0103
Note: ***, and ** indicate significance at the 1%, and 5% levels, respectively. Robust standard errors are clustered at the firm level. HP denotes heavy-polluting firms.
Table 4. Baseline Results: Full Specification.
VariableSubstantive GIStrategic GIGI Quality ShareGI Quality Ratio
(1)(2)(3)(4)
EPU0.1791 ***0.1271 ***0.0503 *0.0520
(0.0512)(0.0451)(0.0272)(0.0412)
HP0.0769−0.09620.04930.1732 ***
(0.0640)(0.0603)(0.0391)(0.0549)
E P U × H P −0.0652 ***0.0265 *−0.0366 ***−0.0917 ***
(0.0141)(0.0143)(0.0078)(0.0121)
Size0.3474 ***0.2829 ***0.0219 **0.0645 ***
(0.0225)(0.0206)(0.0101)(0.0186)
Lev−0.2054 ***−0.0679−0.0450−0.1375 ***
(0.0627)(0.0640)(0.0433)(0.0505)
Roa−0.1839 **0.07030.0086−0.2542 ***
(0.0836)(0.0827)(0.0616)(0.0792)
Growth0.0002 ***0.0001 ***−0.0031 **0.0000
(0.0000)(0.0000)(0.0014)(0.0000)
Cashflow−0.03540.0177−0.0040−0.0531
(0.0666)(0.0664)(0.0617)(0.0658)
Age0.19120.17590.00150.0153
(0.1242)(0.1100)(0.0563)(0.0977)
Top10.0007−0.00030.00080.0009
(0.0012)(0.0012)(0.0006)(0.0009)
Dual0.0514 **−0.02280.0223 **0.0742 ***
(0.0200)(0.0187)(0.0111)(0.0181)
Constant−7.9495 ***−6.4199 ***−0.1164−1.5296 ***
(0.5351)(0.4851)(0.2323)(0.4403)
Firm FEYESYESYESYES
Year FEYESYESYESYES
# of Obs.25,21025,21012,36425,210
R-squared0.23650.20220.01370.0142
Note: ***, **, and * indicate significance at the 1%, 5%, and 10% levels, respectively. Robust standard errors are clustered at the firm level. HP denotes heavy-polluting firms.
Table 5. Robustness Checks Results.
VariableSub. GI GrantNon-Inv. GIHQ DominanceGI Quality RatioGI Quality Ratio
(1)(2)(3)(4)(5)
EPU0.1671 ***0.1341 ***0.0658
(0.0383)(0.0459)(0.0422)
HP0.0862 **−0.08500.0718−0.01730.1613 ***
(0.0436)(0.0604)(0.0498)(0.0489)(0.0603)
EPU × HP−0.0519 ***0.0222−0.0587 ***
(0.0092)(0.0144)(0.0109)
Std. EPU 0.0540
(0.0428)
Std. EPU × HP −0.0952 ***
(0.0126)
L1. EPU 0.0434
(0.0371)
L1. EPU × HP −0.0896 ***
(0.0127)
Constant−4.7075 ***−6.5181 ***−0.4666−1.4216 ***−1.5559 ***
(0.3863)(0.4886)(0.3398)(0.4959)(0.5044)
ControlsYESYESYESYESYES
Firm FEYESYESYESYESYES
Year FEYESYESYESYESYES
# of Obs.25,21025,21012,36425,21023,420
R-squared0.16760.20140.01720.01420.0139
Note: ***, and ** indicate significance at the 1%, and 5% levels, respectively. Robust standard errors are clustered at the firm level. HP denotes heavy-polluting firms.
Table 6. Effects of EPU on Financial Responses.
VariableSA IndexCash HoldingsBank Credit Access
(1)(2)(3)
EPU−0.2677 ***0.0283 ***−0.0887 ***
(0.0087)(0.0077)(0.0074)
HP0.0180 *−0.0189 **0.0331 ***
(0.0092)(0.0089)(0.0114)
EPU × HP−0.0044 **0.0072 ***−0.0072 ***
(0.0019)(0.0021)(0.0023)
Constant−3.5953 ***0.6000 ***−1.0277 ***
(0.1166)(0.0746)(0.0844)
ControlsYESYESYES
Firm FEYESYESYES
Year FEYESYESYES
# of Obs.25,21025,21024,372
R-squared0.86830.18100.1534
Note: ***, **, and * indicate significance at the 1%, 5%, and 10% levels, respectively. Robust standard errors are clustered at the firm level. HP denotes heavy-polluting firms.
Table 7. Individual and Joint Tests of Financial Channels.
VariableGI Quality RatioGI Quality RatioGI Quality RatioGI Quality Ratio
(1)(2)(3)(4)
SA Index0.2818 ** 0.2917 **
(0.1346) (0.1365)
Cash Holdings −0.0831 * −0.0515
(0.0483) (0.0618)
Bank Credit Access 0.1532 *0.0781
(0.0844)(0.0956)
EPU × HP−0.0897 ***−0.0897 ***−0.0939 ***−0.0939 ***
(0.0121)(0.0084)(0.0126)(0.0126)
Constant−0.5699−1.5762 ***−1.4660 ***−0.4693
(0.5727)(0.2764)(0.4575)(0.5984)
ControlsYESYESYESYES
Firm FEYESYESYESYES
Year FEYESYESYESYES
# of Obs.25,21025,21024,37224,372
R-squared0.01520.01430.01440.0158
Note: A higher SA Index indicates weaker financing constraints. Columns (1)–(3) introduce the three financial channels separately, while Column (4) includes them jointly. ***, **, and * indicate significance at the 1%, 5%, and 10% levels, respectively. Robust standard errors are clustered at the firm level. HP denotes heavy-polluting firms.
Table 8. Heterogeneity Analysis Results.
VariableSOEsNon-SOEsLargeSmallHigh Init.GILow Init.GI
(1)(2)(3)(4)(5)(6)
EPU0.0426−0.00770.0784−0.01490.2117 ***−0.0444
(0.0655)(0.0555)(0.0741)(0.0493)(0.0717)(0.0316)
HP0.13560.1848 ***0.2347 **0.0944 **0.1891 *0.1051 **
(0.0889)(0.0707)(0.0937)(0.0461)(0.1128)(0.0427)
EPU × HP−0.1025 ***−0.0674 ***−0.1074 ***−0.0326 **−0.1271 ***−0.0393 ***
(0.0195)(0.0160)(0.0206)(0.0137)(0.0247)(0.0095)
Constant−1.4755 **−1.9845 ***−1.2706−1.5528 ***−1.8923 **0.2665
(0.6649)(0.6462)(0.7775)(0.4878)(0.7624)(0.3324)
ControlsYESYESYESYESYESYES
Firm FEYESYESYESYESYESYES
Year FEYESYESYESYESYESYES
# of Obs.11,57113,13012,71312,49712,23712,973
R-squared0.01950.01490.01780.00660.03390.0155
Note: ***, **, and * indicate significance at the 1%, 5%, and 10% levels, respectively. Robust standard errors are clustered at the firm level. HP denotes heavy-polluting firms.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.