Article

Managerial Climate Attention and Systemic Risk of New Energy Vehicle Firms: Evidence from China

School of Economics and Management, Changsha University of Science and Technology, Changsha 410076, China
Sustainability 2025, 17(17), 8042; https://doi.org/10.3390/su17178042
Submission received: 4 August 2025 / Revised: 27 August 2025 / Accepted: 3 September 2025 / Published: 6 September 2025

Abstract

In the context of the global climate transition, managerial climate attention is influencing the risk posture of new energy vehicle firms as a key non-economic cognitive factor. This paper investigates the mechanism of managerial climate attention (MCA) on the systemic risk of firms using panel data from 111 listed NEV firms in China from 2013 to 2022. The results show that first, the systemic risk of NEV firms is significantly reduced as managerial climate attention increases. Second, the negative influence of MCA on the systemic risk of NEV firms is more significant among state-owned enterprises, firms in non-first-tier cities and in the machinery, equipment and computer communication sub-sectors. Third, MCA negatively affects the systemic risk of NEV firms by increasing market competition, environmental performance and investor sentiment. The difference-in-differences analysis based on the Paris Agreement shows that the systemic risk of the treatment group enterprises increased significantly after policy implementation, confirming the link between climate-related policies and risk. The management of NEV firms should be concerned about climate change, thus providing practical implications for financial stability and sustainable economic development.

1. Introduction

Amid intensifying global climate challenges, the transition toward low-carbon economies has emerged as a key sustainable development priority, as emphasised by international frameworks like the Paris Agreement [1,2,3]. The transportation sector, a major carbon emitter, plays a pivotal role in this transition, with new energy vehicles (NEVs) positioned as a sustainable alternative to traditional fuel vehicles [4]. Supported by policy incentives and technological advancements, the NEV industry has experienced rapid growth, contributing to emissions reduction and energy structure optimisation [5]. However, this expansion also introduces systemic risks that threaten the sector’s long-term sustainability. Firstly, the gradual retreat of the government subsidy policy is constantly testing the cost control ability and cash-flow health of firms. Secondly, the rapid iteration of battery technology routes may rapidly depreciate the value of existing production lines and trigger structural risks upstream and downstream in the supply chain. Thirdly, there is also uncertainty about the pace of market demand growth and changes in consumer preferences, making accurate strategic planning increasingly difficult. Unlike conventional automakers, NEV firms face heightened vulnerabilities due to their dependence on external conditions [6]: (1) policy sensitivity—subsidy cuts and carbon pricing mechanisms directly affect financial stability; (2) technological disruption—competition in battery innovation may destabilise supply chains; and (3) market volatility—fluctuating material costs and uneven consumer adoption amplify operational risks. These underscore the need to balance growth with risk, ensuring that the NEV industry’s development aligns with economic sustainability goals.
Management’s focus on climate issues, as the subject of corporate strategic decision-making, may affect systemic risk through the following pathways: (1) The risk mitigation effect. High climate attention may drive forward-looking technology investment, supply chain decarbonisation layout and enhance long-term corporate resilience. (2) Risk exacerbation effects. Excessive focus on short-term climate policy compliance may lead to a mismatch of resources, crowding out core R&D funding and instead magnifying risks.
Existing research on the factors affecting the systemic risk of firms mostly focuses on the traditional dimensions of finance and economy [7,8,9,10], but there is little literature exploring the role of non-financial dimensions on the systemic risk of firms, especially from the perspective of managerial climate concern. Meanwhile, although current climate change-related research has gradually expanded to the macro level and industry comparison level [11,12,13], the research on how the subjective perception of firm management on climate issues is transmitted to micro risk behaviour of the firm is still weak, and its intrinsic influence path has not been fully revealed. The dual role of NEV firms as “climate solution providers” and “high-risk industry players” makes them ideal candidates for studying this issue. This study elucidates the link between managerial climate attention and systemic risk, thereby enriching corporate climate governance theory while offering sustainable insights for investors to assess risk exposure and for policymakers to design targeted regulatory frameworks.
The research explores the effect of managerial climate attention on the systemic risk of NEV firms, and reveals the mechanism between the two through a combination of theoretical analyses and empirical tests. This research begins with the hypothesis that managerial climate attention reduces the systemic risk of firms through three paths: market competition, environmental performance and investor sentiment. Second, 111 listed NEV firms in China from 2013 to 2022 are taken as a sample, and text analysis is applied to quantify the frequency of climate keywords in companies’ semi-annual and annual reports, especially in the Management Discussion and Analysis (MD and A) section, as a core explanatory variable. The ΔCoVaR model is used to measure the firms’ systemic risk, and mechanism variables such as market competition, environmental performance and investor sentiment are introduced. Methodologically, a panel data fixed effects model is used for benchmark regression, endogeneity is mitigated by instrumental variables approach and the difference-in-differences model, bootstrap-mediated effects are applied to test the path of the mechanism, and sub-sample heterogeneity analysis is carried out. This study advances sustainable governance by linking climate awareness to financial stability.
The contributions are as follows. Firstly, the risks of firms are categorised into systemic and non-systemic risks. This study focuses on the systemic risk dimension of risk of the firm; it breaks away from the traditional research paradigm of focusing on non-systemic risk such as financial risk and explores the mechanism of managerial climate attention on the systemic risk of NEV firms. The research builds a dynamic analytical framework for early warning of systemic risk in NEV firms in the context of climate change, which is of great theoretical value in preventing cross-market risk contagion. Secondly, unlike studies that examine the effect of traditional financial and economic factors on firms’ risk management [14,15,16,17,18,19], this paper explores the impact of managerial climate attention on systemic risk in NEV firms. This helps to reveal the unique role of non-financial factors in risk management in the NEV industry, expands the cognitive boundaries of systemic risk drivers, and provides perspectives for understanding corporate sustainability in the climate transition. Thirdly, incorporating managerial climate attention, a non-financial indicator, into the research framework of the systemic risk of NEV firms, revealing the pathways through which climate governance awareness affects the risk levels of the firm, and realising the precise correlation between cognitive factors and risk effects, bridges the theoretical gap that traditional financial risk models ignore: management’s subjective initiative. This provides empirical evidence for regulators to formulate differentiated climate risk regulatory policies, for investors to identify climate-resilient firms and for corporate management to optimise climate risk management strategies.
The paper is structured below. Section 2 describes the literature review and research hypotheses. Section 3 introduces the research methodology and data. Section 4 provides the empirical analysis. Section 5 is further analysis. Section 6 gives the conclusions and discussion.

2. Literature Review and Hypothesis Development

2.1. Literature Review

Previous metrics about measuring the systemic risk of firms use value-at-risk (VaR) [20], but VaR has some limitations. First, VaR is a non-consistent risk measure that does not satisfy subadditivity. Second, VaR underestimates tail risk. It does not capture tail losses that are below the quantile point, which is the focus of attention when a crisis erupts. Finally, VaR ignores the interconnections and influences between financial institutions and fails to capture risk spillovers.
To address the shortcomings, Adrian and Brunnermeier (2008) introduced conditional value at risk (CoVaR) [21]. The value of spillover risk ΔCoVaR is defined as difference between CoVaR and unconditional VaR. Many scholars have started to measure and study systemic risk using ΔCoVaR [22]. Specifically, Mendonca and Silva (2018) measured systemic risk in Brazilian banks using ΔCoVaR, with a special focus on how accountants and macroeconomic variables contribute to systemic risk [8]. Qian et al. (2025) used the LASSO-ΔCoVaR methodology to construct network topologies and systemic risk indicators and empirically analyse the characteristics of time-varying tail risk spillovers between Chinese banks and firms [23]. Dungey et al. (2022) surveyed systemic importance of U.S. non-financial firms using ΔCoVaR [24]. Li et al. (2025) studied the impact of common institutional ownership on the systemic risk of non-financial firms using data on common institutional ownership and the systemic risk of listed manufacturing firms in China [25]. Zhu et al. (2025) examined the influence of bank liquidity hoarding on risk spillovers of nonfinancial firms [26].
The existing literature has focused on systemic risk in a number of areas such as the stock market, the real estate market and the banking sector [27,28,29,30,31]. In contrast, little research has been performed on systemic risk in firms. Li et al. (2023) found that capital market liberalisation greatly increases the systemic risk of non-financial firms in China [14]. Li et al. (2023) examined how macro-prudential policies affect the systemic risk for listed real estate firms in China using their data [15]. Anwer et al. (2023) [16] evaluated the effect of ESG performance on the systemic risk in major energy firms. While ESG is positively related to default risk, the squared value of ESG performance is negatively related. Lan and Meng (2024) demonstrated that economic policy uncertainty notably increases the systemic risk of real enterprises in terms of financing constraints and external guarantees [17]. Liu et al. (2024) explored the effect of uncertainty factors such as the macroeconomic uncertainty index, the financial uncertainty index and the economic policy uncertainty index in the United States on the systemic tail risk of Chinese firms [18]. Uncertainty in the U.S. is positively associated with systemic tail risk for firms in China. Li et al. (2025) [32] investigated the effect of stock pledges on the systemic risk of non-financial firms in the Chinese A-share market. The greater a stock pledge level, the greater a firm’s contribution to the systemic risk of the stock market.
In summary, current research on the factors influencing the systemic risk of firms focuses mainly on the financial and economic domains, while there is a lack of attention and research on emerging risk factors, such as managerial climate attention. In emerging industries, especially in new energy vehicle, the impact of management decisions about firm stability is becoming more and more significant. Given that climate change is a major global issue and that managerial attention to climate change is a part of firm strategic orientation, it is particularly important to explore the systemic risk of firms. Therefore, this paper endeavours to fill the gap in this area by examining the effect of managerial climate attention on the systemic risk in new energy vehicle firms.

2.2. Hypothesis Development

In the context of climate change, the ability of new energy vehicle firms to address the climate change challenge can affect their financial stability and sustainability [33,34]. Lack of management attention to climate change can lead to firms being less prepared in terms of strategic planning, technological innovation and risk management [35,36]. Firms struggle to respond to environmental regulations, market demand for green products and climate-related physical risks [37,38]. Such neglect increases the likelihood of policy compliance risks, reduced competitiveness in the marketplace and supply chain disruptions, thus driving up systemic risk. From this, we propose Hypothesis 1:
H1. 
The lower (higher) the managerial climate attention, the higher (lower) the systemic risk of new energy vehicle firms.
Established research has found that firm type, location characteristics and industry attributes affect the effectiveness of climate governance decisions through institutional pressures and resource endowment differences [19,39]. The paper further combines institutional theory and regional economics perspectives to propose the following theoretical mechanisms to explain the heterogeneous impact of managerial climate attention on the systemic risk of a firm:
There are essential differences based on the type and intensity of institutional pressures on firms, leading to different behavioural motivations and economic consequences of managerial climate attention. State-owned enterprises (SOEs) are heavily influenced by mandatory isomorphism (having to respond to the national “dual carbon” policy) and imitative isomorphism (imitating industry leaders or policy benchmarks) [2,40]. Non-SOEs are more driven by competitive isomorphisms (competitive market pressures) and normative isomorphisms (industry standards, investor requirements). SOEs need to prioritise responding to government climate policies, and managerial climate attention is more likely to be translated into substantial emissions reductions, thus reducing the risk of policy compliance [41,42]. SOEs typically enjoy higher levels of public trust, and their climate actions are more effective in boosting investor confidence and mitigating systemic risk arising from market volatility [43,44].
Differences in the regional innovation ecosystems in which firms are located and the strategic resources they possess lead to differences in their ability and pathways to translate climate attention into a competitive advantage, which in turn have different impacts on risk. China’s regional development policy is characterised by a ‘core-periphery’ divide [45], with non-first-tier city firms facing the following unique scenario. Local governments often provide policy bonuses such as subsidies and land incentives to attract new energy vehicle industries [46,47], and managerial climate attention can be more efficiently aligned with local support to optimise supply chain costs and enhance risk resilience. Compared to first-tier cities, the intensity of market competition in non-first-tier cities is lower [48], making it easier for climate-orientated innovations to form differentiated advantages and reduce systemic risk associated with homogeneous competition in the industry.
The machinery, equipment and computer communications industries are in the middle and lower reaches of the industry chain and are applicators and innovators of low-carbon technologies. The climate transition presents more opportunities than risks for them. Technology-intensive industries (e.g., computer communications) are highly sensitive to climate policies (e.g., carbon tariffs and green power certification) [49], and managerial climate attention can drive faster technology iteration and avoid the risk of a technology lock-in. Capital-intensive industries (e.g., machinery and equipment) rely on long-term asset investments [50], and climate concerns can reduce the risk of stranded assets through green equipment upgrades, whereas resource-processing industries are dominated by commodity price volatility, and the marginal risk mitigation effect of climate governance is weaker. From this, we propose Hypothesis 2:
H2. 
The dampening effect of managerial climate attention on the systemic risk of new energy vehicle firms is more pronounced among state-owned enterprises (SOEs), firms headquartered in non-first-tier cities, and the machinery, equipment and computer communication sub-sector. These sub-industries represent core segments of the NEV industry chain, making their low-carbon transition more closely related to corporate risk.
Management’s concern about climate issues will drive firms to develop more environmentally friendly products and technologies, which will create competitive differentiation in the new energy vehicle market [51]. Such innovations can attract environmentally conscious consumers, increase market shares and reduce systemic risk due to fluctuations in market demand. Firms with leading green technologies may be able to access international low-carbon markets [52] and reduce their dependence on the single market, thereby reducing systemic risk. The Porter hypothesis suggests that strict environmental policies can stimulate innovation and increase firm competitiveness [53]. The resource-based view recognises climate-related innovation capabilities as a scarce resource for firms that enhance long-term competitive advantage [54].
Firms with high managerial climate attention are more likely to proactively comply with environmental regulations and avoid the risk of fines, shutdowns, or lawsuits [55], which reduces the systemic impact of sudden negative shocks on the firm. Improved environmental performance is usually accompanied by optimised resource efficiency (e.g., energy recovery and waste reuse), which directly reduces production costs [56,57], improves financial stability and reduces systemic risk. Natural resource dependence theory recognises that environmental management capabilities are key to a firm’s ability to cope with ecological constraints [58]. Legitimacy theory suggests that firms gain social legitimacy and reduce policy and regulatory risk by improving environmental performance [59].
Positive climate action enhances corporate ESG ratings, attracts green investors and low-cost green financing and lowers the cost of capital [60], thereby reducing financial risk. Investors are more optimistic about the long-term value of high climate-focused firms, reducing stock price volatility [61] and mitigating systemic risk from market uncertainty. Signalling theory suggests that management’s climate-focused behaviour signals a commitment to sustainable development to the market and enhances investor trust [62]. Behavioural finance suggests that ESG performance positively influences investor sentiment and reduces the risk of irrational selling [63]. From this, we formulate Hypothesis 3:
H3. 
Managerial climate attention affects the systemic risk of new energy vehicle firms through its impact on market competition, environmental performance and investor sentiment.

3. Research Design

3.1. Sample and Data

The new energy vehicle firms studied in this paper mainly include industries involved in the midstream of the new energy vehicle industry chain (core manufacturing links) and some of the upstream (materials and components). For example, the vehicle manufacturing industry includes manufacturers of completely new energy vehicles. The electrical machinery and equipment manufacturing industries mainly cover the manufacturing of motors, electronic control and charging equipment. The computer, communication and other electronic equipment manufacturing industries provide a large number of electronic components and systems. Chemical raw materials and chemical product manufacturing are the chemical basis of battery materials. The non-ferrous metal smelting and rolling processing industry mainly provides core materials for lithium-ion batteries. Other related industries are omitted.
Firstly, in order to ensure the availability and continuity of the data, we limit the study to A-share listed firms; this is because the share price data, financial data and annual report information required in the study have to come from publicly disclosed compliance documents. Secondly, China’s new energy vehicle industry entered a rapid development stage around 2013, and related companies began to go public on a large scale, which gradually resulted in a sufficient sample size; fewer new energy vehicle companies went public before 2013, which resulted in poorer data continuity. Therefore, we further exclude companies listed later than 2013, to ensure that at least ten years of observable market data are available for a more accurate estimation of systemic risk. Thirdly, we also excluded ST and ST* firms as well as firms with serious missing key variables to maintain sample quality and model robustness. The most recent year for which complete financial data is available is 2022, and thus the final list of 111 companies from 2013 to 2022 were identified, all of which are listed companies whose business covers the core segments of new energy vehicles and meets the above screening criteria. Although not all relevant manufacturers are covered, estimation bias due to missing data or an insufficient time span is avoided.
According to Ouyang et al. (2022), this paper constructs the systemic risk of new energy vehicle firms [64]. We use the MCA index [65], which is used to understand the subjective drivers of firm climate action. There are three levels of control variables in this paper: (1) firm financial data from the CSMAR database and iFinD database; (2) macroeconomic variables from the CSMAR database; and (3) energy price data from the EIA. In this paper, the missing data are complemented by linear interpolation to obtain balanced panel data. To eliminate the effect of extreme values, all continuous variables are Winsorized at the 1% and 99% quantiles.

3.2. Empirical Model

According to the literature [66,67], the panel model is used to study the relationship between managerial climate attention and the systemic risk of new energy vehicle firms. The form is:
Δ C o V a R i , t = α 0 + α 1 M C A i , t 1 + α 2 I i , t + α 3 M t + α 4 W T I t + λ t + μ i + ε i , t
where i is firm and t is year. For dependent variables, Δ C o V a R i , t is the systemic risk of new energy vehicle firms. For the independent variables, M C A i , t 1 is the key independent variable and is the level of climate attention by business managers; I i t is a firm-level control variable; M t is a macro external economic level control variable; and W T I t is an energy price return control variable. λ t is the time fixed effect. μ i represents individual fixed effects. ε i t is the error term. All regression models control for firm fixed effects and year fixed effects, using robust standard errors for firm-level clustering.

3.3. Variable Measurement

3.3.1. Systemic Risk of New Energy Vehicle Firms

According to Ouyang et al. (2022), we use the DCC-GARCH model which accounts for two types of systemic risk [64]: dynamic conditional value-at-risk (ΔCoVaR) and marginal expectation shortfall (MES). In this paper, MES is used as a robustness test.
This study uses a GARCH model which estimates the conditional co-movement among individual firms and the industries in which they operate. In this paper, the broad industry category in which new energy vehicle firms are located is set as manufacturing. The specific model is as follows:
u t = η + z t , z t | t 1 ~ N ( 0 , H t )
where u t = ( u 1 , t , , u K , t ) is the return of stock at time t (calculated by subtracting the previous period’s closing price from the current period’s closing price, dividing by the previous period’s closing price, and converting to percentage data), the expected value of condition u t is μ t = ( μ 1 , t , , μ K , t ) , z t = ( z 1 , t , , z K , t ) is the vector of standardised residuals, E [ z t ] = 0 , C o v [ z t ] = H , H t is the conditional variance–covariance matrix. We use the standardised residuals u i , t = z i , t / h i , t for estimating the conditional covariance over time. The conditional covariance matrix H t is further decomposed as follows:
H t = D t R t D t
where D t = d i a g ( h i , t ) , R t is the u t conditional correlation matrix at time t, and D t is the diagonal matrix formed by the conditional standard deviations of the individual sequences. The standard deviation is estimated using the GARCH(1,1) model:
h i , t = ψ + a i z i , t 1 2 + b i h i , t 1
Therefore, the DCC-GARCH model is defined as follows:
Q t = ( 1 a b ) Q ¯ + a u t 1 u t 1 + b Q t 1
R t = ( d i a g ( Q t ) ) 1 / 2 Q t ( d i a g ( Q t ) ) 1 / 2
where Q t = ( q i m , t ) is the time-varying covariance matrix of standardised residuals, u t , Q ¯ = E [ u t u t ] is the conditional correlation of u t and parameters a and b satisfy a + b < 1. The dynamic conditional correlations between individual firms (i) and the industries in which they operate (m) are as follows:
R i m , t = q i m , t / q i i , t q m m , t , i , m = 1 , , K   and   i m
Therefore, we define dynamic conditional value-a-risk (ΔCoVaR) by the following:
Δ C o V a R i , t D C C = h i m , t 1 / 2 / h i , t
ΔCoVaR measures the distribution of returns across the industry if one firm is in crisis. Acharya et al. (2017) proposed the marginal expected shortage (MES) [68]. MES gauges the expected loss in individual firms’ returns in the event of a significant decline in returns across the industry, and which represents the marginal contribution that individual firms make to systemic risk. A single firm’s expected loss ES is when that loss exceeds the expected value of V a R q i :
E S q i = E [ R | R V a R q i ]
where R denotes return. V a R q i is the likelihood that firm i loses VaR in a given time. Suppose that a% at the worst industry performance is I a % , and S 1 i / S 0 i is the stock return of firm i, the MES can be expressed as the following:
M E S a % i = E [ S 1 i / S 0 i 1 | I a % ]

3.3.2. Managerial Climate Attention

Business engagement in climate action is important for reaching peak carbon and carbon neutrality targets, and the key to business action is managerial decision-making. This paper uses the MCA index [65], which is used to understand the subjective drivers of firm climate action. The database of the index is derived from text mining of half-yearly and annual reports of firms, especially the Management Discussion and Analysis (MD and A) section. Climate keywords include air pollution, air quality, air temperature, biomass energy, carbon dioxide, carbon emission, carbon energy, carbon neutral, carbon price, carbon sink, carbon tax, carbon peak, carbon trade, low carbon, zero carbon, carbon reduction, clean energy, clean water, clean air, climate change, electric vehicle, energy conversion, energy environment, environmental sustainability, extreme weather, flue gas, forest land, gas emission, ghg emission, global warm, heat power, Kyoto protocol, Paris agreement, natural hazard, ozone layer, renewable energy, sea level, solar energy, water resource, wave energy, tidal energy, wind power, wind energy, new energy and energy efficiency [65,69,70].

3.3.3. Control Variables

The paper controls for three types of variables, i.e., firm-level control variables, macroeconomic-level control variables and energy-level control variables. These variables are considered to affect the systemic risk of new energy vehicle firms. Detailed information on all variables is displayed in Table 1.

3.4. Descriptive Statistics

Table 2 demonstrates the descriptive statistics of all variables. The standard deviation of MCA is 0.011, which suggests that the management of the new energy vehicle firms is concerned about climate issues. The mean value of ΔCoVaR is 0.321, the maximum value is 0.700 and the standard deviation is 0.147, which suggests there is a gap in the systemic risk of different firms. All variables pass the unit root test.

4. Results and Discussions

4.1. Baseline Result

Table 3 shows the impacts of MCA on systemic risk in new energy vehicle firms. According to column (1), each unit increase in MCA decreases the firm’s systemic risk ΔCoVaR by 0.525 units, which is significant at the 1% level. Column (10) displays the findings after adding all control variables. It can be seen that each unit increase in MCA decreases the firm’s systemic risk ΔCoVaR by 0.505 units and is significant at the 1% level. This suggests that increased attention to climate change by the management of new energy vehicle firms will decrease the systemic risk of the firms. The coefficients remain stable after the addition of control variables, indicating that the core explanatory variables are less correlated with the omitted unobservables, alleviating the omitted variable bias. This suggests that the baseline regression results may be more reliable, and that the effect of the core variables on the explanatory variables is not driven by other confounding factors.
This finding provides insight into the intrinsic link between firm strategic cognition and financial risk in the context of the transition to a low-carbon economy. The conclusion can be strongly supported by several theoretical frameworks, most notably stakeholder theory and the resource base view. The high level of managerial attention means that organisations are no longer looking at climate as a passive compliance cost, but as a core strategic opportunity and risk management point [66,71]. This forward-thinking knowledge leads to active investment in technological innovation, deeper ESG practices and stronger relationships of trust with key stakeholders such as governments, investors and communities [72,73]. These actions make it resilient to external systemic shocks. Examples include sudden and severe environmental regulations (policy risk), sharp fluctuations in fossil fuel prices (market risk) or a collapse in investor confidence due to allegations of “greenwashing” (reputational risk). Highly visible management is therefore essentially building a “moat” for the firm, reducing the sensitivity of its share price to co-movement with the overall high-carbon economic system by enhancing its own resilience and reputational capital [74].

4.2. Heterogeneous Results

Given that the nature of firms, the economic development of cities and the status quo of industries are different, resulting in the systemic risk of enterprises showing differences. This paper analyses the heterogeneity based on the classification criteria of state-owned versus non-state-owned enterprises, headquartered in first-tier cities versus non-first-tier cities and the type of industry in which the enterprise is located, respectively.

4.2.1. Classification by Whether It Is a State-Owned Enterprise

Table 4 demonstrates the heterogeneous effect of managerial climate attention on the systemic risk of new energy vehicle firms. According to columns (1) and (2), the negative effect of MCA on firms’ systemic risk ΔCoVaR is more significant in state-owned firms and significant at the 1% significance level.
This finding has important theoretical implications and practical insights in the intersection of agency theory and stakeholder theory. In terms of agency theory [75,76], the management of SOEs usually faces more complex multiple principal–agent relationships, and their climate-focused behaviours are often not only economically rational decisions but also reflect the institutional requirements of policy implementation and social responsibility fulfilment. For instance, SOEs are required to implement “dual carbon” target assessments, making climate attention more likely to translate into emission reduction actions and the reduction in policy compliance risks. A strong climate attention significantly reduces systemic risk by aligning with national “dual carbon” strategies, reducing the risk of policy uncertainty, increasing government support and enhancing public legitimacy [77,78]. In contrast, while non-SOEs may also gain a market reputation for their environmental behaviour, their climate strategies are more susceptible to short-term profit-orientation constraints and lack deep embeddedness in macro policies, resulting in weaker risk mitigation effects. This finding critically extends traditional theories of corporate governance—in transition economies, the political relevance and social burden of SOEs may translate into an institutional advantage, especially in areas such as environmental governance where positive externalities are significant.

4.2.2. Classification by Whether the Headquarters Is a First-Tier City

According to columns (3) and (4) in Table 4, the negative effect of MCA on the systemic risk of firms ΔCoVaR is more significant among firms headquartered in non-first-tier cities and significant at the 1% significance level.
This finding has important implications in the context of the intersectional perspective of institutional and stakeholder theories. The negative correlation between managerial climate attention and the systemic risk of new energy vehicle firms in non-first-tier cities, which is more significant than that in first-tier cities, may reflect China’s unique institutional environment and market fragmentation characteristics. According to institutional theory [79], non-first-tier cities tend to face stronger institutional pressures and weaker market self-regulatory mechanisms, and managerial climate attention is therefore more likely to translate into substantive green procurement or co-operation decisions, thereby reducing systemic risks for new energy vehicle firms by stabilising the supply chain, enhancing the region’s reputational capital and gaining policy support. In contrast, the higher market maturity in first-tier cities, where climate attention is more likely to flow from firm-level ESG disclosures or marketing strategies rather than substantive risk mitigation actions, explains the difference in significance.

4.2.3. Classification by Sub-Industry

Columns (5) and (6) in Table 4 display the findings categorised according to the sub-industry in which the firm is located. Specifically, resource processing industries include non-metallic mineral products and metal smelting. The machinery, equipment and computer communication industries include general equipment manufacturing; automobile manufacturing; railway shipbuilding; aerospace and other transport equipment manufacturing; and computer, communication and other electronic equipment manufacturing. According to columns (5) and (6), the negative influence of MCA on the systemic risk of firms ΔCoVaR is more significant among firms in the machinery, equipment and computer communication categories and is significant at the 1% significance level.
The findings of this study can be interpreted as being theoretically embedded in the framework of the intersection of resource dependence theory and institutional theory. Managerial climate attention affects systemic risk through a dual path. On the one hand, it strengthens firms’ compliance with trends in environmental regulation and reduces the uncertainty associated with policy shocks [80]. On the other hand, in technology-intensive industries (e.g., machinery, computer and communications), climate innovations are often synergised with energy efficiency improvements and patents on low-carbon technologies to enhance market competitiveness through green technological barriers, thereby reducing industry-specific risks (e.g., the threat of technological substitution) [81]. In contrast, new energy vehicle firms in the resource-processing industry are more dependent on natural capital than innovation capital; their risk structure is more affected by commodity prices and geopolitics and managerial climate attention makes it difficult to hedge against the resource curse effect.

4.3. Results of the Analysis of Mechanisms

To determine the roles of the degree of market competition, firms’ environmental performance and investor sentiment in the effect of management’s climate concern on firms’ systemic risk, this paper includes the Herfindahl index (HI), the environmental performance index (EP) and the investor sentiment index (IS) as mediating variables in the analysis. Specifically, HI is an inverse indicator of the degree of competition in a market. A higher value of the index indicates higher market concentration and weaker competition in the market; conversely, a lower value of the index indicates a more fragmented market and stronger competition in the market. The HI gives a higher weight to large firms by calculating the sum of the squares of the market shares of all market players, thus sensitively reflecting the monopolistic and competitive situation in the market. We measure EP using a combined environmental protection and governance score, which includes six aspects: exhaust gas reduction, wastewater reduction, dust reduction, perimeter waste utilisation and disposal and noise and light control implementation of cleaner production. They are given a score of zero, one or two depending on their level of disclosure (whether they disclosed, qualitative or quantitative). According to Baker and Wurgler (2006), a composite index of investor sentiment is used [61]. The results of the mechanism test are given in Table 5. Column (1) shows the results of the baseline regression.
Column (2) displays that MCA has a significant negative effect on HI, indicating that MCA promotes market competition. Column (3) shows that MCA has a significant negative effect on the systemic risk of firms and HI has a significant positive impact on the systemic risk of firms. This suggests that the mediating role of HI is significant. This suggests that managerial climate attention negatively affects the systemic risk of new energy vehicle firms by exacerbating market competition.
This finding can be explained in depth within the framework of the intersection of strategic competition theory and the resource base view. According to Porter’s theory of competitive strategy [82], managerial attention toward climate issues can be seen as a differentiated strategic orientation that drives firms to accelerate green technology innovation and product iteration, thus triggering more intense market competition within the industry. However, this increased competition reduces the monopoly rents of individual firms, while at the same time diversifying systemic risk through industry reshuffling and efficiency gains. This is consistent with the theoretical expectation of market competition as a mediating variable in the “climate risk transmission mechanism” proposed by Berk et al. (2021) [83]. It is worth noting that this conclusion implicitly criticises the traditional “green premium” theory: climate attention does not necessarily reduce risk directly through lower financing costs or policy bonuses but does so indirectly through the non-price channel of market competition to achieve risk reallocation. Further, from a dynamic capabilities theory perspective [84], the results imply that climate attention may strengthen firms’ market adaptability and innovation resilience, so that the industry as a whole exhibits lower systemic vulnerability in the face of external shocks.
Column (4) represents that MCA has a significant positive effect on EP, indicating that MCA increases firms’ environmental performance. Column (5) shows that MCA has a significant negative effect on the systemic risk of firms and EP has a significant negative effect on the systemic risk of firms. This indicates that the mediating effect of EP is significant. This suggests that managerial climate attention significantly reduces the systemic risk of new energy vehicle firms by enhancing firms’ environmental performance.
This finding is highly consistent with stakeholder theory and the resource base view. Managerial attention toward climate issues can be seen as a strategic investment [85] in improving environmental performance through enhanced environmental management (e.g., reducing carbon emissions, developing eco-friendly technologies), which in turn sends positive signals to the market, enhances investor confidence, reduces policy compliance uncertainty and potential reputational damage, and thus mitigates systemic risk for the firm. In the context of the “dual carbon” target, this mechanism highlights the important role of environmental governance in financial stability [86] and is consistent with the protective effect of environmental performance on firms’ resilience in the ESG research framework.
Column (6) shows that MCA has a significant positive effect on IS, indicating that MCA improves investor sentiment. Column (7) shows that MCA has a significant negative effect on the systemic risk of firms and IS has a significant negative influence on the systemic risk of firms. This indicates that the mediating effect of IS is significant. This suggests that managerial climate attention negatively affects the systemic risk of new energy vehicle firms by elevating investor sentiment.
This finding can be explained in terms of behavioural finance and signalling theory. Managerial public attention toward the climate serves as a positive ESG signal that can increase investor confidence in the long-term sustainability and policy resilience of firms, thereby improving market sentiment and reducing sentiment-driven volatility and risk premiums [87]. In the wider literature, this mechanism echoes research on the “low carbon premium” [88], whereby firms with good climate performance are more likely to be favoured by investors and have a lower cost of capital.

4.4. Robustness Test

The reliability and accuracy of the baseline regression results are tested using the instrumental variables method, the system GMM method, replacement models and the replacement of explanatory variables.

4.4.1. Endogeneity Test

To address endogeneity issues, the paper uses a two-stage least squares (2SLS) regression with the average proportion of female executives in other firms (woman) as an instrumental variable. Table 6 shows the regression results utilising women as instrumental variables. From column (1), the coefficients of women are significant at 1% level of significance in first stage regressions. As can be seen from column (2), the negative effect of MCA on ΔCoVaR estimated by women is significant at the 10% significance level, which suggests that instrumental variables are valid. We conducted a placebo test to regress the instrumental variable on lagged systematic risk. Column (3) presents the results, with statistically insignificant coefficients on the instrumental variable, suggesting that the instrumental variable is unlikely to affect current period risk through omission channels other than historical risk.

4.4.2. System GMM

In a real economy and society, risks may extend over a period of time. Therefore, the lagged term of risk may likewise have an impact on the current value at risk. This paper uses the system generalised method of moments (System GMM) and informs of a one-period lag term for systemic risk. Column (1) of Table 7 demonstrates the findings of the system GMM model. The impact of MCA on the systemic risk of new energy vehicle firms is remarkably negative.

4.4.3. Replacement Model and Explanatory Variable

To remove the possible interference of the model type on the results, we replace the baseline model with a model that includes only individual fixed effects. The findings are listed in column (2) of Table 7. Column (3) represents findings of our regression re-run by replacing the explanatory variable ΔCoVaR with MES. From the results, the effect of MCA on the systemic risk in new energy vehicle firms is still significantly negative, which is in the same direction as the baseline results. All these findings indicate that the findings of this paper are highly reliable and accurate.

5. Further Analysis

On 3 September 2016, China officially joined the Paris Agreement. We consider the Paris Agreement to be a quasi-natural experiment. We set 2016 as the year of policy implementation and used a difference-in-differences (DID) model to reveal the effect of the Paris Agreement on systemic risk for new energy vehicle firms. This effect was estimated through a comparison of the difference in change between the treatment and control groups pre- and post-policy intervention.
Cities with a better climate usually have a higher level of eco-awareness and sustainable development. Climate policies are more likely to be responsive to the public, firms and governments, resulting in an effective environment for policy implementation. Therefore, this paper sets the new energy vehicle firms headquartered in Kunming, Weihai, Qingdao, Xiamen, Zhuhai, Yantai, Hangzhou and Suzhou as the treatment group; the control group is the remaining sample of firms. The DID model is in the following form:
Δ C o V a R i , t = α 0 + α 1 D I D i , t + α 2 M C A i , t 1 + α 3 C o n t r o l i , t + λ t + μ i + ε i , t
where i is a new energy vehicle firm, t is the year and the remaining variables are described in Equation (1). If the registered address of the enterprise is located in the city of the processing group and the year is 2016 and later, D I D i , t is assigned a value of one, otherwise zero.
Table 8 displays the results of DID model. The coefficients of DID are significantly positive at the 5% level, with or without inclusion of control variables. This indicates that the treatment group has a significant additional positive change relative to the control group after the implementation of the 2016 Paris Agreement. This means the Paris Agreement had a positive influence on the treatment group, resulting in a rise in the systemic risk of firms in treatment groups compared to control groups.
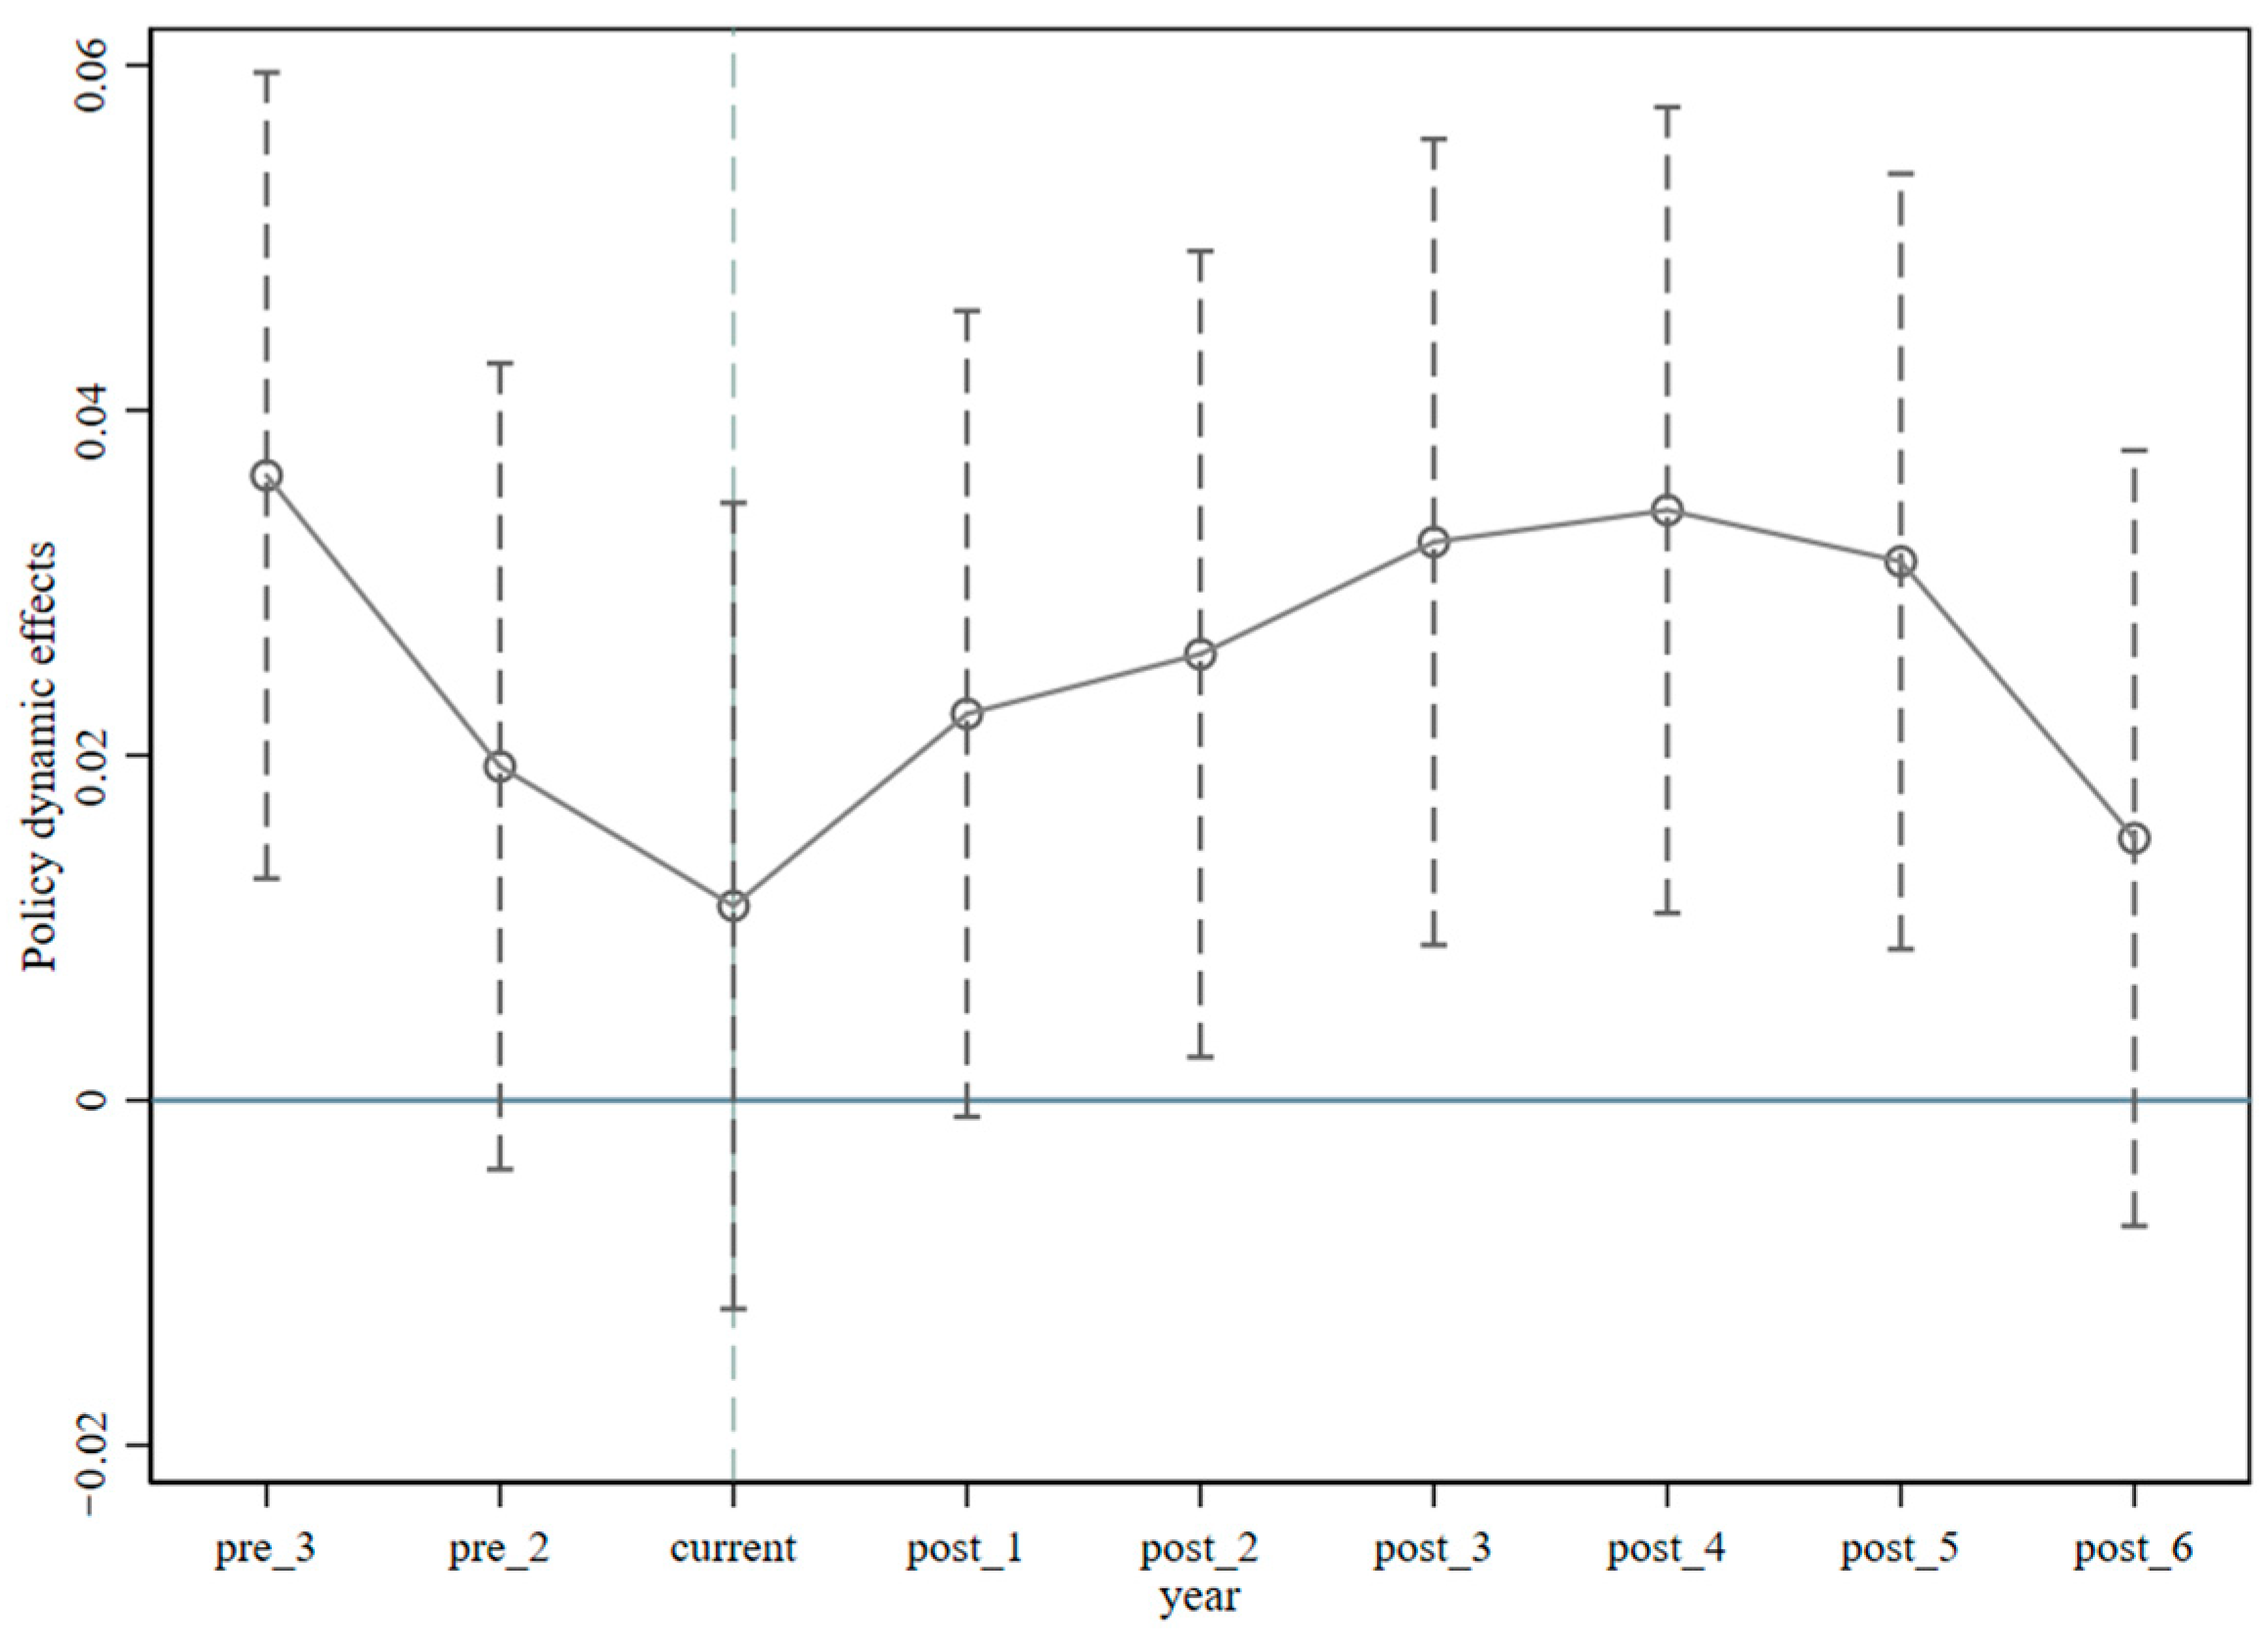
The parallel trend test plots are shown in Figure 1. To avoid the full covariance problem, we chose the period prior to the time of policy implementation to be the baseline set. Therefore, we dropped the data for −1 period. From Figure 1, it can be seen that before the policy was implemented, there was no obvious variation between treatment groups and control groups, which was passed by the parallel trend test, whereas the coefficient is significantly more positive after the implementation of the Paris Agreement, which suggests that the policy has produced positive effects since its implementation. The results suggest the Paris Agreement provides a positive effect on systemic risk for new energy vehicle firms.

6. Conclusions, Recommendations and Limitations

6.1. Conclusions

This research explores the mechanism of managerial climate attention on the systemic risk of firms using panel data of listed Chinese new energy vehicle firms. (1) Benchmark regression results suggest that managerial climate attention reduces the systemic risk of new energy vehicle firms. (2) Heterogeneity analyses show that the negative effect is more significant among new energy vehicle firms headquartered in non-first-tier cities, state-owned enterprises and machinery, equipment and computer communication industries. (3) Mechanistic analyses show that managerial climate attention negatively affects the systemic risk of new energy vehicle firms by increasing market competition, environmental performance and investor sentiment. The results could give a decision-making reference for the risk management and financial stability of new energy vehicle firms.

6.2. Policy Recommendations

Based on the findings of the study, the paper makes the following policy recommendations. Firstly, central government departments should strengthen top-level design, formulate a unified training programme on climate risk for firm managers and information disclosure standards and provide incentives through green financial policies; local government departments can focus on strengthening guidance and implementation support for non-first-tier cities and traditional manufacturing enterprises, taking into account the characteristics of local industries. Secondly, given the high sensitivity of state-owned firms to systemic risks, state-owned asset regulators should incorporate climate risk management into their firm assessment systems to promote their demonstration effect. Thirdly, the capital market should improve the ESG rating mechanism, strengthen investor sentiment guidance and give financing facilities to new energy vehicle firms that actively fulfil their environmental responsibilities to reduce their systemic risk premium. Fourthly, a climate risk early warning and sharing platform can be established at the industry level to promote the interconnection of environmental performance data among firms and to form an industry ecology for the collaborative prevention and control of systemic risks. These measures will help build a risk resilience system for the new energy vehicle industry in the context of the climate transition.

6.3. Limitations and Future Research

There are still some limitations in this research: Firstly, the sample only covers listed Chinese new energy vehicle firms, which limits the generalisability of the conclusions across other industries or economic contexts. Future research could extend to non-listed firms or incorporate cross-country comparative analysis to verify the robustness and applicability of the findings. Secondly, the measurement of managerial climate attention is mainly based on textual analysis; subsequent studies could improve accuracy by integrating multifaceted approaches such as questionnaires or on-site interviews. Furthermore, the study has not fully considered the potential effect of differences in the industry’s technological routes (e.g., pure electric vs. hydrogen energy) on risk transmission mechanisms, and future work could further segment technology sub-fields to clarify these pathways. The conclusions of this study are based on the expectation that the NEV industry as a whole is favourable, and that future research could incorporate methods such as a life cycle assessment to critically examine the industry’s net environmental benefits from a more macro perspective and to explore its relationship with long-term macroeconomic stability. Other promising future directions include exploring the dynamic moderating role of managerial attention in the context of abrupt climate policy changes and investigating the mediating mechanisms of digital technologies in enhancing the efficacy of climate risk management. These expansions will collectively contribute to building a more comprehensive theoretical system of climate finance for new energy vehicle companies.

Funding

This research was funded by the Postgraduate Scientific Research Innovation Project of Hunan Province (No. CX20240793).

Data Availability Statement

The raw data supporting the conclusions of this article will be made available by the authors on request.

Conflicts of Interest

The authors declare no conflicts of interest.

References

  1. Wu, W.; Zhang, N.; Li, A.; Chen, Y. The path to global climate justice: From the perspective of regional discrepancy in embodied carbon emissions. Environ. Impact Assess. Rev. 2024, 105, 107410. [Google Scholar] [CrossRef] [Scilit]
  2. Meng, S.; Duan, Y.; Zhou, W. How does green finance policy reduce the carbon emissions of polluting enterprises? A mediation effect analysis of inclusive finance. Res. Int. Bus. Financ. 2025, 77, 102914. [Google Scholar] [CrossRef] [Scilit]
  3. Ge, R.; Xia, Y.; Ge, L.; Li, F. Knowledge Graph Analysis in Climate Action Research. Sustainability 2025, 17, 371. [Google Scholar] [CrossRef] [Scilit]
  4. John, C.K.; Ajibade, F.O.; Ajibade, T.F.; Kumar, P.; Fadugba, O.G.; Adelodun, B. The impact of international agreements and government policies on collaborative management of environmental pollution and carbon emissions in the transportation sector. Environ. Impact Assess. Rev. 2025, 114, 107930. [Google Scholar] [CrossRef] [Scilit]
  5. Cao, L.; Deng, F.; Zhuo, C.; Jiang, Y.; Li, Z.; Xu, H. Spatial distribution patterns and influencing factors of China’s new energy vehicle industry. J. Clean. Prod. 2022, 379, 134641. [Google Scholar] [CrossRef] [Scilit]
  6. Yuan, X.; Liu, X.; Zuo, J. The development of new energy vehicles for a sustainable future: A review. Renew. Sustain. Energy Rev. 2015, 42, 298–305. [Google Scholar] [CrossRef] [Scilit]
  7. Pavlatos, O.; Kostakis, X. The impact of top management team characteristics and historical financial performance on strategic management accounting. J. Account. Organ. Chang. 2018, 14, 455–472. [Google Scholar] [CrossRef] [Scilit]
  8. Mendonca, H.F.; Silva, R.B. Effect of banking and macroeconomic variables on systemic risk: An application of ΔCOVAR for an emerging economy. N. Am. J. Econ. Financ. 2018, 43, 141–157. [Google Scholar] [CrossRef] [Scilit]
  9. Al-Hashimy, H.N.H. The relationship between financial management strategies and firm financial performance: The moderating role of firm size. J. Financ. Manag. Prop. Constr. 2025, 30, 295–317. [Google Scholar] [CrossRef] [Scilit]
  10. Salvi, A.; Martielli, F.; Battisti, E.; Forliano, C.; Kumar, S. Climate change management and companies’ financial performance: Exploring the moderating role of carbon credits. Res. Int. Bus. Financ. 2025, 75, 102785. [Google Scholar] [CrossRef] [Scilit]
  11. D’Orazio, P. Climate risks and financial stability: Evidence on the effectiveness of climate-related financial policies. Int. Rev. Financ. Anal. 2025, 105, 104304. [Google Scholar] [CrossRef] [Scilit]
  12. Yan, Y.; Lin, T.; Ma, H. The Impact of Corporate Climate Risk on Carbon Intensity: Evidence from China. Energy 2025, 334, 137532. [Google Scholar] [CrossRef] [Scilit]
  13. Zhao, X.; Yao, X.; Huang, J. Climate risks and financial stability: Evidence from China. Int. Rev. Financ. Anal. 2025, 104, 104307. [Google Scholar] [CrossRef] [Scilit]
  14. Li, X.L.; Li, H.; Ge, X.; Si, D.K. Capital market liberalization and systemic risk of non-financial firms: Evidence from Chinese Stock Connect scheme. Pac.-Basin Financ. J. 2023, 82, 102190. [Google Scholar] [CrossRef] [Scilit]
  15. Li, X.L.; Wang, L.; Kong, D. Macro-prudential policy and systemic risk of real estate firms: Evidence from China. Financ. Res. Lett. 2023, 58, 104518. [Google Scholar] [CrossRef] [Scilit]
  16. Anwer, Z.; Goodell, J.W.; Migliavacca, M.; Paltrinieri, A. Does ESG impact systemic risk? Evidencing an inverted U-shape relationship for major energy firms. J. Econ. Behav. Organ. 2023, 216, 10–25. [Google Scholar] [CrossRef] [Scilit]
  17. Lan, S.; Meng, W. Impact of economic policy uncertainty on systemic risk of real enterprises: Evidence from China. Financ. Res. Lett. 2024, 69, 106243. [Google Scholar] [CrossRef] [Scilit]
  18. Liu, L.; Xu, J.; Li, J. The spillover effects of US uncertainties on the systemic tail risk of Chinese enterprises. Financ. Res. Lett. 2024, 64, 105439. [Google Scholar] [CrossRef] [Scilit]
  19. Rahim, N.F.; Sulong, Z.; Abdullah, M.; Ullah, G.M.W. Geopolitical risk and firm climate change risk. Financ. Res. Lett. 2024, 85, 108212. [Google Scholar] [CrossRef] [Scilit]
  20. Ortega-Jiménez, P.; Pellerey, F.; Sordo, M.A.; Suárez-Llorens, A. Probability equivalent level for CoVaR and VaR. Insur. Math. Econ. 2024, 115, 22–35. [Google Scholar] [CrossRef] [Scilit]
  21. Adrian, T.; Brunnermeier, M.K. CoVaR. Working Paper; Federal Reserve Bank of New York: New York, NY, USA, 2008. [Google Scholar]
  22. Wang, H.; Liu, X. Volatility spillover features in financial industries and identification of systemically important financial institutions: A new perspective. Pac.-Basin Financ. J. 2024, 83, 102241. [Google Scholar] [CrossRef] [Scilit]
  23. Qian, S.Q.; You, H.; Zhang, X.Y. Systemic risk between banks and firms in dual-layer dynamic networks. Emerg. Mark. Rev. 2025, 66, 101276. [Google Scholar] [CrossRef] [Scilit]
  24. Dungey, M.; Flavin, T.; O’Connor, T.; Wosser, M. Non-financial corporations and systemic risk. J. Corp. Financ. 2022, 72, 102129. [Google Scholar] [CrossRef] [Scilit]
  25. Li, X.L.; Hao, J.W.; Liu, L. Does common institutional ownership affect systemic risk of non-financial firms? Evidence from China. Econ. Anal. Policy 2025, 87, 235–255. [Google Scholar] [CrossRef] [Scilit]
  26. Zhu, B.; Zhang, Y.; Li, X.; Hu, X. Systemic risk spillovers of nonfinancial firms: Does bank liquidity hoarding matter? Evidence from China. Int. Rev. Econ. Financ. 2025, 103, 104513. [Google Scholar] [CrossRef] [Scilit]
  27. Fang, Y.; Wang, Y.; Yuan, Y.; Zhang, M. Urban air pollution and systemic risk of the real estate market in China. Int. Rev. Econ. Financ. 2024, 96, 103626. [Google Scholar] [CrossRef] [Scilit]
  28. Castiglionesi, F.; Zhao, S. Banks incentive pay, diversification and systemic risk. J. Bank. Financ. 2024, 169, 107299. [Google Scholar] [CrossRef] [Scilit]
  29. Moura, B.G.F.; Ferreira, B.P.; Corrêa, A.C.C. Brazilian banks risk-taking and systemic risk. Q. Rev. Econ. Financ. 2024, 98, 101913. [Google Scholar] [CrossRef] [Scilit]
  30. Wu, B.; Wen, F.; Zhang, Y.; Huang, Z. Climate risk and the systemic risk of banks: A global perspective. J. Int. Financ. Mark. Inst. Money 2024, 95, 102030. [Google Scholar] [CrossRef] [Scilit]
  31. Henriques, I.; Sadorsky, P. Connectedness and systemic risk between FinTech and traditional financial stocks: Implications for portfolio diversification. Res. Int. Bus. Financ. 2025, 73, 102629. [Google Scholar] [CrossRef] [Scilit]
  32. Li, S.; Tian, S.; Gu, Q. Share pledging and non-financial corporations’ systemic risk contribution: Evidence from China. Res. Int. Bus. Financ. 2025, 73, 102604. [Google Scholar] [CrossRef] [Scilit]
  33. Basher, S.A.; Sadorsky, P. Do climate change risks affect the systemic risk between the stocks of clean energy, electric vehicles, and critical minerals? Analysis under changing market conditions. Energy Econ. 2024, 138, 107832. [Google Scholar] [CrossRef] [Scilit]
  34. Qiu, L.; Wong, X.; Zhang, T.; Song, Y. How Do Climate Risks Intersect with the Rise of New Energy Vehicles in China? Econ. Anal. Policy 2025, 87, 675–688. [Google Scholar] [CrossRef] [Scilit]
  35. Samadhiya, A.; Kumar, A.; Yadav, S.; Luthra, S.; Jabbour, C.J.C.; Agrawal, R. Artificial intelligence-partner relationships management for climate management in B2B firms to achieve sustainable competitiveness. Ind. Mark. Manag. 2023, 115, 510–525. [Google Scholar] [CrossRef] [Scilit]
  36. Zeng, F.; Guo, Y.; Fan, Q.; Wang, C.L. AI-orientation and company climate action: The moderating role of dependency structure and innovation capability. Ind. Mark. Manag. 2024, 117, 148–160. [Google Scholar] [CrossRef] [Scilit]
  37. Che, S.; Tao, M.; Ren, X. Climate risk exposure of global energy companies: Green chain vulnerability and countermeasures. J. Environ. Manag. 2025, 378, 124755. [Google Scholar] [CrossRef] [Scilit]
  38. Chen, Y.; Mamon, R.; Spagnolo, F.; Spagnolo, N. Stock market returns and climate risk in the US. J. Multinatl. Financ. Manag. 2025, 77, 100887. [Google Scholar] [CrossRef] [Scilit]
  39. Barbero, J.; Rodríguez-Crespo, E.; Suárez-Varela, M.; Velasco, P. Climate clubs and firm environmental performance: A regional institutional perspective. Econ. Anal. Policy 2024, 84, 663–678. [Google Scholar] [CrossRef] [Scilit]
  40. Zhao, L.; Liu, Z.; Xie, C.; Chen, X. Climate policy uncertainty and corporate carbon performance: Evidence from transportation enterprises. J. Environ. Manag. 2025, 390, 126346. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  41. Liu, Y.; Dong, K.; Nepal, R.; Afi, H. How do climate risks affect corporate ESG performance? Micro evidence from China. Res. Int. Bus. Financ. 2025, 76, 102855. [Google Scholar] [CrossRef] [Scilit]
  42. Cao, Y.; Liu, Y.; Lu, M.; Shan, Y.; Zu, Y. Generosity under environmental pressure: Climate change exposure and corporate philanthropy. Int. Rev. Financ. Anal. 2025, 104, 104336. [Google Scholar] [CrossRef] [Scilit]
  43. Ding, X.S.; Guo, M.; Kuai, Y.; Niu, G. Social trust and firm innovation: Evidence from China. Int. Rev. Econ. Financ. 2023, 84, 474–493. [Google Scholar] [CrossRef] [Scilit]
  44. Wang, L.; Qin, D.; Pan, L. The impact of accountability for illegal operation and investment on investment efficiency of SOEs: Evidence from China. Econ. Anal. Policy 2025, 86, 731–748. [Google Scholar] [CrossRef] [Scilit]
  45. Guo, L.; Tang, M.; Wu, Y.; Bao, S.; Wu, Q. Government-led regional integration and economic growth: Evidence from a quasi-natural experiment of urban agglomeration development planning policies in China. Cities 2025, 156, 105482. [Google Scholar] [CrossRef] [Scilit]
  46. Zhang, L.; Liu, H.; Zhang, X. Enhancing green housing diffusion through density bonuses: An analysis using the Use-Purchase-Supply model. Land Use Policy 2024, 147, 107369. [Google Scholar] [CrossRef] [Scilit]
  47. Qingli, T.A.N.; Yihua, G.A.N. Innovation Ability of China’s New Energy Industry from the Perspective of New Quality Productivity. Clean. Environ. Syst. 2025, 18, 100306. [Google Scholar]
  48. Guo, W.; Xia, W.; Kong, W.; Pan, Y. Policy, innovation, market or behavior driven effects: Energy green transition and environmental management in Chinese heterogeneous cities. J. Environ. Manag. 2024, 370, 122634. [Google Scholar] [CrossRef] [Scilit]
  49. Ghani, M.; Qin, Q. Forecasting climate-sensitive industries’ volatility: A regime-switching GARCH-MIDAS approach with multiple climate risk indicators. Int. Rev. Financ. Anal. 2025, 105, 104412. [Google Scholar] [CrossRef] [Scilit]
  50. Cai, X.; Li, P.; Zhu, W. Spatial proximity in venture capital investments and assets intangibility. Int. Rev. Financ. Anal. 2025, 106, 104464. [Google Scholar] [CrossRef] [Scilit]
  51. He, W.; Hao, X. Competition and welfare effects of introducing new products into the new energy vehicle market: Empirical evidence from Tesla’s entry into the Chinese market. Transp. Res. Part A Policy Pract. 2023, 174, 103730. [Google Scholar] [CrossRef] [Scilit]
  52. Lin, B.; Liu, Y. Global carbon neutrality and China’s contribution: The impact of international carbon market policies on China’s photovoltaic product exports. Energy Policy 2024, 193, 114299. [Google Scholar] [CrossRef] [Scilit]
  53. André, F.J.; Ranocchia, C.; Rubio, S.J. Porter Hypothesis vs. Pollution Haven Hypothesis: Can an environmental policy generate a win-win solution? Energy Econ. 2025, 146, 108477. [Google Scholar] [CrossRef] [Scilit]
  54. Stefano, M.C.; Montes-Sancho, M.J.; Busch, T. A natural resource-based view of climate change: Innovation challenges in the automobile industry. J. Clean. Prod. 2016, 139, 1436–1448. [Google Scholar] [CrossRef] [Scilit]
  55. Gunningham, N.A.; Thornton, D.; Kagan, R.A. Motivating management: Corporate compliance in environmental protection. Law Policy 2005, 27, 289–316. [Google Scholar] [CrossRef] [Scilit]
  56. Ali, M.H.; Zailani, S.; Iranmanesh, M.; Foroughi, B. Impacts of environmental factors on waste, energy, and resource management and sustainable performance. Sustainability 2019, 11, 2443. [Google Scholar] [CrossRef] [Scilit]
  57. Shah, H.H.; Amin, M.; Pepe, F. Maximizing resource efficiency: Opportunities for energy recovery from municipal solid waste in Europe. J. Mater. Cycles Waste Manag. 2023, 25, 2766–2782. [Google Scholar] [CrossRef] [Scilit]
  58. Tashman, P. A natural resource dependence perspective of the firm: How and why firms manage natural resource scarcity. Bus. Soc. 2021, 60, 1279–1311. [Google Scholar] [CrossRef] [Scilit]
  59. Akhter, F.; Hossain, M.R.; Elrehail, H.; Rehman, S.U.; Almansour, B. Environmental disclosures and corporate attributes, from the lens of legitimacy theory: A longitudinal analysis on a developing country. Eur. J. Manag. Bus. Econ. 2023, 32, 342–369. [Google Scholar] [CrossRef] [Scilit]
  60. Zheng, J.; Jiang, Y.; Cui, Y.; Shen, Y. Green bond issuance and corporate ESG performance: Steps toward green and low-carbon development. Res. Int. Bus. Financ. 2023, 66, 102007. [Google Scholar] [CrossRef] [Scilit]
  61. Baker, M.; Wurgler, J. Investor sentiment and the cross-section of stock returns. The journal of Finance 2006, 61, 1645–1680. [Google Scholar] [CrossRef] [Scilit]
  62. Song, S.; Lian, J.; Skowronski, K.; Yan, T. Customer base environmental disclosure and supplier greenhouse gas emissions: A signaling theory perspective. J. Oper. Manag. 2024, 70, 355–380. [Google Scholar] [CrossRef] [Scilit]
  63. Bhatnagar, M.; Rajaram, R. Correlating Investor Patterns and ESG Performance With Neuro Marketing Insights: Behavioural Finance Meets Sustainability. In Neuromarketing’s Role in Sustainable Finance; IGI Global: Hershey, PA, USA, 2025; pp. 1–20. [Google Scholar]
  64. Ouyang, Z.; Liu, M.; Huang, S.; Yao, T. Does the source of oil price shocks matter for the systemic risk? Energy Econ. 2022, 109, 105958. [Google Scholar] [CrossRef] [Scilit]
  65. Lei, L.; Zhang, D.; Ji, Q.; Guo, K.; Wu, F. A text-based managerial climate attention index of listed firms in China. Financ. Res. Lett. 2023, 55, 103911. [Google Scholar] [CrossRef] [Scilit]
  66. Dai, Z.; Zhang, X. Climate policy uncertainty and risks taken by the bank: Evidence from China. Int. Rev. Financ. Anal. 2023, 87, 102579. [Google Scholar] [CrossRef] [Scilit]
  67. Trabert, S. Do younger CEOs really increase firm risk? Evidence from sudden CEO deaths. J. Corp. Financ. 2023, 79, 102367. [Google Scholar] [CrossRef] [Scilit]
  68. Acharya, V.V.; Pedersen, L.H.; Philippon, T.; Richardson, M. Measuring systemic risk. Rev. Financ. Stud. 2017, 30, 2–47. [Google Scholar] [CrossRef] [Scilit]
  69. Sautner, Z.; Lent, L.; Vilkov, G.; Zhang, R. Firm-level climate change exposure. Eur. Corp. Gov. Inst.-Financ. Work. Pap. 2023, 686. [Google Scholar] [CrossRef] [Scilit]
  70. Friedman, H.L.; Huang, K.; Wu, K. Esg Attention in Capical Markets: Evidence from China’s Carbon Neutrality Pledge Announcement. Working Paper; Social Science Research Network (SSRN): Rochester, NY, USA, 2022. [Google Scholar]
  71. Kim, Y.; Park, Y.K.; Ryu, D. Climate policy uncertainty and corporate environmental risk-taking. Financ. Res. Lett. 2025, 82, 107555. [Google Scholar] [CrossRef] [Scilit]
  72. Abdulla, E.; Lim, K.Y.; Morris, D.; Saliba, F. Climate change and innovation: Exploring the mediating role of gender equality at the firm level. Energy Econ. 2025, 148, 108610. [Google Scholar] [CrossRef] [Scilit]
  73. Horbach, J.; Rammer, C. Climate change affectedness and innovation in firms. Res. Policy 2025, 54, 105122. [Google Scholar] [CrossRef] [Scilit]
  74. Sun, Y.; Wu, Z. Reputational risk and firm performance: Family versus nonfamily firms in different regulatory environments. J. Int. Financ. Mark. Inst. Money 2024, 93, 101976. [Google Scholar] [CrossRef] [Scilit]
  75. Shapiro, S.P. Agency theory. Annu. Rev. Sociol. 2005, 31, 263–284. [Google Scholar] [CrossRef] [Scilit]
  76. Liu, X.; Liu, J.; Pan, L. Does accountability for illegal operations and investments affect SOEs’ earnings management strategies? Evidence from China. China J. Account. Res. 2025, 18, 100433. [Google Scholar] [CrossRef] [Scilit]
  77. Zhang, C.; Li, Y.; Liang, S. Climate change attention and systemic financial risk: A TENET analysis. Financ. Res. Lett. 2025, 72, 106555. [Google Scholar] [CrossRef] [Scilit]
  78. Wang, C.; Jia, C.; Liu, X. Carbon-related credit concentration and banking systemic risk due to climate transition shocks. Int. Rev. Financ. Anal. 2025, 105, 104411. [Google Scholar] [CrossRef] [Scilit]
  79. Balzano, M.; Marzi, G.; Turzo, T. SMEs and institutional theory: Major inroads and opportunities ahead. Manag. Decis. 2025, 63, 1–27. [Google Scholar] [CrossRef] [Scilit]
  80. Li, S. Environmental regulation policy, firm endogenous capability, and green technological innovation: Evidence from a multi-period DID study in heavily polluting industries. J. Environ. Manag. 2025, 391, 126436. [Google Scholar] [CrossRef] [Scilit]
  81. Naz, M.; Maroof, Z.; Naheed, R.; Jawad, M. Climate bond issuance and enterprise EESM competitiveness: Steps toward environmental and climate-responsible development. J. Clean. Prod. 2025, 493, 144769. [Google Scholar] [CrossRef] [Scilit]
  82. Porter, M.E. Competitive Strategy: Techniques for Analyzing Industries and Competitors; Free Press: New York, NY, USA, 1980. [Google Scholar]
  83. Berk, J.; DeMarzo, P.; Harford, J.; Stangeland, D.; Marosi, A. Fundamentals of Corporate Finance, 4th ed.; Pearson Canada: Toronto, ON, Canada, 2021. [Google Scholar]
  84. Teece, D.J. Explicating dynamic capabilities: The nature and microfoundations of (sustainable) enterprise performance. Strateg. Manag. J. 2007, 28, 1319–1350. [Google Scholar] [CrossRef] [Scilit]
  85. Li, W.; Luo, D.; Cheng, T.Y. Strategy choices in strategic risk-taking: Does climate risk matter? Int. Rev. Financ. Anal. 2025, 97, 103861. [Google Scholar] [CrossRef] [Scilit]
  86. Wang, L.; Tang, R.; Zhou, X. Financial Crime Risks in Environmental, Social, and Governance (ESG) Investment: Perspectives on Greenwashing and False Disclosure. Financ. Res. Lett. 2025, 85, 107856. [Google Scholar] [CrossRef] [Scilit]
  87. Guo, X.; Li, R. Climate physical risks and corporate supply chain resilience: How do investor sentiment and risk-taking behaviors influence supply chain operations? Financ. Res. Lett. 2025, 85, 107903. [Google Scholar] [CrossRef] [Scilit]
  88. Krueger, P.; Sautner, Z.; Starks, L.T. The importance of climate risks for institutional investors. Rev. Financ. Stud. 2020, 33, 1067–1111. [Google Scholar] [CrossRef] [Scilit]
Figure 1. Dynamic effects of policy.
Sustainability 17 08042 g001
Table 1. Variable definitions.
VariableDefinition
ΔCoVaRSystemic risk.
MCAManagerial climate attention.
sizeNatural logarithm of total assets (%).
leverageFinancial leverage.
roaReturn on assets.
rdTotal R&D investment as a percentage of operating revenue.
cashRatio of cash assets.
debtGearing.
gdpGDP per capita index (previous year = 100).
msiMacroeconomic sentiment index (consensus index, 1996 = 100).
wtiU.S. West Texas Intermediate crude oil price returns (%).
Table 2. Summary statistics.
Obs.MeanStd.Dev.MinMaxADF
ΔCoVaR11100.3210.1470.0290.700295.257 ***
MCA11100.0170.0110.0030.0541028.723 ***
size11100.2240.0120.2020.264536.110 ***
leverage11101.2360.9310.0006.605572.052 ***
roa11100.0330.050−0.1870.160283.038 ***
rd11104.4702.3190.25012.700287.138 ***
cash11100.1310.0890.0160.423556.513 ***
debt11100.4440.1780.0830.795422.064 ***
gdp1110105.7981.836101.740108.010325.526 ***
msi111098.0415.54391.340110.360346.859 ***
wti11100.09033.233−64.95755.376492.376 ***
Notes: The *** indicating significance levels of 1%.
Table 3. Baseline results.
(1)(2)(3)(4)(5)(6)(7)(8)(9)(10)
MCA−0.525 **
(−2.15)
−0.520 **
(−2.10)
−0.531 **
(−2.15)
−0.528 **
(−2.13)
−0.505 **
(−2.04)
−0.505 **
(−2.04)
−0.505 **
(−2.03)
−0.505 **
(−2.03)
−0.505 **
(−2.03)
−0.505 **
(−2.03)
size −0.059
(−0.16)
−0.152
(−0.42)
−0.143
(−0.39)
−0.143
(−0.39)
−0.143
(−0.39)
−0.142
(−0.37)
−0.142
(−0.37)
−0.142
(−0.37)
−0.142
(−0.37)
leverage 0.002
(1.60)
0.002 *
(1.62)
0.002 *
(1.75)
0.002 *
(1.75)
0.002 *
(1.74)
0.002 *
(1.74)
0.002 *
(1.74)
0.002 *
(1.74)
roa −0.011
(−0.41)
−0.021
(−0.74)
−0.021
(−0.73)
−0.021
(−0.70)
−0.021
(−0.70)
−0.021
(−0.70)
−0.021
(−0.70)
rd −0.001
(−1.33)
−0.001
(−1.32)
−0.001
(−1.31)
−0.001
(−1.31)
−0.001
(−1.31)
−0.001
(−1.31)
cash 0.000
(0.02)
0.000
(0.02)
0.000
(0.02)
0.000
(0.02)
0.000
(0.02)
debt −0.000
(−0.01)
−0.000
(−0.01)
−0.000
(−0.01)
−0.000
(−0.01)
gdp −0.005 ***
(2.61)
0.770 ***
(3.46)
−0.002
(−1.49)
msi −2.659 ***
(−3.46)
0.001 ***
(3.20)
wti 0.001 ***
(3.46)
Constant0.317 ***
(75.75)
0.330 ***
(4.19)
0.348 ***
(4.38)
0.346 ***
(4.35)
0.352 ***
(4.41)
0.352 ***
(4.38)
0.351 ***
(4.27)
0.834 ***
(3.52)
170.235 ***
(3.46)
0.388 **
(2.36)
Firm Fixed EffectsYesYesYesYesYesYesYesYesYesYes
Year Fixed EffectsYesYesYesYesYesYesYesYesYesYes
Number of Firms111111111111111111111111111111
R-squared0.0640.0640.0670.0670.0690.0690.0690.0690.0690.069
Notes: This table presents the regression results for the impact of managerial climate attention on systemic risk of new energy vehicle firms. The t-values are reported in parentheses, with *, ** and *** indicating significance levels of 10%, 5% and 1%, respectively.
Table 4. Heterogeneity tests.
State-Owned
(1)
Non-State-Owned
(2)
First-Tier
(3)
Non-First-Tier
(4)
Resource Processing Industry
(5)
Machinery, Equipment and Computer Communication
(6)
MCA−1.595 ***
(−2.96)
−0.098
(−0.35)
0.354
(0.66)
−0.790 ***
(−2.80)
0.868
(1.29)
−0.805 ***
(−2.98)
size−0.321
(−0.33)
−0.158
(−0.37)
−0.931
(−1.11)
0.249
(0.57)
−0.319
(−0.42)
−0.443
(−0.94)
leverage0.007 ***
(3.01)
−0.000
(−0.33)
0.009 ***
(3.01)
0.001
(0.45)
−0.001
(−0.46)
0.003 **
(2.23)
roa−0.020
(−0.29)
−0.016
(−0.49)
−0.018
(−0.28)
−0.022
(−0.66)
0.046
(0.56)
−0.040
(−1.22)
rd−0.004
(−1.60)
−0.000
(−0.39)
−0.002
(−0.76)
−0.001
(−0.55)
−0.004
(−1.07)
−0.001
(−0.98)
cash−0.056
(−1.22)
0.012
(0.60)
0.055
(1.35)
−0.015
(−0.71)
−0.034
(−0.87)
0.011
(0.52)
debt0.078 **
(2.15)
−0.008
(−0.46)
0.024
(0.73)
−0.010
(−0.53)
0.002
(0.05)
−0.003
(−0.17)
gdp−0.005 **
(−2.02)
−0.001
(−0.47)
0.001
(0.62)
−0.002 **
(−1.99)
0.004
(1.53)
−0.003 ***
(−2.62)
msi0.002 **
(2.43)
0.001 **
(2.10)
0.003 ***
(3.28)
0.001
(1.37)
0.003 ***
(2.86)
0.001 **
(2.43)
wti0.001 ***
(3.70)
0.000
(1.62)
0.001 **
(2.14)
0.001 **
(2.26)
0.000
(1.16)
0.001 ***
(3.48)
Constant0.713 *
(1.75)
0.301 *
(1.68)
0.101
(0.28)
0.462 **
(2.49)
−0.298
(−0.80)
0.636 ***
(3.35)
Firm Fixed EffectsYesYesYesYesYesYes
Year Fixed EffectsYesYesYesYesYesYes
Number of Firms298231802487
R-squared0.2200.0570.1330.0690.1080.082
Notes: This table gives heterogeneity results for the impact of managerial climate attention on systemic risk of new energy vehicle firms. The t-values are reported in parentheses, with *, ** and *** indicating significance levels of 10%, 5% and 1%, respectively.
Table 5. Mechanism tests.
ΔCoVaR
(1)
HI
(2)
ΔCoVaR
(3)
EP
(4)
ΔCoVaR
(5)
IS
(6)
ΔCoVaR
(7)
HI 0.014 *
(1.73)
EP −0.002 **
(−2.41)
IS −0.005 **
(−1.99)
MCA−0.505 **
(−2.03)
−1.981 ***
(−4.02)
−0.503 **
(−1.99)
1.784 *
(1.74)
−0.502 **
(−2.03)
0.749 *
(1.76)
−0.515 **
(−2.04)
size−0.142
(−0.37)
4.448 ***
(5.85)
−0.222
(−0.56)
55.824 ***
(2.69)
−0.226
(−0.58)
9.953 **
(2.01)
−0.150
(−0.38)
leverage0.002 *
(1.74)
−0.002
(−0.98)
0.002 *
(1.79)
0.000
(0.00)
0.002 *
(1.75)
−0.033 **
(−2.11)
0.002 *
(1.83)
roa−0.021
(−0.70)
0.145 **
(2.46)
−0.024
(−0.78)
−2.29
(−1.42)
−0.017
(−0.58)
1.269 ***
(3.31)
−0.028
(−0.92)
rd−0.001
(−1.31)
0.007 ***
(3.62)
−0.001
(−1.43)
0.006
(0.11)
−0.001
(−1.32)
0.012
(0.90)
−0.001
(−1.35)
cash0.000
(0.02)
−0.047
(−1.27)
0.002
(0.09)
−2.162 **
(−2.16)
0.004
(0.19)
0.395 *
(1.66)
−0.001
(−0.06)
debt−0.000
(−0.01)
0.014
(0.46)
0.001
(0.05)
−2.353 ***
(−2.74)
0.003
(0.21)
0.641 ***
(3.12)
−0.004
(−0.24)
gdp−0.002
(−1.49)
0.018 ***
(8.29)
−0.002 *
(−1.73)
−0.247 ***
(−4.26)
−0.001
(−1.13)
0.007
(0.48)
−0.002
(−1.51)
msi0.001 ***
(3.20)
−0.001 *
(−1.65)
0.001 ***
(3.22)
0.032
(1.33)
0.001 ***
(3.10)
−0.003
(−0.52)
0.001 ***
(3.19)
wti0.001 ***
(3.46)
−0.002 ***
(−8.82)
0.000 ***
(3.54)
0.020 ***
(5.76)
0.000 ***
(2.94)
−0.001
(−0.01)
0.001 ***
(3.40)
Constant0.388 **
(2.36)
−2.500 ***
(−7.71)
0.436 **
(2.56)
14.095
(1.59)
0.366 **
(2.23)
−2.876
(−1.37)
0.394 **
(2.36)
Firm Fixed EffectsYesYesYesYesYesYesYes
Year Fixed EffectsYesYesYesYesYesYesYes
Number of Firms111111111111111111111
R-squared0.0690.2680.0690.2320.0750.4700.075
Notes: This table gives the results of mechanism tests. The t-values are reported in parentheses, with *, ** and *** indicating significance levels of 10%, 5% and 1%, respectively.
Table 6. Endogeneity test: 2SLS regression estimation.
First
MCA
(1)
Second
ΔCoVaR
(2)
L.ΔCoVaR
(3)
size0.196 ***
(0.029)
1.348
(0.936)
−0.183
(0.362)
leverage0.001
(0.000)
0.005
(0.004)
−0.001
(0.001)
roa−0.010
(0.005)
−0.118
(0.136)
−0.015
(0.028)
rd0.001 ***
(0.000)
0.026 ***
(0.001)
−0.001
(0.001)
cash−0.019 ***
(0.003)
−0.081
(0.081)
0.046 ***
(0.018)
debt0.011 ***
(0.000)
0.106 **
(0.040)
0.024
(0.015)
gdp−0.001 ***
(0.000)
−0.004
(0.004)
−0.001
(0.001)
msi0.001 ***
(0.000)
0.006
(0.002)
0.001 **
(0.000)
wti0.001 ***
(0.000)
0.005
(0.000)
0.000
(0.000)
woman10.105 ***
(0.001)
0.006
(0.018)
MCA −0.705 *
(0.856)
Constant−0.015
(0.015)
0.010
(0.376)
0.271
(0.140)
R-squared0.294 0.075
Notes: This table shows the results of 2SLS estimator with the instrumental variable. Standard errors are reported in parentheses, with *, ** and *** indicating significance levels of 10%, 5% and 1%, respectively.
Table 7. Robustness test.
System GMM
(1)
Replacement Model
(2)
Replacement of Explanatory
Variable: MES
(3)
L.ΔCoVaR0.088 **
(2.46)
MCA−0.488 **
(−1.97)
−0.715 ***
(−3.02)
−1.416 **
(−2.54)
size−0.129
(−0.34)
0.763 **
(2.30)
1.162
(1.49)
leverage0.002 *
(1.82)
0.002 *
(1.65)
0.003
(0.96)
roa−0.020
(−0.65)
−0.050 *
(−1.70)
−0.052
(−0.74)
rd−0.001
(−1.29)
−0.001
(−0.58)
−0.003
(−1.06)
cash−0.004
(−0.19)
−0.008
(−0.41)
−0.028
(−0.64)
debt−0.002
(−0.14)
−0.004
(−0.22)
−0.008
(−0.21)
gdp−0.002
(−1.44)
−0.002 *
(−1.82)
−0.003
(−1.27)
msi0.001 ***
(3.05)
−0.000
(−0.44)
−0.001 *
(−1.85)
wti0.001 ***
(3.39)
0.001 *
(1.89)
0.000
(1.07)
Constant0.359 **
(2.18)
0.338 **
(2.43)
0.578 *
(1.76)
Firm Fixed EffectsYesYesYes
Year Fixed EffectsYesNoYes
Number of Firms111111111
R-squared0.0750.0310.014
Notes: The table reports the results of robustness tests. The t-values are reported in parentheses, with *, ** and *** indicating significance levels of 10%, 5% and 1%, respectively.
Table 8. Impact of the 2016 Paris Agreement.
(1)(2)
DID0.016 **
(2.36)
0.016 **
(2.33)
MCA−0.553 **
(−2.26)
−0.538 **
(−2.17)
size −0.120
(−0.31)
leverage 0.002 *
(1.75)
roa −0.016
(−0.53)
rd −0.001
(−1.23)
cash −0.001
(−0.07)
debt 0.000
(0.03)
gdp −0.001
(−1.35)
msi 0.001 ***
(2.78)
wti 0.001 ***
(3.01)
Constant0.318 ***
(75.98)
0.384 **
(2.34)
Firm Fixed EffectsYesYes
Year Fixed EffectsYesYes
Number of Firms111111
R-squared0.0700.074
Notes: This table reports the results of the difference-in-differences (DID) approach. t-statistics are presented in parentheses. *, ** and *** means significant at the 10%, 5% and 1% level, respectively.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.