Article

ESG Integration in Residential Real Estate: The Case of Constanța, Romania

by
Maria Christina Georgiadou
* and
Maria Lǎcrǎmioara Ionica
School of the Built Environment, London Metropolitan University, 166-220 Holloway Road, London N7 8DB, UK
*
Author to whom correspondence should be addressed.
Sustainability 2025, 17(17), 7701; https://doi.org/10.3390/su17177701
Submission received: 23 July 2025 / Revised: 11 August 2025 / Accepted: 19 August 2025 / Published: 26 August 2025
(This article belongs to the Section Resources and Sustainable Utilization)

Abstract

This study examines the integration of Environmental, Social, and Governance (ESG) principles within Romania’s residential real estate sector, concentrating on Constanța, a rapidly evolving urban centre in a transitional economy. Drawing on qualitative data from semi-structured interviews with local real estate professionals and secondary analysis of policy and market documents, the research uncovers inconsistencies in ESG implementation. Environmental compliance is advancing, largely driven by EU regulations such as the European Grean Deal, the Corporate Sustainability Reporting Directive and the Energy Performance of Buildings Directive. Voluntary certification schemes like BREEAM and LEED are emerging as benchmarks for environmental performance; however, their uptake remains limited and insufficiently tailored to local conditions. Meanwhile, the social and governance dimensions lag behind, characterised by inconsistent application and weak institutional backing. Key barriers to effective ESG integration in Romania’s residential real estate sector include weak regulatory enforcement, fragmented policies, limited green finance, low awareness, and a lack of standardised social value metrics. The study concludes that without moving beyond mere regulatory compliance to a framework embedding social inclusivity and adaptive governance, ESG efforts risk perpetuating existing inequalities. It calls for a reconceptualisation of ESG frameworks, developed for mature markets, to better suit transitional urban contexts and support long-term resilience in residential real estate.

1. Introduction

The real estate sector is a major consumer of natural resources and a significant source of global carbon emissions, making it a critical component of climate change mitigation. International frameworks such as the Paris Agreement and the United Nations (UN) Sustainable Development Goals (SDGs), particularly SDG 11 (Sustainable Cities and Communities) and SDG 13 (Climate Action), endorse the importance of the built environment in achieving sustainability targets [1,2]. Environmental, Social, and Governance (ESG) principles have emerged as a key framework for promoting sustainable development, investment, and asset management in real estate.
Global initiatives including the UN Global Compact, the Principles for Responsible Investment, and the Sustainable Stock Exchanges Initiative have promoted the integration of ESG criteria into financial and property markets [3,4,5]. ESG frameworks are increasingly used to assess long-term asset risk, enhance portfolio resilience, and guide low-carbon urban strategies [6]. In turn, ESG performance influences asset valuation, investor decision-making, and real estate development outcomes [7,8].
In Europe, ESG integration in real estate is driven by regulatory requirements and shifting market expectations. Key legislative instruments, such as Corporate Sustainability Reporting Directive (CSRD) and the Sustainable Finance Disclosure Regulation (SFDR), are aligned with the European Green Deal and require firms to disclose ESG risks, strategies, and performance metrics [9,10,11,12]. These policies are formalising ESG adoption across the real estate sector. However, progress is uneven across member states. Advanced markets are moving quickly, while emerging economies like Romania face institutional, regulatory, and financial barriers [13,14].
Investor interest in ESG-compliant assets continues to rise. Certification systems such as BREEAM (Building Research Establishment Environmental Assessment Method), LEED (Leadership in Energy and Environmental Design), DGNB (German Sustainable Building Council), HQE (High-Quality Environmental), and the WELL Building Standard facilitate the integration of sustainability across building design, construction, operation, and management [15]. Since 2022, the European residential real estate sector has slowed after a decade of growth due to rising interest rates from the European Central Bank and tighter financing conditions. Additionally, stricter energy efficiency regulations have increased pressure on the sector [16,17]. Despite this, evidence indicates that certified buildings attract price premiums [18,19].
Romania, as an European Union (EU) member, is committed to achieving net-zero greenhouse gas emissions by 2050 in line with the European Green Deal [10]. However, ESG adoption within its real estate sector remains limited [13,14,17]. Key barriers include an ageing building stock, inconsistent enforcement of building codes and construction standards, low investor awareness and engagement, fragmented governance and regulatory frameworks, financial constraints, and limited access to green financing [14]. A 2022 survey of companies listed on the Bucharest Stock Exchange revealed that only 30% had an ESG implementation plan, while 63% reported limited familiarity with ESG requirements. Furthermore, 50% of respondents indicated a lack of transparency and did not employ any formal ESG reporting standards, highlighting the gap between regulatory expectations and market practice [20,21].
Certification systems are gradually gaining visibility in Romania, improving ESG data reporting and performance benchmarking [22,23]. Environmental concerns such as decarbonisation, energy efficiency, renewable energy, and biodiversity are becoming more visible [14,20,21,22,23,24], though the social and governance components of ESG remain underdeveloped [13,24,25]. Issues such as affordable housing and community engagement are rarely addressed in real estate development [19,21,23], and governance remains weak despite institutions such as the National Anti-Corruption Directorate [23,24].
The strategic value of ESG adoption is increasingly recognised, offering improved risk management, asset resilience, and investor confidence [21,22,23,24,25]. However, the available evidence remains largely concentrated in mature economies, with limited empirical insights from transitional and emerging markets [7,26,27].
While ESG adoption challenges in transitional economies are documented, Romania presents a distinctive context shaped by specific institutional, regulatory, and socio-economic factors affecting residential real estate. Unlike some neighbouring countries, Romania’s regulatory framework is fragmented with inconsistent enforcement. This is further complicated by the legacy of post-communist property ownership structures and comparatively low market transparency. These conditions create a unique environment where governance weaknesses, financial constraints, and limited investor engagement intersect, highlighting the importance of focused empirical research to better understand ESG integration in this setting. This study addresses this gap by examining ESG integration in residential real estate in Constanța, Romania’s largest coastal city and a rapidly growing urban centre. The study has the following objectives, namely to:
  • To map current ESG practices in Romania’s residential sector and identify key barriers and enablers of ESG adoption in emerging markets;
  • To explore how ESG performance affects investor perceptions, asset valuation, and market positioning in Constanța’s residential real estate market;
  • To provide evidence-based recommendations for policy and practice to accelerate ESG uptake in Romania and comparable contexts.
This study draws on semi-structured interviews with key stakeholders and a secondary analysis of relevant market and policy documents to examine how ESG principles are interpreted and operationalised within the context of transitional urban environments. As ESG implementation in emerging residential real estate markets is primarily driven by industry and regulatory actors, this focus provides a necessary foundation for understanding current approaches to balancing environmental and social priorities amidst rapid urban expansion. It also highlights the persistent gaps between policy ambitions and practical delivery, establishing the groundwork for further inquiry into context-sensitive, inclusive, and resilient urban development strategies aligned with the UN SDGs, EU’s decarbonisation, climate and social policy targets.

2. Theoretical Background

2.1. Environmental Integration of ESG in the European Residential Real Estate Market

Over the past decade, the integration of ESG principles into the European residential real estate sector has evolved from a secondary consideration to a central and strategic aspect of both regulatory frameworks and market practice. Among the three ESG pillars, the environmental dimension is the strongest and most comprehensively integrated element within policy instruments and industry practice, significantly outpacing the development of the social and governance pillars [28].
This shift has been guided by overarching EU frameworks such as the 2030 Climate and Energy Framework and the European Green Deal, both of which introduced progressively stringent decarbonisation targets [10]. Key legislative instruments such as the Sustainable Finance Disclosure Regulation (SFDR), the Corporate Sustainability Reporting Directive (CSRD), and the recast Energy Performance of Buildings Directive (EPBD) have collectively expanded ESG-related reporting and compliance obligations for a wide range of real estate stakeholders, including developers, investors, asset managers, and financial institutions [11,12,27,29,30]. These measures are complemented by Regulation 2023/0177, which enforces stringent oversight over ESG rating providers, aiming to enhance the credibility, transparency, and comparability of sustainability assessments across member states [31].
The EPBD requires EU member states to upgrade their residential building stock to achieve at least an Energy Performance Certificate (EPC) class E rating by 2030, with further targets to reduce average primary energy consumption by 16% by 2030 and between 20 and 22% by 2035 [30,32]. These goals are to be met primarily through the renovation of the least energy-efficient buildings, specifically targeting the bottom-performing 43% of the housing stock, where a minimum of 55% of energy efficiency improvements must be concentrated [33]. EPCs, as a key policy instrument of the EU’s decarbonisation strategy, are implemented through national methodologies that differ widely in calculation protocols, enforcement mechanisms, and data quality, thereby creating challenges for comparability and scalability across markets [15]. This heterogeneity constrains cross-border generalisability of performance outcomes, underscoring the need for harmonised approaches.
These regulatory developments are influencing investment strategies in the residential sector. Institutional investors, including pension funds and Real Estate Investment Trusts (REITs), are progressively shifting capital allocations toward ESG-aligned portfolios, motivated by risk mitigation and sustainability objectives [34,35]. EPCs and voluntary certification schemes, such as BREEAM, LEED, DGNB, HQE, or WELL, serve as key benchmarks for evaluating the environmental performance of housing assets [36]. Higher ratings typically indicate lower energy consumption, reflecting improvements in building fabric, management systems, and the integration of low- or zero-carbon technologies. These attributes enhance carbon performance, align residential properties with green investment criteria, and increase their attractiveness to environmentally conscious buyers and institutional investors seeking ESG-aligned portfolios. Properties with such credentials often command price premiums, benefit from stronger market demand, and demonstrate lower operational costs, higher occupant retention, and enhanced resale values, thereby informing valuation models and investment strategies [7,18,19,26,28,36,37]. However, the uneven application and recognition of these schemes between countries can lead to market segmentation, where the same sustainability credentials may hold differing market values depending on local policy environments and investor familiarity.
Despite their importance, the fragmented implementation of EPC schemes and underutilisation of voluntary certification tools reduce comparability across EU markets and limit their utility for decision-making [15,36,37,38]. Greater alignment of metrics, disclosure formats, and verification standards would not only enhance their effectiveness in supporting ESG-aligned investment decisions, but also facilitate cross-national benchmarking, a prerequisite for generating insights that are transferable beyond individual market contexts.
In parallel, ESG frameworks and benchmarking tools have become increasingly central to investment appraisal and performance monitoring. At the portfolio level, the Global Real Estate Sustainability Benchmark (GRESB) remains the most widely adopted tool by institutional investors globally. GRESB assesses ESG performance across real estate and infrastructure assets, including large-scale residential portfolios, by evaluating governance, environmental, and social indicators [7]. Its widespread uptake has promoted transparency and encouraged sustainability reporting within the sector. However, its reliance on self-reported data and voluntary participation can limit comparability and risk masking underperformance, particularly when applied across markets with differing disclosure cultures To address the shortcomings of global standards in capturing local specificities, Tailored Market Frameworks (TMFs) have emerged. These provide context-sensitive assessment tools better suited to national or regional residential markets. For example, the Common European Sustainable Building Assessment Mediterranean (CESBA MED) framework integrates the UN SDGs into a comprehensive approach for assessing sustainability at both building and neighbourhood levels within Mediterranean urban contexts [15,39]. Likewise, the EU’s LEVEL(s) framework offers a voluntary, performance-based tool tailored to European buildings [15,39]. It focuses on lifecycle-based performance metrics such as greenhouse gas emissions, resource efficiency, and climate resilience. Empirical evidence from pilot projects in Mediterranean urban contexts shows that CESBA MED adoption faces practical challenges such as limited access to reliable data, varying capacity in local administrations, and the need for extensive training, all of which hinder consistent implementation in emerging settings [39]. A comparative analysis of ESG frameworks focusing on their scope, metrics, verification methods, and adaptability to different regional contexts would provide valuable guidance for policymakers and investors in selecting the most appropriate tools for specific socio-economic and climatic conditions. This is particularly important in transitional economies of Eastern and South-Eastern Europe where regulatory frameworks and market incentives differ significantly from those in Western Europe, influencing both the uptake and long-term impact of such tools [39].

2.2. Social Integration of ESG in the European Residential Real Estate Market

While the environmental dimension of ESG is well established, the integration of social and governance considerations in the European residential real estate sector remains comparatively underdeveloped and conceptually fragmented [28]. Affordability remains a major issue, especially in urban areas, with investment prospects for affordable and social housing weakening due to rising construction costs, inflation, and fiscal uncertainty [17]. In addition, housing affordability is gaining increased recognition within ESG frameworks, particularly under the social pillar [40]. Although social demand for inclusive housing has increased, investor interest remains cautious due to perceived financial and regulatory risks. Policy initiatives have consequently sought to prioritise housing on the EU agenda, reflecting growing political attention to social sustainability [41].
However, this political emphasis has yet to translate fully into consistent and measurable social outcomes within residential developments, highlighting a critical gap between policy intent and practical delivery. Demographic trends further complicate social sustainability efforts. Eurostat [42] projects a decline in the EU population from 446.7 million in 2022 to 419.5 million by 2100, alongside increased life expectancy. These shifts are reshaping housing needs, driving demand for adaptable, accessible, and age-inclusive residential models. Emerging typologies, including senior housing, multi-generational units, and flexible living spaces, have been identified as strategic responses by both developers and policymakers [17].
While Corporate Social Responsibility (CSR) has become more prominent in the real estate sector, its integration into residential property development remains limited and uneven [43]. Within the built environment, social value refers to the broader social, economic, and environmental benefits that construction, infrastructure, and real estate projects contribute to individuals, communities, and wider society, extending beyond the delivery of physical or engineering structures [44,45]. In residential real estate, the social aspect of ESGs is closely tied to social value through housing affordability, occupant wellbeing, community resilience, and inclusive design factors that shape the lived experience across the project lifecycle [43,44]. However, practical implementation remains fragmented due to inconsistent terminology, regulatory gaps, and limited institutionalisation of social metrics within planning and investment processes [28,34,35,36,37,38,45,46,47].
This fragmentation signals the necessity for harmonised definitions and standardised metrics to facilitate integration of social value into ESG assessments and investment decisions [43]. Without this, the social pillar risks remaining a secondary concern, overshadowed by the more quantifiable environmental metrics. In particular, the measurement of social value remains challenging, with standardised indicators for outcomes such as social cohesion, mental health, and inclusivity often absent or weakly embedded in policy and practice [44,45]. Consequently, social considerations tend to be underrepresented in ESG reporting compared to environmental and governance dimensions [48,49]. Embedding the knowledge, experience, and values of residents, community groups, and local authorities into design and property management is increasingly recognised as essential for capturing social value and aligning developments with local community needs [44,45].
Although international frameworks like the UN SDGs have heightened attention to social outcomes, the quantification of social value remains problematic [44]. Tools such as Social Return on Investment (SROI) aim to measure social impacts in the residential development [44,45,49,50] but their effectiveness is limited by the subjective, context-specific, and multi-dimensional nature of social value. Unlike environmental metrics, social outcomes lack standardised indicators, making them difficult to measure, compare, or integrate into regulatory and ESG frameworks with consistency or rigour [45]. Therefore, advancing social value integration requires innovation in measurement approaches and policy incentives to encourage their adoption, an area that remains underexplored in existing research and practice.

2.3. Governance Integration of ESG in the European Residential Real Estate Market

Governance integration in the European residential real estate sector continues to lag behind environmental advancements. While financial transparency and corporate reporting are increasingly mandated, other governance dimensions, such as ethical leadership, stakeholder engagement, and community accountability, are rarely embedded in real estate regulations [51,52]. This regulatory gap limits the operationalisation of governance principles at both asset and organisational levels. This challenge is especially pronounced in transitional economies, where structural institutional weaknesses hinder effective governance integration. Issues such as weak enforcement mechanisms, fragmented governance structures involving multiple agencies with overlapping or unclear responsibilities, and a disconnect between formal policies and their practical implementation contribute to persistent governance gaps [13,23,24]. These systemic factors limit the embedding of ethical leadership and community accountability within real estate governance, despite the presence of formal regulatory frameworks.
Nonetheless, governance quality has been positively correlated with investment outcomes; attributes such as transparency, ethical conduct, and compliance have been associated with higher price-to-earnings ratios and stronger reputational performance in property markets [7,26,53,54]. Furthermore, effective governance underpins stakeholder engagement and fosters community trust, both of which are essential for long-term real estate asset resilience and social value creation [43,44,45,48,49,50].
Corporate Reporting Frameworks (CRFs) such as the Global Reporting Initiative (GRI) [55], EPRA Sustainability Best Practices Recommendations (sBPR) [56], the GRESB [57], the Greenhouse Gas Protocol (GHG Protocol), and the Carbon Disclosure Project (CDP) play a central role in ESG governance by enhancing accountability, transparency, and comparability [58]. These frameworks are increasingly adopted by residential developers, asset managers, and institutional investors seeking to improve decision-making and meet stakeholder expectations.
GRI is particularly prominent in Europe, especially among Nordic firms, which frequently adopt multiple frameworks to comprehensively disclose environmental and social performance [55,56,57,58]. The GHG Protocol and CDP complement these tools, reflecting the growing institutionalisation of CRFs across firms in multiple EU countries. GRESB’s influence on ESG governance is widely recognised, with EPRA sBPR also established as a standard in related studies [52,55,56,57,58].As an EU directive, the CSRD significantly strengthens governance by embedding clearer accountability mechanisms, mandating integration of ESG risks into corporate governance, and enhancing transparency for stakeholders [11]. By requiring consistent oversight and strategic management of sustainability factors, the CSRD positions governance as a central dimension of ESG across European residential real estate firms [58].

2.4. ESG Integration in Transitional Economies: The Romanian Context

While the EU has introduced a more harmonised ESG regulatory framework, its implementation in transitional economies such as Romania remains fragmented, inconsistent, and often superficial. ESG adoption in Romania’s residential real estate sector reflects broader patterns across newer EU member states, where progress is often incremental due to structural and institutional challenges [7,26,52,59]. However, existing literature insufficiently accounts for how institutional voids, characterised by weak formal institutions, limited enforcement capacity, and fragmented regulatory frameworks, fundamentally constrain ESG integration in transitional contexts [23]. Romania’s ESG integration is distinctly shaped by its unique post-communist institutional legacy, fragmented regulatory landscape, and socio-economic realities, setting it apart from neighbouring transitional economies. This theoretical lens is essential for understanding why ESG outcomes diverge from those in mature European markets [23,24,26].
Barriers including s limited institutional capacity, weak enforcement mechanisms, and low transparency particularly among Small and Medium-sized Enterprises (SMEs), continue to constrain meaningful integration [7,26,52,59]. Furthermore, ESG performance benchmarking tools like GRESB, though widely used by institutional investors, have important limitations: they rely heavily on self-reported data and often lack sensitivity to local governance, socio-political, and market contexts [7,57]. This reduces their effectiveness in capturing material risks and guiding investment decisions, particularly in emerging and transitional markets where regulatory maturity varies widely [52,57]. A critical gap in ESG research and practice in transitional economies is the lack of comparative synthesis evaluating the scope, metrics, verification processes, and adaptability of existing frameworks to Romania’s unique institutional and socio-economic conditions. This gap reflects a broader pattern of policy-practice decoupling, where formal compliance with EU ESG directives fails to result in meaningful implementation due to systemic institutional weaknesses and administrative inertia.
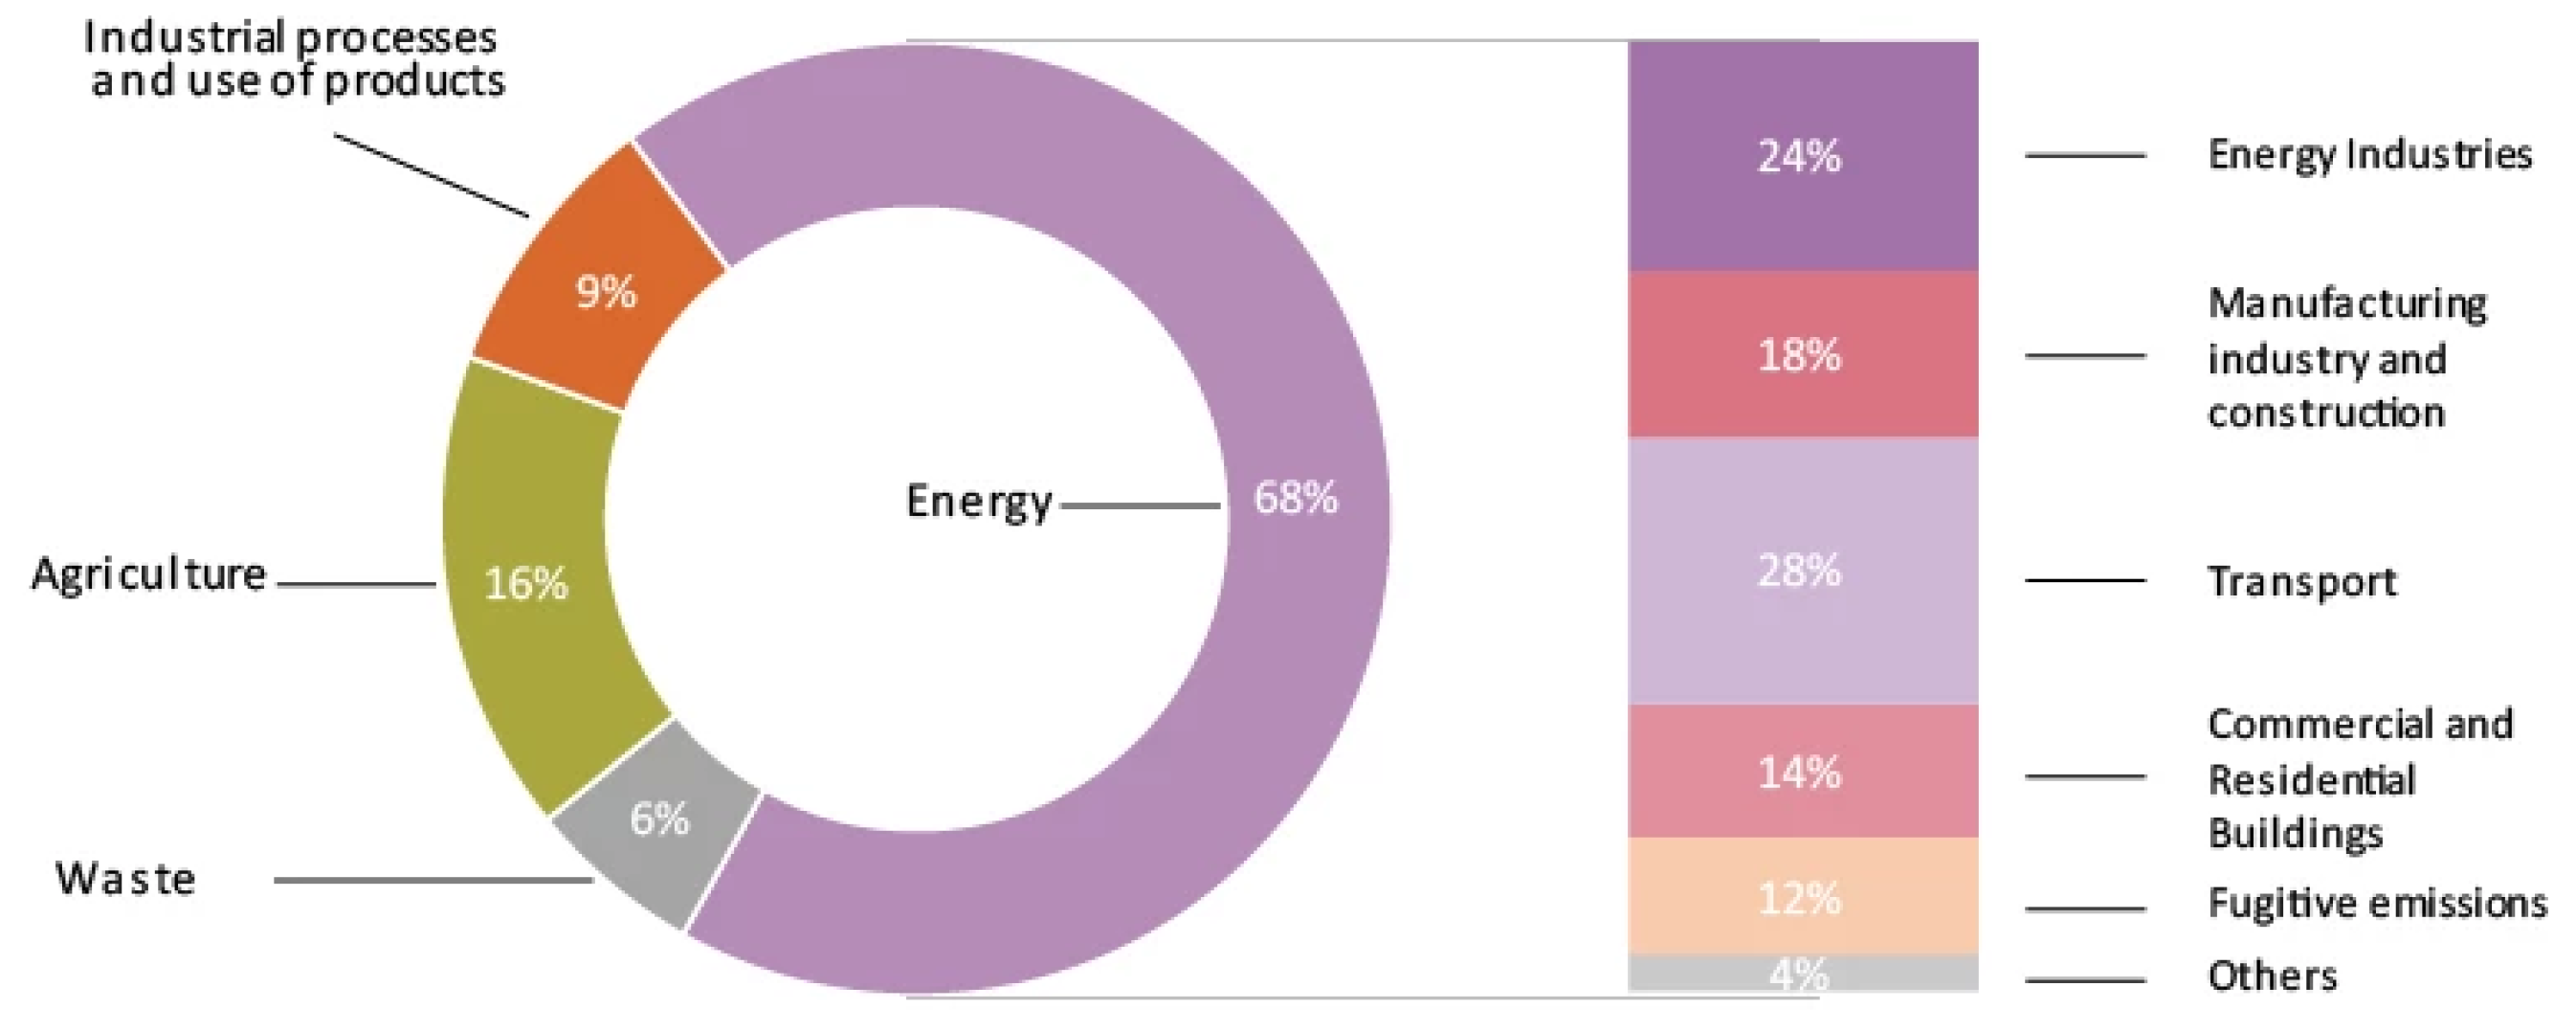
Romania’s recent environmental performance reflects growing alignment with EU sustainability goals, as shown in Figure 1. In 2022, its net GHG emissions per capita fell below the EU average, driven largely by decarbonisation in the energy sector, which accounted for approximately 68% of total national emissions [60]. Residential and commercial buildings contributed around 14%, revealing the significance of the built environment in national emissions profiles [60]. However, decarbonising Romania’s ageing and poorly insulated residential stock poses a substantial policy and investment challenge [22,61]. Around 80% of the housing stock requires significant thermal renovation to meet EU energy efficiency targets, highlighting an urgent need for large-scale retrofitting. However, most homeowners lack access to affordable financing, rendering such upgrades largely unfeasible without public support or targeted financial incentives [22,61,62].
Romania is progressively aligning with EU directives such as the Corporate Sustainability Reporting Directive and the Energy Performance of Buildings Directive, particularly through energy sector reforms and updated building regulations. Yet implementation remains inconsistent. Weak institutional frameworks, uneven enforcement, and limited data availability continue to impede effective policy delivery [36,62]. Municipalities, especially those outside major urban centres, frequently lack the technical and administrative capacity to enforce sustainability standards. These systemic constraints reflect widespread institutional voids and governance fragmentation that are characteristic of transitional economies and perpetuate a persistent gap between policy ambition and practical implementation, particularly impacting the small and medium-sized enterprises that predominate Romania’s real estate sector [36]. Compared to other transitional economies, Romania’s regulatory enforcement is further hindered by entrenched bureaucratic inertia and insufficient coordination between national and local authorities, which collectively restrict ESG integration at scale.
This challenging policy environment has direct implications for market behaviour. While the link between sustainability certifications, improved energy performance, and higher property values has been well established in mature markets [7,18,19,26,28,37], recent CBRE findings confirm a similar trend in Romania [36]. However, green investment uptake remains limited due to inconsistent data and disclosure practices, economic constraints, and regulatory uncertainty [13,14,20,22,23,24]. Without focused support and adaptation to local conditions, environmental initiatives risk remaining superficial and nominal in emerging markets [7,58].
The social dimension of ESG remains especially underdeveloped in transitional economies. Despite widespread housing affordability issues and growing concerns about urban equity, no standardised metrics or reporting frameworks exist to assess social value in the built environment. Indicators such as community wellbeing, inclusive design, local economic development, are rarely incorporated into development appraisals or investment models [63]. This gap reflects broader institutional voids common to transitional economies, where weak or absent formal structures limit the measurement and enforcement of social ESG dimensions. As a result, social outcomes remain difficult to quantify, and accountability mechanisms are often ineffective. Additionally, ESG frameworks often prioritise environmental metrics developed in mature markets, overlooking critical social considerations relevant to transitional contexts. In Romania and similar settings, social wellbeing and community resilience are key investment risks and determinants of asset value [46,52,63], yet existing ESG tools lack the flexibility to account for these local socio-economic realities [63,64,65]. Such limitations illustrate a clear policy-practice decoupling, where frameworks designed for advanced institutional environments fail to adequately address or reflect the social complexities and vulnerabilities characteristic of transitional markets. Governance in Romania’s residential real estate sector faces significant challenges. Although the National Anticorruption Directorate (DNA) supports public sector accountability, key ESG governance practices, such as sustainability oversight at the board level, stakeholder engagement, and transparent corporate reporting, are not well established in the sector [24]. Basic labour protections exist; however, broader governance issues such as ethical supply chains, inclusive hiring, and risk management are largely neglected [23,24,66]. This situation illustrates governance fragmentation, where overlapping or unclear mandates and insufficient coordination between regulatory bodies and corporate actors undermine comprehensive governance implementation. Governance remains a critical obstacle to ESG progress in transitional markets due to weak institutional capacity, fragmented regulations, and low transparency [58,59]. Furthermore, pervasive informal practices and corruption risks within the real estate sector erode transparency and stakeholder trust, impeding consistent ESG adoption [23,66]. Such informal governance and corruption reflect entrenched institutional voids, creating structural barriers to the development of robust ESG governance systems. These deficiencies foster reactive, compliance-driven responses rather than strategic, proactive management. Limited stakeholder engagement and ambiguous legal mandates exacerbate these challenges, restricting effective ESG implementation [58,67,68]. The frequent disconnect between formal ESG policies and their enforcement exemplifies policy-practice decoupling, intensified by institutional weaknesses and governance fragmentation that inhibit progress beyond superficial compliance. While EU initiatives such as the CSRD seek to enhance governance through mandatory disclosure, their effectiveness depends on the extent to which national frameworks adapt to local institutional and administrative contexts [68,69]. This highlights that without addressing fundamental institutional voids and fragmentation, governance reforms risk remaining largely symbolic rather than genuinely transformative in transitional economies.

3. Materials and Methods

3.1. Research Design

This study investigates the influence of ESG performance indicators on residential real estate in Constanța, Romania focusing on two primary research questions:
  • What is the current state and level of adoption of ESG performance indicators in the residential real estate sector in Constanța as an emerging market?
  • What are the challenges, key success factors, and future opportunities related to ESG integration, and how do these influence property valuation, investment attractiveness, and market preparedness in Constanța’s residential real estate market?
The study adopts a case study approach integrating interview data to provide a comprehensive understanding of ESG impacts on property values, market demand, and investor perspectives in the Romanian residential real estate sector, specifically in Constanța [70,71]. This method allows for an in-depth examination of phenomena within their real-world context, offering rich insights into how ESG factors influence investment and market behaviour [71]. Rather than aiming for generalisable findings, the study focuses on exploring context-specific conditions to identify patterns or trends that could be transferable or tested in other emerging markets [70,71].
Six semi-structured interviews were conducted with representatives from six real estate limited liability companies (SRLs) in Constanța as shown in Table 1, including Building Stefan, Imobiliaria Tomis SRL, Sun Constanța, Agenția Ella, and Biroul Imobiliar. Although these companies operate in the residential sector, their portfolios also encompass other areas of the property market. The six participants were purposively selected from established real estate companies operating in the residential sector of Constanța. Selection criteria included a minimum of seven years of market experience and relevant expertise in residential property development, investment, or sales, to ensure informed perspectives on ESG adoption.
These companies represent a substantial segment of Constanța’s residential real estate market. For instance, Building Stefan manages over 200 residential units alongside hospitality and rental services, while Imobiliaria Tomis SRL is a key regional developer and investor. The agencies (Sun Constanța, Agenția Ella, Biroul Imobiliar) hold significant shares of local sales and rental markets, collectively covering a broad client base. Precise market share and sales volume data were not publicly available nor provided by participants; therefore, market presence is inferred from publicly accessible company profiles and regional market analyses. This study critically examines ESG adoption from core industry actors in an emerging market. Although the sample lacks diversity because it does not include government, civil society, or financial institutions, this focused perspective is necessary to establish a clear understanding of developers’ views. As ESG integration in residential real estate is underexplored, especially in transitional economies, capturing this foundational insight is vital before expanding to broader, multi-stakeholder analyses.
Data collection took place between June and July 2024. Each interview lasted approximately one hour, allowing for open and in-depth discussions. The interviews yielded approximately seven hours of recorded material, which was translated into English and thematically analysed according to the three key themes of this study:
  • ESG awareness and perceived significance;
  • drivers influencing ESG adoption and its impact on market dynamics; and,
  • barriers to effective ESG engagement.
These themes emerged through an iterative thematic coding process, where initial codes were grouped and refined based on their relevance, frequency, and alignment with the research objectives, ensuring a comprehensive capture of the sector’s ESG landscape. To protect participants’ privacy, comments are anonymised, although the organisations involved are acknowledged. Table 2 presents the interview template, which also included structured questions for numerical analysis. Transcripts were shared with participants between August and September 2024 for review allowing for verification, clarification, and additional input to enhance transparency and data validity.

3.2. Case Study: The City of Constanța

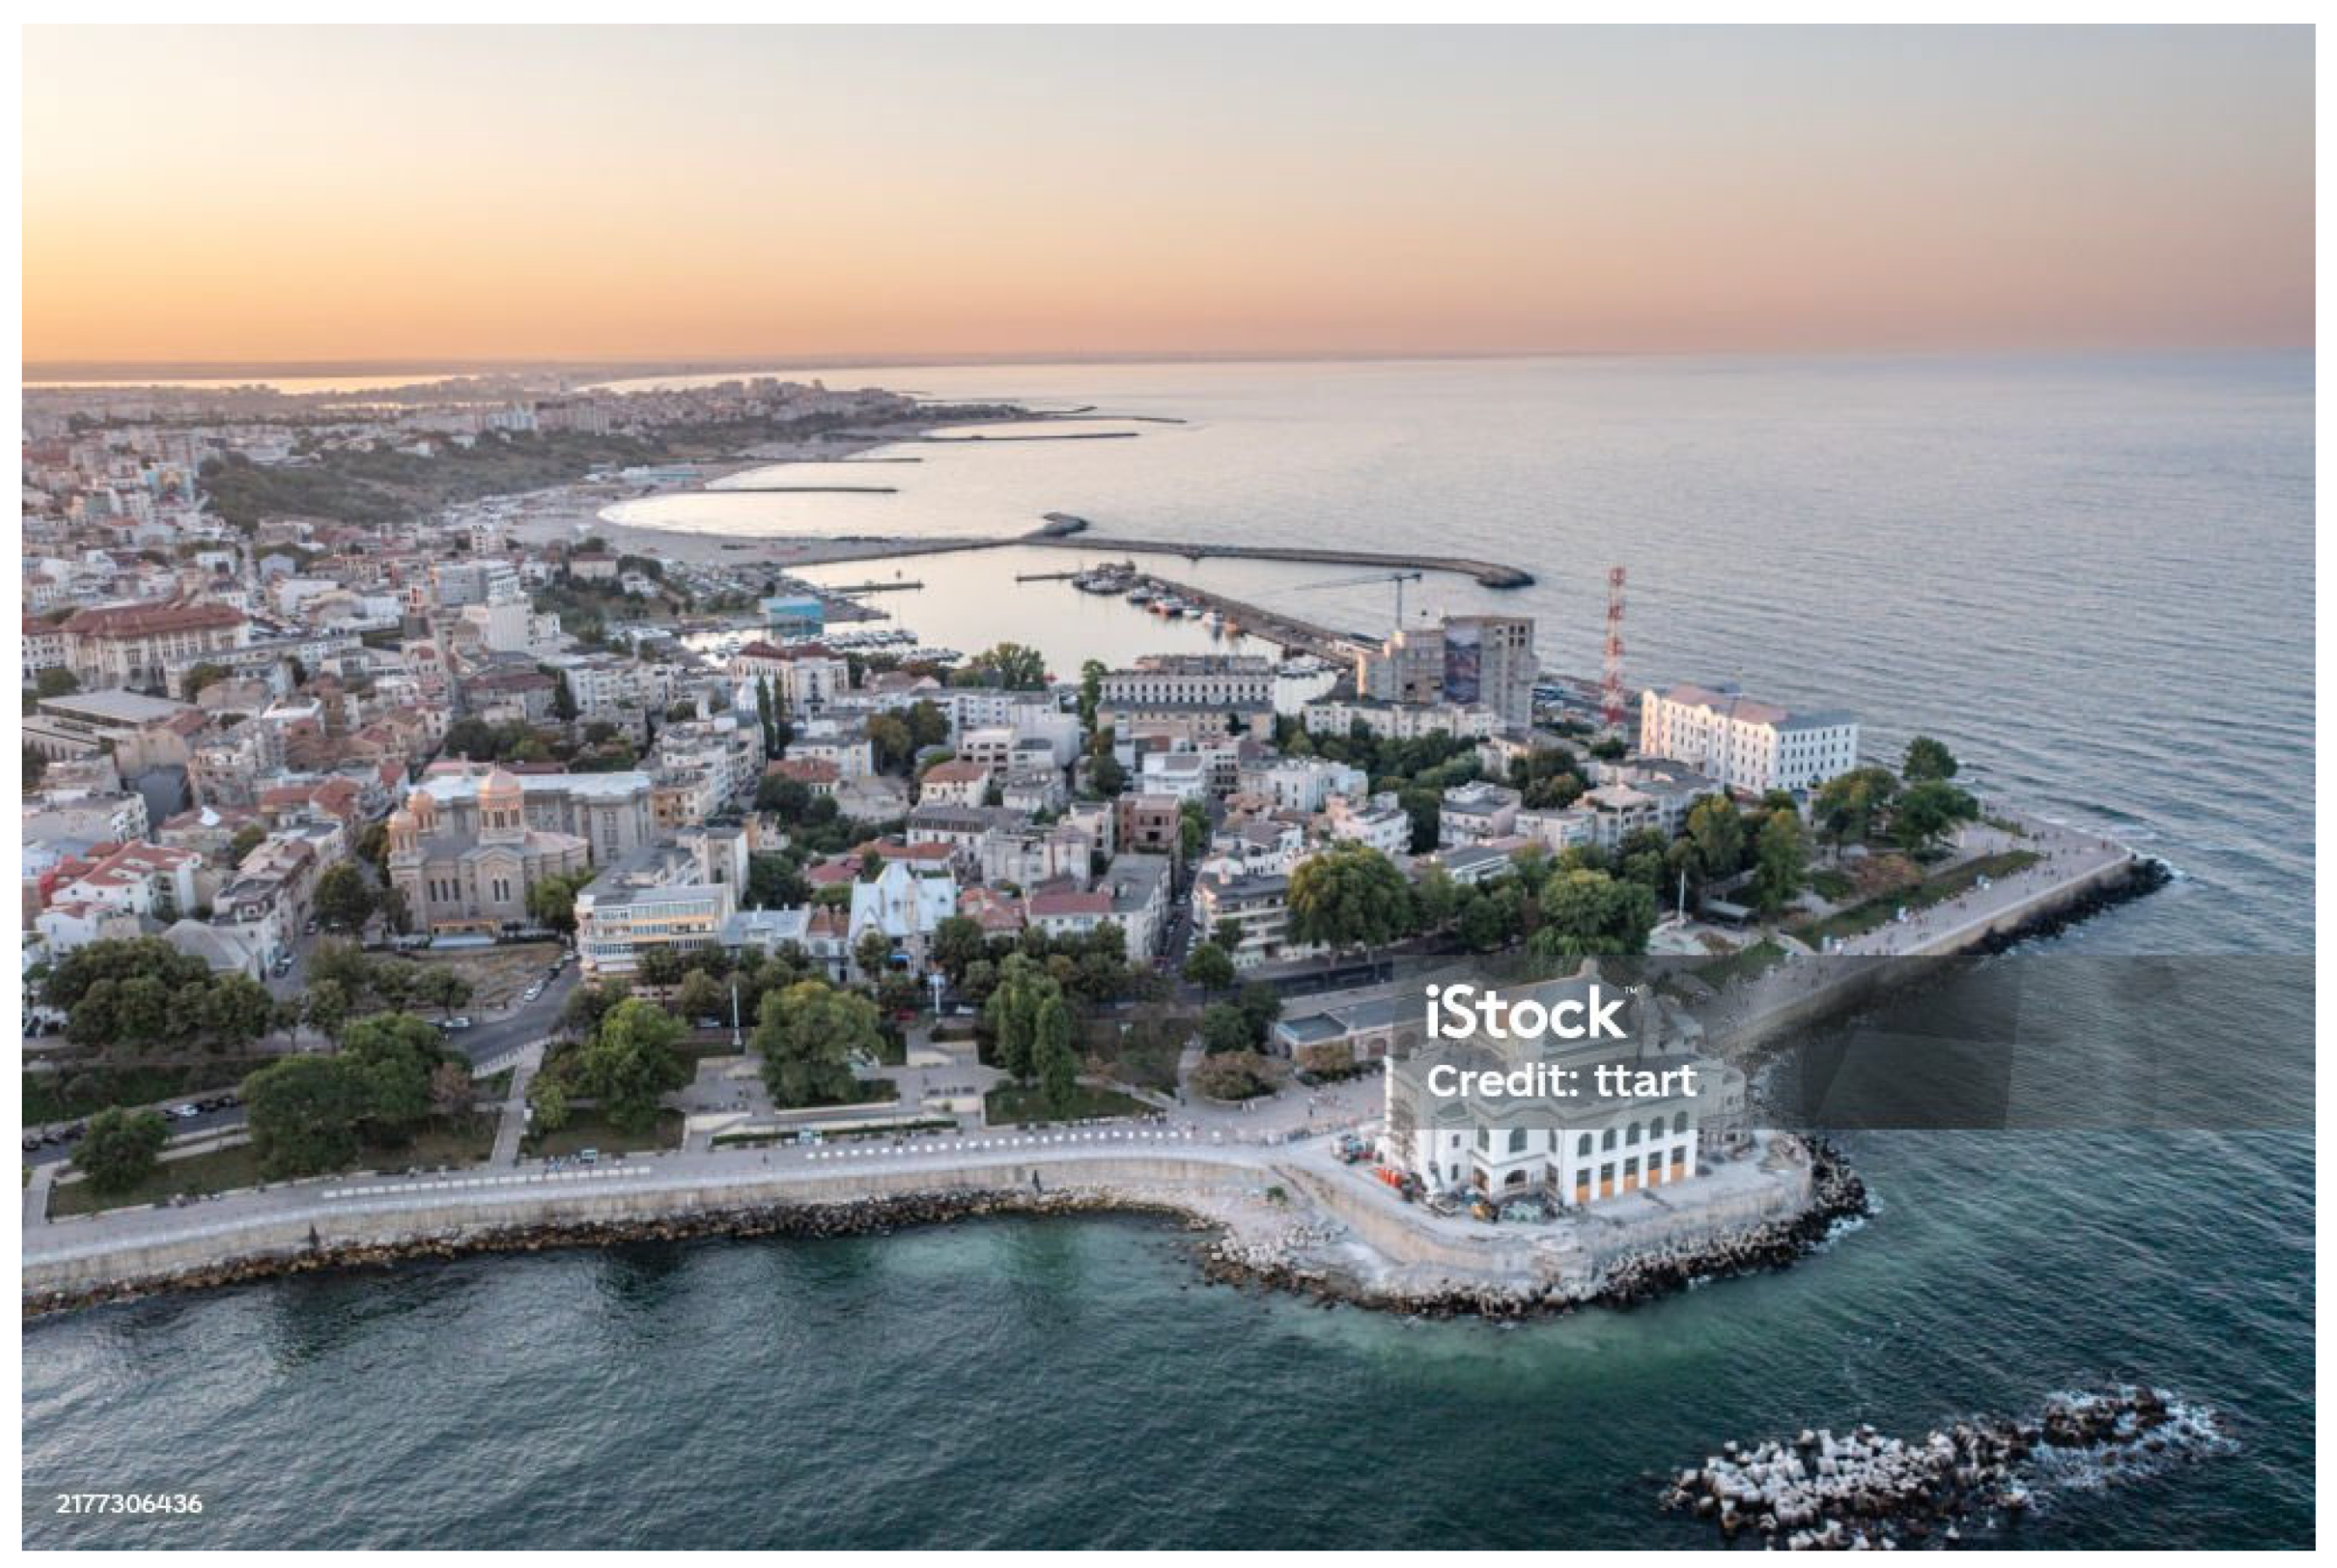
Constanța is a major port city and tourist hub on the Black Sea, as shown in Figure 2. With a population of around 310,000 inhabitants, the city combines historic districts, new residential zones, and growing commercial areas [72]. The real estate market saw a 12.7% increase in residential sales in late 2023, driven by its urban-coastal location and status as Romania’s second most visited city [73]. Infrastructure upgrades, including port modernisation and improved transport connections, have supported real estate investment amid rapid urban growth and the city’s transition towards decarbonisation. Rising coastal climate risks have driven adoption of passive solar design, high-performance insulation, low-emissivity glazing, and low-carbon materials like recycled steel and timber, alongside circular economy practices to boost resilience and reduce impact [14,22].
Despite this growth, real estate development has often focused on short-term returns, while governance challenges contributing to spatial inequality and environmental concerns [60,62]. Efforts to strengthen governance and implement local sustainability frameworks are underway to mitigate these issues and promote more balanced and resilient urban development.

4. Results

This section presents an analysis of empirical data collected through six semi-structured interviews with real estate professionals operating in Constanța’s residential market. The findings are organised around three overarching themes central to understanding ESG adoption in this context: (1) ESG awareness and perceived significance, (2) drivers influencing ESG adoption and emerging market dynamics, and (3) barriers to effective ESG engagement. These themes reveal the sector’s current stance on ESG, highlighting both progress and persistent challenges in a transitional economy.

4.1. ESG Awareness and Perceived Significance

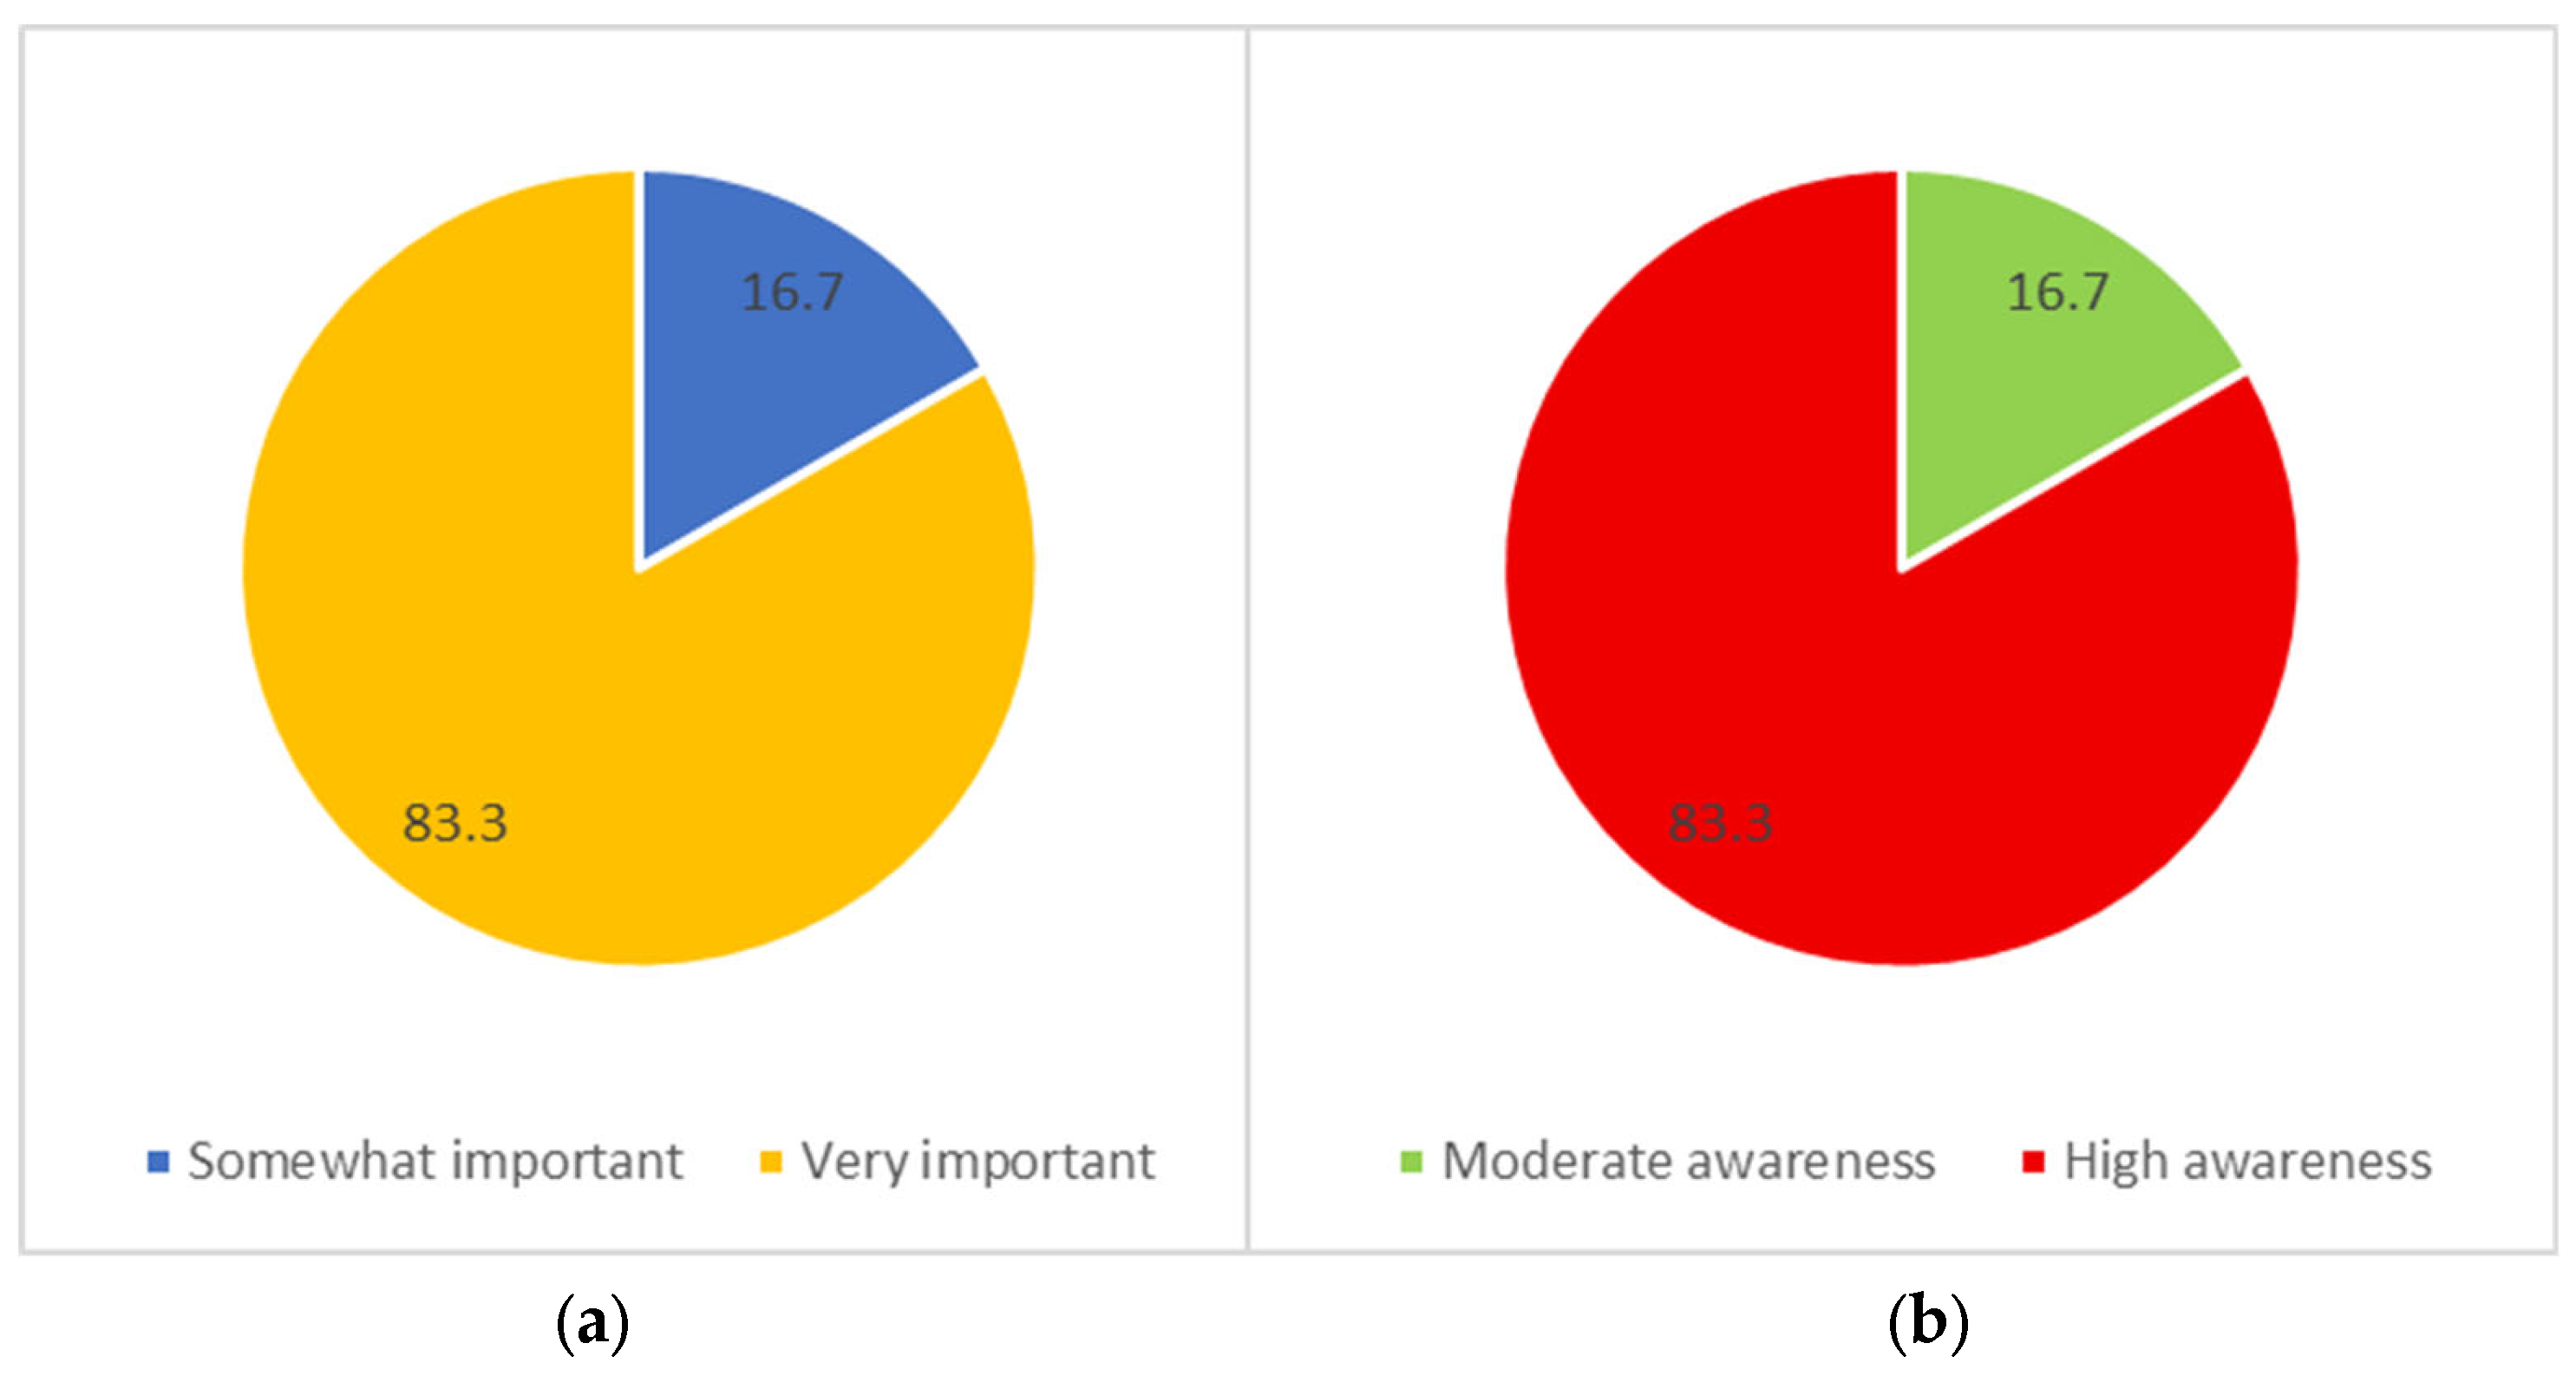
The data indicate a notable increase in ESG awareness among estate agents, developers, and homebuyers in Constanța. Half of the interviewees rated their familiarity with ESG at 100%, and over 80% scored 8 or above on a 10-point scale, showing strong understanding. Respondents consistently emphasised the growing importance of ESG, with 83.3% describing ESG indicators as “very important” to their operations and decision-making, and the remainder considered them “likely important.” This suggests ESG is becoming a core strategic consideration (Figure 3a). A clear hierarchy emerged in how ESG pillars are prioritised. Environmental sustainability dominates current initiatives, with developers actively incorporating energy-efficient technologies, sustainable building materials, and green certifications into their projects. However, social and governance aspects lag behind; as one participant (IP5) noted, “While we have clear environmental targets, social inclusion and employee welfare are not systematically tracked or prioritised”. Another interviewee (IP1) remarked “Environmental sustainability is well understood, but social equity and governance structures are yet to be fully integrated into our local frameworks”. Social considerations, such as community impact, affordable housing, and occupant wellbeing, are rarely embedded into development strategies. A real estate agent (IP4) noted, “Romanian buyers are mostly concerned with energy bills and comfort but less so with wider ESG issues. Until this changes, there is little incentive for developers to invest beyond environmental basics”. This limited consumer demand for social criteria weakens the business case for developers to expand ESG integration beyond environmental measures.
Regarding governance, challenges around transparency and accountability were recurrent themes. A project manager (IP3) commented, “We lack standardised governance frameworks and struggle with clear reporting lines on sustainability issues”. One real estate agent (IP4) added, “Ethical procurement and anti-corruption measures are not yet standard practice here, despite being critical for investor confidence”. This is particularly significant in the Romanian context, where informal practices and corruption risks persist in the real estate sector, compounding governance weaknesses. Interviewees pointed to opaque decision-making processes and informal networks that can undermine regulatory compliance and distort market fairness. As one participant (IP5) reflected, “There is an unspoken tolerance for informal deals and shortcuts, which makes implementing formal governance mechanisms difficult”. These entrenched informal practices not only reduce transparency but also increase the risk of unethical behaviour and diminish trust among investors and consumers. Such conditions pose a substantial barrier to effective ESG governance and highlight the need for stronger institutional reforms and anti-corruption enforcement to complement sustainability initiatives.
Furthermore, governance challenges can weaken the sector’s capacity to adequately prepare for and respond to climate-related risks, which are especially pressing in Constanța given its coastal location. All interviewees acknowledged growing awareness of hazards such as flooding and heatwaves; however, without transparent governance and robust enforcement, integrating these climate considerations into development decisions remains inconsistent and vulnerable to short-term interests. Strengthening governance frameworks is therefore essential not only for ethical compliance but also for building resilience against escalating climate impacts.
EU policies and regulatory instruments were repeatedly cited as shaping attitudes and practices. Respondents pointed to incentives, access to funding, and broader alignment with European sustainability goals as key motivators for ESG adoption. Still, many acknowledged that implementation remains in early stages, with firms gradually adjusting their strategies to keep pace with evolving expectations. In this emerging market setting, the interaction between policy, organisational capacity, and investor behaviour continues to define ESG uptake.
Homebuyer awareness primarily focuses on environmental aspects. Figure 3b illustrates that 83.3% of respondents believe prospective buyers are highly aware of ESG issues, with the same proportion stating that buyers are “very likely” to invest in ESG-compliant homes. None reported low awareness, highlighting strong consumer demand for sustainable housing. One interviewee (IP2) observed, “Today’s buyers, especially younger demographics, are increasingly asking about energy efficiency and environmental standards.”, prompting developers to prioritise ESG features to stay competitive.

4.2. Drivers of ESG Adoption and Emerging Market Dynamics

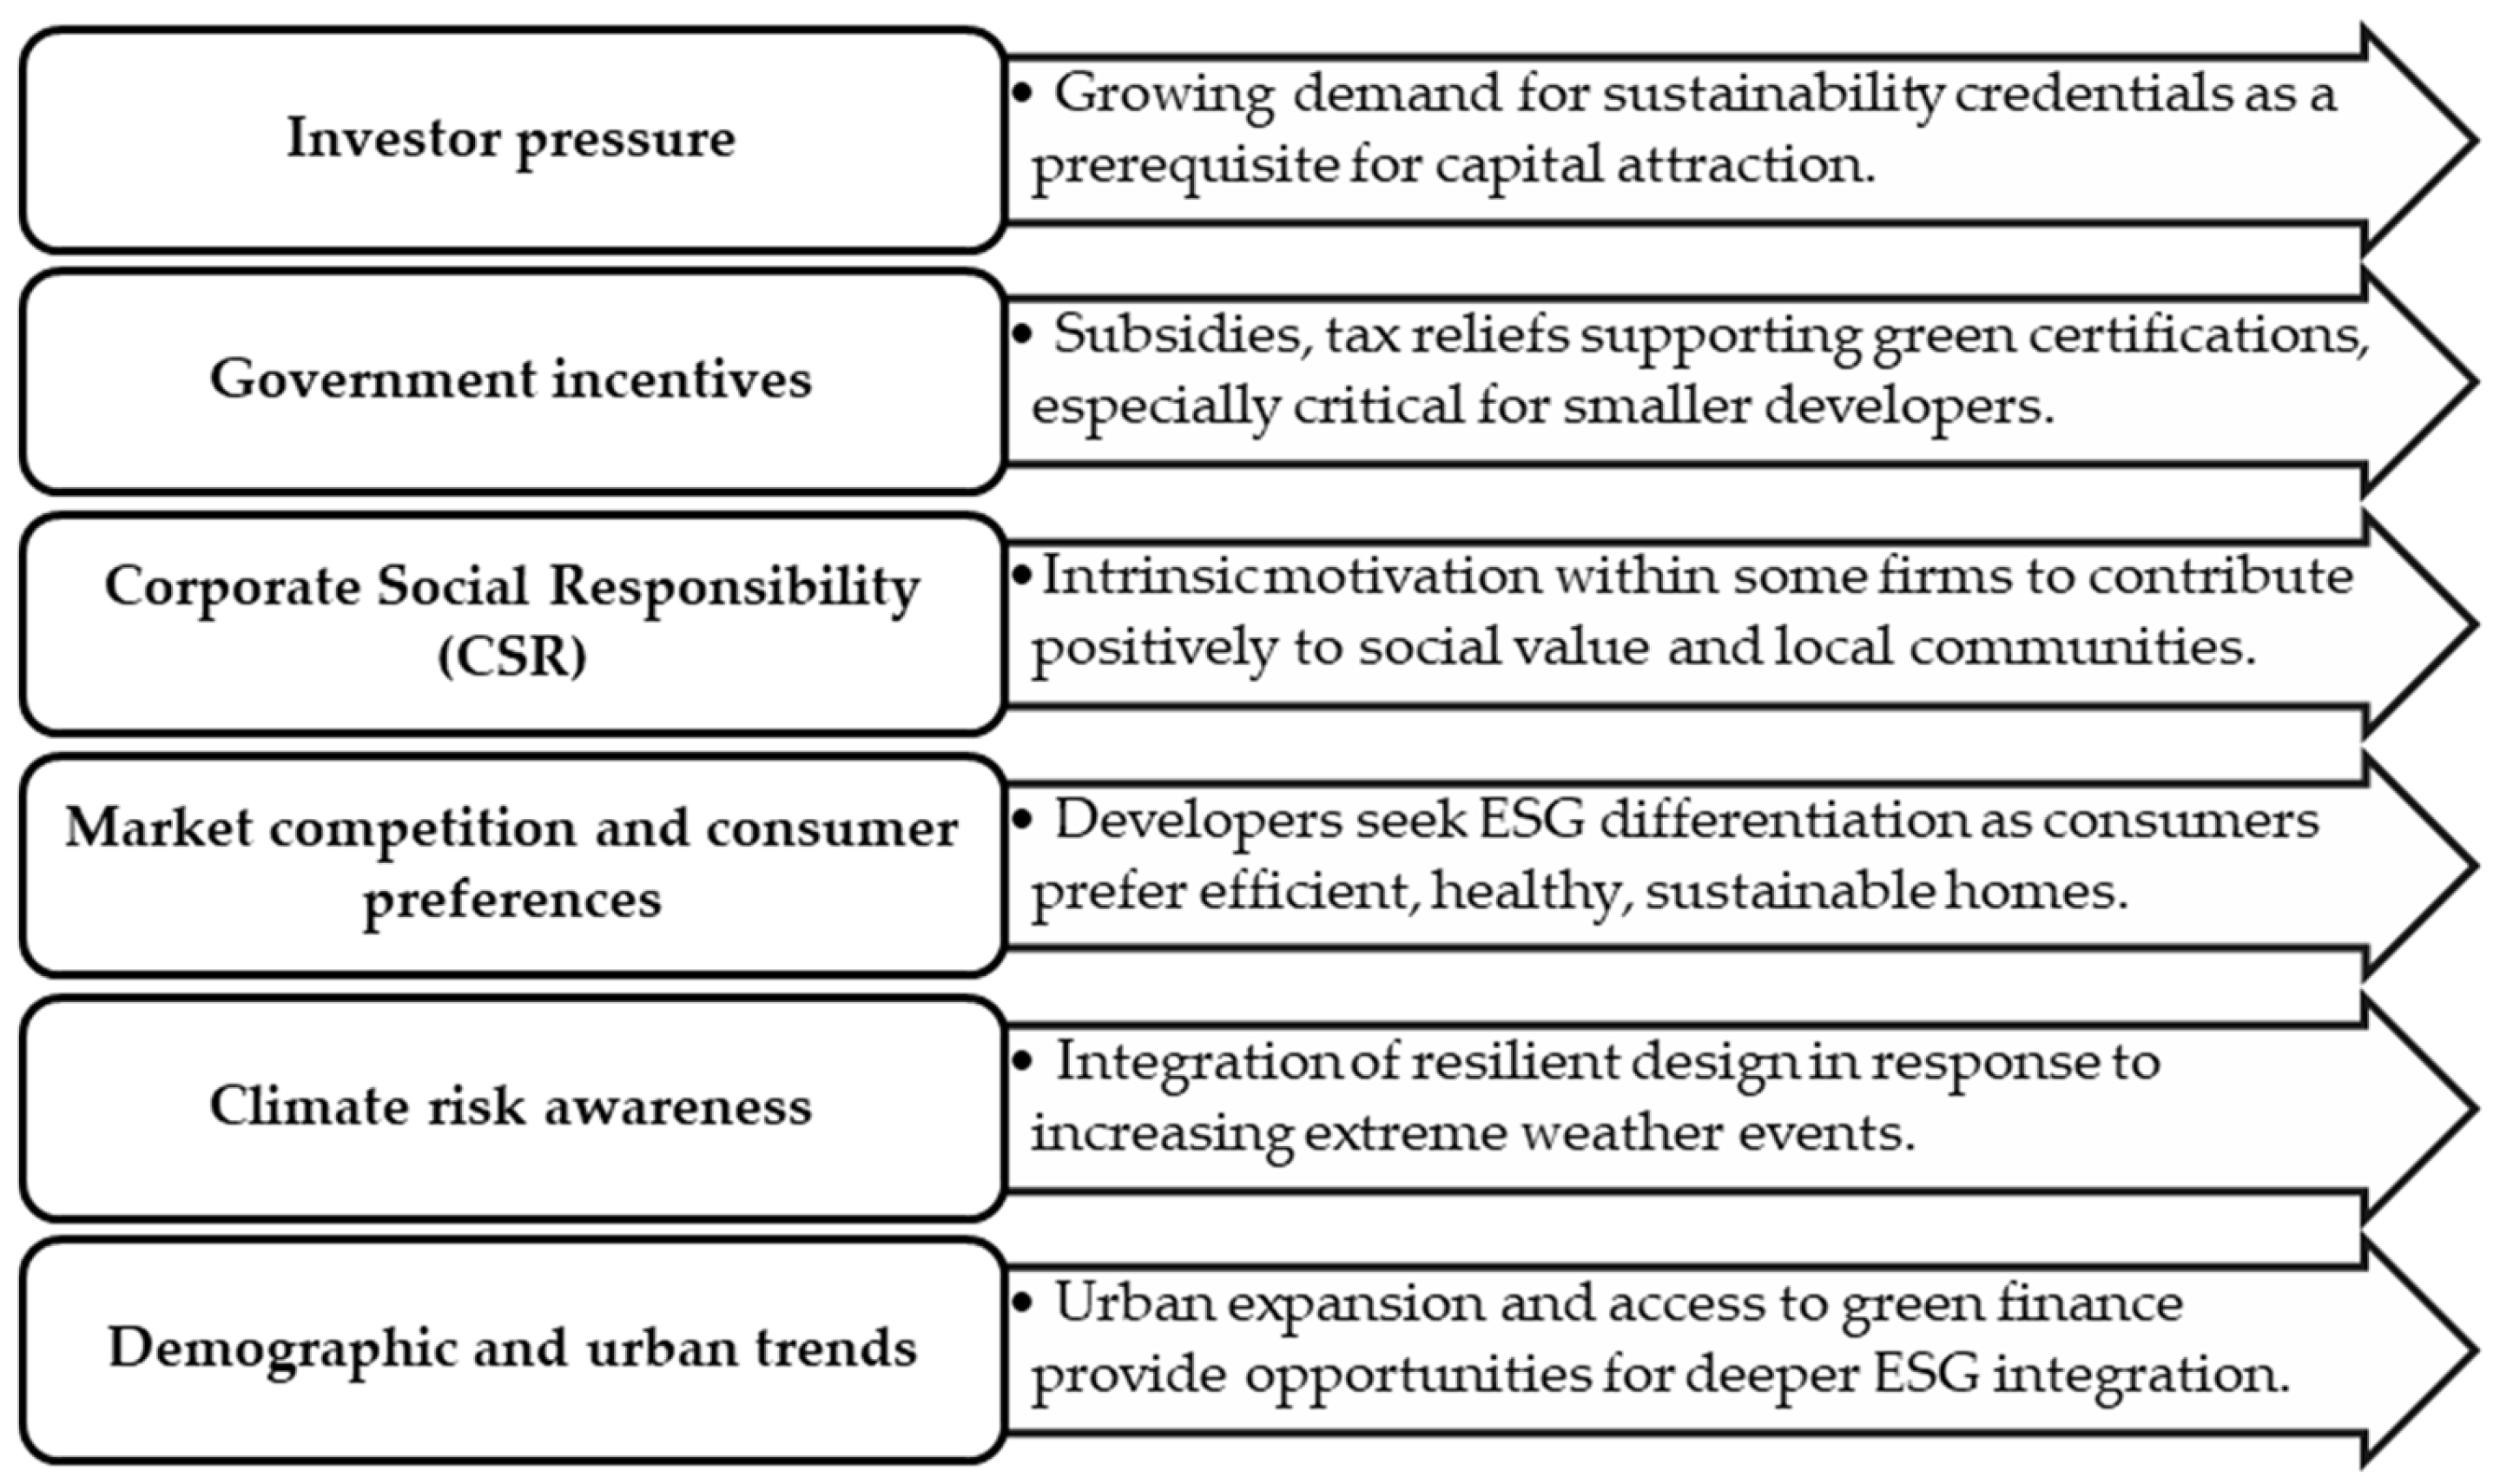
ESG adoption in Constanța’s residential market is shaped by a combination of investor pressure, policy incentives, competitive positioning, and emerging cultural shifts within firms. Interviewees identified investor expectations as a significant driver of change. One project manager (IP3) stated, “In Constanța and across Romania, investors are beginning to look beyond traditional factors like price and location. Sustainability credentials are becoming a prerequisite for attracting capital, or investors will simply direct funds elsewhere”. Interviewees emphasised that these investor demands are increasingly prompting firms to improve governance standards, with one noting, “Investors now expect transparent governance practices alongside environmental certifications(IP2). Government incentives, particularly subsidies for green certifications and tax reliefs, were highlighted as critical enablers. For developers with limited financial margins, these supports often determine whether ESG measures are viable. As another respondent (IP6) explained, “For smaller developers operating with limited margins, these incentives are vital—they turn sustainable projects from an unaffordable expense into a feasible opportunity”. However, interviewees also indicated that these incentives mainly target environmental upgrades, with fewer programmes supporting social or governance improvements.
Some organisations reported being driven by intrinsic CSR values rather than external pressures. One respondent (IP1) explained, “Sustainability forms part of our corporate ethos. We feel a responsibility not just to deliver returns but to contribute positively to our communities”. This internal motivation encourages early adoption of social and governance considerations, although such instances remain limited. However, this commitment is not universal. Resistance to change persists as a significant barrier. One project manager noted, “Convincing teams to abandon established building practices remains challenging, particularly when the financial benefits of ESG investments are neither immediate nor guaranteed”. Market competition and shifting consumer preferences are further encouraging developers to differentiate through ESG credentials, mainly environmental but with emerging attention to social wellbeing and governance transparency. A local agent (IP5) emphasised this point: “Developers who fail to meet these expectations risk losing market share”. Consumer preferences are shifting towards homes that offer not only efficiency but healthier environments and lower environmental impact, which reinforces the importance of sustainable practices. Increasing climate-related extreme weather events are driving residential developers to integrate resilient design measures, such as flood mitigation and improved thermal performance, to enhance building durability and reduce lifecycle costs (IP1, IP2, IP3).
Participants expressed cautious optimism that demographic trends, urban expansion, and access to green finance may accelerate ESG uptake. These conditions offer opportunities to embed ESG more deeply within development practices, provided there is alignment between public policy and market needs. A summary table of key enablers based on the interview analysis is presented in Figure 4.

4.3. Barriers to ESG Engagement

Despite positive trends, several barriers continue to constrain ESG implementation. The most frequently mentioned challenge is the high upfront cost of sustainable construction. Developers often find it difficult to balance long-term sustainability with short-term financial constraints. One project manager (IP2) explained, “For many developers, especially smaller firms, the additional costs associated with green materials and certification processes are difficult to justify within tight profit margins”. These financial constraints limit the willingness to invest beyond essential environmental measures.
Governance challenges emerge as significant barriers to effective ESG integration. Interviewees cited regulatory complexity and inconsistent enforcement as key impediments. As one project manager (IP3) explained, “The bureaucracy around ESG compliance is inconsistent and time-consuming. The lack of clear, uniform regulations creates uncertainty, making firms hesitant to invest heavily in sustainability initiatives”.
Beyond formal regulatory obstacles, participants highlighted the persistence of informal practices and corruption risks, well-documented issues within Romania’s real estate market. Such practices, including unofficial payments, preferential treatment, and opaque contracting processes, undermine fair competition and compromise sustainability commitments. As noted by a respondent (IP4), “Corruption and informal dealings are still widespread; this creates a shadow system where ESG governance is often sidelined or manipulated”. These informal dynamics significantly erode the integrity of sustainability reporting and governance frameworks, thereby complicating efforts to enhance transparency and accountability.
Internal organisational factors further constrain progress. Limited ESG expertise and inadequate data management systems hinder companies’ abilities to monitor performance and transparently report to investors and buyers. As interviewee (IP3) reflected, “Without reliable ESG data and reporting mechanisms, companies struggle to monitor progress and demonstrate transparency to investors and buyers”. These internal challenges are compounded by the broader governance environment, where corruption risks and informal norms diminish incentives for full ESG compliance.
Despite these challenges, there is cautious optimism for change. Interviewees expressed a willingness to expand ESG efforts, contingent on enhanced financial incentives and clearer regulatory guidance. As a Head of Development (IP1) concluded, “We have yet to fully embrace ESG, but growing market and policy pressures in Romania make it clear that change is inevitable and necessary”. Future progress will depend on improved regulatory clarity, stronger financial support mechanisms, and strengthened organisational capacity.

5. Discussion

Over the past decade, ESG integration within Constanța’s residential real estate sector has mirrored broader European trends but remains weighted towards environmental sustainability, largely driven by EU frameworks such as the CSRD, EPBD, and EU Taxonomy, which prioritise energy efficiency and decarbonisation [10,11,12,27,29,30,31,32,33]. Developers respond to investor demand and shifting consumer preferences by incorporating energy-saving technologies and sustainable materials, encouraged by disclosure frameworks such as GRESB and the increasing integration of ESG criteria in real estate investment decision-making [7,18,19,26,28,34,35,36,37,57]. However, social and governance dimensions receive comparatively limited attention, indicating a constricted interpretation of ESG that prioritises measurable environmental factors over sustainability concerns [17,28,40,41,42,43,44,45,46,47,48,49,50].
The limited integration of social value within ESG practices constitutes a significant deficiency in the sector. Social aspects such as affordability, community wellbeing, and inclusivity remain underrepresented, reflecting broader challenges noted in the literature concerning the absence of standardised metrics and integration within ESG frameworks [17,28,40,41,42,43,44,45,46,47,48,49,50]. This deficit undermines the capacity of ESG to address equity and resilience comprehensively. Although frameworks like the CSRD aim to broaden disclosure requirements, their practical implementation in transitional markets remains nascent and inconsistent, with few mechanisms adequately addressing social value and community inclusion. This phenomenon can be understood through the lens of institutional voids, where the absence or weakness of formal institutions and standardised mechanisms impedes the operationalisation of social ESG criteria [23]. Embedding inclusive social criteria alongside environmental targets is essential for constructing ESG approaches that truly reflect the needs of diverse stakeholders, including vulnerable groups [43,51,52,53,54,55,56,57,58].
Governance practices in transitional economies like Romania predominantly focus on financial transparency and regulatory compliance, often reacting to regulations rather than demonstrating proactive corporate responsibility. This reactive approach limits the transformative potential of ESG initiatives [7,11,26,43,51,52,53,54,55,56,57,58]. Such governance fragmentation, characterised by overlapping responsibilities, weak enforcement, and informal parallel systems, exacerbates these challenges by creating inconsistencies and inefficiencies in ESG implementation [7,23,26]. Frameworks such as the CSRD could strengthen governance by mandating transparency and stakeholder engagement, but their effectiveness depends heavily on local institutional capacity and enforcement [69,70]. Moreover, informal practices and corruption, including unofficial payments and opaque contracting, undermine fair competition and weaken ESG governance by creating a shadow system that compromises sustainability commitments and transparency. This dynamic exemplifies policy-practice decoupling, where formal governance frameworks exist but are undermined in practice by entrenched informal behaviours and limited enforcement capacity.
Financial constraints and regulatory complexity present substantial barriers to more comprehensive ESG engagement. High upfront costs associated with sustainable construction and certification, coupled with unclear and inconsistent regulatory frameworks, restrict the capacity and willingness of developers, especially smaller firms, to adopt integrated ESG strategies [22,61]. These findings corroborate documented challenges in comparable transitional markets, where ‘green premiums’ and bureaucratic obstacles reduce innovation [15,59]. Moreover, voluntary benchmarking tools like GRESB, widely used by institutional investors, depend on self-reported data and often lack sensitivity to local governance and socio-political contexts, limiting their utility in emerging markets [7,57]. Consequently, targeted financial incentives and clearer, context-sensitive regulations are essential to facilitate broader ESG adoption and bridge the gap between ambition and practice [15,36,39,59]. The key barriers to ESG adoption in Constanța’s residential real estate sector, summarised in Table 3, reflect broader systemic challenges typical of transitional economies, including institutional voids, governance fragmentation, and policy-practice decoupling.
Internal organisational factors, including limited expertise, cultural resistance, and inadequate ESG data management systems, further constrain progress. The sector’s cautious stance reflects entrenched traditional practices and risk aversion, suggesting that ESG adoption represents as much a cultural challenge as a technical one [7,26,43,51,58]. Enhancing organisational capacity through professional training and improved data transparency is imperative to transition from aspirational commitments to credible, operational ESG integration. Effective ESG integration in Constanța’s residential market requires coordinated action among developers, regulators, financial institutions, and community stakeholders. The findings demonstrate that no single actor can surmount the financial, regulatory, and cultural barriers independently. Instead, aligning incentives and establishing clear, context-specific policies are essential to build trust and foster momentum for change. This governance challenge underscores the necessity to address institutional voids and fragmented governance through collaborative stakeholder engagement and enhanced institutional capacity [23,26]. These findings resonate with broader research emphasising that ESG adoption is not merely a technical task but a complex governance process demanding cooperation across actors [7,26,43,51,58]. As ESG transitions from voluntary practice to regulatory obligation under EU frameworks such as the CSRD and EU Taxonomy, aligning market participants and public policy will be critical to achieving meaningful and sustainable development in transitional economies [11,26,39].

6. Conclusions and Recommendations

This study positions Constanța’s residential real estate sector within the wider debates on ESG adoption in transitional economies, where the prioritisation of environmental factors can deepen both global and local sustainability inequalities. Strong ESG performance has the potential to raise property values, attract investment, and reduce climate-related risks. However, the emphasis on environmental metrics, often shaped by frameworks originating in mature economies, may fail to address the socio-economic and governance realities of emerging markets. In Romania, this imbalance can marginalise the social and governance dimensions that are equally important for long-term resilience and equitable development.
To enable effective ESG integration, developers and housing professionals should incorporate these principles into project planning from the outset, safeguarding asset value, resilience, and market competitiveness. Strengthening sector expertise through targeted training is vital for consistent application across design, construction, and asset management. Expanding access to green finance, including grants, subsidised loans, and fiscal incentives, can help offset the high upfront costs of sustainable technologies, energy-efficient materials, and environmentally responsible construction methods.
Clear and enforceable ESG standards, tailored to the residential sector and aligned with regulatory requirements and investor expectations, are essential to drive adoption. Policymakers, including the Romanian Ministry of Environment, Water and Forests, local authorities, and EU institutions, should complement these standards with financial incentives and detailed technical guidance. Alignment with Romania’s National Sustainable Development Strategy and the European Green Deal will improve policy coherence and delivery. Targeted support for small and medium-sized developers, combined with a focus on social inclusion, will help ensure that ESG practices promote affordable, equitable, and sustainable urban housing.
The Constanța case also reflects wider structural challenges. Institutional voids limit effective governance, and gaps between policy and practice mean that formal ESG commitments are often not implemented locally. Weak institutional capacity, informal governance practices, and limited stakeholder engagement threaten the sector’s long-term stability. Environmental gains alone cannot guarantee community wellbeing or socio-economic resilience without parallel reforms in governance and social equity.
A holistic and context-sensitive ESG approach that integrates environmental goals with social equity and governance reform is essential for building resilient and inclusive urban environments. Without this balance, initiatives risk producing short-term results that deepen inequalities and undermine resilience.
Evidence from earlier econometric research in Romania, although not focused specifically on ESG or residential real estate, shows that consumer benefits from sustainable process efficiencies depend on both measurable factors and subjective psychological and rational considerations [75]. Understanding consumer preferences, motivations, and behavioural drivers is therefore central to designing ESG strategies that engage end-users and stimulate demand for sustainable housing. Incorporating these consumer dimensions into future research will improve the alignment between ESG objectives and market realities.
Based on the findings of this study, the following key recommendations are proposed:
  • Develop ESG assessment tools tailored to Constanța’s urban growth, socio-economic conditions, and climate risks. These tools should guide sustainable investment and support local policy and planning decisions.
  • Expand empirical research beyond Constanța to other Romanian cities and the wider Balkan and Eastern European region. Involving a broad range of stakeholders such as developers, investors, regulators, housing associations, and residents will help identify barriers and drivers and enable more effective and relevant policy responses.
  • Build professional capacity by providing ESG training and encouraging knowledge sharing among real estate professionals. Cooperation between developers, investors, researchers, and policymakers should be promoted to foster practical and locally relevant solutions.
  • Improve access to green finance with targeted incentives including subsidised loans, grants, and tax relief. Clear and consistent regulatory guidance aligned with national and European strategies is essential to reduce financial barriers and support ESG implementation.
  • Increase transparency and accountability by requiring mandatory ESG disclosure for residential projects. This will build market trust, improve competitiveness, and encourage consistent ESG reporting.
  • Ensure social inclusion is a key part of ESG frameworks to keep sustainable housing affordable and promote fair urban development. Policies must address the needs of all social groups to build resilient and cohesive communities.
  • Adapt ESG frameworks for transitional economies by shifting from compliance-only approaches to inclusive and flexible governance models. ESG strategies should aim to reduce inequalities and support long-term resilience in residential real estate.
  • Recognise and address informal practices and corruption risks that affect governance in Romania’s real estate market. Strengthening institutional integrity and promoting transparency are crucial for effective ESG adoption and creating a fair and sustainable market.
While the qualitative case study approach, based on six in-depth interviews, provides valuable insights into ESG dynamics in Constanța’s residential real estate sector, the limited sample size constrains the extent to which these findings can be generalised to the wider Romanian market or other transitional economies. The results should therefore be interpreted as indicative rather than representative of national or regional trends. To strengthen external validity, future research should employ larger and more diverse samples, incorporating stakeholders from multiple cities, regions, and types of residential developments. Comparative case studies across Romania and other emerging markets in Eastern and South-Eastern Europe would enable cross-contextual analysis, helping to identify recurring barriers and transferable best practices in ESG implementation. Longitudinal studies tracking ESG adoption over time would also provide evidence on how evolving policies, regulatory frameworks, and market conditions influence both environmental and socio-economic outcomes. In addition, further investigation is needed to assess how ESG-aligned housing contributes to social objectives such as affordability, community resilience, and inclusive urban regeneration. These expanded research efforts are essential for strengthening the theoretical and practical connections between ESG integration and the UN SDGs in the residential real estate sector. By broadening the evidence base, future studies can offer more robust, scalable, and context-sensitive recommendations to policymakers, developers, and other stakeholders, thereby supporting sustainable development strategies tailored to transitional economies.

Author Contributions

Conceptualization, M.C.G. and M.L.I.; Formal-analysis, M.C.G. and M.L.I.; Investigation, M.L.I.; Methodology, M.C.G. and M.L.I.; Project administration, M.L.I.; Supervision, M.C.G.; Validation, M.L.I.; Writing—original draft, M.C.G. and M.L.I.; Writing—review and editing, M.C.G. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Institutional Review Board Statement

According to London Metropolitan University’s Research Ethics Policy and Procedures and Code of Good Research Practice (http://www.londonmet.ac.uk/research/current-students/research-ethics/, accessed on 21 May 2024), all Master of Science students must complete an ethics form to complete their Master of Science dissertations, without the need to submit a formal Research Ethics Review Panel (RERP) review.

Informed Consent Statement

Informed consent for participation was obtained from all subjects involved in the study.

Data Availability Statement

The original contribution presented in this study are included in the article, further inquiries can be directed to the corresponding author.

Conflicts of Interest

The authors declare no conflicts of interest.

Abbreviations

The following abbreviations are used in this manuscript:
AOPBusiness Association (translated from Romanian)
BREEAMBuilding Research Establishment Environmental Assessment Method
CDPCarbon Disclosure Project
CESBA MEDCommon European Sustainable Building Assessment Mediterranean
CRFCorporate Reporting Frameworks
CSRCorporate Social Responsibility
DGNBGerman Sustainable Building Council
EPRAEuropean Public Real Estate Association
ESGEconomic, Social and Governance
EUEuropean Union
IPInterview Participant
GHG ProtocolGreenhouse Gas Protocol
GRESBGlobal Real Estate Sustainability Benchmark
GRIGlobal Reporting Initiative
HQEHigh Quality Environmental
LEEDLeadership in Energy and Environmental Design
REITReal Estate Investment Trust
sBPRSustainability Best Practices Recommendations
SDGsSustainable Development Goals
SFDRSustainable Finance Disclosure Regulation
SROISocial Return on Investment
SRLLimited Liability Company (translated from Romanian)
TMFTailored Market Frameworks
UNUnited Nations

References

  1. UNFCCC. The Paris Agreement. Available online: https://unfccc.int/process-and-meetings/the-paris-agreement (accessed on 24 June 2025).
  2. United Nations. Transforming Our World: The 2030 Agenda for Sustainable Development. Available online: https://sdgs.un.org/2030agenda (accessed on 24 June 2025).
  3. United Nations Global Compact. About the UN Global Compact. Available online: https://www.unglobalcompact.org/what-is-gc (accessed on 24 June 2025).
  4. Principles for Responsible Investment. About PRI. Available online: https://www.unpri.org/about-us/about-the-pri (accessed on 24 June 2025).
  5. Sustainable Stock Exchanges Initiative. Overview. Available online: https://sseinitiative.org/ (accessed on 24 June 2025).
  6. Eccles, R.G.; Ioannou, I.; Serafeim, G. The Impact of Corporate Sustainability on Organizational Processes and Performance. Manage. Sci. 2014, 60, 2835–2857. [Google Scholar] [CrossRef] [Scilit]
  7. Newell, G.; Nanda, A.; Moss, A. Improving the Benchmarking of ESG in Real Estate Investment. J. Prop. Invest. Financ. 2023, 41, 380–405. [Google Scholar] [CrossRef] [Scilit]
  8. Deloitte. ESG and Real Estate: The Journey Continues. Available online: https://www.deloitte.com/ce/en/Industries/real-estate/research/esg-real-estate-insights-20210.html (accessed on 6 July 2025).
  9. JLL. Sustainability Remains a Key Driver for European Real Estate Investors. Available online: https://www.jll.com/en-uk/insights/sustainability-remains-a-key-driver-for-european-real-estate-investors (accessed on 6 July 2025).
  10. European Commission. The European Green Deal. Available online: https://eur-lex.europa.eu/resource.html?uri=cellar:b828d165-1c22-11ea-8c1f-01aa75ed71a1.0002.02/DOC_1&format=PDF (accessed on 6 July 2025).
  11. European Commission. Proposal for a Directive of the European Parliament and of the Council on Corporate Sustainability Reporting (COM/2021/189 Final). Available online: https://eur-lex.europa.eu/legal-content/EN/TXT/PDF/?uri=CELEX:52021PC0189 (accessed on 6 July 2025).
  12. European Parliament and Council. Regulation (EU) 2019/2088 of 27 November 2019 on Sustainability-Related Disclosures in the Financial Services Sector. Official Journal of the EU, L_2019/317. Available online: https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX%3A32019R2088 (accessed on 6 July 2025).
  13. Tiron-Tudor, A.; Nistor, C.S.; Ştefănescu, C.A.; Zanellato, G. Encompassing Non-Financial Reporting in a Coercitive Framework for Enhancing Social Responsibility: Romanian Listed Companies’ Case. Amfiteatru Econ. 2019, 21, 52. [Google Scholar] [CrossRef] [Scilit]
  14. Vrabie, A.; Ianole-Calin, R. Regulating the Urban Commons: A Romanian Case Study of Improving Building Facades. Cent. Eur. Pub. Admin. Rev. 2020, 18, 183–202. [Google Scholar] [CrossRef] [Scilit]
  15. Balaras, C.A.; Droutsa, K.G.; Dascalaki, E.G.; Kontoyiannidis, S.; Moro, A.; Bazzan, E. Urban Sustainability Audits and Ratings of the Built Environment. Energies 2019, 12, 4243. [Google Scholar] [CrossRef] [Scilit]
  16. European Central Bank. Real Estate Markets in an Environment of High Financing Costs. ECB Financial Stability Review. 2023. Available online: https://www.ecb.europa.eu/press/financial-stability-publications/fsr/special/html/ecb.fsrart202311_02~75cf0710b9.en.html (accessed on 18 July 2025).
  17. PwC; Urban Land Institute. Emerging Trends in Real Estate® Europe 2024; PwC and the Urban Land Institute: London, UK, 2023; Available online: https://www.pwc.com/gx/en/asset-management/emerging-trends-real-estate/assets/emerging-trends-in-real-estate-europe-2024.pdf (accessed on 7 July 2025).
  18. Copiello, S.; Coletto, S. The price premium in green buildings: A spatial autoregressive model and a multi-criteria optimization approach. Buildings 2023, 13, 276. [Google Scholar] [CrossRef] [Scilit]
  19. Ionașcu, E.; Mironiuc, M.; Anghel, I.; Huian, M.C. The involvement of real estate companies in sustainable development—An analysis from the SDGs reporting perspective. Sustainability 2020, 12, 798. [Google Scholar] [CrossRef] [Scilit]
  20. PwC Romania. Only 30% of BVB-Listed Companies Have an ESG Strategy. Available online: https://www.pwc.ro/en/press-room/press-releases-2022/pwc-romania-report--only-30--of-bvb-listed-companies-have-an-esg.html (accessed on 6 July 2025).
  21. Olteanu, A.L.; Ionascu, A.E. The Importance of ESG in Real Estate Investments. Ovidius Univ. Ann. Econ. Sci. Ser. 2023, 23, 810–817. [Google Scholar]
  22. González-Vallejo, P.; Muntean, R.; Solís-Guzmán, J.; Marrero, M. Carbon Footprint of Dwelling Construction in Romania and Spain. A Comparative Analysis with the OERCO2 Tool. Sustainability 2020, 12, 6745. [Google Scholar] [CrossRef] [Scilit]
  23. Bucurean, R.-C.; Bucurean, R.-N. ESG Reporting in Romania—A Challenge of Ensuring a Greener Financial System. In Exploring ESG Challenges and Opportunities: Navigating Towards a Better Future; Emerald Publishing Limited: Bingley, UK, 2024; pp. 113–125. [Google Scholar]
  24. OECD. Strengthening Romania’s Integrity and Anti-Corruption Measures; OECD Public Governance Reviews 2023; OECD: Paris, France, 2023; Available online: https://www.oecd.org/content/dam/oecd/en/publications/reports/2023/06/strengthening-romania-s-integrity-and-anti-corruption-measures_f2b3a2fe/ff88cfa4-en.pdf (accessed on 6 July 2025).
  25. Dosanu, M.; Ciobanu, A.; Gheorghe, S. Exploring the Environmental, Social and Governance Measures in Real Estate—The Impact in Energy Management. In Proceedings of the 11th International Conference on ENERGY and ENVIRONMENT (CIEM), Bucharest, Romania, 26–27 October 2023. [Google Scholar]
  26. Newell, G.; Marzuki, M.J. The Increasing Importance of Environmental Sustainability in Global Real Estate Investment Markets. J. Prop. Invest. Financ. 2022, 40, 411–429. [Google Scholar] [CrossRef] [Scilit]
  27. Kitulazzi, D.; Ametefe, F.K.; Karimu, A.; Akinsomi, O. ESG investing and the performance of JSE-listed real estate firms: A system GMM approach. J. Prop. Invest. Financ. 2025, 43, 222–243. [Google Scholar] [CrossRef] [Scilit]
  28. Zairis, G.; Liargovas, P.; Apostolopoulos, N. Sustainable finance and ESG importance: A systematic literature review and research agenda. Sustainability 2024, 16, 2878. [Google Scholar] [CrossRef] [Scilit]
  29. Morri, G.; Colantoni, F.; De Paolis, A.M. ESG performance variability: Profitability and market implications for real estate entities in a worldwide context. J. Eur. Real Estate Res. 2024, 17, 373–394. [Google Scholar] [CrossRef] [Scilit]
  30. European Parliament and Council. Directive (EU) 2024/1275 of 24 April 2024 on the Energy Performance of Buildings (Recast). Official Journal of the EU, L_2024/1275. Available online: https://eur-lex.europa.eu/legal-content/EN/TXT/PDF/?uri=OJ:L_202401275 (accessed on 6 July 2025).
  31. European Commission. Regulation (EU) 2023/0177 on the Transparency and Integrity of Environmental, Social and Governance (ESG) Rating Activities. Official Journal of the European Union. Available online: https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX:52023PC0314 (accessed on 6 July 2025).
  32. RICS. RICS Welcomes the Final Approval of the EPBD; Royal Institution of Chartered Surveyors: London, UK, 2024; Available online: https://www.rics.org/news-insights/rics-welcomes-the-final-approval-of-the-epbd (accessed on 17 July 2025).
  33. BPIE. Delivering the EPBD: A Guide Towards Better, Affordable and More Resilient Buildings for All in Europe; Buildings Performance Institute Europe: Bruxelles, Belgium, 2025; Available online: https://www.bpie.eu/delivering-the-epbd-a-guide-towards-better-affordable-and-more-resilient-buildings-for-all-in-europe/ (accessed on 7 July 2025).
  34. Erol, I.; Unal, U.; Coskun, Y. ESG Investing and the Financial Performance: A Panel Data Analysis of Developed REIT Markets. Environ. Sci. Pollut. Res. 2023, 30, 85154–85169. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  35. Feng, Z.; Wu, Z. ESG Disclosure, REIT Debt Financing and Firm Value. J. Real Estate Financ. Econ. 2023, 67, 388–422. [Google Scholar] [CrossRef] [Scilit]
  36. CBRE Research. Is Sustainability Certification in Real Estate Worth It? Available online: https://www.cbre.es/insights/reports/is-sustainability-certification-in-real-estate-worth-it (accessed on 10 July 2025).
  37. Akin, I.; Akin, M. Promoting sustainable practices through green investments in the United Kingdom real estate industry. Sustain. Dev. 2025, 33, 1526–1544. [Google Scholar] [CrossRef] [Scilit]
  38. Mangialardo, A.; Micelli, E.; Saccani, F. Does sustainability affect real estate market values? Empirical evidence from the office buildings market in Milan (Italy). Sustainability 2019, 11, 12. [Google Scholar] [CrossRef] [Scilit]
  39. Balaras, C.A.; Droutsa, K.G.; Dascalaki, E.G.; Kontoyiannidis, S.; Moro, A.; Bazzan, E.; Borgaro, P. Auditing and Rating Sustainability of Mediterranean Buildings, Neighbourhoods and Cities. Energies 2024, 17, 82. [Google Scholar] [CrossRef] [Scilit]
  40. Battisti, F. SDGs and ESG Criteria in Housing: Defining Local Evaluation Criteria and Indicators for Verifying Project Sustainability Using Florence Metropolitan Area as a Case Study. Sustainability 2023, 15, 9372. [Google Scholar] [CrossRef] [Scilit]
  41. Hernández-Morales, A. Von der Leyen Bets Big on Housing. Politico. Available online: https://www.politico.eu/article/von-der-leyen-bets-big-on-housing-european-commission/ (accessed on 7 July 2025).
  42. Eurostat. Population Projections in the EU. Available online: https://ec.europa.eu/eurostat/statistics-explained/index.php?oldid=497115 (accessed on 7 July 2025).
  43. Savills. Is Social Value the New Real Estate Essential? Savills: London, UK, 2024; Available online: https://impacts.savills.com/social-change/is-social-value-the-new-real-estate-essential.html (accessed on 19 July 2025).
  44. Raiden, A.; King, A. Connecting social value to the United Nations’ Sustainable Development Goals in the built environment. Build. Cities 2022, 2, 769–778. [Google Scholar] [CrossRef] [Scilit]
  45. Mulholland, C.; Georgiadou, M.C.; Fitton, S. Key Challenges in Social Value 2025: Responsible Stakeholder Engagement, Robust Data Management and Reliable Digitalisation; Aurora Engagements Ltd.: Rochdale, UK, 2025; pp. 1–10. [Google Scholar]
  46. Kauko, T. Innovation in urban real estate: The role of sustainability. Prop. Manag. 2019, 37, 197–214. [Google Scholar] [CrossRef] [Scilit]
  47. Brooks, M.; McArthur, J.J. Drivers of investment in commercial real estate sustainability: 2006–2018. J. Sustain. Real Estate 2019, 11, 130–155. [Google Scholar] [CrossRef] [Scilit]
  48. Ghazwani, M. Transforming governance into social value: The critical role of board culture diversity and anti-corruption policies in affecting corporate social performance in G20 countries. Corp. Soc. Responsib. Environ. Manag. 2025, 32, 2964–2987. [Google Scholar] [CrossRef] [Scilit]
  49. Menghwar, P.S.; Daood, A. Creating shared value: A systematic review, synthesis and integrative perspective. Int. J. Manag. Rev. 2021, 23, 466–485. [Google Scholar] [CrossRef] [Scilit]
  50. Fujiwara, D.; Dass, D.; King, E.; Vriend, M.; Houston, R.; Keohane, K. A framework for measuring social value in infrastructure and built environment projects: An industry perspective. Proc. Inst. Civ. Eng. Eng. Sustain. 2022, 175, 175–185. [Google Scholar] [CrossRef] [Scilit]
  51. Robinson, S.; McIntosh, M.G. A literature review of environmental, social, and governance (ESG) in commercial real estate. J. Real Estate Lit. 2022, 30, 54–67. [Google Scholar] [CrossRef] [Scilit]
  52. Ionașcu, E.; Taltavull de La Paz, P.; Mironiuc, M. The Relationship between Housing Prices and Market Transparency. Evidence from the Metropolitan European Markets. Housing Theory Soc. 2019, 38, 42–71. [Google Scholar] [CrossRef] [Scilit]
  53. Brounen, D.; Marcato, G.; Op ’t Veld, H. Pricing ESG Equity Ratings and Underlying Data in Listed Real Estate Securities. Sustainability 2021, 13, 2037. [Google Scholar] [CrossRef] [Scilit]
  54. Keenan, J.M. From Sustainability to Adaptation: Goldman Sachs’ Corporate Real Estate Strategy. Build. Res. Inf. 2016, 44, 407–422. [Google Scholar] [CrossRef] [Scilit]
  55. GRI. 2022 The GRI Standards—Enabling Transparency on Organizational Impacts. Global Reporting Initiative. 2022. Available online: https://www.globalreporting.org/media/wmxlklns/about-gri-brochure-2022.pdf (accessed on 19 July 2025).
  56. EPRA. 2022 EPRA Annual Report Survey—Sustainability Best Practice Recommendations; European Public Real Estate Association: Brussels, Belgium, 2022; Available online: https://www.epra.com/application/files/8016/6506/6469/2022-09-22_09-15_113_3.pdf (accessed on 19 July 2025).
  57. GRESB. 2025 Real Estate Reference Guide; GRESB: Amsterdam, The Netherlands, 2025; Available online: https://documents.gresb.com/generated_files/real_estate/2025/real_estate/reference_guide/complete.html (accessed on 21 July 2025).
  58. Rashidfarokhi, A.; Toiconen, S.; Viitanen, K. Sustainability Reporting in the Nordic Real Estate Companies: Empirical Evidence from Finland. Int. J. Strateg. Prop. Manag. 2018, 22, 51–63. [Google Scholar] [CrossRef] [Scilit]
  59. ICMA. Sustainable Finance High-Level Definitions; ICMA: London, UK, 2020; Available online: https://www.icmagroup.org/assets/documents/Regulatory/Green-Bonds/Sustainable-Finance-High-Level-Definitions-May-2020-051020.pdf (accessed on 19 July 2025).
  60. World Bank. Romania Leverages Climate Financing to Achieve National Priorities; The World Bank: Washington, DC, USA, 2024; Available online: https://blogs.worldbank.org/en/climatechange/romania-leverages-climate-financing-to-achieve-national-prioriti (accessed on 7 July 2025).
  61. Muresan, A.A.; Attia, S. Energy efficiency in the Romanian residential building stock: A literature review. Renew. Sustain. Energy Rev. 2017, 74, 349–363. [Google Scholar] [CrossRef] [Scilit]
  62. World Bank. Romania: Real Estate Sector Assessment and ESG Challenges; The World Bank: Washington, DC, USA, 2024; Available online: https://www.worldbank.org/en/country/romania/overview (accessed on 6 July 2025).
  63. Danila, A.; Gheorghiu, G.; Trandafir, R.A.; Iftene, C.; Serban-Comanescu, A. Analysis of the relationship between environmental, social and governance factors and financial performance of Romanian small and medium sized enterprises. Transform. Bus. Econ. 2023, 22, 1003–1021. [Google Scholar]
  64. Gamage, S.K.; Amidu, A.-R.; Levy, D. Social value of property: A qualitative-bibliometric analysis of literature. J. Prop. Res. 2025, 1, 1–27. [Google Scholar] [CrossRef] [Scilit]
  65. Dobrovolskienė, N.; Pozniak, A.; Tvaronavičienė, M. Assessment of the sustainability of a real estate project using multi-criteria decision making. Sustainability 2021, 13, 4352. [Google Scholar] [CrossRef] [Scilit]
  66. Protectia Muncii. Codul Muncii Actualizat. 2024. Available online: https://www.iprotectiamuncii.ro/codul-muncii-actualizat-2024 (accessed on 15 July 2025).
  67. Soares, N.; Bastos, J.; Pereira, L.D.; Soares, A.; Amaral, A.R.; Asadi, E.; Rodrigues, E.; Lamas, F.B.; Monteiro, H.; Lopes, M.A.R.; et al. A review on current advances in the energy and environmental performance of buildings towards a more sustainable built environment. Renew. Sustain. Energy Rev. 2017, 77, 845–860. [Google Scholar] [CrossRef] [Scilit]
  68. Michl, P.; Lorenz, D.; Lützkendorf, T.; Sayce, S. Reflecting sustainability in property valuation—A progress report. J. Prop. Invest. Finance 2016, 34, 552–577. [Google Scholar] [CrossRef] [Scilit]
  69. Danivska, V.; Heywood, C.; Christersson, M.; Zhang, E.; Nenonen, S. Environmental and social sustainability—Emergence of well-being in the built environment, assessment tools and real estate market implications. Intell. Build. Int. 2019, 11, 212–226. [Google Scholar] [CrossRef] [Scilit]
  70. Flyvbjerg, B. Five misunderstandings about case-study research. Qual. Inq. 2006, 12, 219–245. [Google Scholar] [CrossRef] [Scilit]
  71. Yin, R.K. Case Study Research and Applications, 6th ed.; Sage: Thousand Oaks, CA, USA, 2018. [Google Scholar]
  72. Council of Europe. Constanța: Intercultural Cities Programme. Available online: https://www.coe.int/en/web/interculturalcities/constanta (accessed on 22 July 2025).
  73. Investropa. 15 Strong Trends for 2025 in the Romania Property Market. Available online: https://investropa.com/blogs/news/romania-real-estate-trends (accessed on 22 July 2025).
  74. iStockphoto. Aerial View of Constanța Bay, Romania. Available online: https://www.istockphoto.com/photo/aerial-view-of-constanta-bay-romania-gm2177306436-596727127 (accessed on 22 July 2025).
  75. Busu, C.; Busu, M.; Grasu, S.; Skačkauskienė, I.; Fonseca, L.M. A Study of Economic and Social Preferences in Energy-Saving Behavior Using a Structural Equation Modeling Approach: The Case of Romania. Econometrics 2025, 13, 10. [Google Scholar] [CrossRef] [Scilit]
Figure 1. Romania’s GHG emissions by sector, 2022. Source: European Environment Agency [60].
Sustainability 17 07701 g001
Figure 2. Constanța city, Romania [74].
Sustainability 17 07701 g002
Figure 3. Interviewee perspectives on the impact of ESG performance on: (a) property values and investment appeal in Constanța; (b) homebuyer awareness of ESG factors in Constanța.
Sustainability 17 07701 g003
Figure 4. Key enablers of ESG adoption in Constanța’s residential real estate market [from interview data].
Sustainability 17 07701 g004
Table 1. Interview Participant (IP) profile.
IPName of OrganisationType of OrganisationAffiliation
1Building Stefan Business Association (AOP) Limited Liability Company (SRL)Residential development, hospitality services, resort management, property rentalsHead of Development
2Building Stefan AOP SRLResidential development, hospitality services, resort management, property rentalsSenior project manager
3Imobiliaria Tomis SRLReal estate (residential and commercial) development and investment companyProject manager
4Sun Constanța SRLReal estate agencyReal estate agent
5Agenția Imobiliara Ella SRLReal estate agencyReal estate agent
6Biroul Imobiliar SRLReal estate agencyReal estate agent
Table 2. Semi-structured interview template.
Semi-Structured Interview Questionnaire
  • Could you briefly describe your current role and responsibilities within Constanța’s residential real estate sector?
  • On a scale of 1–10 (very low to very high awareness), how would you characterise the level of awareness of ESG principles among key stakeholders in Constanța’s residential real estate industry?
  • Based on your experience, what are the main challenges developers face when attempting to integrate ESG principles into residential projects in Constanța?
  • Can you share any successful initiatives or strategies that you or your organisation have implemented to enhance environmental sustainability in residential developments?
  • On a scale of 1–10 (very low to very high importance), how do ESG considerations influence property values and investment appeal in Constanța’s residential market?
  • Are there any formal mechanisms or tools currently used to assess or monitor ESG performance in residential real estate projects in Constanța?
  • On a scale of 1 to 10 (very low to very high awareness), how familiar do you think homebuyers in Constanța are with ESG principles?
  • What role do you believe local or national government policies and regulations play in shaping the adoption of ESG practices in the residential real estate sector?
  • Looking ahead, what trends or opportunities do you foresee for further embedding ESG principles into residential real estate development in Romania?
Table 3. Key barriers to ESG adoption in Constanța’s residential real estate sector and corresponding policy recommendations.
Key BarriersDescriptionPolicy Recommendations
Narrow environmental focusOveremphasis on energy efficiency and decarbonisation; marginalisation of social and governance dimensions despite broader EU ESG mandates.Promote inclusive ESG frameworks embedding standardised social and governance metrics, in line with CSRD and EU Taxonomy goals.
Limited social value integrationUnderrepresentation of affordability, community wellbeing, and inclusivity, due to absence of standard metrics and limited practical mechanisms.Develop standardised social value metrics; incentivise social inclusion.
Weak governance practicesReactive governance focusing on compliance, weak structures in transitional economies; widespread informal practices and corruption risks undermine governance integrity and ESG credibility.Strengthen governance standards; encourage proactive corporate responsibility; implement anti-corruption measures and transparency initiatives tailored to local contexts; and, enhance enforcement mechanisms and stakeholder engagement to address informal governance dynamics.
Financial constraints and regulatory complexityHigh costs and unclear regulations deter especially smaller developers.Introduce targeted financial incentives; clarify and simplify regulations.
Internal organisational limitationsLimited ESG expertise, cultural resistance to change and poor data management restrict progress and transparency.Provide professional ESG training and capacity building; invest in robust ESG data collection and management systems to support transparent reporting.
Fragmented stakeholder coordinationDisconnected efforts among developers, regulators, financiers, and communities reduce synergy and slow ESG adoption.Foster multi-stakeholder collaboration; align incentives and policies across sectors to create shared goals and coordinated ESG implementation.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.