Systematic Review

Navigating Financial Challenges: A Systematic Review of Enablers for Women Entrepreneurs in South Africa

by
Jeremiah Machingambi
* and
Edward Rankhumise
Department of Management and Entrepreneurship, Faculty of Management Sciences, Tshwane University of Technology, Pretoria 0003, South Africa
*
Author to whom correspondence should be addressed.
J. Risk Financ. Manag. 2026, 19(3), 181; https://doi.org/10.3390/jrfm19030181
Submission received: 11 November 2025 / Revised: 14 December 2025 / Accepted: 19 December 2025 / Published: 4 March 2026
(This article belongs to the Section Business and Entrepreneurship)

Abstract

Access to finance is believed to be a key enabler that enhances women’s entrepreneurship and improves business performance, sustainability, and their empowerment. Despite its importance, scholarly literature has mentioned financial challenges as one of the factors that hinder women’s entrepreneurship success, not only in South Africa but also in other developing countries. There is, however, scant literature regarding the enablers that help women entrepreneurs navigate financial challenges in South Africa. To address this gap, this study conducted a systematic review of literature, where 21 documents drawn from Google Scholar, Scopus, and Google databases were used to identify the enablers that help women entrepreneurs navigate their financial challenges in businesses. Identified enablers that help women entrepreneurs navigate their financial challenges include stokvels, government finance programs, banks, Microfinance Institutions (MFIs), and financial education programs. The study shows how women entrepreneurs navigate financial gaps through informal networks, MFIs, and banks, while government support, institutional innovations, and tailored financial products promote sustainable business growth. The study also highlights the need for governments, banks, MFIs, universities, and NGOs to improve awareness, accessibility, gender-sensitive financial services, digital solutions, training, and mentorship for women entrepreneurs and, therefore, promote sustainable entrepreneurial growth.

1. Introduction

Women constitute 52% of the total population in South Africa (Radebe & Smith, 2023). While men generally exhibit more entrepreneurial activity than women in South Africa, a higher percentage of women (84.1%) operate micro-businesses with one to five employees compared to men (73.5%) in early-stage businesses (Meyer et al., 2024). Furthermore, Meyer et al. (2024) the further asserts that 13.5% of women (between the ages of 18 and 64) are involved in entrepreneurial activity. Chinomona and Maziriri (2015) defined women entrepreneurs as individual women or a group of women who establish a new firm, usually with considerable initiative or risk. In this article, the term “women entrepreneurs” will be used interchangeably with “female entrepreneurs.” Additionally, “women businesses” will be used interchangeably with “female-led businesses.”
Women entrepreneurs are considered a critical component of the entrepreneurial ecosystem in South Africa, contributing significantly to socioeconomic development, job creation, empowerment, and innovation (Bobek et al., 2023). The financial challenges faced by women entrepreneurs in South Africa are usually caused by a lack of access to formal capital due to collateral constraints (Simatele & Kabange, 2022). Women entrepreneurs in South Africa engage in entrepreneurial activities across sectors such as fashion, hairdressing, food services (Kandolo & Ngibe, 2025), retail and trade, smallholder farming, crafts, hospitality, and health and wellness. Formal financial institutions (FFIs) in South Africa are less likely to fund women-owned businesses due to information asymmetry, higher perceived risks, and rigid lending criteria (Asah & Hove-Sibanda, 2025). Women-owned businesses lack skills in financial planning, pitching, and accounting, which are critical for accessing finance (Kandolo & Ngibe, 2024).
Research that focuses on enablers to navigate financial challenges faced by women entrepreneurs in South Africa is limited, with most studies concentrating on the general challenges encountered by women entrepreneurs in the country. Several studies on women entrepreneurship in South Africa have highlighted lack of financial resources as a significant challenge for women entrepreneurs (Aliamutu & Mkhize, 2024; Donga & Chimucheka, 2024; Hlanyane & Acheampong, 2017; Chinomona & Maziriri, 2015; Mhlongo, 2025; Mulaudzi & Schachtebeck, 2022). Women entrepreneurs often struggle to secure traditional sources of funding, such as bank loans and investment capital, as compared to men. This disparity can be attributed to factors such as discriminatory financing practices, lack of guarantees, and a history of poor credit (Aliamutu & Mkhize, 2024). While challenges related to lack of financial resources and access to finance have been identified as key obstacles to the growth and sustainability of women entrepreneurs in South Africa, little research has been conducted on the enablers that help women entrepreneurs navigate these financial challenges. Although numerous studies identify obstacles to women’s access to finance, there is little systematic synthesis of the factors that have enabled successful financial inclusion or business growth among women entrepreneurs. Existing reviews are largely narrative and lack the methodological rigor of systematic review protocols such as PRISMA, limiting generalizability. This article differs from existing literature in that it synthesizes diverse enablers into an integrated structure that reveals interdependencies, particularly how policy interventions and financial innovations interact to strengthen women’s entrepreneurial capacity. This holistic approach provides a basis for both theoretical advancement and practical policy design.
Although scholars have explored general contributing and constraining factors for women entrepreneurship (Ebewo et al., 2025) and socio-economic factors hindering women entrepreneurship in the Gauteng province (Enwereji et al., 2024), limited research has examined these enablers from a broader comparative literature base. Guided by institutional theory, the current study addresses this gap and further develops a conceptual framework that enhances the understanding of enablers for women entrepreneurs to navigate financial challenges in South Africa. The central research question that guides this investigation is as follows: What enablers support women entrepreneurs in overcoming financial challenges in South Africa? To address this research question, the researchers conducted a systematic literature review and subsequently developed an integrative conceptual framework that synthesizes the enablers for women entrepreneurs to navigate financial challenges. This study is significant because the examination of key enablers for women entrepreneurs to navigate financial challenges will help policymakers come up with policies that mitigate financial constraints that hinder the growth of women entrepreneurship. The integrative conceptual framework suggested in this study will enhance the identification of key institutions/stakeholders that can improve women entrepreneurship’s access to finance. To the best of the authors’ knowledge, this is the first systematic literature review that specifically focused on the key enablers for women entrepreneurs to navigate financial challenges, marking a novel contribution to the women entrepreneurship finance field. The study also offers valuable contributions to Sustainable Development Goal (SDG) 5 on gender equality. This research question aligns with SDG 5 by pinpointing elements that reinforce women entrepreneurs, thereby fostering gender equality through enhanced access to financial resources, skills development, and inclusive economic involvement. The study also aligns with SDG 8: Decent work and SDG 9: Infrastructure. This is because enabling women entrepreneurs to access finance to start and grow their businesses will lead to decent employment opportunities and the development of infrastructure to support their entrepreneurial activities. The article is organized as follows: theoretical framework, where the Institutional Theory was deployed; methodology, which stipulates how the Preferred Reporting Items for Systematic Reviews and Meta-Analysis (PRISMA) method was utilized in the study; results of the study; discussion of findings; and integrative conceptualization and conclusion, where research gaps and areas for further research were identified.

2. Theoretical Framework

Women entrepreneurs’ access to finance is influenced by the institutions to which women-owned businesses are subject. This study uses the Institutional Theory as its guiding framework to examine the enablers of women entrepreneurs in navigating financial challenges in South Africa. The Institutional Theory is a valuable framework for understanding how systemic factors shape women’s entrepreneurial experiences (Scott, 1995). The Institutional Theory categorizes the institutional environment into three interconnected pillars: regulatory, normative, and cultural cognitive (Burdon & Sorour, 2020). These pillars collectively influence entrepreneurial behavior, decisions, and opportunities (Risi et al., 2023). By advocating that institutions wield enabling and constraining factors, the Institutional Theory offers a structured approach to analyzing the structural factors that affect women entrepreneurs’ access to finance.
The regulatory pillar addresses formal systems such as policies, laws, and government programs that influence entrepreneurship. The regulatory pillar suggests how policies, support mechanisms, and formal rules like government entrepreneurship and access to finance programs can support and constrain women entrepreneurship (Ebewo et al., 2025). The policies can be supportive and have solid objectives of creating equitable access to finance for women entrepreneurs, but issues like corruption and bureaucratic inefficiencies can create barriers for women entrepreneurs (Lammers & Garcia, 2014). In South Africa, the policies that encompass small business-focused legislation and finance programs serve both supportive and restrictive functions, reflecting the structural inequalities that women entrepreneurs face, though their implementation remains fraught with difficulties (Ebewo et al., 2025). Despite the broad support for human rights and equality in legislation and the constitution and the goal of the National Development Plan (NDP) to eliminate poverty and inequality, these measures often do not include explicit provisions for women’s gendered roles and practices in resource redistribution and economic growth (Ojo & Zondi, 2021). Furthermore, Ojo and Zondi (2021) state that in South Africa, there is a lack of specific, clearly defined, and effective regulatory enablers directly addressing women’s access to finance. In support of that, a report by Bennett et al. (2023) asserts that South African financial institutions do not have dedicated policies for women’s financial inclusion because these are not required by the existing regulatory framework. This suggests a gap in the regulatory requirements that would otherwise compel or incentivize financial institutions to create gender-specific financial products and services.
The normative pillar consists of social norms, values, beliefs, and assumptions that allow a prescriptive, evaluative, and obligatory dimension into the social life of a people (Amine & Staub, 2009). The normative pillar encompasses societal expectations, cultural norms, and behavioral standards. According to Amine and Staub (2009), the normative pillar presents significant challenges for women entrepreneurs in sub-Saharan Africa by capturing societal expectations and cultural norms that directly and indirectly affect their access to finance. Deeply rooted discriminatory cultural values, attitudes, practices, and traditions of patriarchal tendencies create prejudice against women entrepreneurs, which is more severe in Africa than in developed Western nations (Woldie & Adersua, 2004). Additionally, while men becoming entrepreneurs is legitimately acceptable, women as successful entrepreneurs is widely regarded as illegitimate and unacceptable, especially if they outperform their husbands (Trupp & Sunanta, 2017). Also, the concept of Ubuntu, a pervasive spirit of caring and oneness, which ought to guide people’s day-to-day life, can, at times, paradoxically work against individual women entrepreneurs, particularly concerning the management of micro-loans. In collectivist communities, if one member fails to repay a loan for which the group is liable, it leads to stringent negative social consequences, such as loss of personal reputation (Kobeissi & Damanpour, 2003). In a nutshell, by limiting legitimacy, raising group-based lending risks, and reinforcing societal expectations, normative cultural values and gender biases make it difficult for women entrepreneurs to obtain financing.
The cultural-cognitive pillar focuses on internalized beliefs and perceptions such as self-efficacy and resilience. Women entrepreneurs with a college education were found to have confidence in their skills and were more inclined to start their businesses with higher amounts of finances (Egbo et al., 2020). Additionally, Egbo et al. (2020) assert that financial literacy training has been shown to improve entrepreneurs’ confidence in making informed independent decisions regarding savings, setting savings goals, and creating savings plans, while also enhancing positive attitudes about money management behaviors. This directly links cognitive interventions to improved self-efficacy and positive financial perceptions. Financial literacy training plays a pivotal role in enhancing women entrepreneurs’ internalized beliefs, perceptions, and resilience. Lack of training and insufficient financial literacy hinder the empowerment of women entrepreneurs in South Africa (Donga & Chimucheka, 2024; Mulaudzi & Schachtebeck, 2022). Financial literacy skills improve the confidence of women entrepreneurs, thereby leading to improved business income and business sustainability (Jiyane & Zawada, 2013). While education and training improve resilience, informed decision-making, and financial empowerment, low financial literacy and self-efficacy restrict the confidence and financial access of women entrepreneurs.
The justification for utilizing the Institutional Theory in examining the enablers of women entrepreneurs to navigate financial challenges in their businesses is that the researchers also intended to navigate gender-biased institutional systems and identify structural enablers of women entrepreneurs’ access to finance in South Africa. The application of the Institutional Theory in this study contributes to women entrepreneurship research by shedding light on how institutional contexts influence access to finance. The Institutional Theory best fits this study, as it explains how formal and informal institutional structures, such as financial regulations, gender norms, and policy environments, shape women entrepreneurs’ access to financial enablers (Chandran et al., 2025). Unlike resource-based or social capital theories, it captures systemic constraints and supports within South Africa’s distinctive institutional context. The research findings offer recommendations for policymakers, academics, and other stakeholders on the need to address structural challenges while harnessing existing enablers to support women entrepreneurs in navigating the financial challenges they face in their businesses.

3. Materials and Methods

The study was conducted using a systematic review of literature methodological framework. According to Lame (2019), an SLR is a way of synthesizing scientific evidence to address a particular research question in a transparent, reproducible manner, while seeking to include all published evidence on the topic and appraising the quality of evidence. An SLR includes all types of relevant studies from high-quality journals through subjective selection and interpretation of data to synthesize the findings of prior studies in a systematic manner (Paul & Barari, 2022). The researchers initiated a search strategy in three databases, namely, Google Scholar, Google and Scopus. The search strategy followed the following sequence: (i) determining the research question, (ii) describing the articles to address the research question, (iii) deciding the key concepts that address the research question, (iv) deciding the key themes to use in the results, and (v) selecting appropriate registers and databases to search for the articles.

3.1. Publication Screening and Selection

The researchers downloaded the articles for this study from the search engines, and they were saved in Microsoft Excel to identify duplicate articles. The studies were first screened for relevance based on titles, abstracts, and full-text content. Only studies that explicitly examined financial enablers or support mechanisms for women entrepreneurs in South Africa were retained. An Excel spreadsheet was utilized as a data extraction sheet to guide the preliminary screening process. Additionally, if the abstract and title did not provide sufficient information relating to the study, the study findings and conclusions were also reviewed for inclusion in the study analysis. To assess for quality, each article was evaluated using a standardized critical appraisal checklist adapted from the Critical Appraisal Skills Programme (CASP). The criteria included the clarity of research aims, appropriateness of research methods and design, transparency of data collection and analysis, validity and credibility of research findings, and relevance to this systematic review research question.

3.2. Inclusion and Exclusion Criteria

To ensure the rigor and relevance of the review, studies were included if they focused on women entrepreneurs in South Africa and identified enablers that address financial challenges of women entrepreneurs. The inclusion and exclusion criteria for the study are shown in Table 1 below:
Eligible studies were published in English between 2011 and 2025 and included peer-reviewed articles. The justification for using the time frame (2011 to 2025) is that several national programs aimed at supporting women entrepreneurs and improving financial inclusion were implemented after 2010. Therefore, research from 2011 onwards reflects the modern policy environment. These programs include the revision of the Small Business Act and the Broad-Based Black Economic Empowerment (B-BBEE) reforms with an emphasis on supporting women-owned businesses post-2011. The establishment and expansion of agencies like the Small Enterprise Development Agency (SEDA) and Small Enterprise Finance Agency (SEFA) increasingly support women post-2011. To enhance objectivity, two reviewers independently appraised all articles. Discrepancies were discussed and resolved through consensus.

3.3. Identification of Primary Search Terms and Threads

To identify potentially relevant studies for the study, keywords such as ‘financial challenges’, ‘enablers’, ‘access to finance’, ‘women entrepreneurs’, ‘women businesses’, and ‘South Africa’ were used. The key words that were used in the study were aligned with the research question and the main theme of the research. The literature search was conducted by combining these keywords using suitable Boolean operators (for example, AND, OR) (Beaven & Craig, 2019; Rao & Moon, 2021). Below are the keywords used in the primary search:
(“women entrepreneur*” OR “female entrepreneur*” OR “women-owned business*”
OR “female-owned enterprise*” OR “women business owner*” OR “women-led SME*”)
AND
(“financial challenge*” OR “financial constraint*” OR “access to finance”
OR “credit access” OR “capital access” OR “funding constraint*”
OR “financial barrier*” OR “financial inclusion” OR “entrepreneurial finance”)
AND
(“enabler*” OR “support mechanism*” OR “facilitator*” OR “support program*”
OR “government support” OR “policy support” OR “capacity building”
OR “financial enabler*” OR “entrepreneurship support”)
AND
(“South Africa”)
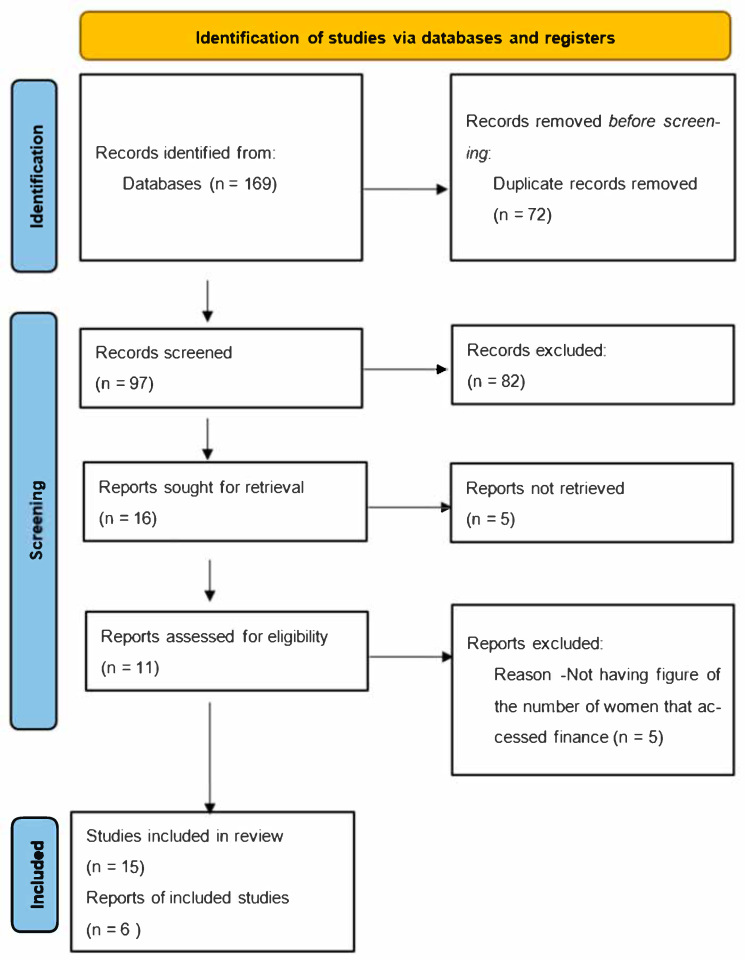
The systematic review was conducted in line with the Preferred Reporting Items for Systematic Reviews and Meta-Analyses (PRISMA) 2020 guidelines. The study selection process was documented using the PRISMA 2020 flow diagram shown in Figure 1. Compliance with the PRISMA 2020 checklist (Page et al., 2021) is provided in the Supplementary Materials. The review protocol was not registered.

3.4. Data Extraction and Assessment

3.4.1. Database Search

The study inclusion criteria outlined that the research studies needed to be in peer-reviewed journals (Atkinson et al., 2015; Patino & Ferreira, 2018). The literature search was conducted in May, June and July 2025 across the following databases: Google Scholar, Scopus and Google. The inclusion of Google Scholar and Google was performed to access a wide array of relevant literature, as they are among the largest research databases globally, specifically for accessing peer-reviewed journals (Ranganai Matenda & Sibanda, 2023). As highlighted earlier, only peer-reviewed journals were included in the SLR study to ensure the reliability and validity of the research. Master’s theses, doctoral theses, non-peer-reviewed articles, books, and book chapters were excluded from the study. A total of 21 peer-reviewed articles and reports were included for the final review after removing studies that did not meet the inclusion criteria and duplicates. The article selection process is shown in Figure 1. The PRISMA diagram showed that 169 articles were initially identified from the database search using relevant keywords highlighted earlier. A total of 72 documents were excluded as they were not relevant to the research topic during the initial screening process. Furthermore, the researchers also identified and removed duplicate records from the database search. The initial screening process thus produced 97 documents that were further screened using titles, abstracts, findings and conclusions in some cases. As a result, 82 documents were excluded, as they did not focus on enablers of women entrepreneurs in navigating their financial challenges but, rather, on general challenges facing women entrepreneurs. In addition, 16 reports were initially retrieved for the study, and 5 reports were not, leaving 11 being assessed for eligibility. Of the 11 reports, 5 were excluded for not having figures on the number of women who accessed finance, leaving 6 reports included for the study. The study was then left with 21 relevant documents that were used in the data analysis. The small number of selected articles reflects the topic’s specificity and the rigorous inclusion criteria applied. Saturation was achieved as the 21 studies consistently addressed recurring themes and enablers, indicating that additional sources were unlikely to contribute new insights relevant to enablers of women entrepreneurs’ capacity to navigate the financial challenges in South Africa.

3.4.2. Coding Process and Analysis

In this SLR, relevant information from 21 peer-reviewed articles and reports was extracted, arranged and coded. From the codes, five themes emerged as enablers for women entrepreneurs to navigate their financial challenges. The research focused only on enablers for South African women entrepreneurs to navigate their financial challenges; thus, article saturation was reached at 21 documents. A descriptive analytical method was utilized to formulate the key themes. Key findings from reviewed studies, in line with each theme, were identified to address the research question.

4. Results

This section describes the enablers that enhance women entrepreneurs in navigating financial challenges. The results are based on themes (enablers) identified through the literature review. Table 2 shows a summary of reviewed literature on enablers that help women entrepreneurs to navigate financial challenges. The results section is arranged as follows: author(s), methodology, sector, and area, as well as findings/conclusions.

5. Discussion

5.1. Stokvels

Stokvels, also known as savings clubs or rotating savings and credit associations (ROSCAs), are seen as a common aspect of women entrepreneurs residing in South African townships and are viewed as a semi-formal tool that promotes a savings culture (Maziriri et al., 2024). Stokvels offer access to capital, networking opportunities, and a supportive community. Women who are part of stokvels can easily obtain small loans to sustain their businesses and cover their expenses, including family responsibilities (Maziriri et al., 2024). Stokvels play a significant role in women’s entrepreneurship, particularly for women who are financially excluded or facing extreme poverty (Masha & Fihla, 2025). Stokvels appeal to women because they require less documentation for access to finance and can be set up at people’s convenience as compared to most formal financial services. Stokvels in South Africa have led to the rise in women entrepreneurship. Masha and Fihla (2025) state that women invest their stokvel funds into micro-enterprises such as shebeens (taverns), laundry and sewing services, small grocery shops (spaza shops), and dairy shops. Also, in rural areas, women operate most micro-enterprises using collective savings funds for purchasing stock or transporting goods, among other things (Masha & Fihla, 2025). Adewumi et al. (2025) assert that stokvels offer an alternative to mainstream banking services and financial institutions for women entrepreneurs who are financially excluded, thereby allowing impoverished people a way to make their own money.
Stokvels foster entrepreneurial competencies such as getting people into new initiatives, building financial resources for the group, and instilling a financial and entrepreneurial mindset; they also contribute to economic growth and job creation (Armstrong, 2022). According to Mba and Mzileni (2023), stokvels are investment arms that Black women street vendors have used to create and grow their collective earnings. An earlier study by Van Wyk (2017) revealed that in rural South Africa, stokvels help women entrepreneurs by supplementing their limited earnings and guaranteeing them access to credit when needed. Through access to finance from stokvels, women entrepreneurs manage to access start-up capital to engage in small, medium, and micro-enterprises (SMMEs) (Van Wyk, 2017). This is vital for women entrepreneurs who are often regarded as ‘‘unworthy of credit’’ by formal financial institutions like commercial banks, thereby enabling them to start small businesses with stokvel loans. In the South African context, where formal institutions often exclude women, stokvels emerge as an alternative, community-driven mechanism that legitimizes entrepreneurial activity. Stokvels, thus, reshape financial norms by enabling access to capital, fostering entrepreneurship, and promoting inclusive economic participation.
The research findings revealed that stokvels are pivotal informal financial mechanisms that promote women’s entrepreneurship in South Africa. Stokvels are key in providing women entrepreneurs in South African townships with access to start-up capital and networking. The results resonate well with Niyonsaba et al. (2022), who assert that saving and credit groups (ROSCA) have a very successful story since they aid people who are unable to have access to saving and credit services from banks. This implies that informal institutions like stokvels (also called ROSCA) fill in the void left by formal financial systems. This supports the Institutional Theory in that social norms and collective agreements shape entrepreneurial behavior and economic participation of women entrepreneurs in disadvantaged and resource-constrained environments. Savings and credit organizations are very effective in increasing women’s entrepreneurship (Niyonsaba et al., 2022). In support of that, Adekanla (2021) posits that most women entrepreneurs use ROSCA money for capital accumulation and other business expansion purposes. Furthermore, ROSCA was found to have a significant and positive effect on the performance of businesses of rural women. ROSCA significantly serves as an alternative financial source for rural women and hence helps in empowering this economically vulnerable group. In Zimbabwe, Mutsindikwa and Gelderblom (2023) state that women entrepreneurs were using ROSCA money to carry out unregistered businesses, selling from their homes or undesignated places.

5.2. Government Finance Support

During the period 2023/2024, the Small Enterprise Finance Agency (SEFA) disbursed R811,043,079 to women entrepreneurs in South Africa, achieving 99% of the annual target of R822,688,000 (SEFA, 2024). Businesses in rural towns and villages received R728,357,253 in disbursements from SEFA, representing 85% of the annual target of R856,336,000 (SEFA, 2024). In line with the Institutional Theory, formal norms such as transformation frameworks, government policies, and gender equity targets create coercive pressures that require SEFA to prioritize women and rural entrepreneurs, thus explaining SEFA’s disbursements of 99% and 85% of annual targets. The women entrepreneurs and rural entrepreneurs funded were mainly operating in the retail sector, such as spaza shops, general dealers, or grocery stores (SEFA, 2024), which are traditionally prominent points for women entrepreneurs. The Institutional Theory explains SEFA’s concentration of funding in spaza shops and general dealers and reflects alignment with culturally embedded entrepreneurial patterns in rural and township economies.
Other sectors funded by SEFA include agriculture (contract farming activities), small construction contractors, wholesale and tourism, and green industries (renewable energy and recycling management). The same sentiments were echoed by Sethwana and Ramukumba (2024), who asserted that SEFA funds tourism women-owned SMMEs in Limpopo province and offers loans and grants to small businesses, with low interest rates and flexible repayment terms. These grants are available for startup and expansion projects. (Sethwana & Ramukumba, 2024). Mandipaka (2014a) asserts that in the absence of personal savings and gender prejudice in current lending institutions, IWF is an attempt by the government to increase women’s access to formal financing. Isivande Women’s Fund thus addresses the discriminatory attitudes and practices of formal lending institutions towards lending to women entrepreneurs.
To mitigate challenges of discrimination against women entrepreneurs in a male-dominated society, Mandipaka (2014b) suggested that the South African government needs to offer financial support and mentorship programs for them. Ojo and Zondi (2021), however, assert that the South African government has not yet fully integrated women’s access to finance as an effective strategy for their empowerment. Additionally, Derera (2021) posited that most women entrepreneurs were not aware of government finance support programs that were targeting them; hence, most of them were not benefiting from the programs. In this regard, Ebewo et al. (2025) recommended the South African government simplify access to funding opportunities to create a more equitable and supportive environment for women entrepreneurs. The Institutional Theory highlights the role of formal institutions in shaping and enabling entrepreneurial activity through supportive policies and financial mechanisms. In this context, government initiatives like SEFA and the Isivande Women’s Fund demonstrate how formal institutions can evolve to address institutional gaps such as gender bias and financial exclusion. These efforts legitimize and support women’s entrepreneurship by providing inclusive access to finance.
The Department of Trade and Industry (DTI) allocated substantial financial resources amounting to millions of rand to support women entrepreneurs through training, grants, counseling and care facilities (Kandolo & Ngibe, 2024). According to IDC (2025), there was a decline in support for women-led businesses from R11.4 billion to R5.6 billion. However, this exceeded the annual target by 142%. The funding for women entrepreneurs in South Africa was part of the overall R26.6 billion investment for a priority group of entrepreneurs by the IDC in the 2024/2025 year. Compliance with national development plans and performance targets drives structured programs like IDC support across strategic industries and SEFA’s sectorial funding. The IDC reported that support was provided to women-led businesses operating in the automotive and transport, chemicals and pharmaceuticals, machinery, equipment, electronics, energy or renewable energy, and green hydrogen sectors (IDC, 2025). IDC’s support for women in high-value sectors reflects evolving informal societal norms that increasingly expect women to participate in industrial, energy, and technology arenas. The Isivande Women’s Fund is administered by the IDC and supports at least 60% of women-owned businesses. The funding ranges from R30,000 to R2 million for use as working capital, asset finance, and business expansion and offers recipients low interest and flexible terms. Gender-responsive grants like the Isivande Women’s Fund provide up to R5 million rand to Black-owned women’s enterprises in sectors like manufacturing and services, and the WEF assists women-owned enterprises, particularly in green economy industries (Ogujiuba et al., 2025). These grants are specifically designed to alleviate the financial barriers encountered by women entrepreneurs by offering essential equity-free financial support aimed at creating equal opportunities. The IDC’s continued support for women entrepreneurs through the Isivande Women’s Fund reflects normative pressures to advance gender equality, aligning them with national development agendas.
The Women Empowerment Fund (WEF) is administered by the National Empowerment Fund (NEF) and targets South African women-owned businesses with 51% or more ownership. It provides strategic guidance and mentorship as well as debt and equity finance (National Empowerment Fund, 2025). The WEF supports women-owned businesses across the services, manufacturing, and agriculture sectors (National Empowerment Fund, 2025). According to the National Empowerment Fund (2025) report, the Women Empowerment Fund funded different sectors, including manufacturing (R37.3 million), waste management (R15 million), tourism (R13.9 million), mining services (R45.7 million), and IT services (R14 million). It is important to note that this funding was allocated to single women-owned businesses in each sector. Formal norms, including national policies like gender equality, Broad-Based Black Economic Empowerment (B-BBEE) requirements, and the NEF’s transformation mandate, create pressures for WEF to prioritize women-owned businesses with at least 51% ownership. Additionally, informal norms such as societal expectations around women’s entrepreneurial capabilities and emerging perceptions of women’s participation in non-traditional sectors influence how WEF allocates resources. Historically, women entrepreneurs in South Africa were concentrated in service-oriented informal sectors, but the growing social acceptance of women operating in manufacturing, IT, and mining sectors now enables WEF to fund women beyond the traditional roles.
The study reveals that government financial support services such as IDC, SEFA, and the Isivande Women’s Fund provide financial access, mentorship, and training to women entrepreneurs through accessible venture capital, loans, and grants. Despite these efforts, there is limited accessibility and awareness, which constrains their effectiveness, highlighting the need for institutional alignments improving communication and policy implementation. Government-backed schemes contribute positively but are hindered by implementation inefficiencies in Sub-Saharan Africa (Irene et al., 2025). Manwari et al. (2017) recommended the government of Kenya improve access to finance for women entrepreneurs by strengthening friendly loan policies and regulations and using ICT platforms like mobile telephony to provide loans. The issues in South Africa and Kenya highlight Institutional Theory’s emphasis on the role of formal structures and norms, revealing misalignment between policy intent and implementation. Limited awareness and access underscore institutional inefficiencies, requiring improved coordination, communication, and supportive regulatory frameworks to enhance women’s entrepreneurship. In India, Raj (2018) asserts that the government and banks were providing financial assistance to youths and women through programs like Start-up India, the MUDRA Yojana scheme for women, the Annapurna scheme, the Stree Shakti package for women entrepreneurs, the Bharatiya Mahila Bank business loan, and the Mahila Udyami Nidhi scheme, among others. In support of this, the Government of Pakistan effectively delivered existing resources and capital to women entrepreneurs during the COVID-19 pandemic (Hussain et al., 2023). The pandemic brought the government and women entrepreneurs on the same page in terms of communication to solve challenges faced by women entrepreneurs.

5.3. Banks

The Standard Bank South Africa, through the Basali Development program, disbursed R1.1 million in grant funding that was provided to 200 women business owners who accessed business skills development through the program (Standard Bank, 2024). Within the agribusiness sector, the OneFarm Share program procured R78 million worth of produce from supported farmers, with 31% of the produce value procured from women farmers (Standard Bank, 2024). Furthermore, Standard Bank (2024) reported that the program supported 582 small-scale farmers, with 30% of them being women. In 2021, Absa spent R6.5 billion on procurement, with 30% being from Black women-owned business suppliers (Absa Group Limited, 2021). Additionally, Absa has a women empowerment finance facility that finances start-ups and existing women-led businesses, providing funding of up to R15 million, with repayment periods ranging from 12 months to 5 years (Absa Group Limited, 2021). The Development Bank of Southern Africa (DBSA) has a women empowerment fund that targets women-owned and women-led enterprises aligned with national development goals. DBSA focuses on infrastructure, education, public health, and the green economy, providing market facilitation, technical support, and project development funding (Development Bank of Southern Africa, 2024). According to DBSA (Development Bank of Southern Africa, 2024), the value of infrastructure delivered to Black-owned entities amounted to R2.3 billion, with 49% of the work awarded to B-BBEE companies that have 30% or more Black women ownership (Development Bank of Southern Africa, 2024).
Witbooi and Ukpere (2011) posited that some of the big four commercial banks in South Africa have started implementing clear strategies to target the women’s market, with one major bank even integrating gender-aware staff training into their strategy for banking women, implying that trained bank staff can serve as a source of information and support for women entrepreneurs. However, few banks are willing to fund women entrepreneurs who have no formal training or entrepreneurial skills (Donga & Chimucheka, 2024). An earlier study by Chiloane-Tsoka (2013) showed that most African women resort to using pensions and social club donations like stokvels as a way of starting their own businesses rather than relying on formal financial institutions. The study found that 54.17% of participants used their pension funds and stokvel contributions, while only 22.56% relied on commercial banks (Chiloane-Tsoka, 2013). This implies that women entrepreneurs are usually at a disadvantage in their ability to raise start-up funds and guarantees required for external financing. Additionally, women entrepreneurs’ relationships with bankers may suffer from sexual stereotyping and discrimination, including the outdated assumption that “women can’t handle money” (Marlow & Swail, 2014). In summary, women entrepreneurs face barriers in accessing bank finance due to limited outreach, lack of training, insufficient collateral, and gender bias. Many women entrepreneurs thus tend to rely on pensions or stokvels instead of formal financial institutions.
The systematic review reflected that women entrepreneurs face challenges in accessing bank finance due to limited outreach, lack of training, inadequate collateral, and gender bias. The results align well with Ghosh et al. (2018), who observed that collateral disputes, lengthy processes, suspicion, preconceptions, conservative attitudes of employees, and complexities in loan processing limit women entrepreneurs’ access to institutional finance. An earlier study by Emon and Nipa (2024) revealed formidable obstacles such as restricted access to formal financial resources due to gender biases, societal norms that reinforce traditional roles, a lack of tailored training, and barriers to networking and mentorship. Studies have shown that women entrepreneurs face challenges in accessing bank finance. High collateral demands and interest rates remain major obstacles, particularly for smaller or informal women-led enterprises.

5.4. Microfinance Institutions (MFIs)

MFIs are crucial in providing women-owned businesses with access to financial resources, especially for women who have been excluded from economic activities due to factors like stereotypical gender roles, lack of funds, and historical gender imbalances (Koti & Modiba, 2022). Many women-owned businesses cannot access funding from commercial banks due to a lack of collateral security (Chiloane-Tsoka, 2013). Microfinance provides these women small business owners with the necessary finance to participate actively in the economy. Microfinance loans are disbursed through MFIs to help women to start businesses in South Africa (Chiloane-Tsoka, 2013; Koti & Modiba, 2022). According to Koti and Modiba (2022), women constituted most MFI clients. In 2018, 80% of loans were disbursed to women, with approximately 65% going to women borrowers in poorer provinces like the Eastern Cape. This was partly because women clients tend to repay their loans on time, helping MFIs to close the financial access gaps.
In the quest to mitigate financial challenges faced by women entrepreneurs, MFIs partnered with other organizations, including government departments like the Department of Trade and Industry, Small Enterprise Development Agency (SEDA), Small Enterprise Finance Agency (SEFA), Department of Social Development, and educational institutions like Nelson Mandela University to provide a broad range of financial and business support (Koti & Modiba, 2022). Microfinance lenders such as Marang Financial Services and Small Enterprise Foundation (which collectively serve a significant number of clients) are seen as resources for women’s economic empowerment (Witbooi & Ukpere, 2011). Additionally, Shambare (2011) highlighted that microfinance targeting women entrepreneurs, like the Small Enterprise Foundation (SEF) in South Africa, has proved to be very successful.
The study revealed that MFIs provide crucial financial access to women entrepreneurs who are excluded from banks due to a lack of collateral security by partnering with government and educational bodies to empower women and support business start-ups. At the growth stage, women-owned businesses usually require working capital to scale operations, such as investment in marketing activities, purchasing assets, and recruiting new talent. In this study, we recommend that sustainable MFIs fund women entrepreneurs at the growth stage. Sustainable MFIs target active clients with marketable skills (Morduch, 2000; Machingambi, 2020). MFIs can introduce larger ticket-size loans with longer repayment periods and design financial products that are tailored for specific sectors where women entrepreneurs operate. MFIs can also provide collateral-free or low-collateral loans by accepting alternatives like purchase orders, invoices, and inventory, as well as exploring revenue-based lending where repayment is a percentage of sales.

5.5. Financial Literacy Programs

The high rate of illiteracy among some entrepreneurs makes them reluctant to take loans, even with low interest rates (Derera, 2021). Women entrepreneurs access financial education programs from university incubators. Women entrepreneurs largely access financial education and literacy through dedicated skills development programs, workshops on financial management, and government intervention initiatives often facilitated by entrepreneurship development centers owned by universities (Ebewo et al., 2025). Furthermore, Ebewo et al. (2025) asserted that university incubation hubs have led women entrepreneurs to understand how to budget and plan and have confidence in making business decisions. Ngcobo et al. (2025) note that the gender gap in entrepreneurial activities is narrowing in South Africa, as observed by an increase in gender-focused financial education training, leading to more women starting their own businesses.
Women entrepreneurs in South Africa, particularly in KwaZulu-Natal (Durban), face challenges due to insufficient or limited financial literacy and business skills (Kandolo & Ngibe, 2024). Kandolo and Ngibe (2024) recommended that the eThekwini Municipality managers organize seminars and vocational courses on entrepreneurship gender sensitivity and entrepreneurial financial management for aspiring women entrepreneurs. Lack of financial literacy and business skills is, thus, a barrier to women’s entrepreneurship in South Africa. There is a need, as per the recommendation for the eThekwini municipality, for localized financial education interventions to improve women’s entrepreneurial success (Kandolo & Ngibe, 2024). Also, MFIs need to incorporate financial literacy training that includes bookkeeping, financial management, and investment readiness at this stage. Financial education training for women entrepreneurs can also be offered by universities through their incubators. Financial literacy is a critical enabler of access to credit for women entrepreneurs in Sub-Saharan Africa (Irene et al., 2025).

6. Conclusions

The study focused on enablers that enhance women entrepreneurs in navigating their financial challenges. Research found that women entrepreneurs use stokvels, government finance programs, banks, MFIs, and financial education programs to navigate their financial challenges.

6.1. Theoretical Implications

The study has several theoretical implications. The study findings showed that there are five enablers that enhance women entrepreneurs in navigating their financial challenges: stokvels, banks, MFIs, government finance, and financial education. The study provides strong evidence that the Institutional Theory is a useful lens for understanding how women entrepreneurs navigate financial ecosystems in South Africa. As highlighted earlier, the Institutional Theory emphasizes that entrepreneurial activity is shaped by a combination of formal institutions and informal institutions. Stokvels represent informal institutions that address structural gaps within the formal financial system. Through trust-based norms, collective savings, and community accountability, stokvels offer accessible credit, social capital, and legitimacy for women who face exclusion from mainstream finance. Their success demonstrates how informal institutions adapt to local realities and become stabilizing mechanisms in resource-constrained environments, aligning directly with the Institutional Theory’s argument that informal norms strongly influence behavior when formal systems fail. Government finance support, including SEFA, IDC, IWVF, and WEF, illustrates how coercive institutional pressures such as gender equity policies, transformation mandates, and national development agendas shape organizational behavior. These formal institutions are compelled to design gender-responsive financing mechanisms, thereby actively reshaping the entrepreneurial landscape. The findings on banks show the enduring influence of normative and cognitive institutional barriers. Despite gender-focused initiatives, entrenched biases, collateral-based lending norms, and stereotypes about women’s financial competencies persist. These illustrate the Institutional Theory’s concept of path dependency, where deeply rooted practices change slowly, even when new norms encourage inclusivity. MFIs serve as hybrid institutional actors that blend formal organizational structures with informal community-based lending practices. By offering collateral-free loans and partnering with government agencies, MFIs reduce institutional voids and expand access to finance for women. Their growing role reflects institutional adaptation, where new organizational forms arise in response to unmet needs within the financial system.

6.2. Practical Implications

There are several practical implications that were drawn from this study. The government agencies in South Africa need to strengthen awareness and accessibility of the financial services support programs available for women entrepreneurs through localized outreach. There must also be improved coordination of government agencies in South Africa, such as SEDA, SEFA, IDC, and WEF, to enhance efficiency in availing finance for women entrepreneurs. There is a need for regular monitoring and evaluation of current financing programs to identify gaps. The categories of financial institutions identified as enablers of women entrepreneurs to navigate their financial challenges are banks and MFIs. It is recommended that banks and MFIs adopt gender-sensitive banking models to address barriers faced by women entrepreneurs in accessing finance, such as limited outreach, gender bias, and collateral requirements. MFIs also need to develop tailor-made products like micro-savings schemes, micro-loans, and flexible repayment plans for women entrepreneurs. MFIs can also digitize the loan process to improve women entrepreneurs’ access to finance by using mobile-based applications for loan disbursement and repayments. MFIs can also implement digital credit scoring using business transaction data like Point of Sale (POS) records and mobile money transactions. Universities need to expand their entrepreneurship incubation hubs and integrate gender-inclusive training and financial literacy into the entrepreneurship curriculum. Research in universities also needs to be conducted to document women entrepreneurs’ financial challenges and best practices that guide institutional reforms and policy programs. Non-Governmental Organizations (NGOs) need to collaborate with MFIs, government agencies, and stokvels to enhance business mentorship and access to microfinance and finance for women entrepreneurs. NGOs also need to integrate training, advocacy, and grassroots empowerment for women entrepreneurs to foster entrepreneurial growth, economic inclusion, and financial independence.

6.3. Limitations of the Study and Research Gaps

This systematic review acknowledges limitations stemming from the small sample of 18 studies and its reliance on secondary data. The limited number of eligible publications may constrain the comprehensiveness and depth of insights, while dependence on existing literature restricts contextual validation. Future research should integrate primary data and broader sources to strengthen empirical robustness and applicability.

6.4. Research Gaps

Women entrepreneurs’ access to finance is a vital research area that contributes to SDG 5, addresses South Africa’s economic growth and employment issues, and promotes women’s economic empowerment and gender equality. It remains a vital topic with significant research potential. The study recommends further studies to be conducted on government financial support programs in the following areas: (1) How government organizations identify women entrepreneurs for funding. (2) Which women entrepreneurs have received funding and from which sectors. (3) The impact of individual funding from organizations like SEFA on the performance of women entrepreneurs. Microfinance can serve as a powerful economic development enabler and a vital tool in alleviating the challenge of lacking access to finance among women entrepreneurs in South Africa (Chinomona & Maziriri, 2015). The impact of microfinance on poverty alleviation has revolved around two contrasting approaches: sustainable lending, which focuses on serving the ‘active poor’ clients, and subsidized lending, which focuses on serving ‘extremely poor’ clients (Machingambi, 2020). The study recommends further research on how women entrepreneurs benefit from sustainable and poverty lending-aligned microfinance programs at different stages of their businesses, whether informal or formal.

Supplementary Materials

The following supporting information can be downloaded at: https://www.mdpi.com/article/10.3390/jrfm19030181/s1.

Author Contributions

Conceptualization, J.M. and E.R.; methodology, J.M.; validation, J.M.; formal analysis, J.M.; writing—original draft preparation, J.M.; writing—review and editing, E.R.; supervision, E.R.; project administration, J.M.; funding acquisition, E.R. All authors have read and agreed to the published version of the manuscript.

Funding

The research was funded by Tshwane University of Technology, Postdoctoral Funding (PST-1810).

Institutional Review Board Statement

Not applicable.

Informed Consent Statement

Not applicable.

Data Availability Statement

All data sources can be found in cited papers.

Conflicts of Interest

The authors declare no conflicts of interest.

Abbreviations

The following abbreviations are used in this manuscript:
B-BBEEBroad-based Black Economic Empowerment
DBSADevelopment Bank of South Africa
FFIFormal Financial Institutions
MFIMicrofinance Institutions
SDGSustainable Development Goals
NDPNational Development Plan
SLRSystematic Literature Review
ROSCAsRotating Savings and Credit Associations
SEFASmall Enterprise Finance Agency
IDCIndustrial Development Corporation
DTIDepartment of Trade and Industry
SEDASmall Enterprise Development Agency
WEFWomen Empowerment Fund
NEFNational Empowerment Fund
ICTInformation Communication Technology

References

  1. Absa Group Limited. (2021). Broad-based black economic empowerment report. Available online: https://www.absa.africa/wp-content/uploads/2023/03/Absa-Group-Broad-Based-Black-Economic-Empowerment-Report.pdf (accessed on 5 October 2025).
  2. Adekanla, N. (2021, November 4–5). Alternative financial inclusion and women empowerment in the covidian era: Evidence from rural women entrepreneur in ROSCA in south-western Nigeria. Conference on Cooperatives and the Solidarity Economy (CCSE) (pp. 4–5), Johannesburg, South Africa. [Google Scholar]
  3. Adewumi, S. A., Masha, A. K., & Bwowe, P. (2025). An analysis of reasons why widows join stokvels: An Eastern Cape story. E-Journal of Humanities Arts and Social Sciences, 6(6), 653–669. [Google Scholar] [CrossRef] [Scilit]
  4. Aliamutu, K. F., & Mkhize, M. V. (2024). The obstacles of women entrepreneurship on empowerment in rural communities KwaZulu Natal, South Africa. Indonesian Journal of Innovation and Applied Sciences (IJIAS), 4(1), 88–96. [Google Scholar] [CrossRef] [Scilit]
  5. Amine, L. S., & Staub, K. M. (2009). Women entrepreneurs in sub-Saharan Africa: An institutional theory analysis from a social marketing point of view. Entrepreneurship and Regional Development, 21(2), 183–211. [Google Scholar] [CrossRef] [Scilit]
  6. Armstrong, A. (2022). Stokvels: A South African innovation in economic justice for women. In S. H. Caroline, & P. J. Christabell (Eds.), Community economies in the global south: Case studies of rotating savings and credit associations and economic cooperation. Oxford University Press. [Google Scholar]
  7. Asah, F. T., & Hove-Sibanda, P. (2025). Formal financial institutions’ financing of women-owned small and medium enterprises in South Africa: A supply-side perspective. Qualitative Research in Financial Markets, 17(1), 210–228. [Google Scholar] [CrossRef] [Scilit]
  8. Atkinson, K. M., Koenka, A. C., Sanchez, C. E., Moshontz, H., & Cooper, H. (2015). Reporting standards for literature searches and report inclusion criteria: Making research syntheses more transparent and easy to replicate. Research Synthesis Methods, 6(1), 87–95. [Google Scholar] [CrossRef] [Scilit]
  9. Beaven, O., & Craig, J. V. (2019). Searching the literature. In J. V. Craig, & D. Dowding (Eds.), Evidence-based practice in nursing (p. 31). Elsevier Health Sciences. [Google Scholar]
  10. Bennett, D., Sriram, K., Rathore, R., Grundling, I., Gibb, Y., Iyer, S., Jenkins, A., Thomas, M., Niethammer, C., Pettitt, A., & Premchander, S. (2023). Ensuring access to finance for women entrepreneurs. Available online: https://www.global-solutions-initiative.org/wp-content/uploads/2025/03/T20_PB_TF1_24_Ensuring_Access_to_Finance_for_Women_Entrepreneurs.pdf (accessed on 10 September 2025).
  11. Bobek, V., Schachl, A., & Horvat, T. (2023). The impact of women’s economic empowerment on the rise of female entrepreneurship and human capital in South Africa. International Journal of Diplomacy and Economy, 9(1), 23–56. [Google Scholar] [CrossRef] [Scilit]
  12. Burdon, W. M., & Sorour, M. K. (2020). Institutional theory and evolution of ‘a legitimate’ compliance culture: The case of the UK financial service sector. Journal of Business Ethics, 162(1), 47–80. [Google Scholar] [CrossRef] [Scilit]
  13. Chandran, R., Chandran, M. S., Achuthan, K., & Sahib, P. R. (2025). Theoretical perspectives on green banking adoption in India: Regulatory uncertainty, institutional barriers, and policy solutions. Discover Sustainability, 6(1), 581. [Google Scholar] [CrossRef] [Scilit]
  14. Chiloane-Tsoka, E. (2013). An investigation into the financial barriers facing women entrepreneurs operating in SMMEs in Tshwane, South Africa. Journal of Economic and Financial Sciences, 6(2), 347–358. [Google Scholar] [CrossRef] [Scilit]
  15. Chinomona, E., & Maziriri, E. T. (2015). Women in action: Challenges facing women entrepreneurs in the Gauteng Province of South Africa. The International Business & Economics Research Journal, 14(6), 835. [Google Scholar] [CrossRef] [Scilit]
  16. Derera, E. (2021). Awareness of government entrepreneurial support programmes: A survey of women entrepreneurs in South Africa. In Handbook of research on nascent entrepreneurship and creating new ventures (pp. 253–272). IGI Global Scientific Publishing. [Google Scholar] [CrossRef] [Scilit]
  17. Development Bank of Southern Africa. (2024). 40 years of development progress: 2024 integrated annual report—Building Africa’s prosperity. Available online: https://www.dbsa.org/sites/default/files/media/documents/2024-08/DBSA%20Annual%20Financial%20Statements%202024_0.pdf (accessed on 4 December 2025).
  18. Donga, G., & Chimucheka, T. (2024). Rural women entrepreneurship in South Africa: Issues and challenges. African Journal of Inter/Multidisciplinary Studies, 6(1), 1–12. [Google Scholar] [CrossRef] [Scilit]
  19. Ebewo, P. E., Schultz, C., & Mmako, M. M. (2025). Towards inclusive entrepreneurship: Addressing constraining and contributing factors for women entrepreneurs in South Africa. Administrative Sciences, 15(1), 14. [Google Scholar] [CrossRef] [Scilit]
  20. Egbo, O. P., Ezeaku, H., Igwemeka, E., & Okeke, O. M. (2020). Financial literacy and access: Revisiting the bridges and barriers to women entrepreneurship in Nigeria. Amazonia Investiga, 9(29), 436–444. [Google Scholar] [CrossRef] [Scilit]
  21. Emon, M. M. H., & Nipa, M. N. (2024). Exploring the gender dimension in entrepreneurship development: A systematic literature review in the context of Bangladesh. Westcliff International Journal of Applied Research, 8(1), 10-47670. [Google Scholar] [CrossRef] [Scilit]
  22. Enwereji, P. C., Innocent, B., & Aluko, T. O. A. (2024). Socio-economic challenges hindering women entrepreneurs’ business sustainability in Gauteng Province. Research on Enterprise in Modern Economy, 1(38), 37–61. [Google Scholar]
  23. Ghosh, P. K., Ghosh, S. K., & Chowdhury, S. (2018). Factors hindering women entrepreneurs’ access to institutional finance-an empirical study. Journal of Small Business & Entrepreneurship, 30(4), 279–291. [Google Scholar] [CrossRef] [Scilit]
  24. Hlanyane, T. M., & Acheampong, K. O. (2017). Tourism entrepreneurship: The contours of challenges faced by female-owned BnBs and Guesthouses in Mthatha, South Africa. African Journal of Hospitality, Tourism and Leisure, 6(4), 1–17. [Google Scholar]
  25. Hussain, N., Li, B., & Sahibzada, H. E. (2023). Government support to Pakistani women entrepreneurs during the COVID-19 pandemic. Public Administration and Policy, 26, 80–92. [Google Scholar] [CrossRef] [Scilit]
  26. Industrial Development Corporation (IDC). (2025). Partnering you, growing the economy, developing Africa: Integrated report 2025—Performance overview. Available online: https://www.idc.co.za/integrated-report/wp-content/uploads/2025/09/IDC-Integrated-Report-2025.pdf (accessed on 15 December 2025).
  27. Irene, B., Ndlovu, E., Felix-Faure, P. C., Dlabatshana, Z., & Ogunmokun, O. (2025). The role of financial institutions in bridging the financing gap for women entrepreneurs in Sub-Saharan Africa. Administrative Sciences, 15(8), 323. [Google Scholar] [CrossRef] [Scilit]
  28. Jiyane, G., & Zawada, B. (2013). Sustaining informal sector women entrepreneurs through financial literacy. Libri, 63(1), 47–56. [Google Scholar] [CrossRef] [Scilit]
  29. Kandolo, K. M., & Ngibe, M. (2024). Exploring financial knowledge influences on the economic empowerment of women entrepreneurs in Kwazulu-Natal, South Africa. International Journal of Research in Business & Social Science, 13(8), 212. [Google Scholar] [CrossRef] [Scilit]
  30. Kandolo, K. M., & Ngibe, M. (2025). Female entrepreneurship: How Congolese refugee women drive economic growth in KwaZulu-Natal, South Africa. In M. Twum-Darko (Ed.), Economics and entrepreneurship: The proceedings of the 10th international conference on business and management dynamics (ICBMD) Edition 1 (pp. 230–248). Available online: https://stm.bookpi.org/EETPICBMD/article/view/17196 (accessed on 13 December 2025). [CrossRef] [Scilit]
  31. Kobeissi, N., & Damanpour, F. (2003). From poor to entrepreneur: An innovative strategy to entrepreneurship and small business development. Journal of Enterprising Culture, 11(4), 399–405. [Google Scholar] [CrossRef] [Scilit]
  32. Koti, K., & Modiba, F. S. (2022). The role of microfinance institutions in enhancing the sustainability of women-owned SMMES. Investment Management & Financial Innovations, 19(2), 306. [Google Scholar] [CrossRef] [Scilit]
  33. Lame, G. (2019). Systematic literature reviews: An introduction. Proceedings of the Design Society: International Conference on Engineering Design, 1(1), 1633–1642. [Google Scholar] [CrossRef] [Scilit]
  34. Lammers, J. C., & Garcia, M. A. (2014). Institutional theory. In L. L. Putnam, & D. K. Mumby (Eds.), The SAGE handbook of organizational communication: Advances in theory, research, and methods (3rd ed., pp. 195–216). SAGE Publications. [Google Scholar]
  35. Machingambi, J. (2020). The impact of microfinance on the sustainability of poor clients: A conceptual review. Journal of Entrepreneurial Innovations, 1(1), 50. [Google Scholar] [CrossRef] [Scilit]
  36. Mandipaka, F. (2014a). An investigation of the challenges faced by women entrepreneurs in developing countries: A case of King Williams’ Town, South Africa. Mediterranean Journal of Social Sciences, 5(27), 1187–1193. [Google Scholar] [CrossRef] [Scilit]
  37. Mandipaka, F. (2014b). Overview of women entrepreneurs in South Africa. Mediterranean Journal of Social Sciences, 5(9), 127–130. [Google Scholar] [CrossRef] [Scilit]
  38. Manwari, L., Ngare, P., & Kipsang, R. (2017). Access to finance for women entrepreneurs in Kenya: Challenges and opportunities. Journal of Emerging Trends in Economics and Management Sciences, 8(1), 37–47. [Google Scholar]
  39. Marlow, S., & Swail, J. (2014). Gender, risk and finance: Why can’t a woman be more like a man? Entrepreneurship & Regional Development, 26(1–2), 80–96. [Google Scholar] [CrossRef] [Scilit]
  40. Masha, A. K., & Fihla, S. (2025). Alleviation of poverty through entrepreneurship in savings and credit associations–stokvels—A case study from South Africa. Insights into Regional Development, 7(1), 159–173. [Google Scholar] [CrossRef] [Scilit]
  41. Maziriri, E. T., Nyagadza, B., & Maramura, T. C. (2024). “Oh no! all my money is gone”: The detrimental consequences of participating in stokvels among women entrepreneurs within the South African township economy. Journal of Enterprising Communities: People and Places in the Global Economy, 18(5), 1193–1219. [Google Scholar] [CrossRef] [Scilit]
  42. Mba, T., & Mzileni, P. (2023). Stokvels and livelihoods of black women street vendors in urban South Africa. African Journal of Development Studies, 2023(si1), 167. [Google Scholar] [CrossRef] [Scilit]
  43. Meyer, N., Samsami, M., & Bowmaker-Falconer, A. (2024). Women entrepreneurship in South Africa: What does the future hold? Stellenbosch University. Available online: https://edhe.co.za/wp-content/uploads/gem-womens-special-report-electronic-single-compressed-1717418321.pdf (accessed on 15 December 2025).
  44. Mhlongo, A. F. (2025). The impact of financial inclusion on women entrepreneurship in South Africa. In T. Moloi (Ed.), Impacting society positively through technology in accounting and business processes. ICAB 2024. Springer Proceedings in Business and Economics. Springer. [Google Scholar] [CrossRef] [Scilit]
  45. Morduch, J. (2000). The microfinance schism. World Development, 28(4), 617–629. [Google Scholar] [CrossRef] [Scilit]
  46. Mulaudzi, M., & Schachtebeck, C. (2022). Challenges faced by female entrepreneurs: The case of the South African learner transport industry. International Journal of Research in Business & Social Science, 11(5), 523–531. [Google Scholar]
  47. Mutsindikwa, C., & Gelderblom, D. (2023). An analysis of the coping strategies of small-scale female entrepreneurs in Harare, Zimbabwe. Development Southern Africa, 40(4), 854–866. [Google Scholar] [CrossRef] [Scilit]
  48. National Empowerment Fund. (2025). Catalysing transformation, creating shared prosperity for the future: Integrated report 2025—Growing Black economic participation. Available online: https://www.nefcorp.co.za/wp-content/uploads/2025/10/12.-NEF-IR-Layout-2025_V17_29Sep_GM_signed.pdf (accessed on 5 December 2025).
  49. Ngcobo, N., Tshikovhi, N., & Moyo, S. (2025). Exploring entrepreneurship education: Trends and student enrollment at a university of technology. Administrative Sciences, 15(2), 48. [Google Scholar] [CrossRef] [Scilit]
  50. Niyonsaba, B., Adenikinju, A., & Ntoiti, M. (2022). Rotating and accumulating savings and credit associations as effective tool for enhancing the women entrepreneurship. A theoretical review. European Scientific Journal ESJ, 18(22), 141. [Google Scholar] [CrossRef] [Scilit]
  51. Ogujiuba, K., Makhubupetsi, K., & Maponya, L. (2025). Pathways to business financing in South Africa: Exploring microloans, venture capital, and gender-responsive grants. Administrative Sciences, 15(8), 319. [Google Scholar] [CrossRef] [Scilit]
  52. Ojo, T. A., & Zondi, S. (2021). Impact of institutional quality and governance on financial inclusion for women in South Africa: A case of Gauteng women entrepreneurs. The Strategic Review for Southern Africa, 43(2), 59–82. [Google Scholar] [CrossRef] [Scilit]
  53. Page, M. J., McKenzie, J. E., Bossuyt, P. M., Boutron, I., Hoffmann, T. C., Mulrow, C. D., Shamseer, L., Tetzlaff, J. M., Akl, E. A., Brennan, S. E., & Chou, R. (2021). The PRISMA 2020 statement: An dated guideline for reporting systematic reviews. BMJ, 372, n71. [Google Scholar] [CrossRef]
  54. Patino, C. M., & Ferreira, J. C. (2018). Inclusion and exclusion criteria in research studies: Definitions and why they matter. Jornal Brasileiro de Pneumologia, 44, 84–84. [Google Scholar] [CrossRef] [Scilit]
  55. Paul, J., & Barari, M. (2022). Meta-analysis and traditional systematic literature reviews—What, why, when, where, and how? Psychology & Marketing, 39(6), 1099–1115. [Google Scholar] [CrossRef] [Scilit]
  56. Radebe, T. N., & Smith, M. (2023). The current state of women’s entrepreneurship in South Africa. Available online: https://www.womensreport.africa/wr2023-paper-one/ (accessed on 6 July 2025).
  57. Raj, P. (2018). Women entrepreneurship and government support in present scenario in the context of India. IOSR Journal of Business and Management, 20(2), 25–31. [Google Scholar]
  58. Ranganai Matenda, F., & Sibanda, M. (2023). The influence of entrepreneurship on economic growth in BRICS economies. Economic Research-Ekonomska Istraživanja, 36(3), 2275582. [Google Scholar] [CrossRef] [Scilit]
  59. Rao, S., & Moon, K. (2021). Literature search for systematic reviews. In Principles and practice of systematic reviews and meta-analysis (pp. 11–31). Springer. [Google Scholar] [CrossRef] [Scilit]
  60. Risi, D., Vigneau, L., Bohn, S., & Wickert, C. (2023). Institutional theory-based research on corporate social responsibility: Bringing values back in. International Journal of Management Reviews, 25(1), 3–23. [Google Scholar] [CrossRef] [Scilit]
  61. Scott, W. R. (1995). Institutions and organizations. Sage Publications. [Google Scholar]
  62. Sethwana, M. V., & Ramukumba, T. (2024). Government support for rural tourism SMMEs: The case of greater Letaba municipality in South Africa. Studia Periegetica, 46(2), 157–182. [Google Scholar] [CrossRef] [Scilit]
  63. Shambare, R. (2011). MDGs and gender equity in higher education in South Africa. International Journal of Management & Innovation, 3(2), 46+. [Google Scholar]
  64. Simatele, M., & Kabange, M. (2022). Financial inclusion and intersectionality: A case of business funding in the South African informal sector. Journal of Risk and Financial Management, 15(9), 380. [Google Scholar] [CrossRef] [Scilit]
  65. Small Enterprise Finance Agency [SEFA]. (2024). Unlocking potential by investing in the success of small businesses—Annual report 2024. Available online: https://nationalgovernment.co.za/entity_annual/3999/2024-small-enterprise-finance-agency-%28sefa%29-annual-report.pdf (accessed on 5 December 2025).
  66. Standard Bank. (2024). The Standard Bank of South Africa: Annual integrated report for the year ended 31 December 2024—Africa is our home, we drive her growth. Standard Bank. Available online: https://reporting.standardbank.com/static_file/StandardBankGroup/filedownloads/RTS/2024/SBSA_AnnualReport.pdf (accessed on 8 December 2025).
  67. Trupp, A., & Sunanta, S. (2017). Gendered practices in urban ethnic tourism in Thailand. Annals of Tourism Research, 64, 76–86. [Google Scholar] [CrossRef] [Scilit]
  68. Van Wyk, M. M. (2017). Stokvels as a community-based saving club aimed at eradicating poverty: A case of South African rural women. The International Journal of Community Diversity, 17(2), 13. [Google Scholar] [CrossRef] [Scilit]
  69. Witbooi, M., & Ukpere, W. (2011). Indigenous female entrepreneurship: Analytical study on access to finance for women entrepreneurs in South Africa. African Journal of Business Management, 5(14), 5646. [Google Scholar]
  70. Woldie, A., & Adersua, A. (2004). Female entrepreneurs in a transitional economy: Businesswomen in Nigeria. International Journal of Social Economics, 31(1/2), 78–93. [Google Scholar] [CrossRef] [Scilit]
Figure 1. PRISMA Flow Diagram for the study.
Jrfm 19 00181 g001
Table 1. Inclusion and exclusion criteria.
CriteriaInclusionExclusion
PopulationWomen entrepreneurs, women-owned businesses, female-led SMEsGeneral entrepreneurship with no specific gender analysis
Phenomenon of interestAddresses financial challenges, access to finance, funding constraints, financial inclusion or credit accessWomen entrepreneurs but not financial challenges
OutcomeIdentify enablers, policies, facilitators, support programs that help overcome financial challengesFinancial challenges but not enablers or solutions
ContextSouth AfricaGeographic focus is not South Africa
Study typePeer-reviewed articles, conference articles, reputable reportsEditorials, news articles, non-peer-reviewed articles, books, theses
Time frame 2011 to 2025Not within the time frame
LanguageEnglishNot written in English
Source: Authors’ compilation.
Table 2. Enablers that help women entrepreneurs navigate their financial challenges.
Author (s)MethodologySector and /AreaFindings/Conclusions
Maziriri et al. (2024)Method: Qualitative
Instrument-Semi-structured interviews
Design: Narrative design
Sectors: Clothing boutique, Home décor, Hair saloon, Bakery, Restaurant, Restaurant, Freelance photographer, Fruit and vegetable store, Interior design, Carwash and Transportation business.
Area: Soweto township
Women who are part of stokvels can easily obtain small loans to sustain their businesses
Masha and Fihla (2025)Method: Quantitative
Instrument: Self-administered questionnaire
Design: Descriptive, and correlational design
Sector: Retail sector, e.g., spaza shops, Shaheens, Fruit and vegetable.
Area: Eastern Cape rural
Women invest their stokvel funds into businesses like taverns, laundry and sewing, small grocery shops, and dairy shops
Adewumi et al. (2025)Method: Quantitative
Instrument: Questionnaire
Design: Correlational design
Sector: Retail sector, e.g., spaza shops, Shaheens, Fruit and vegetable.
Area: Eastern Cape rural
Stokvels are an alternative to the mainstream banking system that is financially excluded from the formal financial system
Armstrong (2022)Method: Quantitative
Instrument: Semi-structured interviews
Design: Case study
Sector: Retail sector, e.g., Fruit and vegetable.
Area: Rural communities
Stokvels build financial skills, resources, mindset, and support women entrepreneurship
Mba and Mzileni (2023)Method: Qualitative
Instrument: Semi-structured interviews
Design: Narrative design
Sector: Street vendors
Area: Urban-Township
Stokvels are investment arms used by black women street vendors
Van Wyk (2017)Method: Qualitative
Instrument: Semi-structured interviews
Design: Narrative-based inquiry interviews
Sector: Fruit and vegetable vending
Area: Rural women
Stokvels supplement limited earnings, guaranteeing access to credit when needed, and provide start-up capital for new women businesses.
Sethwana and Ramukumba (2024)Method: Mixed methods
Instrument: Questionnaires and Semi-structured interviews
Design: Explanatory sequential design
Sector: Tourism
Area: Mix of rural and urban villages
SEFA offer loans and grants to small businesses with flexible repayment terms and low interest rates.
Kandolo and Ngibe (2024)Method: Quantitative
Instrument: Questionnaires
Design: Explanatory design
Sector: Retail informal sector
Area: Township-urban- refugees and migrants
- DTI allocate substantial resources to support women entrepreneurs through grants
- There has been an increase in gender focused financial education training leading to a high number of women businesses start ups
Mandipaka (2014a)Method: Qualitative
Instrument: In depth interviews
Design: Explanatory
Sector: Not mentioned
Area: Urban area-King Williams Town
Isivande Women’s Fund offer women business start-up and business expansion loans
Mandipaka (2014b)Method: Literature reviewSector: All sectors
Area: Urban and rural
The South African government need to offer financial support and mentorship programs for women entrepreneurs
Ojo and Zondi (2021)Method: Qualitative
Instrument: Semi-structured open-ended interviews
Sector: All sectors
Area: Urban and rural
Women entrepreneurs are not aware of government financial support programs
Derera (2021)Method: Mixed methods
Instrument: Questionnaires and Semi-structured interviews
Design: Explanatory sequential design
Sector: Informal sector
Area: Urban Pietermaritzburg
Women entrepreneurs are not aware of government financial support programs
Ebewo et al. (2025)Method: Qualitative
Instrument: Semi- interviews
Design: Interpretive, hermeneutic, and phenomenological design
Sector: All sectors
Area: Urban women entrepreneurs affiliated with a Centre for Entrepreneurship Development.
- There is a need to develop alternative funding mechanisms, such as microfinance, tailored to women without collateral
- Entrepreneurship development centers owned by universities play an important role in offering financial education programs for women entrepreneurs
Shambare (2011)Method: Qualitative
Instrument: In-depth interviews
Design: Explanatory
Sector: All sectors
Area: Urban
Microfinance targeting women entrepreneurs like Small Enterprise Foundation (SEF) in South Africa has proven to be very successful
Absa Group Limited (2021)ReportSector: All sectors
Area: Urban and rural
Absa has a women empowerment finance facility, that finance new start-ups and existing women led businesses, which provide funding of up to R15million
Standard Bank (2024)ReportSector: All sectors
Area: Urban and rural
The bank disbursed R1.1 million in grant funding that was provided to 200 women business owners in 2023/2024.
Development Bank of Southern Africa (2024)ReportSector: All sectors
Area: Urban and rural
Value infrastructure delivered to black owned entities amounted to R2.3 billion, and 30% was awarded to black women businesses.
National Empowerment Fund (2025)ReportSector: All sectors
Area: Urban and rural
Women Empowerment Fund, funded the following different sectors, manufacturing (R37.3 million), waste management (R15 million), tourism (R13.9 million), mining services (R45.7 million) and IT services (R14 million)
SEFA (2024)ReportSector: All sectors
Area: Urban and rural
SEFA disbursed R811,043,079 to women entrepreneurs in South Africa, and this funding amount achieved 99% of the annual target of R822,688,000 in 2023/2024
IDC (2025)ReportSector: All sectors
Area: Urban and rural
there was a decline in women led businesses support from R11.4 billion to R5.6 billion, this however exceeded a target of 142% annual target in 2024/2025
Ogujiuba et al. (2025)Method: Secondary literature reviewSector: All sectors
Area: Urban and rural
Gender responsive grants like Isivande Women’s Fund, provides up to R5 million to black owned women enterprises in sectors like manufacturing and services, and the WEF which assists women owned enterprises
Source: Researchers’ compilation.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.